
 Global HD Maps Market | 2026-2036
Global HD Maps Market Size, Share, and Industry Trends Forecast 2026-2036
Global HD Maps Market Foresight
Semiconductor-grade silicon photonics is consolidating as the preferred substrate for LiDAR sensor arrays that feed HD map generation pipelines. HERE Technologies leverages its acquisition-era mapping corpus to sustain dense road-network coverage across European arterial corridors. NVIDIA Corporation anchors cloud-based map-training infrastructure through its autonomous-vehicle compute platforms. Mobileye Global Inc. differentiates by bundling crowdsourced map updates directly into its EyeQ chip deployments with OEM partners.
HD maps constitute georeferenced digital representations that encode lane-level geometry, traffic semantics, and surface topology with centimeter-scale absolute accuracy, typically generated through LiDAR point-cloud registration fused with RTK-GNSS corrections and SLAM-based trajectory optimization. Their primary commercial purpose is to provide autonomous navigation systems with deterministic environmental priors that compensate for real-time sensor occlusion or adverse weather degradation. The application dimension shows autonomous vehicles commanding the dominant share of current procurement volumes, while smart cities and augmented reality represent faster-growing adjacent demand pools with distinct margin structures. Within technology, LiDAR-based acquisition still occupies the premium tier for initial map creation, though computer-vision-only pipelines are narrowing the fidelity gap for update cycles at substantially lower unit economics.
The UNECE WP.29 regulation shapes market access by mandating validated localization performance for Level 3+ autonomous systems sold in contracting-party markets including Germany and Japan. The EU AI Act imposes risk-classification requirements on automated decision systems that ingest HD map data for path planning, compelling documentation of training-data provenance and edge-case coverage. China's MIIT issues GB standards that specify map-encryption protocols for surveyed geographic information, creating compliance friction for foreign providers seeking to serve domestic OEMs. Stakeholders must monitor whether national security reviews of geospatial data broaden to restrict cross-border map-update flows before committing to regional cloud-infrastructure placement.
Market Dynamics
Robotaxi fleet operators are consolidating procurement power and demanding real-time map freshness, compressing update cycles from quarterly to weekly frequencies and forcing HD map providers to rebuild cloud infrastructure around streaming data architectures.
Growth Catalysts
- UNECE WP.29 localization mandates:Level 3+ autonomous systems sold in Germany and Japan must demonstrate validated positioning accuracy, compelling OEMs to license centimeter-grade HD maps as compliance infrastructure.
- Silicon photonics LiDAR:Semiconductor-grade sensor substrates are collapsing LiDAR unit costs for map acquisition vehicles, expanding fleet sizes at data-collection providers.
- Smart city digital twins:Municipal governments in Singapore and Dubai are procuring HD map layers for traffic simulation and infrastructure planning, diversifying revenue beyond automotive.
Market Restraints
- Geospatial data nationalism:China's MIIT GB standards mandate encryption protocols for surveyed geographic information, creating compliance friction that blocks foreign providers from serving domestic OEMs.
- LiDAR sensor supply concentration:Foundry capacity for indium phosphide wafers concentrates in Taiwan and South Korea, exposing map data pipelines to single-source disruption risk.
- Vision-only substitution:Tesla and Mobileye are narrowing the fidelity gap using camera-based SLAM, threatening premium pricing for LiDAR-dependent map tiers.
Strategic Opportunities
- EU AI Act risk classification:Automated path-planning systems ingesting HD map data face new documentation requirements, creating services revenue for compliance auditing and training-data provenance verification.
- India's PLI scheme for automotive:Domestic OEMs establishing proving grounds in Tamil Nadu and Gujarat require localized HD map coverage with limited incumbent competition.
- AR navigation convergence:Head-up display manufacturers are licensing lane-geometry layers for windshield projection, opening consumer electronics as a parallel demand channel.
Industry Challenges
- SLAM algorithm talent scarcity:Map providers compete with autonomous vehicle developers for robotics engineers capable of optimizing real-time point-cloud registration pipelines.
- Cross-border data transfer restrictions:National security reviews of geospatial information in Russia and China are fragmenting cloud infrastructure strategies, forcing redundant regional server deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HD Maps Market |
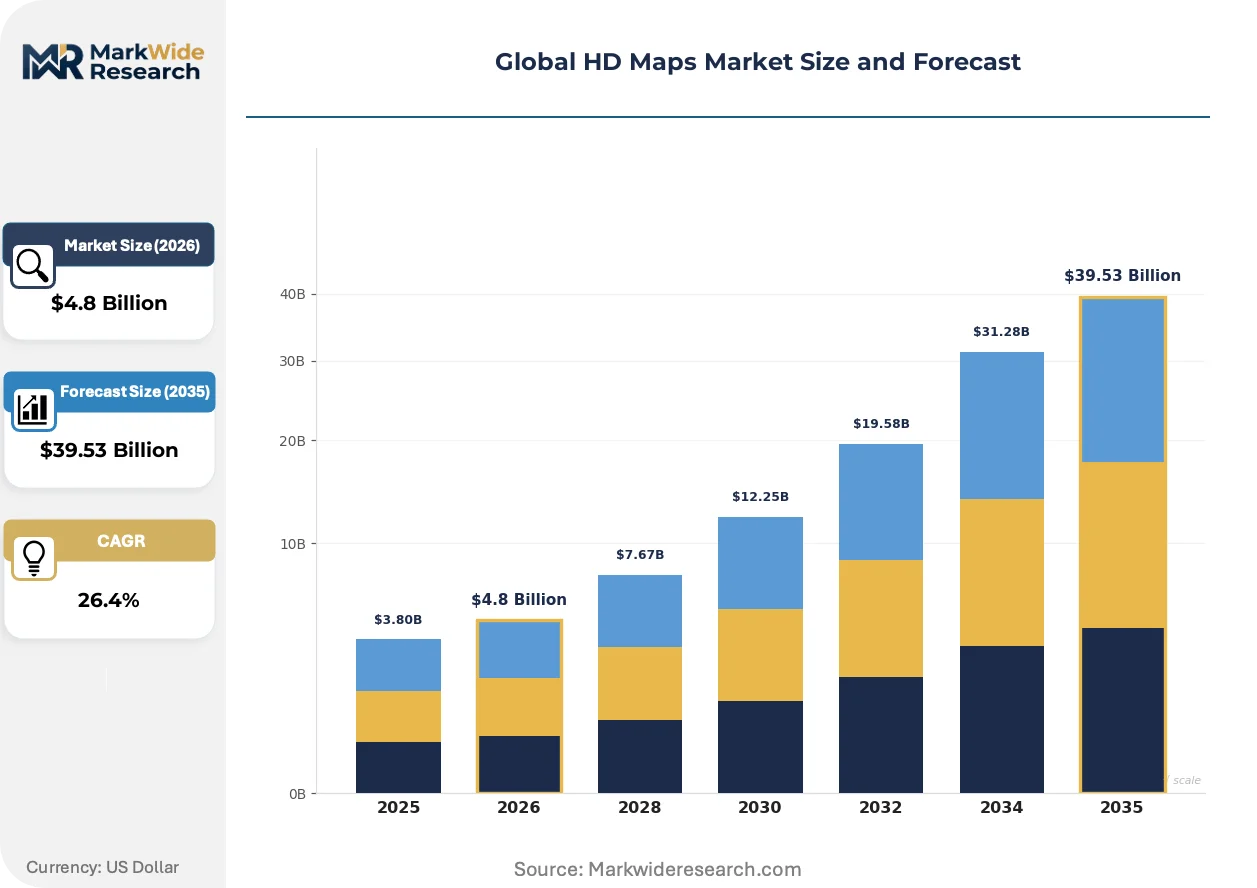
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $39.53 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vector Maps, Raster Maps, 3D Maps, Real-time Maps, Static Maps Technology: LiDAR, Radar, Computer Vision, GNSS, SLAM Application: Autonomous Vehicles, Fleet Management, Smart Cities, Augmented Reality, Navigation Systems End User: OEMs, Mapping Service Providers, Logistics Companies, Urban Planners, Surveyors |
| Companies Covered | HERE Technologies, TomTom International BV, Mobileye Global Inc., NVIDIA Corporation, Baidu Inc., Waymo LLC, Dynamic Map Platform Co., Ltd., NavInfo Co., Ltd., AutoNavi (Alibaba Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HD Maps Market Shifts & Advancements
HD map generation is pivoting from static survey campaigns to continuous crowdsourced updates, with sensor-equipped consumer vehicles feeding cloud pipelines that refresh road geometry within hours of infrastructure changes.
Sensor fusion architectures are unifying LiDAR point clouds with RTK-GNSS corrections and visual-inertial odometry into single pipelines that reduce map production costs by eliminating redundant survey passes. Tier 1 suppliers are adopting these unified stacks for their own fleet data collection. The compression of acquisition economics is enabling weekly refresh cycles for arterial corridors previously mapped quarterly.
The EU AI Act imposes risk-classification documentation on automated decision systems that ingest HD map data for path planning, compelling providers to maintain auditable training-data provenance and edge-case coverage records. Automotive OEMs selling Level 3+ systems in Germany and France must demonstrate compliance through third-party certification. This regulatory layer is creating new services revenue for map vendors capable of supplying documented data lineage.
Fleet operators are consolidating procurement around subscription-based map freshness tiers rather than perpetual licenses, with robotaxi developers in California and Arizona demanding real-time update SLAs that penalize stale geometry. Tier 2 automotive suppliers are responding by unbundling after-sales map maintenance from initial hardware sales. This shift compresses customer switching costs and intensifies vendor competition on streaming infrastructure reliability.
Global HD Maps Market Segmentation
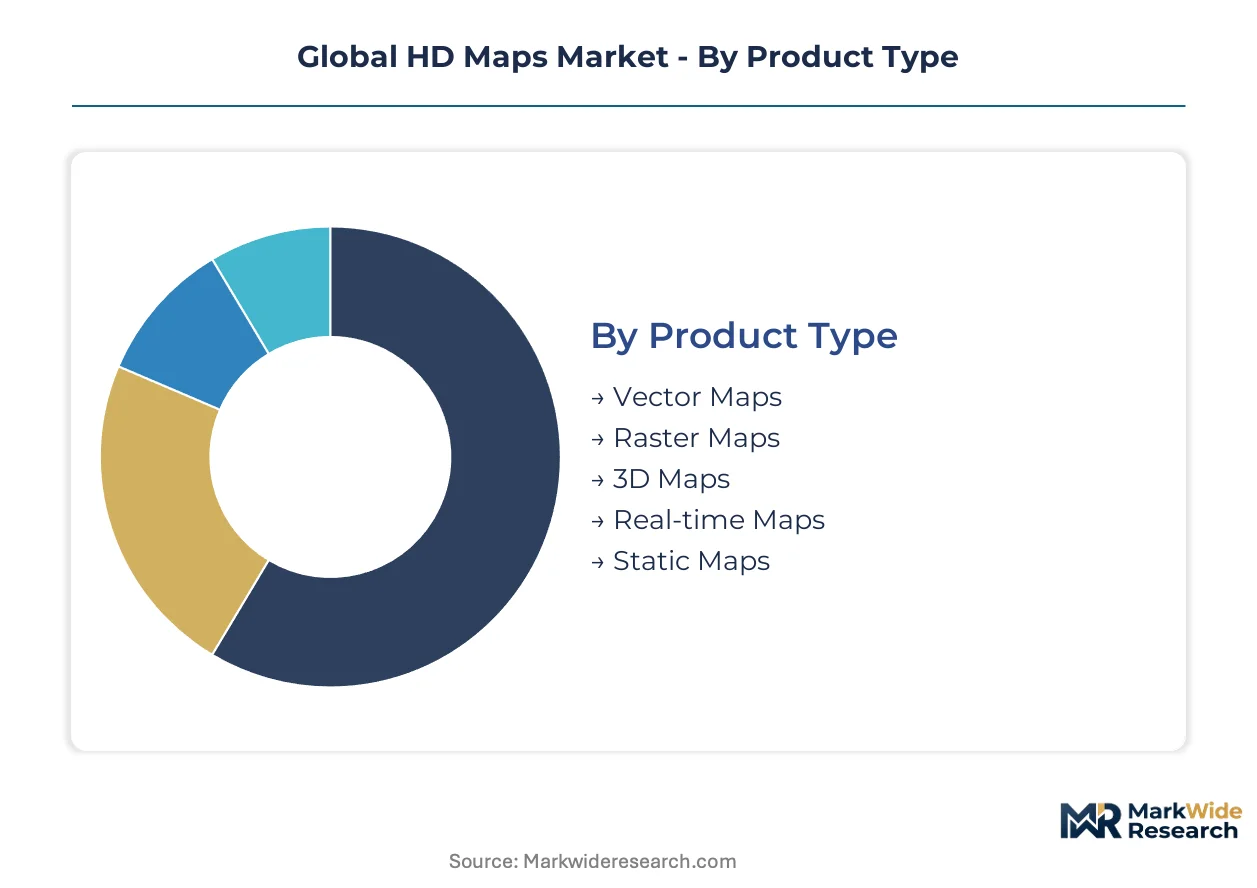
HD map providers structure offerings around data format, sensor technology, and end-use application to capture diverging value pools across automotive and municipal procurement channels. Each segmentation axis reflects distinct margin profiles, update frequency requirements, and compliance documentation burdens.
Product Type:
Supply concentrates among providers mastering vector geometry compression for embedded automotive systems versus cloud-streamed raster tiles for fleet dispatch centers.
- Vector Maps:Encode lane centerlines, boundary geometries, and traffic rules as scalable mathematical curves with centimeter-grade absolute accuracy. German OEMs and Japanese Tier 1 suppliers specify vector formats for Level 3+ autonomous systems under UNECE WP.29 localization mandates, compressing file sizes for embedded storage while preserving geometric fidelity.
- 3D Maps:Layer elevation data, overpass clearances, and roadside infrastructure into volumetric representations supporting sensor simulation and path planning validation. Singapore and Dubai municipal authorities procure 3D layers for digital twin construction, integrating HD map meshes with building information models for traffic flow optimization.
- Raster Maps:Store georeferenced imagery tiles for visualization layers in human-machine interfaces and dispatch dashboards.
- Real-time Maps:Stream delta updates on lane closures, construction zones, and surface conditions with sub-hour latency.
- Static Maps:Provide baseline road network geometry refreshed on quarterly or annual survey cycles for legacy navigation systems.
Vector maps absorb the bulk of installed capacity; real-time maps are expanding most quickly.
Technology:
Cost tiers separate semiconductor-grade LiDAR arrays from camera-only pipelines, with hybrid approaches occupying intermediate positions on fidelity and unit economics.
- LiDAR:Semiconductor-grade silicon photonics substrates generate dense point clouds with millimeter-range precision for initial map creation and validation benchmarking. Waymo and Mobileye robotaxi fleets specify LiDAR-denominated accuracy tiers for regulatory submission packages in California and Arizona operating domains.
- Computer Vision:Camera-based SLAM pipelines extract lane geometry and traffic signage using convolutional neural networks trained on fleet-collected imagery. Tesla's vision-only architecture narrows fidelity gaps for map update cycles at substantially lower sensor procurement costs, pressuring LiDAR-dependent pricing structures.
- Radar:Penetrates precipitation and low-light conditions to validate surface topology when optical sensors degrade.
- GNSS:RTK-corrected satellite positioning anchors absolute georeferencing for map tile alignment.
- SLAM:Simultaneous localization and mapping algorithms optimize trajectory estimation from sequential sensor frames.
LiDAR dominates premium-tier map creation; computer vision is climbing the fastest on update-cycle economics.
Application:
Customer type determines refresh frequency requirements, with robotaxi operators demanding hourly updates versus quarterly cycles for municipal planning departments.
- Autonomous Vehicles:Centimeter-grade localization layers compensate for real-time sensor occlusion and adverse weather degradation in path planning pipelines. UNECE WP.29 regulations in Germany and Japan mandate validated positioning accuracy for Level 3+ systems, embedding HD maps as compliance infrastructure.
- Smart Cities:Traffic simulation and infrastructure planning applications consume HD map layers for digital twin construction and congestion modeling. Municipal governments in Singapore procure lane-geometry data for intersection signal optimization, while Dubai integrates HD maps with building information models for urban development scenario testing.
- Fleet Management:Logistics operators license route optimization layers for fuel efficiency and delivery time reduction.
- Augmented Reality:Head-up display manufacturers license lane-geometry layers for windshield projection guidance.
- Navigation Systems:Consumer device manufacturers embed simplified HD map extracts for lane-level guidance.
Autonomous vehicles absorb the bulk of installed capacity; smart cities are gaining share fastest.
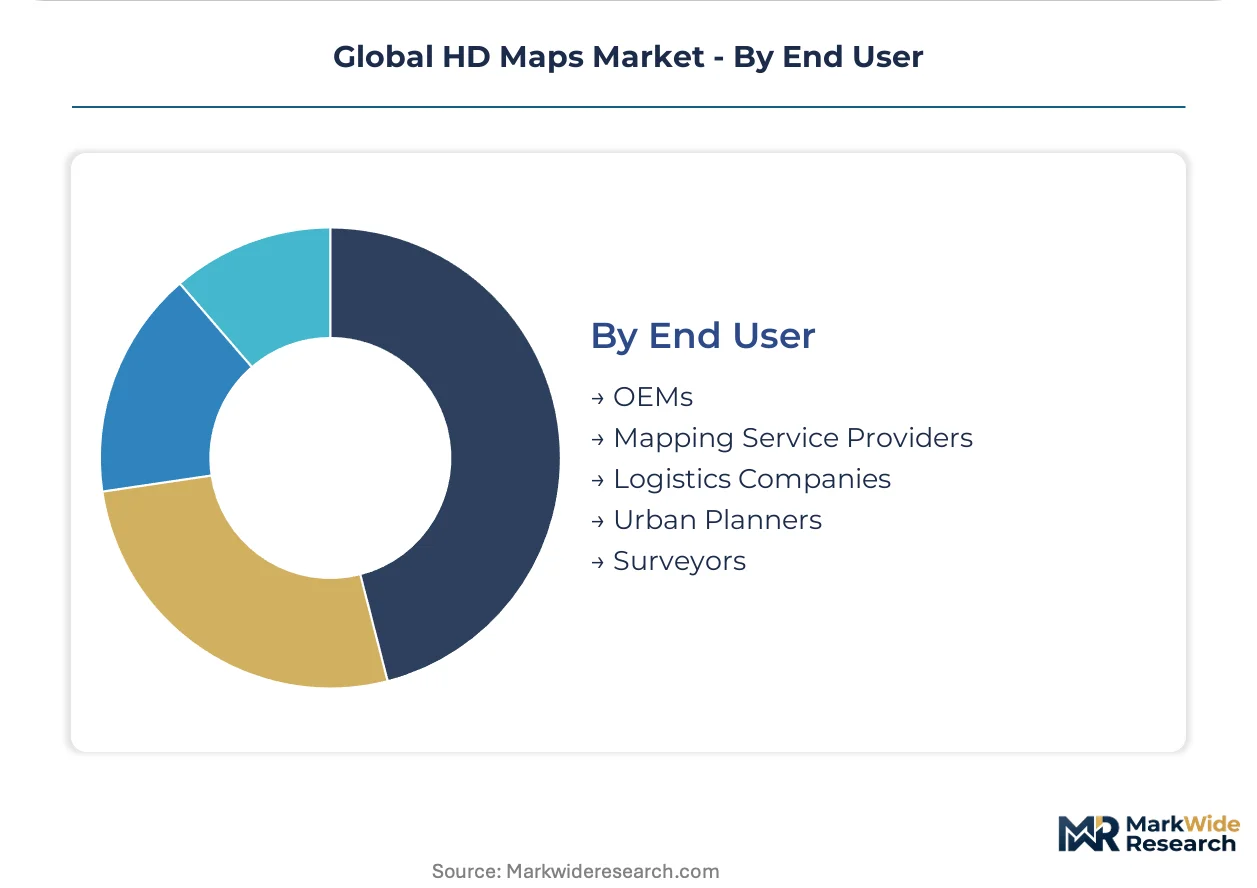
End User:
Procurement authority concentrates among OEMs integrating maps into vehicle platforms versus service providers unbundling subscription-based freshness tiers.
- OEMs:Vehicle manufacturers license HD map layers for factory-installed autonomous driving systems, specifying multi-year supply agreements with validated update SLAs. German and Japanese OEMs operate dedicated proving grounds for map validation under national type-approval frameworks.
- Mapping Service Providers:Aggregators license base map corpora from survey companies and refresh layers through crowdsourced probe data. HERE Technologies sustains dense European arterial coverage through acquisition-era mapping assets combined with streaming update infrastructure.
- Logistics Companies:Fleet operators procure route-optimization layers for commercial vehicle dispatch and fuel management.
- Urban Planners:Municipal technical departments license 3D map meshes for infrastructure investment scenario modeling.
- Surveyors:Geospatial services firms contract initial map creation for private campus and industrial site deployments.
OEMs absorb the bulk of installed capacity; mapping service providers are expanding most quickly on subscription revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robotaxi fleet operators and automotive OEMs concentrate procurement in Germany, Japan, and the United States, where dedicated proving grounds and permissive regulatory frameworks enable validation at scale.
United States
Waymo and Cruise operate commercial robotaxi services in San Francisco and Phoenix, generating continuous demand for real-time map updates with hourly refresh SLAs. The NHTSA maintains voluntary guidance for automated driving system testing, while California DMV issues deployment permits contingent on geofenced operational design domains. Silicon Valley hosts the dominant cloud infrastructure for map training pipelines.
Germany
BMW, Mercedes-Benz, and Volkswagen operate dedicated proving grounds in Bavaria and Lower Saxony for Level 3 system validation under national type-approval frameworks. The KBA enforces UNECE WP.29 localization mandates that embed HD maps as compliance infrastructure for highway pilot systems. Stuttgart and Munich anchor automotive R&D clusters where Tier 1 suppliers integrate vector geometry layers into embedded compute platforms.
Japan
Toyota, Honda, and Nissan procure HD maps for highway autonomous systems under METI-sponsored verification programs. The Ministry of Land, Infrastructure, Transport and Tourism maintains national standards for dynamic map data exchange between vehicles and infrastructure. Nagoya and Tokyo metropolitan areas concentrate sensor fusion development for crowdsourced update pipelines.
China
Baidu and AutoNavi dominate domestic procurement through partnerships with SAIC, Geely, and BYD for intelligent connected vehicle programs. The MIIT issues GB standards mandating encryption protocols for surveyed geographic information, creating compliance friction for foreign providers. Beijing and Shanghai regulatory sandboxes permit commercial robotaxi testing with restricted operational zones.
Singapore
The Land Transport Authority procures HD map layers for digital twin construction and intersection signal optimization across the island-state. The country's national regulator mandates cybersecurity certification for autonomous vehicle trials through designated test corridors. One-North and Jurong Innovation District host validation facilities where municipal authorities integrate map meshes with building information models.
Global HD Maps Market Competitive Landscape
Strategic partnerships dominate the current landscape as map providers align with automotive OEMs and cloud infrastructure vendors to secure multi-year supply agreements. The vendor base concentrates among three tiers: acquisition-era mapping specialists with dense road-network corpora, semiconductor-anchored platform vendors bundling hardware and software, and crowdsourced update aggregators leveraging consumer vehicle fleets. Dominant competitive moves include technology licensing arrangements that embed map layers into autonomous driving compute platforms, and geographic expansion through regional cloud infrastructure placement to satisfy data residency requirements.
Within the acquisition-era mapping tier, HERE Technologies and TomTom International BV exemplify providers sustaining dense arterial coverage through legacy survey assets combined with streaming update infrastructure. Among semiconductor-anchored platform vendors, NVIDIA Corporation occupies a position representing cloud-based map-training infrastructure integration. These three companies anchor distinct strategic archetypes: corpus-dependent coverage extension, hardware-software bundling, and cloud-native pipeline scaling.
| Leading Market Players |
|---|
| HERE Technologies |
| TomTom International BV |
| Mobileye Global Inc. |
| NVIDIA Corporation |
| Baidu Inc. |
| Waymo LLC |
| Dynamic Map Platform Co., Ltd. |
| NavInfo Co., Ltd. |
| AutoNavi (Alibaba Group) |
| Others |
Supply & Pricing Matrix
Silicon photonics substrate migration for LiDAR sensor arrays is collapsing unit economics for map acquisition fleets while simultaneously redrawing foundry dependency maps across East Asian manufacturing clusters. This dual transformation compresses pricing power for legacy survey-dependent tiers even as it amplifies vulnerability to single-source wafer supply.
Pricing Analysis
Volume-heavy robotaxi procurement absorbs margin compression through subscription-based freshness tiers, while premium vector-map licensing for German and Japanese OEM compliance sustains pricing power. Three-tier pricing structure across premium, standard, and economy levels separates LiDAR-validated accuracy tiers from vision-only update cycles. Cost compression in crowdsourced update pipelines is intensifying because Tesla and Mobileye are narrowing fidelity gaps without semiconductor-grade sensors. Fleet operators exhibit highest price sensitivity; regulatory-mandated OEM procurement shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for indium phosphide wafer foundry capacity feeding LiDAR sensor production. HD map generation draws from semiconductor-grade silicon photonics, RTK-GNSS correction services, and cloud compute infrastructure as core inputs. Tariff exposure runs through cross-border geospatial data flows restricted by China's MIIT encryption mandates. Distribution runs through direct OEM integration contracts and mapping service provider subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global HD Maps Market functions as a cost-of-compliance arena where UNECE WP.29 localization mandates erect regulatory moats that favor incumbents with validated certification documentation. This barrier-to-entry structure rewards players bearing the fixed cost of audit-ready training-data provenance systems.
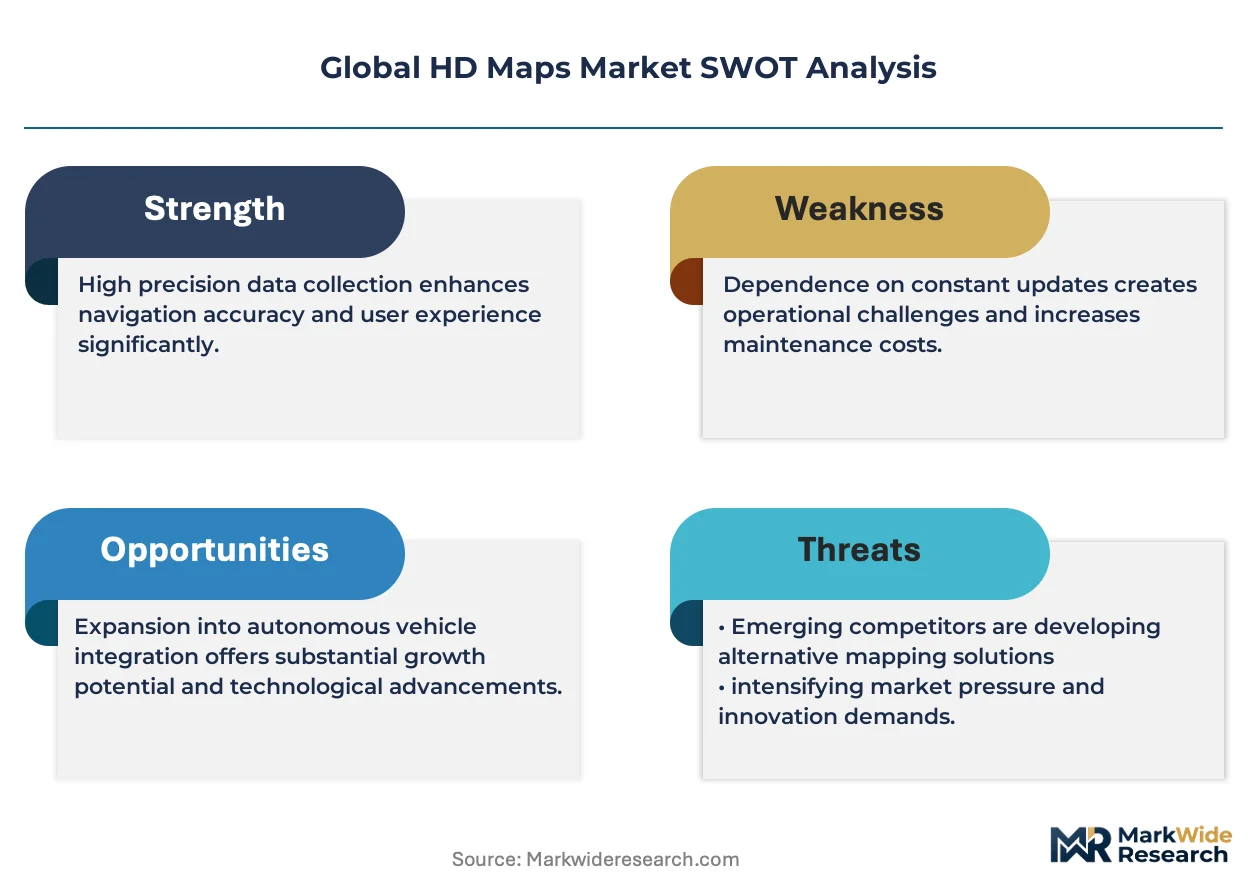
For Market Incumbents: Anchor cloud infrastructure placement in Germany, Japan, and the United States to satisfy data residency requirements under national security reviews of geospatial information. Defensive consolidation should prioritize SLAM algorithm talent acquisition to offset robotics engineer scarcity, while backward integration into silicon photonics sensor supply hedges foundry concentration risk from Taiwan and South Korea. For New Entrants and Emerging Players: Tier 2 automotive suppliers represent the most penetrable channel partner type for unbundled after-sales map maintenance contracts. White-space targets include India's PLI scheme automotive proving grounds in Tamil Nadu and Gujarat with limited incumbent coverage, plus AR navigation head-up display licensing for consumer electronics parallel demand. Go-to-market positioning should emphasize real-time update SLA reliability against legacy quarterly survey cycles. For Investors and Strategic Acquirers: Re-rating potential sits with crowdsourced update aggregators leveraging consumer vehicle fleets given the pivot from static survey campaigns to continuous cloud pipelines. Long-term viability over the five-to-ten year horizon favors platform vendors bundling hardware-software integration over corpus-dependent coverage extension. The signal to watch is weekly refresh cycle penetration on arterial corridors as inflection indicator for streaming infrastructure maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Regionalization | Data residency compliance in Germany, Japan, and the United States satisfies geospatial nationalism restrictions. |
| Silicon Photonics Backward Integration | Captive wafer supply from Taiwan and South Korea mitigates single-source LiDAR sensor disruption risk. |
| Crowdsourced Update Platform Scaling | Consumer vehicle probe data feeds compress map refresh cycles from quarterly to weekly frequencies. |
| EU AI Act Compliance Documentation | Auditable training-data provenance creates services revenue from German and French OEM certification requirements. |
| AR Navigation Licensing Partnership | Head-up display manufacturers in consumer electronics open parallel demand channel beyond automotive procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across autonomous vehicle fleet operators, automotive OEM platform engineers, Tier 1 supplier procurement leads, LiDAR sensor foundry specialists, and municipal smart city planners. UNECE WP.29 submission documents, MIIT GB standard publications, EU AI Act risk classification guidance, and robotaxi deployment permit records supplied regulatory validation. Bottom-up fleet procurement estimates triangulated against top-down OEM supply agreement aggregates.
Granularity-level modeling disaggregated volume and value across vector, 3D, raster, real-time, and static map product types; LiDAR, computer vision, radar, GNSS, and SLAM technology tiers; and autonomous vehicle, smart city, fleet management, augmented reality, and navigation system applications. CAGRs were derived from segment-level growth trajectory synthesis across the projection horizon. Industry-specific forecast inputs included silicon photonics cost curves and robotaxi fleet expansion schedules.
Caveats apply where geospatial data nationalism expansion or vision-only SLAM fidelity breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and sensor substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market