
 Global Pension Administration Software Market | 2026-2036
Global Pension Administration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pension Administration Software Market Outlook
The EU Green Deal disclosure requirements is rebalancing how pension funds evaluate software procurement, pushing administrators toward platforms with embedded carbon-footprint tracking and ESG reporting modules. Oracle leverages its database infrastructure dominance to anchor large public-sector fund deployments across North America and Europe. SAP competes through deep ERP integration that sustains renewal rates among multinational corporate pension plans.
Pension administration software encompasses cloud-based, on-premise, and hybrid platforms that automate member enrollment, contribution processing, benefit calculations, and regulatory reporting for defined-benefit and defined-contribution schemes. These systems typically integrate actuarial engines, document management workflows, and API connectivity to payroll and banking networks, serving trustees and plan sponsors who must reconcile participant data against shifting tax and labor codes. Cloud-based solutions now lead solution-type demand as funds retire legacy mainframe installations, while SaaS deployment models capture the fastest growth by eliminating capital-intensive infrastructure cycles. Financial institutions represent the most concentrated end-user margin pool due to their bundled wealth-management and pension-administration service lines.
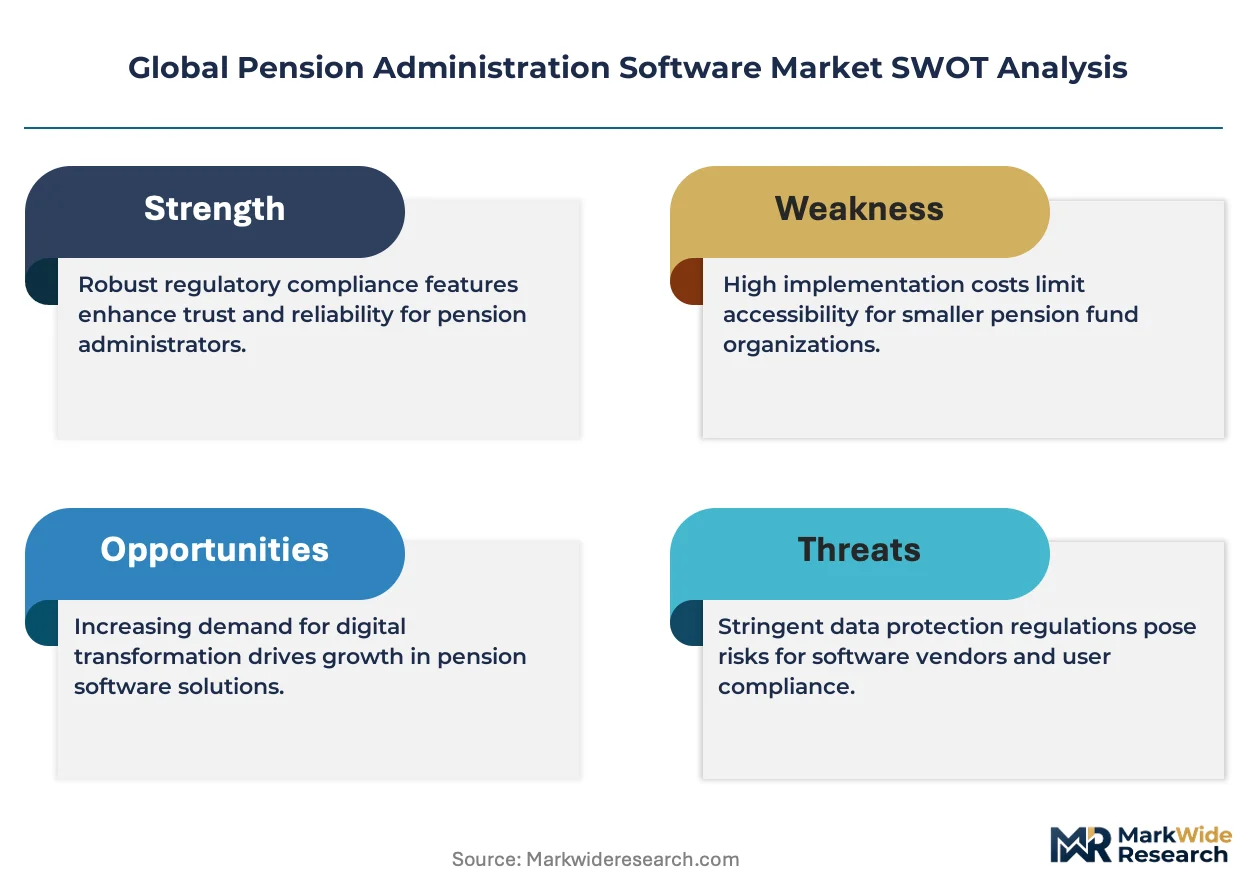
The US Department of Labor fiduciary rules, the EU's CSRD sustainability reporting framework, and Japan's METI guidelines on digital governance collectively shape product roadmaps by mandating audit trails, participant-data portability, and climate-risk disclosures. Software vendors must architect compliance management and reporting tools that satisfy divergent jurisdictional requirements without fragmenting code bases. Stakeholders should monitor how forthcoming AI-actuarial hybrids attract scrutiny from national financial regulators before committing to multi-year platform contracts.
Market Dynamics
The EU AI Act and CSRD disclosure mandates are compressing procurement cycles as pension administrators demand audit-ready cloud architectures that embed compliance automation from deployment. These regulatory frameworks are forcing vendors to rearchitect platforms around explainable algorithms and carbon-footprint traceability.
Growth Catalysts
- Automated compliance engines:The EU AI Act mandates algorithmic transparency for pension benefit calculations, driving demand for platforms with built-in audit trails and regulatory reporting modules.
- Japan:METI guidelines on digital governance require participant-data portability, accelerating replacement of legacy mainframe systems with API-native architectures.
- Cloud migration waves:Corporate pension plans in Germany are retiring on-premise installations to eliminate capital-intensive infrastructure refresh cycles.
Market Restraints
- Actuarial talent scarcity:The specialized skill set bridging pension mathematics and software engineering concentrates in London, New York, and Zurich, inflating implementation costs.
- Data localization requirements:China's SAMR and the EU's GDPR impose conflicting sovereignty rules on cross-border pension data flows, fragmenting vendor code bases.
- Legacy system entrenchment:US public-sector funds face decade-long amortization schedules that delay SaaS migration despite total-cost advantages.
Strategic Opportunities
- India:SEBI's expanding pension fund regulations and the PLI scheme for fintech create entry points for modular administration platforms serving the National Pension System.
- AI-actuarial convergence:Machine learning models predicting longevity risk and portfolio drawdowns are opening white space for hybrid platforms that automate both calculations.
- Embedded ESG reporting:The EU Green Deal's climate-risk disclosure requirements enable premium pricing for platforms with native carbon-footprint tracking across pension portfolios.
Industry Challenges
- COBOL-to-cloud migration complexity:Pension funds maintaining decades-old benefit calculation engines face brittle integration paths that extend implementation timelines.
- Cross-jurisdictional certification lag:Vendors must obtain separate approvals from the US Department of Labor, Germany's BaFin, and Japan's FSA, delaying multi-country deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pension Administration Software Market |
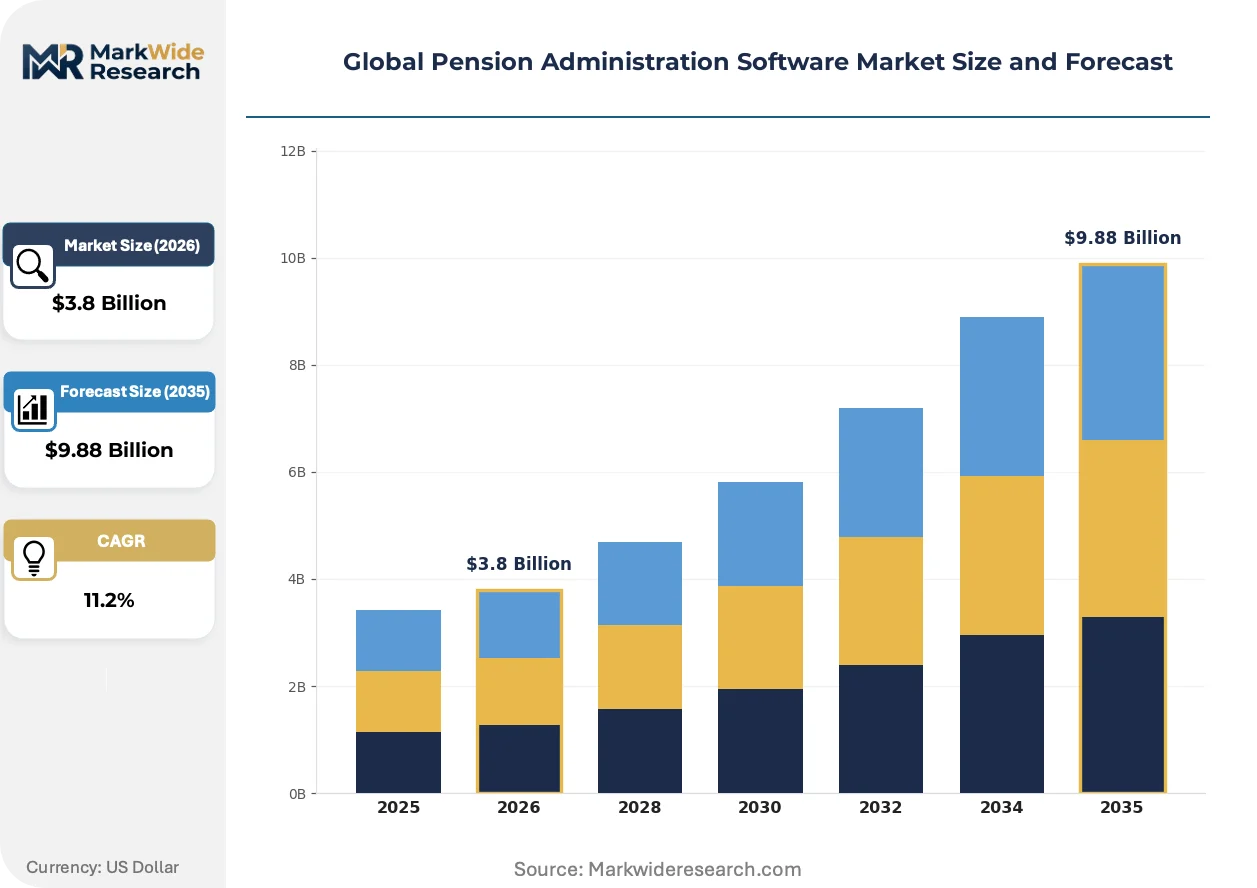
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, Custom Solutions End User: Corporate Pension Plans, Public Pension Funds, Non-Profit Organizations, Financial Institutions Deployment Model: Private Cloud, Public Cloud, Community Cloud, SaaS Feature Set: Reporting Tools, Compliance Management, Contribution Tracking, Benefit Calculation |
| Companies Covered | Milliman Marc, Oracle, Alight Solutions, Sagitec Solutions, Vitech Systems Group, Equiniti Group, Paycom, TELUS Health, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pension Administration Software Market Strategic Shifts
Microservices architectures are fragmenting monolithic pension platforms into composable components that funds can deploy selectively. This decomposition is compressing vendor margins while accelerating feature velocity.
Containerized deployment is modularizing pension administration stacks into discrete services for enrollment, contribution processing, and benefit calculations. Mid-size corporate plans in the United States are adopting these components faster than public-sector funds. The technology is modularizing competitive differentiation away from suite breadth toward API interoperability and single-function excellence.
The EU CSRD sustainability reporting framework mandates granular carbon-footprint disclosures for pension fund investments. Asset managers must now trace emissions through multi-tier supply chains. European corporate pension plans are prioritizing platforms with pre-built ESG data pipelines and automated CSRD template generation.
Subscription pricing is displacing perpetual licenses as the dominant procurement model for pension administration software. Third-party administrators and bundled wealth-management providers are driving this shift to align software costs with participant-headcount volatility. The pattern is most visible in the United Kingdom and Australia where outsourcing concentration is highest.
Global Pension Administration Software Market Segmentation
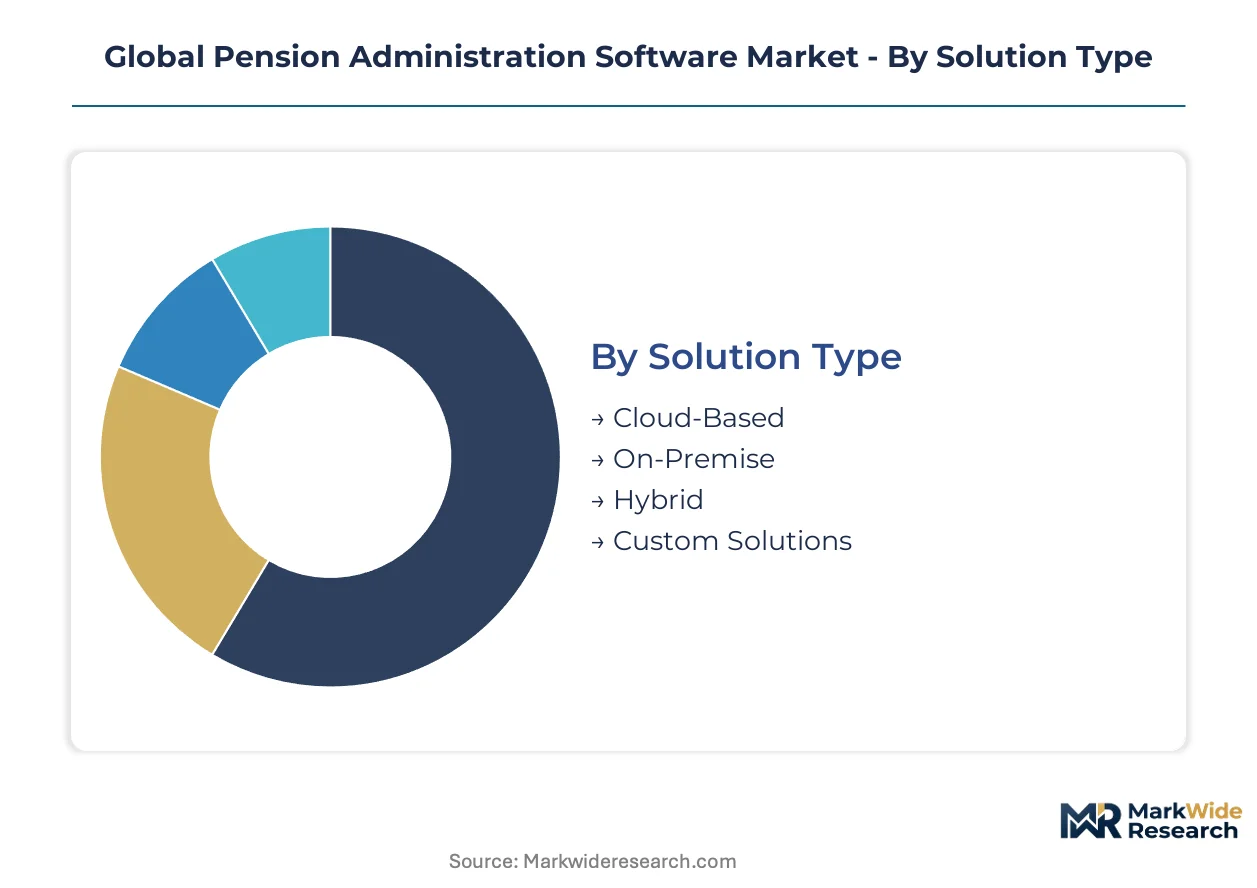
Pension administration software segments reflect divergent risk tolerances and regulatory pressures across fund types. Procurement patterns cluster around deployment flexibility, compliance automation depth, and integration complexity with legacy actuarial systems.
Solution Type:
Cloud-based platforms command volume leadership while on-premise installations retain premium pricing among risk-averse public funds. The cost-to-control spectrum shapes vendor R&D allocation and sales cycle duration.
- Cloud-Based:Multi-tenant architectures with automatic compliance patching attract corporate pension plans in Germany and the United States seeking to eliminate infrastructure capital cycles. METI guidelines in Japan are accelerating migration from domestic data centers to API-native cloud stacks.
- On-Premise:Dedicated hardware installations with full data sovereignty satisfy fiduciary committees at US public-sector funds facing decade-long amortization schedules. These deployments sustain higher professional services attach rates due to customization requirements.
- Hybrid:Split architectures placing sensitive participant data on-premise while routing reporting workloads to cloud instances.
- Custom Solutions:Bespoke builds for sovereign wealth funds and multi-employer plans with unique benefit formulas.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
End User:
Financial institutions bundle pension administration with wealth management, capturing margin concentration through cross-sell economics. Corporate and public fund procurement diverges on customization tolerance and compliance timeline urgency.
- Corporate Pension Plans:Defined-benefit and defined-contribution schemes prioritize automated contribution tracking and real-time participant portals. Procurement in the United Kingdom and Australia favors subscription pricing aligned with headcount volatility.
- Financial Institutions:Banks and insurance carriers demand white-label administration platforms with embedded ESG reporting modules. The EU CSRD disclosure mandates are forcing upgrades to carbon-footprint traceability across bundled service lines.
- Public Pension Funds:Government-sponsored schemes with legacy COBOL dependencies.
- Non-Profit Organizations:Smaller schemes with limited IT staffing and compliance expertise.
Financial Institutions drive premium pricing. Corporate Pension Plans are expanding most quickly.
Deployment Model:
SaaS models displace perpetual licenses fastest where outsourcing concentration is highest. Private cloud retains traction among funds with data localization obligations.
- SaaS:Fully managed subscription platforms eliminate version fragmentation and accelerate regulatory patch deployment. Third-party administrators in Australia and the United Kingdom prefer this model for cost alignment with participant flows.
- Private Cloud:Single-tenant virtualized infrastructure offering dedicated resource pools without full on-premise hardware ownership.
- Public Cloud:Shared hyperscaler infrastructure with consumption-based pricing.
- Community Cloud:Collaborative infrastructure shared among pension funds with common regulatory jurisdictions.
Private Cloud anchors incumbent renewal bases. SaaS is gaining share fastest among new procurement.
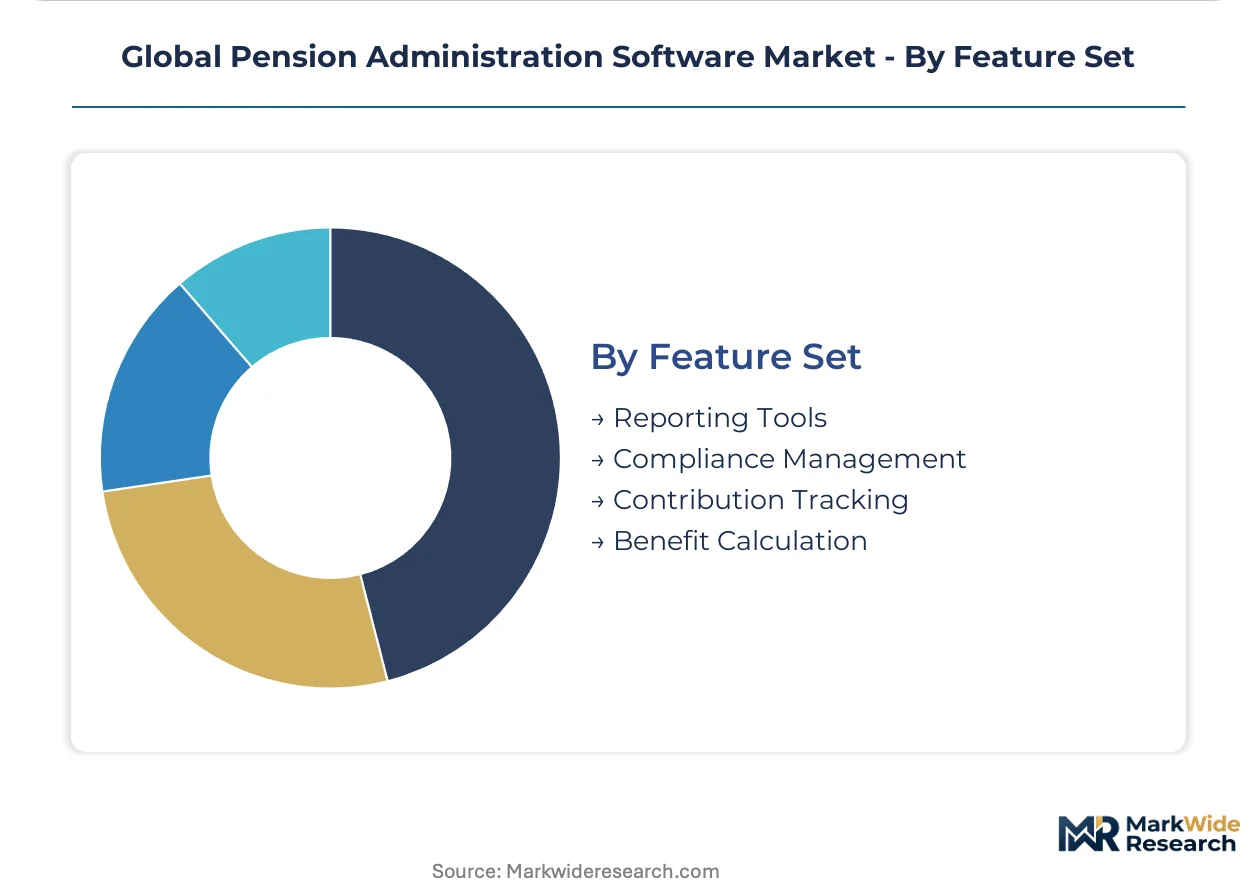
Feature Set:
Compliance automation commands implementation priority as regulatory divergence intensifies across jurisdictions. Reporting tools follow as funds face granular disclosure mandates.
- Compliance Management:Algorithmic audit trails and automated regulatory template generation address EU AI Act transparency requirements and US Department of Labor fiduciary documentation rules. Vendors architect these modules for multi-jurisdictional certification without code base fragmentation.
- Benefit Calculation:Actuarial engines performing defined-benefit liability valuations and defined-contribution drawdown projections.
- Reporting Tools:Pre-built CSRD and ESG disclosure pipelines with carbon-footprint tracking across pension portfolios.
- Contribution Tracking:Real-time payroll integration and reconciliation workflows.
Compliance Management leads replacement cycles. Reporting Tools follow as secondary procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Germany, while consumption spreads across pension fund jurisdictions tightening fiduciary-technology standards. Procurement cycles compress where regulatory mandates demand audit-ready cloud architectures. Regional divergence in compliance timelines creates asynchronous upgrade waves across fund types.
United States
Corporate pension plans and third-party administrators drive cloud migration to eliminate capital-intensive infrastructure cycles. The Department of Labor fiduciary rules mandate algorithmic audit trails for benefit calculations, accelerating replacement of legacy COBOL systems. The Boston-Washington corridor hosts concentrated vendor development centers serving public-sector funds with decade-long amortization constraints.
Germany
BaFin's digital governance standards and the EU AI Act's transparency requirements compress procurement timelines for automated compliance engines. Corporate pension plans in Baden-Württemberg and North Rhine-Westphalia prioritize subscription pricing aligned with headcount volatility. Frankfurt's financial cluster anchors vendor professional services teams supporting multi-employer plan migrations.
Japan
METI guidelines on participant-data portability force retirement of domestic mainframe installations in favor of API-native architectures. Corporate pension plans in Tokyo and Osaka accelerate SaaS adoption to satisfy digital governance mandates. The Kanto region's vendor ecosystem specializes in actuarial-engine integration for hybrid cloud deployments.
United Kingdom
The Pensions Regulator's automatic enrollment expansion and ESG disclosure requirements drive demand for platforms with embedded carbon-footprint tracking. Third-party administrators in London favor fully managed subscription models to align costs with participant flow volatility. The Southeast's outsourcing concentration sustains premium pricing for compliance automation modules.
India
SEBI's expanding pension fund regulations and the PLI scheme for fintech create entry points for modular administration platforms serving the National Pension System. Mumbai and Bangalore host development centers building API-native stacks for longevity-risk modeling. Domestic funds prioritize cost-efficient SaaS deployment over on-premise customization.
Global Pension Administration Software Market Competitive Environment
The competitive structure tilts toward database-centric incumbents with installed infrastructure dominance. Consolidation pressure intensifies as microservices architectures fragment monolithic platforms into composable components. Three archetypes define positioning: ERP-integrated suite vendors, standalone pension specialists, and cloud-native challengers. M&A activity targets actuarial-engine capabilities, while strategic partnerships accelerate cross-jurisdictional certification timelines.
Within the database-infrastructure tier, Oracle anchors large public-sector fund deployments across North America and Europe. SAP exemplifies ERP-integrated positioning that sustains renewal rates among multinational corporate pension plans. Milliman Marc occupies a specialist position bridging actuarial consulting with software delivery for defined-benefit liability valuations.
| Leading Market Players |
|---|
| Milliman Marc |
| Oracle |
| Alight Solutions |
| Sagitec Solutions |
| Vitech Systems Group |
| Equiniti Group |
| Paycom |
| TELUS Health |
| SAP |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's carbon-footprint disclosure mandates gate qualified supply for pension administration platforms, restricting premium-tier pricing access to vendors with pre-built ESG data pipelines and automated CSRD template generation. Procurement committees in Germany and the United Kingdom now disqualify vendors lacking embedded climate-risk traceability, compressing margins for undifferentiated cloud providers while sustaining pricing power for compliance-native architectures.
Pricing Analysis
Per-participant subscription pricing anchors the market, with SaaS tiers scaling against headcount volatility and compliance automation depth. Price differentiation rests on CSRD-ready ESG modules and API interoperability with legacy actuarial engines. Cost compression in the mid-market intensifies as microservices architectures fragment monolithic suites into commoditized components. Third-party administrators in Australia and the United Kingdom exhibit highest price sensitivity due to outsourcing margin pressure, while US public-sector funds accept premium professional services attach rates for customization.
Supply Chain Analysis
Regional distribution of software development talent concentrates in the Boston-Washington corridor, Frankfurt's financial cluster, and Bangalore's fintech corridor, creating hub-and-spoke delivery models for implementation and support. The supply chain draws from specialized actuarial-engine developers, hyperscaler infrastructure providers, and compliance-regulation consultants. Single-source vulnerability sits with COBOL-to-cloud migration specialists concentrated in London, New York, and Zurich. Distribution runs through direct enterprise sales teams serving large funds and channel partners reaching mid-size corporate plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pension Administration Software Market functions as a cost-of-compliance story where the EU AI Act's algorithmic transparency mandates erect barrier-to-entry moats favoring vendors with multi-jurisdictional certification and explainable actuarial engines.
For Market Incumbents: Lock in renewal bases among multinational corporate pension plans by deepening ERP integration and accelerating CSRD-ready ESG module deployment. Defend against cloud-native challengers through captive professional services capacity in Frankfurt and Tokyo. Prioritize backward integration into actuarial-engine development to reduce dependency on scarce talent pools in London and Zurich. For New Entrants and Emerging Players: Capture white space in India's National Pension System by delivering modular API-native stacks aligned with SEBI's expanding fund regulations. Target third-party administrators in the United Kingdom and Australia with fully managed SaaS pricing that aligns software costs with participant-flow volatility. Lead with AI-actuarial convergence capabilities that automate longevity-risk modeling and portfolio drawdown projections. For Investors and Strategic Acquirers: METI's enforcement actions on participant-data portability in Japan are the leading indicator that API-native architecture demand is accelerating replacement cycles across Asia-Pacific pension markets. Funds should prioritize acquisition targets with proven COBOL-to-cloud migration toolkits and established BaFin or FSA certification pathways. Watch for regulatory patch velocity divergence between the EU AI Act and US Department of Labor fiduciary rules as the signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Module Launch | Pre-built ESG data pipelines satisfy EU Green Deal disclosure mandates for German corporate pension plans. |
| Actuarial Engine Acquisition | Specialized longevity-risk modeling capabilities address defined-benefit liability valuation demand in Japan. |
| API-Native Architecture Migration | Microservices decomposition accelerates feature velocity for mid-size US corporate pension plans. |
| Strategic Partnership with Hyperscaler | Consumption-based infrastructure pricing aligns costs with participant-headcount volatility in Australia. |
| Geographic Expansion into India | Modular platforms serving SEBI-regulated National Pension System capture PLI scheme incentives. |
Study Parameters
Multi-period observation of vendor R&D allocation, regulatory patch deployment timelines, and pension fund procurement cycles anchored the trend analysis, supplemented by interviews with pension fund CIOs, third-party administrator operations directors, actuarial consulting partners, compliance technology vendors, and hyperscaler cloud strategists. Secondary validation drew from SEC 10-K filings of listed software vendors, BaFin and FSA regulatory guidance documents, EU AI Act implementation timelines, and METI digital governance advisories. Bottom-up triangulation of individual fund procurement patterns with top-down market sizing across deployment models and end-user segments ensured analytical consistency.
Segment-weighting applied differential growth assumptions across cloud-based, on-premise, and hybrid solution types, with further stratification by corporate pension plan, financial institution, and public fund end-user categories. CAGRs were derived from regression analysis of historical procurement data against regulatory mandate enforcement schedules, with sensitivity testing for cloud migration velocity and actuarial talent availability constraints. Forecast inputs incorporated METI guideline compliance deadlines, CSRD disclosure phase-in requirements, and US Department of Labor fiduciary rule amendment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-jurisdictional certification lag, COBOL-to-cloud migration complexity, and divergent AI-actuarial hybrid regulatory scrutiny. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Proxy Services and Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Automotive Design Software Market
Software & Services
Email Applications Market
Software & Services
K8s Market
Software & Services
Stone Analysis Software Market
Software & Services
Real Estate Software Market
Software & Services
Auto Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Global Award Management Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Preschool Education Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Avionics Software Market
Software & Services
Time and Attendance Software Market
Software & Services
United Kingdom HR Payroll Software Market