
 Geographic Information System Analytics Market | 2026-2036
Geographic Information System Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Geographic Information System Analytics Market Analysis
The divergence between premium enterprise-grade spatial analytics and commodity mapping services is hardening as procurement teams separate mission-critical geospatial intelligence from basic visualization tools. Esri leverages its ArcGIS ecosystem to sustain dominance in government and defense accounts where data sovereignty requirements anchor long-term contracts. Hexagon AB competes through its sensor-to-software integration, while SuperMap Software Co., Ltd. dominates domestic Chinese infrastructure projects where localization mandates control vendor selection.
Geographic Information System Analytics encompasses the computational processing, statistical modeling, and predictive inference applied to georeferenced data layers, typically operating on vector and raster datasets with sub-meter accuracy requirements for cadastral and network applications. The primary commercial purpose centers on optimizing asset location decisions, risk exposure quantification, and operational routing across distributed physical infrastructure. Cloud GIS deployments are capturing the fastest expansion as utilities and real estate developers shift capital expenditure models toward subscription-based spatial platforms. Desktop GIS retains entrenched positions in defense and natural resource management where air-gapped environments and legacy workflow dependencies preserve installed bases. Government Agencies represent the deepest margin pool given multi-year enterprise agreements and specialized compliance requirements.
ISO 19115 metadata standards, the EU INSPIRE directive, and China's GB/T 18578 national surveying specifications collectively shape product certification requirements and cross-border data interoperability rules. The US Federal Geographic Data Committee enforces coordinate system standardization that filters vendor eligibility for federal procurement vehicles. Stakeholders must monitor accelerating sovereignty requirements around cross-border geospatial data flows as jurisdictions tighten export controls on high-resolution imagery and derived intelligence products.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for spatial analytics platforms while fragmenting vendor economics between subscription SaaS and perpetual license models. Municipal procurement offices now bifurcate requirements between mission-critical cadastral systems and departmental visualization tools.
Growth Catalysts
- EU INSPIRE directive:Mandates standardized spatial data infrastructure across member states, forcing interoperability investments that expand addressable platform markets for compliant vendors.
- Utility digitization programs:Electric distribution operators in Germany deploy network digital twins to optimize outage response and vegetation management workflows.
- AI-enhanced raster processing:Automated feature extraction from satellite imagery compresses manual digitization labor for land registry modernization projects.
Market Restraints
- High-resolution imagery export controls:Cross-border restrictions on sub-meter satellite data fragment global product portfolios and force jurisdictional data center investments.
- Legacy desktop workflow dependencies:Defense and natural resource agencies maintain air-gapped ArcGIS installations that resist cloud migration despite higher total cost of ownership.
- Specialized geospatial talent scarcity:Shortages in computational geometry and coordinate systems engineering inflate implementation timelines for complex federated deployments.
Strategic Opportunities
- Smart city infrastructure mandates:China's municipal governments channel funding into integrated command platforms combining IoT sensor layers with real-time spatial analytics.
- Digital twin convergence:Building Information Modeling platforms are merging with geospatial engines to create unified infrastructure lifecycle management environments.
- Federal mapping procurement vehicles:The US Federal Geographic Data Committee's coordinate standardization requirements filter vendor eligibility toward certified enterprise platforms.
Industry Challenges
- ISO 19115 metadata compliance:Certification timelines for standardized geospatial cataloguing extend sales cycles by six to twelve months in government verticals.
- Interoperability friction:GB/T 18578 surveying specifications in China and INSPIRE schemas in Europe create divergent product roadmaps that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geographic Information System Analytics Market |
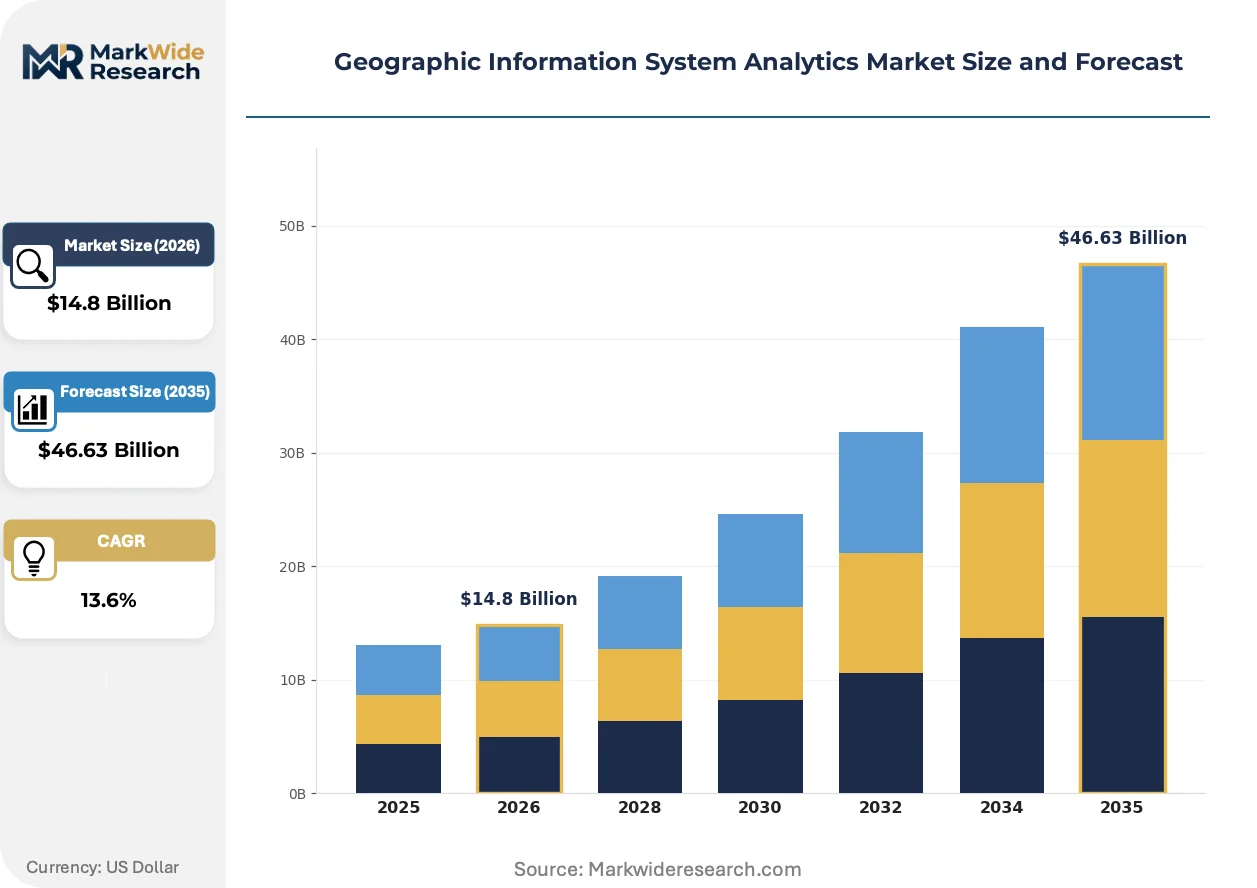
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Management, Transportation, Natural Resource Management Technology: Web-Based GIS, Desktop GIS, Mobile GIS, Cloud GIS End User: Government Agencies, Real Estate Developers, Utilities, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Open Source |
| Companies Covered | Esri, Hexagon AB, Trimble Inc., Bentley Systems, Incorporated, Autodesk Inc., Pitney Bowes Inc., SuperMap Software Co., Ltd., Topcon Corporation, Caliper Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geographic Information System Analytics Market Emerging Trajectories
Spatial analytics platforms are absorbing adjacent data modalities—sensor streams, building models, demographic layers—into unified processing engines. This integration is collapsing the historical separation between GIS, CAD, and business intelligence toolchains.
Real-time edge processing architectures are converging with cloud-based model training pipelines to enable sub-second spatial inference at remote infrastructure sites. Pipeline operators and logistics networks deploy these hybrid configurations for anomaly detection across distributed assets. The architecture is compressing latency requirements that previously justified centralized supercomputing investments.
The EU AI Act's risk classification framework subjects high-stakes geospatial inference systems—flood prediction, critical infrastructure routing—to conformity assessment procedures. Vendors serving European defense and emergency management sectors must document algorithmic transparency and training data provenance. German utility regulators now reference these requirements in technical specifications for grid resilience platforms.
Subscription pricing models are displacing perpetual licenses in municipal and mid-market accounts, compressing upfront revenue recognition while extending customer lifetime value horizons. Procurement offices in US state governments now mandate SaaS-evaluation clauses in enterprise software RFPs. California's Department of Transportation exemplifies this shift, consolidating fragmented desktop licenses into unified enterprise agreements with usage-based scaling provisions.
Geographic Information System Analytics Market Segmentation
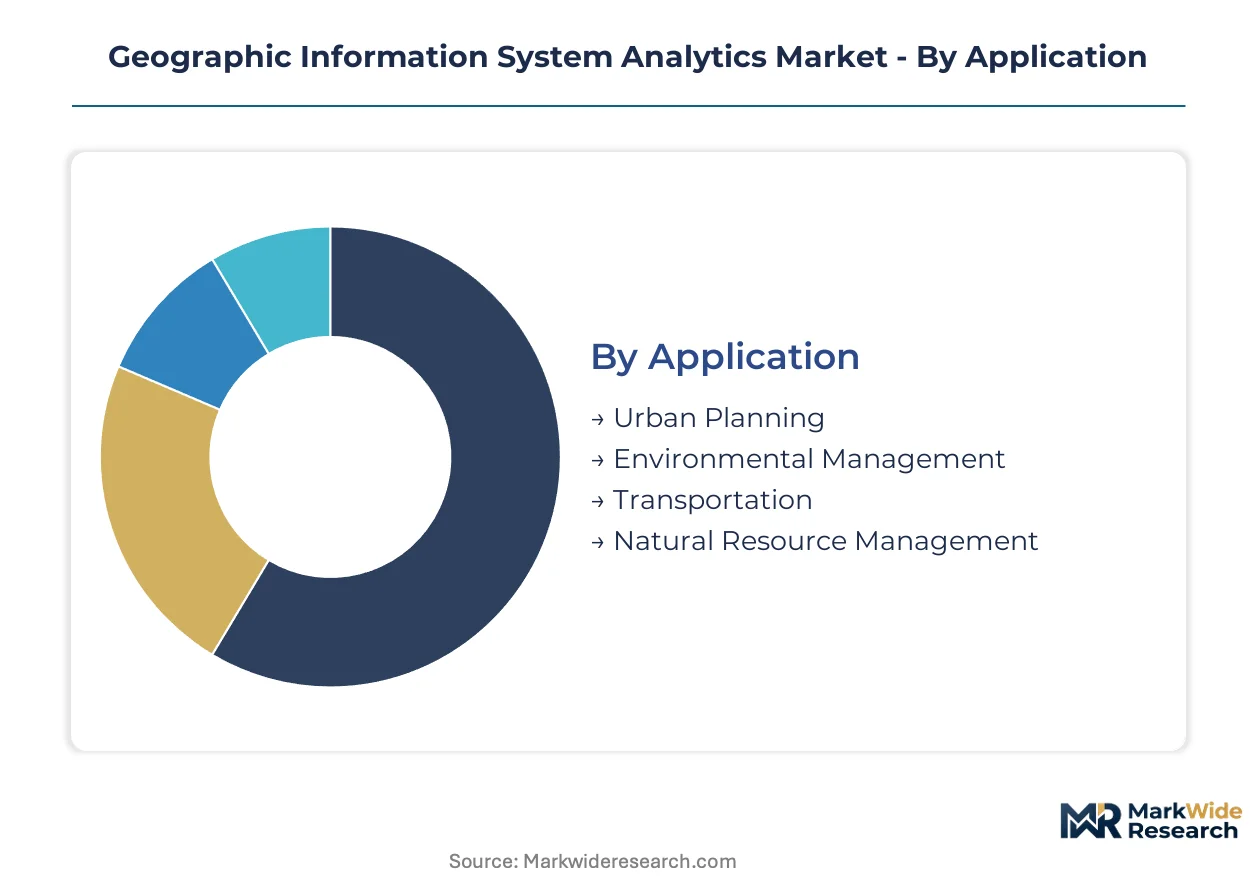
Procurement teams in the GIS analytics market bifurcate spending between mission-critical infrastructure systems and departmental visualization tools. Technology selection hinges on data sovereignty mandates, legacy workflow dependencies, and subscription model flexibility across government and commercial accounts.
Application:
Project scale and regulatory compliance intensity drive software licensing tiers and implementation timelines.
- Urban Planning:Municipal zoning authorities deploy 3D city modeling and demographic overlay tools to optimize land-use decisions. German smart city programs and Chinese municipal infrastructure mandates concentrate procurement volume here, with INSPIRE directive compliance extending sales cycles.
- Environmental Management:Flood prediction and vegetation monitoring workflows demand sub-meter raster processing and automated feature extraction. The EU AI Act's risk classification framework subjects these systems to conformity assessments, filtering vendor eligibility toward certified platforms.
- Transportation:Route optimization and logistics networks utilize real-time spatial inference across distributed assets.
- Natural Resource Management:Air-gapped desktop installations persist in defense and forestry applications where legacy dependencies resist cloud migration.
Volume sits with Urban Planning; growth tilts toward Environmental Management.
Technology:
Architecture decisions fragment between centralized cloud processing and edge-deployed inference engines.
- Cloud GIS:Subscription-based spatial platforms capture expanding utility and real estate developer demand as capital expenditure models shift toward operational spending. California's Department of Transportation exemplifies this migration, consolidating fragmented desktop licenses into unified enterprise agreements.
- Desktop GIS:Perpetual license models retain entrenched positions in defense and natural resource management where air-gapped environments and specialized coordinate systems engineering preserve installed bases.
- Web-Based GIS:Browser-accessible visualization tools serve departmental users with lighter analytical requirements.
- Mobile GIS:Field data collection and asset inspection applications run on ruggedized devices with offline synchronization capabilities.
Desktop GIS anchors current revenue; Cloud GIS climbs the fastest as procurement offices mandate SaaS-evaluation clauses.
End User:
Budget authority and compliance specialization determine platform tier selection and contract duration.
- Government Agencies:Multi-year enterprise agreements with specialized ISO 19115 metadata requirements generate the deepest margin pools. The US Federal Geographic Data Committee's coordinate standardization filters vendor eligibility for federal procurement vehicles.
- Utilities:Electric distribution operators in Germany deploy network digital twins combining IoT sensor layers with real-time spatial analytics for outage response optimization.
- Real Estate Developers:Site selection and portfolio risk quantification drive demand for cloud-native subscription platforms.
- Research Institutions:Academic licensing and open-source integration priorities shape procurement toward flexible, API-accessible systems.
Contract value concentrates with Government Agencies; Utilities gain share fastest through grid modernization mandates.
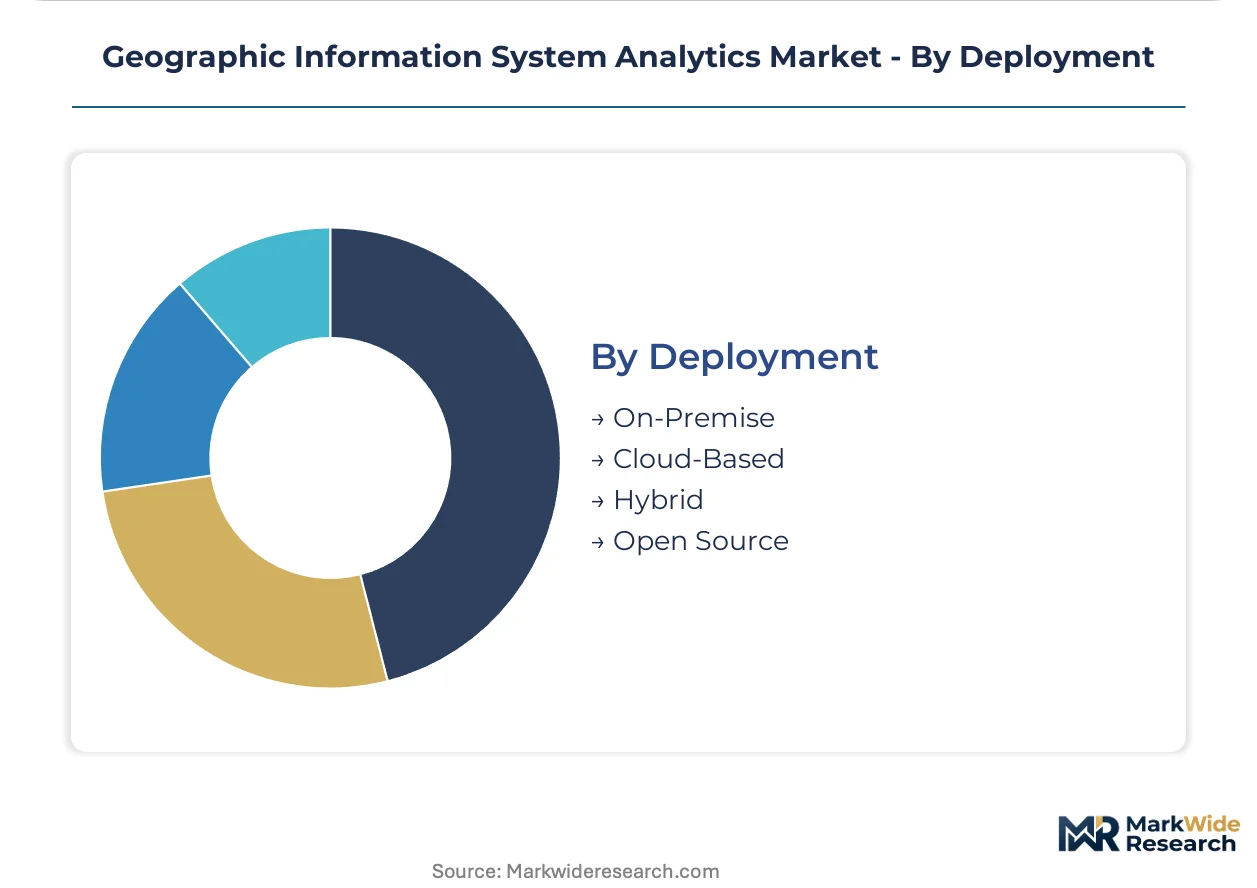
Deployment:
Data residency requirements and interoperability standards constrain architecture choices across jurisdictions.
- On-Premise:Air-gapped installations satisfy defense and critical infrastructure operators where cross-border data flows face tightening export controls on high-resolution imagery.
- Cloud-Based:Municipal and mid-market accounts displace perpetual licenses with subscription pricing, compressing upfront revenue recognition while extending customer lifetime value horizons.
- Hybrid:Edge-cloud configurations enable sub-second spatial inference at remote pipeline and logistics sites.
- Open Source:Academic and non-governmental organizations leverage community-developed tools with custom extension capabilities.
Installed base remains with On-Premise; Hybrid deployments show steepest expansion trajectory from real-time processing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C.'s federal procurement corridors anchor the densest concentration of government GIS contracts, with the Federal Geographic Data Committee's coordinate standardization requirements filtering vendor eligibility toward certified enterprise platforms.
United States
California's Department of Transportation consolidates fragmented desktop licenses into unified enterprise agreements with usage-based scaling provisions. The Federal Geographic Data Committee enforces coordinate system standardization that filters vendor eligibility for federal procurement vehicles. Defense agencies in Virginia and Colorado maintain air-gapped installations that resist cloud migration despite higher total cost of ownership.
China
Beijing-Tianjin-Hebei and Yangtze River Delta municipal governments channel funding into integrated command platforms combining IoT sensor layers with real-time spatial analytics. GB/T 18578 national surveying specifications control vendor selection for domestic infrastructure projects. SuperMap Software Co., Ltd. dominates procurement pipelines in these clusters where localization mandates anchor long-term contracts.
Germany
Electric distribution operators in Bavaria and North Rhine-Westphalia deploy network digital twins to optimize outage response and vegetation management workflows. The EU INSPIRE directive mandates standardized spatial data infrastructure across member states, forcing interoperability investments. German utility regulators reference the EU AI Act's risk classification framework in technical specifications for grid resilience platforms.
Japan
Tokyo's metropolitan government accelerates smart city infrastructure investments with 3D city modeling and demographic overlay tools for land-use optimization. METI guidelines shape procurement criteria for utility digitization programs. Osaka-based industrial clusters concentrate demand for sensor-to-software integration in manufacturing facility management applications.
United Kingdom
London's municipal authorities deploy cloud-native spatial platforms for urban planning and transportation routing optimization. The Environment Agency references EU-derived flood prediction standards that subject high-stakes geospatial inference systems to conformity assessment procedures. Cambridge research clusters drive demand for API-accessible systems with open-source integration priorities.
Geographic Information System Analytics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across data sovereignty and compliance specialization tiers. Esri leverages its ArcGIS ecosystem to sustain dominance in government and defense accounts where multi-year enterprise agreements generate the deepest margin pools. Hexagon AB competes through sensor-to-software integration, while cloud-native specialists capture expanding utility and real estate developer demand. Strategic moves concentrate on M&A for AI-enhanced raster processing capabilities and jurisdictional data center investments to satisfy cross-border data residency requirements.
Within the ecosystem-integrated tier, Esri and Hexagon AB exemplify contrasting approaches to government and industrial accounts. SuperMap Software Co., Ltd. occupies a position within the China-centric localization tier where GB/T 18578 compliance anchors domestic infrastructure procurement. Autodesk Inc. and Bentley Systems, Incorporated sit within the building information modeling convergence space where geospatial engines merge with infrastructure lifecycle management platforms. Trimble Inc. represents the sensor-to-software integration archetype across precision agriculture and construction applications. These company structures reflect the market's bifurcation between mission-critical enterprise platforms and departmental visualization tools.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Trimble Inc. |
| Bentley Systems, Incorporated |
| Autodesk Inc. |
| Pitney Bowes Inc. |
| SuperMap Software Co., Ltd. |
| Topcon Corporation |
| Caliper Corporation |
| Others |
Supply Flow & Price Mechanics
Municipal procurement offices in Germany, China, and the United States anchor demand concentration for GIS analytics platforms, locking in subscription-based SaaS pricing as the dominant commercial model across government verticals. This buyer archetype concentration compresses upfront revenue recognition while extending customer lifetime value horizons through multi-year enterprise agreements with usage-based scaling provisions.
Pricing Analysis
Outcome-based pricing tied to platform uptime and spatial processing throughput anchors enterprise-tier contracts for mission-critical cadastral and utility network applications. Three-tier pricing structure across premium, standard, and economy levels segments the market by compliance certification intensity and data sovereignty requirements. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting legacy desktop license renewals with flexible subscription terms. State transportation departments exhibit highest price sensitivity due to budget cycle constraints, while defense agencies show lowest sensitivity given air-gapped environment mandates that preserve premium perpetual license acceptance.
Supply Chain Analysis
Computational geometry and coordinate systems engineering talent scarcity in the United States, Germany, and China extends implementation timelines for complex federated deployments. Software development draws from satellite imagery providers, cloud infrastructure vendors, and specialized sensor hardware manufacturers. Single-source vulnerability concentrates in high-resolution imagery supply chains where cross-border export controls fragment global product portfolios. Distribution runs through direct enterprise sales teams for government accounts and channel partners for mid-market municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized geospatial talent scarcity props pricing power for certified implementation partners, creating a supply-constrained market structure that favors incumbent platform vendors with established training pipelines and professional services capacity.
For Market Incumbents:Deploy jurisdictional data center investments to satisfy tightening cross-border data residency requirements around high-resolution imagery flows. Esri and Hexagon AB should deepen sensor-to-software integration capabilities through targeted capability acquisitions, countering cloud-native specialists that are capturing utility and real estate developer demand with flexible subscription terms.
For New Entrants and Emerging Players:Capture white-space opportunity in mid-market municipal accounts where fragmented desktop license consolidation creates procurement windows for unified enterprise agreements. Environmental management applications present the most penetrable segment given EU AI Act conformity assessment requirements that filter vendor eligibility toward certified platforms. A cloud-native SaaS go-to-market angle with ISO 19115 metadata pre-certification accelerates sales cycle compression in government verticals.
For Investors and Strategic Acquirers:The window for entry favors vertically integrated sensor-to-software platforms with established government certification pathways and multi-year contract backlogs. Acquisition targets should demonstrate GB/T 18578 compliance for China market access or INSPIRE directive interoperability for European utility digitization programs. Monitor accelerating sovereignty requirements around geospatial data flows as the primary inflection indicator for jurisdictional data center investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Raster Processing Acquisition | Automated feature extraction from satellite imagery compresses manual digitization labor for land registry modernization. |
| Jurisdictional Data Center Expansion | Localized infrastructure satisfies China's GB/T 18578 mandates and EU data sovereignty requirements for defense contracts. |
| Digital Twin Platform Integration | Merging geospatial engines with Building Information Modeling creates unified infrastructure lifecycle management environments. |
| ISO 19115 Metadata Pre-Certification | Standardized geospatial cataloguing compliance extends addressable market into federal procurement vehicles with shortened sales cycles. |
| Edge-Cloud Hybrid Architecture Deployment | Sub-second spatial inference at remote pipeline sites captures utility demand for real-time outage response optimization. |
Methodological Framework
Regulatory filings from the US Federal Geographic Data Committee, EU INSPIRE directive implementation reports, and China's GB/T 18578 national surveying specifications formed the secondary backbone for compliance and standardization mapping. Primary interviews with municipal GIS directors, federal procurement officers, utility network planners, and platform engineering leads at Esri, Hexagon AB, and SuperMap Software Co., Ltd. validated deployment timelines and pricing model transitions. SEC 10-K disclosures and customs data on geospatial software trade flows enabled bottom-up and top-down triangulation across the analysis window.
Bottom-up segmentation modeling tracked application splits across urban planning, environmental management, transportation, and natural resource management verticals. Technology architecture decisions fragmented between cloud GIS, desktop GIS, web-based GIS, and mobile GIS deployments, with end-user concentration in government agencies, utilities, real estate developers, and research institutions. CAGRs were derived from procurement pipeline analysis and subscription pricing migration rates, incorporating AI-enhanced raster processing adoption curves and smart city infrastructure mandate funding flows as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border imagery export control tightening, legacy desktop workflow persistence in defense accounts, and computational geometry talent scarcity inflation. Material deviation in EU AI Act enforcement intensity or China localization mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market