
 Bring Your Own Device Market | 2026-2036
Bring Your Own Device Market Size, Share, and Industry Trends Forecast 2026-2036
Bring Your Own Device Market Analysis
A capital-intensity divergence between integrated platform vendors and point-solution specialists is rotating competitive dynamics across the enterprise mobility stack. Cisco Systems Inc. leverages its network infrastructure dominance to bundle security and access control for BYOD environments. Microsoft Corp. anchors its position through Entra ID and Intune integration with the broader Microsoft 365 ecosystem. VMware Inc. competes through Workspace ONE's endpoint management specialization in hybrid workforce scenarios.
Bring Your Own Device refers to organizational policies permitting employees, contractors, and students to use personally owned smartphones, laptops, and tablets to access corporate applications, data, and networks through containerization, mobile device management (MDM) agents, and identity-aware proxies that enforce encryption, application sandboxing, and conditional access rules. The deployment dimension splits between cloud-based and hybrid architectures, with cloud-based configurations capturing the fastest expansion as enterprises abandon on-premises MDM servers for SaaS-delivered endpoint platforms. Device type segmentation shows smartphones maintaining the largest volume footprint while laptops generate disproportionate security spending per endpoint due to broader data access privileges and persistent VPN requirements.
FCC guidelines on telecommunications infrastructure intersect with NIST zero-trust architecture mandates to elevate baseline security requirements for BYOD program certification across federal contractors and regulated industries. HIPAA security rule enforcement by the Department of Health and Human Services directly shapes healthcare BYOD deployment patterns, particularly around encrypted messaging and patient data access controls. Stakeholders must monitor evolving state-level biometric privacy statutes and their interaction with facial recognition and fingerprint authentication methods deployed on personal devices accessing corporate resources.
Market Dynamics
NIST zero-trust architecture mandates are compressing procurement cycles for federal contractors while HIPAA enforcement tightens healthcare endpoint requirements. These regulatory pressures are restructuring vendor qualification criteria across enterprise mobility stacks.
Growth Catalysts
- Healthcare Clinician Mobility:Hospital systems deploy BYOD policies to reduce hardware procurement costs while maintaining HIPAA-aligned encrypted messaging and patient data access controls.
- FCC Infrastructure Guidelines:Telecommunications security baselines elevate certification requirements for BYOD program deployment across regulated industries and federal contractor supply chains.
- Cloud-Native MDM Migration:Enterprises abandon on-premises endpoint management servers for SaaS-delivered platforms, accelerating subscription revenue models for platform vendors.
Market Restraints
- Biometric Privacy Friction:State-level statutes in Illinois, Texas, and Washington restrict facial recognition and fingerprint authentication deployment on personal devices accessing corporate resources.
- Legacy System Integration Costs:On-premises identity directories and VPN concentrators require expensive middleware development to interoperate with cloud-native zero-trust architectures.
- Certificate Authority Concentration:Device trust anchor provisioning depends on a narrowing oligopoly of commercial root certificate programs, creating single-point-of-failure risk.
Strategic Opportunities
- India Manufacturing Corridor:PLI scheme incentives for electronics assembly create localized device supply chains reducing import duty exposure for multinational BYOD fleets.
- Conditional Access Convergence:Integration of endpoint detection and response with identity-aware proxies enables real-time risk scoring for continuous authentication beyond password boundaries.
- EU AI Act Compliance:Automated behavioral biometrics for device trust scoring must demonstrate explainability and human oversight, favoring vendors with transparent algorithmic governance.
Industry Challenges
- Zero-Trust Architecture Talent Scarcity:Enterprise security teams lack depth in microsegmentation policy design and identity-aware proxy configuration for heterogeneous device fleets.
- Cross-Border Data Residency Complexity:GDPR data localization requirements conflict with centralized SaaS MDM console architectures, forcing regional infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bring Your Own Device Market |
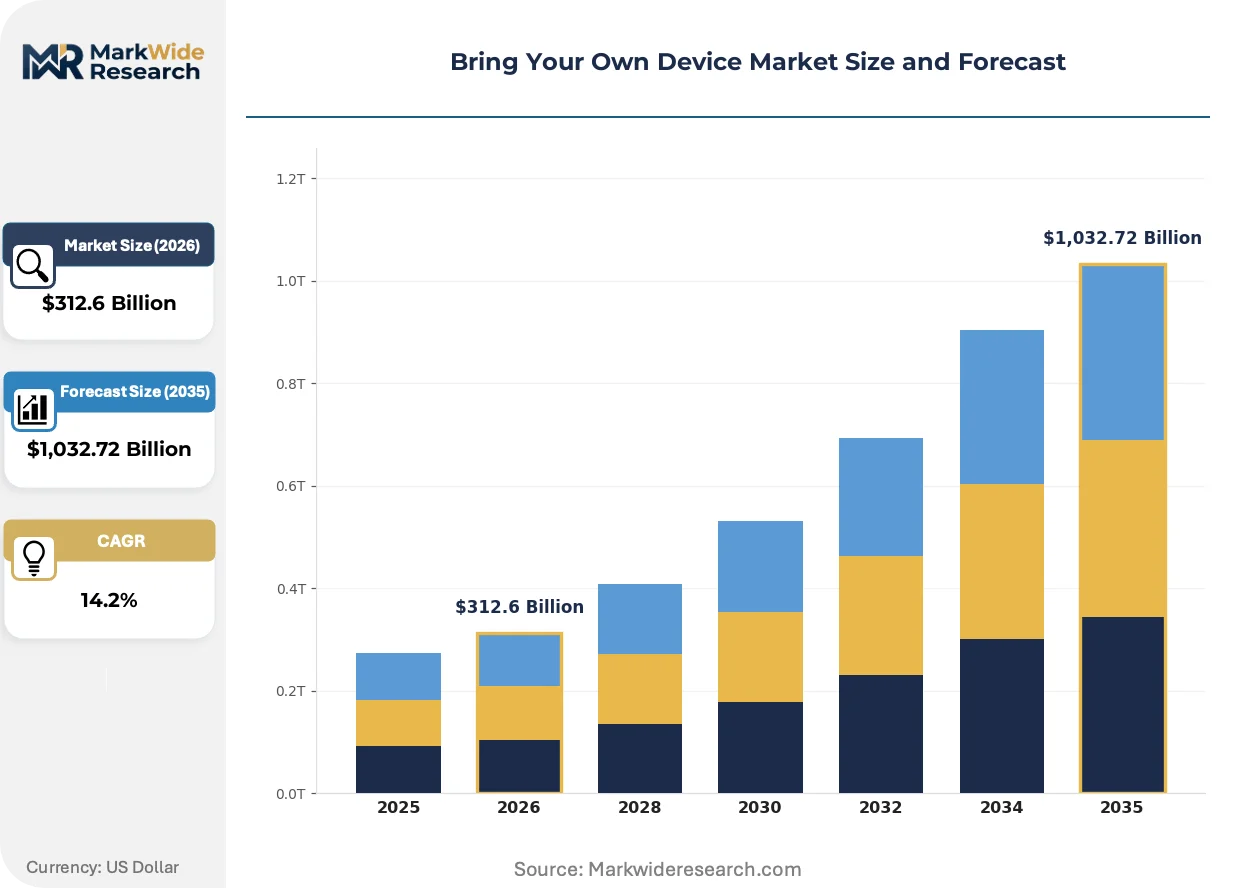
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Employees, Students, Contractors, Freelancers Deployment: On-Premises, Cloud-Based, Hybrid, Remote Device Type: Smartphones, Laptops, Tablets, Desktops Industry Vertical: Education, Healthcare, Finance, Retail |
| Companies Covered | Hewlett Packard Enterprise Development LP, Ivanti, Cisco Systems Inc., Citrix Systems Inc., VMware Inc., IBM, AT&T Intellectual Property, Microsoft Corp., Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bring Your Own Device Market Emerging Trajectories
Containerization technologies are dissolving the boundary between corporate and personal data silos on employee-owned hardware. This architectural shift is redefining liability frameworks and insurance underwriting for enterprise mobility programs.
Software-defined perimeter architectures are fragmenting traditional network security perimeters into identity-centric access policies. Financial services institutions adopt these models fastest, replacing VPN tunnels with session-based microtunnels that authenticate each application request independently. The technology is fragmenting incumbent firewall vendor revenue streams as enterprises decouple network access from network infrastructure ownership.
EU CSRD sustainability reporting mandates now capture Scope 3 emissions from employee-owned devices accessing corporate cloud resources. Hardware manufacturers face disclosure pressure on supply chain carbon intensity for smartphones and laptops procured through BYOD stipend programs. European-headquartered multinationals are responding by tightening device eligibility criteria around energy efficiency certifications and modular repairability standards.
Device-as-a-service procurement models are displacing capital expenditure stipends in large enterprise BYOD programs. Technology sector employers in the United States and United Kingdom pilot subscription arrangements where vendors retain ownership responsibility for security patching and end-of-life data sanitization. This shift transfers residual value risk from employees to employers while centralizing compliance accountability within procurement functions.
Bring Your Own Device Market Segmentation
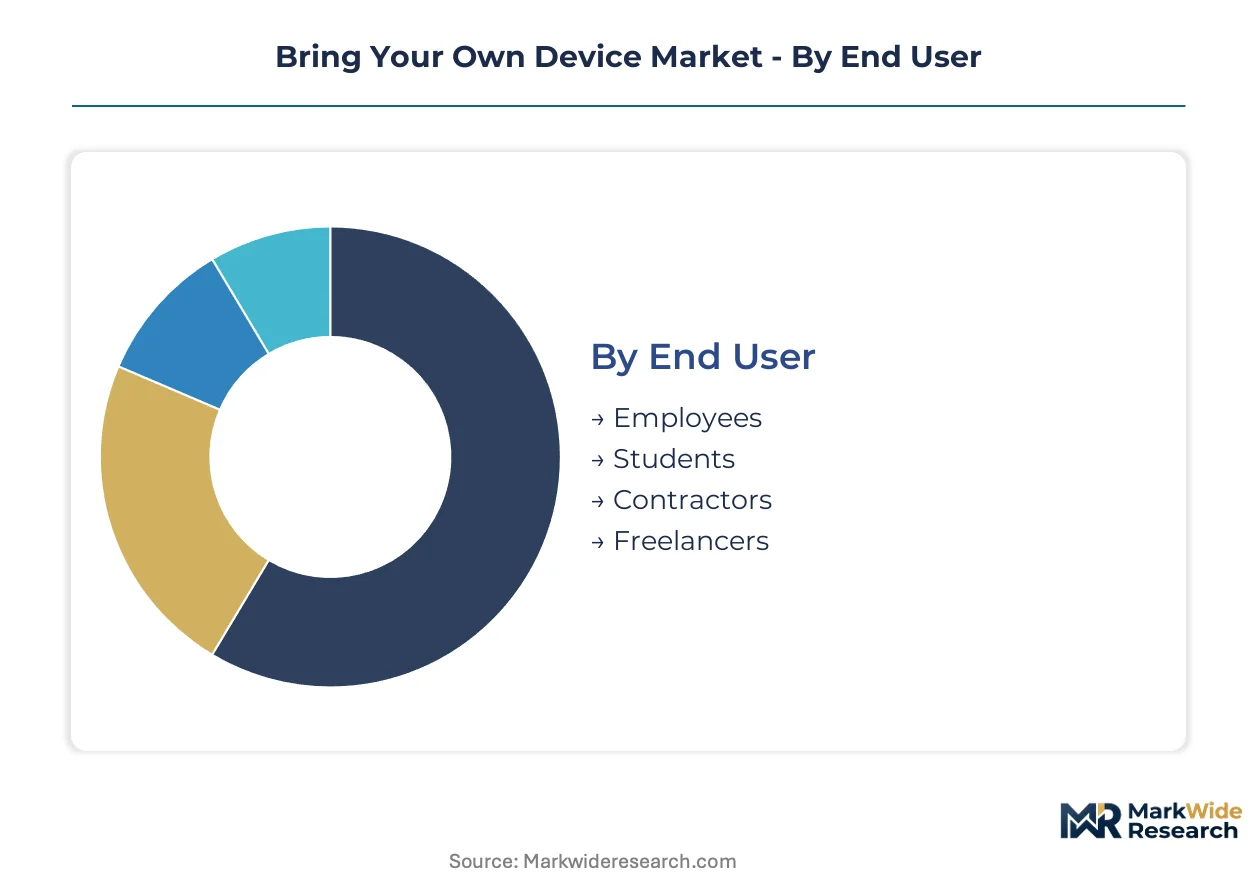
Segmentation in BYOD markets reveals how security requirements, access patterns, and compliance obligations fragment procurement priorities across user populations and infrastructure configurations. Understanding these divides exposes where platform vendors must specialize versus where standardization wins.
End User:
Substitution pressure intensifies where personal device ownership overlaps with employer-funded alternatives, reshaping cost allocation and liability frameworks.
- Employees:Full-time staff accessing corporate email, collaboration suites, and ERP systems through containerized workspaces generate the core revenue base for MDM platform vendors. United States federal contractors dominate procurement volume as NIST zero-trust mandates compress deployment timelines.
- Students:Educational institutions deploy lightweight BYOD policies for learning management system access, though limited budgets constrain spending on advanced endpoint detection. Demand concentrates in K-12 districts and public universities seeking to avoid one-to-one device procurement costs.
- Contractors:Temporary workers require time-bound access credentials and automated deprovisioning workflows that increase per-seat security overhead.
- Freelancers:Independent professionals accessing project-based collaboration tools drive demand for self-service enrollment portals with minimal IT intervention.
Employees anchor the volume base while Contractors gain share at the steepest rate as gig economy workforce models expand.
Deployment:
Cost tier differentiation separates capital-intensive legacy infrastructure from subscription-native SaaS platforms, rotating vendor competitive dynamics.
- Cloud-Based:SaaS-delivered endpoint management platforms eliminate server maintenance overhead and accelerate feature deployment cycles. Enterprises in the United States abandon on-premises MDM servers fastest, driven by federal contractor zero-trust certification requirements.
- Hybrid:Split architectures preserve on-premises identity directory integration while offloading policy enforcement to cloud consoles. Financial services institutions favor this model to maintain legacy core system connectivity.
- On-Premises:Self-hosted MDM servers persist in classified environments and highly regulated jurisdictions with strict data residency mandates.
- Remote:Work-from-anywhere configurations prioritize zero-trust network access over traditional VPN tunneling, demanding continuous device posture validation.
Cloud-Based deployments dominate new procurement while Remote configurations climb the fastest as distributed workforce models harden.
Device Type:
Application-specific access privileges and data exposure levels create divergent security spending per endpoint across form factors.
- Smartphones:Mobile-first collaboration and encrypted messaging applications drive the highest unit volumes, though limited screen real estate constrains deep system access. Healthcare systems deploy smartphones fastest for clinician mobility, tethered to HIPAA-aligned patient data controls.
- Laptops:Full operating system access and persistent VPN requirements generate disproportionate security investment per device, including advanced threat detection and data loss prevention agents. Knowledge workers in finance and technology sectors concentrate demand.
- Tablets:Intermediate form factors serve field service and retail floor applications where touch-first interfaces outweigh keyboard dependency.
- Desktops:Personal workstation access to corporate resources remains rare outside creative industries with specialized peripheral requirements.
Smartphones anchor the volume base while Laptops command the highest security expenditure intensity per deployed unit.
Industry Vertical:
Regulatory maturity and data sensitivity gradients separate sectors where BYOD accelerates from those where it faces structural headwinds.
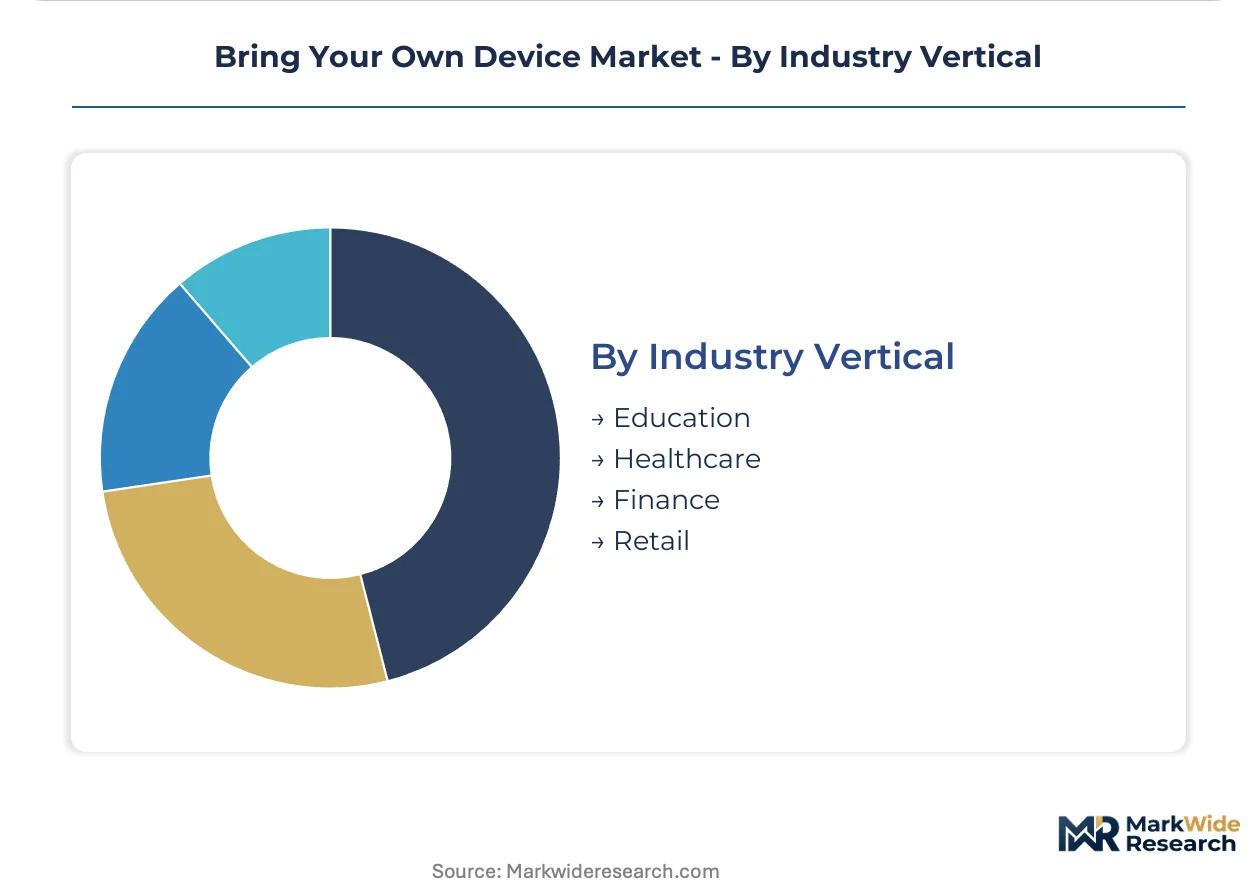
- Healthcare:HIPAA security rule enforcement mandates encrypted messaging, audit logging, and remote wipe capabilities that elevate platform procurement specifications. Hospital systems in the United States reduce hardware capital expenditure through clinician BYOD programs.
- Finance:Gramm-Leach-Bliley Act and SEC cybersecurity guidelines impose stringent access controls on personal devices touching customer financial data. Broker-dealers and investment advisors lead zero-trust architecture adoption.
- Education:FERPA compliance requirements and limited IT budgets favor lightweight containerization over comprehensive endpoint detection.
- Retail:Seasonal workforce fluctuations and high turnover drive demand for rapid provisioning and deprovisioning automation.
Healthcare anchors the volume base while Finance expands most quickly as regulatory pressure intensifies cybersecurity investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between federal contractor-heavy markets and privacy-regulated jurisdictions. The United States concentrates procurement volume through NIST zero-trust mandates, while European deployments navigate GDPR biometric restrictions. Asian markets split between India's PLI-driven manufacturing localization and China's domestic platform substitution.
United States
Federal contractors and healthcare systems drive BYOD deployment intensity. NIST zero-trust architecture mandates compress procurement cycles for defense and civilian agency suppliers. Hospital networks in Texas and California reduce capital expenditure through clinician mobility programs.
Germany
Industrial Mittelstand firms adopt hybrid workforce endpoint management. The EU AI Act shapes automated behavioral biometrics deployment for device trust scoring. Manufacturing clusters in Bavaria and Baden-Württemberg integrate BYOD with shop-floor digitalization initiatives.
India
IT services exporters and financial institutions expand BYOD for distributed engineering teams. PLI scheme incentives for electronics assembly localize device supply chains. Bengaluru and Hyderabad technology corridors concentrate SaaS-delivered MDM platform adoption.
United Kingdom
Financial services institutions lead software-defined perimeter adoption for remote trading floors. FCA operational resilience requirements elevate endpoint detection specifications. London's insurance and fintech clusters drive conditional access convergence investments.
Japan
Manufacturing conglomerates deploy BYOD for field service and supply chain mobility. METI cybersecurity guidelines harmonize with NIST frameworks for multinational operations. Tokyo-Osaka industrial corridors anchor hybrid cloud endpoint management demand.
Bring Your Own Device Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Network infrastructure vendors bundle security and access control, while endpoint management specialists compete through hybrid workforce scenarios. Strategic archetypes include platform integrators, network-security bundlers, and cloud-native SaaS providers. Dominant competitive moves center on ecosystem lock-in through identity directory integration and subscription revenue model migration.
Among platform integrators, Microsoft Corp. and VMware Inc. exemplify contrasting approaches to enterprise mobility stack dominance. Cisco Systems Inc. anchors the network-security bundler archetype, leveraging infrastructure relationships for BYOD program penetration. These three occupy positions across the integrated leader tier, each representing distinct vectors of competitive differentiation.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Development LP |
| Ivanti |
| Cisco Systems Inc. |
| Citrix Systems Inc. |
| VMware Inc. |
| IBM |
| AT&T Intellectual Property |
| Microsoft Corp. |
| Oracle |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with SaaS endpoint management vendors lock in multi-year price visibility for enterprise buyers while securing recurring revenue pipelines for platform providers. These arrangements concentrate procurement leverage among United States federal contractors facing compressed NIST zero-trust deployment timelines.
Pricing Analysis
After-sales revenue from security patch management and compliance audit support drives lifetime value beyond initial subscription fees. Three-tier pricing structure across premium, standard, and economy levels segments by endpoint detection sophistication and SLA response guarantees. Cost compression in mid-tier offerings intensifies as VMware and Microsoft bundle identity management with broader cloud suites. Federal contractors show lowest price sensitivity due to mandate-driven procurement urgency, while K-12 education districts anchor the economy tier with constrained IT budgets.
Supply Chain Analysis
Just-in-time provisioning dominates device enrollment workflows, though strategic stockpiling of hardware security modules persists among financial services institutions. Component sourcing concentrates in Taiwan for semiconductor trust anchors, China for smartphone assembly, and South Korea for display panels. Supply chain vulnerability rests on concentrated certificate authority root programs operated by a narrowing oligopoly of commercial providers. Distribution runs through direct vendor relationships with enterprise procurement functions, bypassing traditional IT channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as zero-trust architecture mandates splinter procurement requirements across federal, healthcare, and financial verticals with incompatible compliance timelines.
For Market Incumbents: Compound ecosystem lock-in through deeper Entra ID and Intune integration with Microsoft 365 productivity suites, while acquiring niche zero-trust policy automation specialists to offset talent scarcity in microsegmentation design. Vertical integration into hardware security module manufacturing reduces certificate authority concentration risk. For New Entrants and Emerging Players: Lead with transparent algorithmic governance for EU AI Act-compliant behavioral biometrics, targeting German industrial Mittelstand firms with explainable device trust scoring. White-space concentration sits in conditional access convergence for hybrid cloud financial services deployments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native SaaS endpoint management providers with healthcare and federal contractor customer concentration. Acquisition priority targets vendors with pre-built HIPAA and NIST compliance templates. Signal to watch is PLI scheme localization progress in India's electronics manufacturing corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Entra ID anchoring unifies identity, device, and application access policies. |
| Acquisition of Specialist Firm | Zero-trust policy automation targets address enterprise talent scarcity in microsegmentation. |
| Strategic Partnership | Cisco infrastructure bundling penetrates federal contractor supply chains through existing relationships. |
| Geographic Expansion | India PLI-driven manufacturing corridors reduce import duty exposure for multinational BYOD fleets. |
| Product Launch | EU AI Act-compliant behavioral biometrics favor vendors with transparent algorithmic governance frameworks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CISOs, IT procurement officers, endpoint management engineers, and compliance auditors at healthcare systems and federal contractors. Secondary validation drew from NIST framework documentation, HIPAA security rule enforcement records, SEC cybersecurity disclosure filings, and hyperscaler MDM platform revenue disclosures. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against aggregate platform vendor revenues anchored the analytical framework.
Across the analysis window, the forecasting framework modeled segmentation by deployment architecture, device type, end-user category, and industry vertical with explicit regulatory cluster differentiation. CAGRs derived from historical subscription revenue trajectories and projected endpoint proliferation rates across federal contractor and healthcare addressable markets. Input variables included NIST zero-trust mandate implementation timelines, HIPAA enforcement intensity indices, and cloud-native MDM migration velocity metrics.
The analysis sits within stated boundaries; outcomes outside sustained federal procurement urgency or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect assumptions around certificate authority market structure stability and cross-border data residency framework evolution. Revision becomes warranted when PLI scheme localization thresholds in India's electronics manufacturing corridor accelerate or decelerate materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
GCC Managed Service Market