
 Brazil Geospatial Analytics Market | 2026-2036
Brazil Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Geospatial Analytics Market Insights
Platform licensing revenue is reshaping competitive economics as vendors shift from perpetual software sales to recurring subscription models. Esri Global, Inc. anchors its position through deep integration with Brazilian cadastral databases and municipal planning workflows. Hexagon AB leverages its sensor manufacturing heritage to bundle hardware-software offerings for infrastructure monitoring contracts. Google LLC competes aggressively on cloud-based imagery access, undercutting traditional enterprise pricing while expanding developer adoption across regional governments.
Geospatial analytics encompasses the computational processing of location-referenced data to extract spatial patterns, typically operating on raster resolutions from sub-meter satellite imagery to centimeter-grade drone surveys and vector datasets with topological integrity rules. The discipline serves core functions in land tenure verification, resource allocation optimization, and disaster response coordination across Brazilian federal agencies. Remote sensing technology leads current deployment volumes as INPE's satellite constellation and international imagery providers feed agricultural and deforestation monitoring pipelines. Cloud-based solutions represent the fastest-expanding delivery mode, driven by SEBRAE-backed digital transformation programs that lower capital barriers for municipal governments. On-premises installations retain entrenched positions within defense and critical infrastructure operators governed by data sovereignty requirements.
ANVISA regulates health-geospatial data integration through patient privacy protocols, while INCRA mandates georeferenced parcel documentation for land regularization programs that directly stimulate cadastral analytics demand. IBGE's national spatial data infrastructure standards shape interoperability requirements for vendors seeking federal procurement eligibility. Stakeholders must monitor evolving CAR (Rural Environmental Registry) enforcement intensity, as expanded satellite verification obligations will determine whether environmental compliance analytics becomes a sustained high-margin specialization or a commoditized baseline capability.
Market Dynamics
Platform licensing economics are restructuring vendor revenue streams as perpetual software sales give way to recurring subscription models across Brazilian federal and municipal procurement channels.
Growth Catalysts
- CAR Satellite Verification Mandates:INCRA's expanded Rural Environmental Registry enforcement obligations require georeferenced parcel documentation, directly stimulating cadastral analytics demand from land regularization programs.
- SEBRAE Digital Transformation:The agency's cloud migration subsidies reduce capital barriers for municipal governments adopting geospatial platforms through software-as-a-service delivery.
- Precision Agriculture Expansion:Mato Grosso and São Paulo farming operations deploy satellite-based crop monitoring systems to optimize input application and yield forecasting.
Market Restraints
- Data Sovereignty Infrastructure Costs:Defense and critical infrastructure operators mandate on-premises installations, requiring substantial capital expenditure for localized server architecture and security hardening.
- INPE Dataset Dependency:Domestic solution providers rely heavily on the national space research institute's proprietary remote sensing data, creating concentration risk in upstream data supply.
- ANVISA Privacy Protocol Friction:Health-geospatial data integration faces patient confidentiality restrictions that complicate cross-referencing medical records with location-based analytics.
Strategic Opportunities
- Amazon Basin Deforestation Monitoring:Expanded environmental compliance verification obligations position specialized analytics providers to capture sustained federal contracting volume.
- Drone Survey Convergence:Integration of centimeter-grade unmanned aerial vehicle data with satellite imagery creates new service tiers for infrastructure and agricultural clients.
- Municipal Planning Workflow Embeddedness:Deep integration with Brazilian cadastral databases enables vendors to establish switching-cost barriers within state and local government procurement.
Industry Challenges
- IBGE Interoperability Certification:Federal procurement eligibility requires compliance with national spatial data infrastructure standards, extending vendor sales cycles and technical validation timelines.
- Geospatial Data Science Talent Scarcity:Shortage of professionals combining remote sensing expertise with cloud platform architecture limits implementation velocity for mid-tier municipal clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Geospatial Analytics Market |
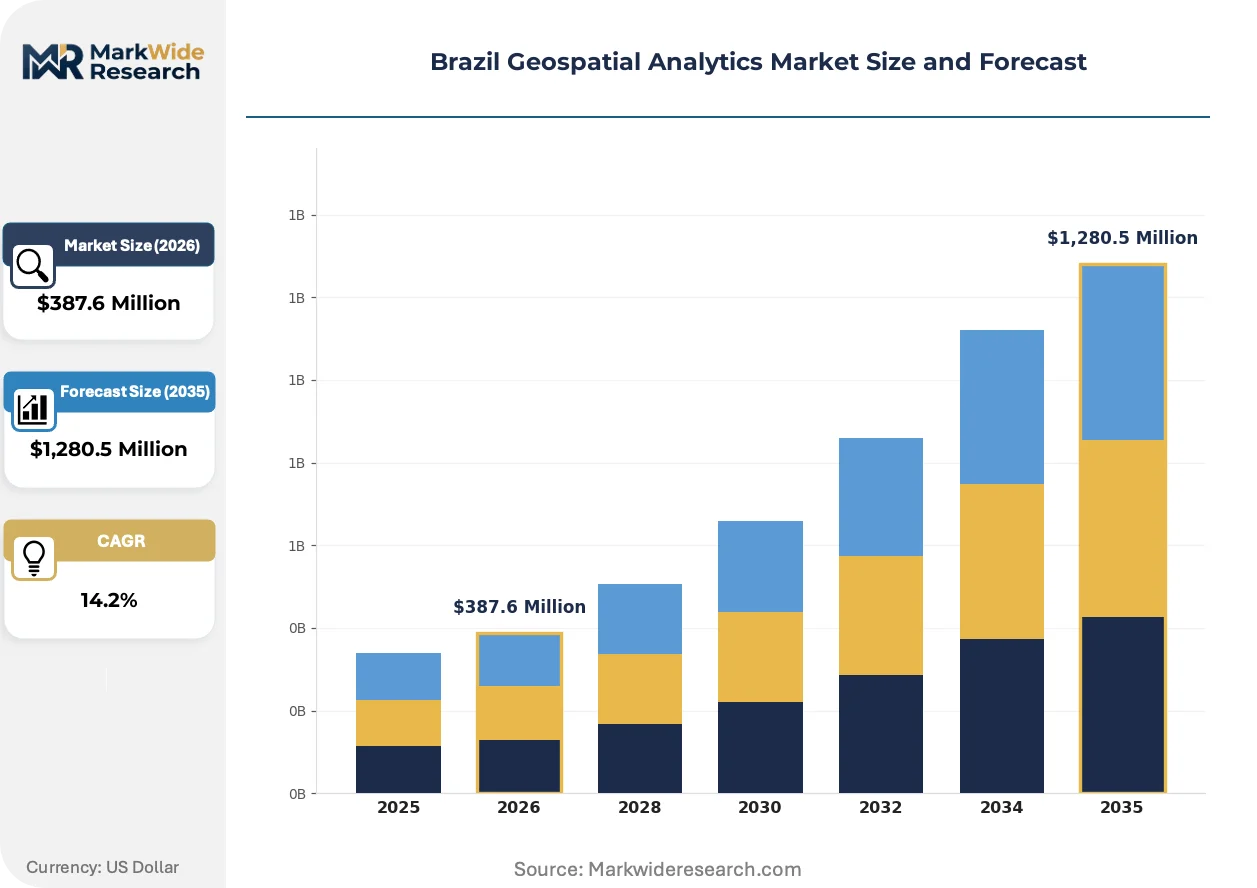
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Management, Transportation, Agriculture Technology: Remote Sensing, Geographic Information System, Global Navigation Satellite System, Data Visualization End User: Government, Defense, Retail, Energy Solution: Cloud-based, On-premises, Hybrid, Mobile |
| Companies Covered | Esri Global, Inc., Google LLC (Alphabet Inc.), Hexagon AB, Trimble Inc., INPE (National Institute for Space Research), Microsoft Corporation, IBM Corporation, Oracle Corporation, Leica Geosystems AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Geospatial Analytics Market Trends and Innovations
Cloud-native delivery architectures are displacing legacy on-premises deployments across Brazilian public sector procurement, with subscription economics reshaping vendor-customer relationships and technical implementation patterns.
Real-time satellite imagery processing pipelines are collapsing the latency between data capture and actionable agricultural insight. Mato Grosso soybean operators now receive sub-24-hour crop health assessments. This compression eliminates the competitive advantage of traditional weekly reporting services.
IBGE's national spatial data infrastructure standards are mandating topological integrity rules across all federal procurement-eligible platforms. Vendors must reengineer vector dataset handling to achieve certification. Municipal governments in São Paulo and Minas Gerais states are prioritizing pre-certified solutions to accelerate deployment timelines.
Outcome-based service contracting is replacing perpetual license purchases in state environmental agencies. IBAMA regional offices now procure deforestation monitoring as operational expenditure rather than capital investment. This shift concentrates vendor selection authority within federal program administrators rather than distributed municipal IT departments.
Brazil Geospatial Analytics Market Segmentation
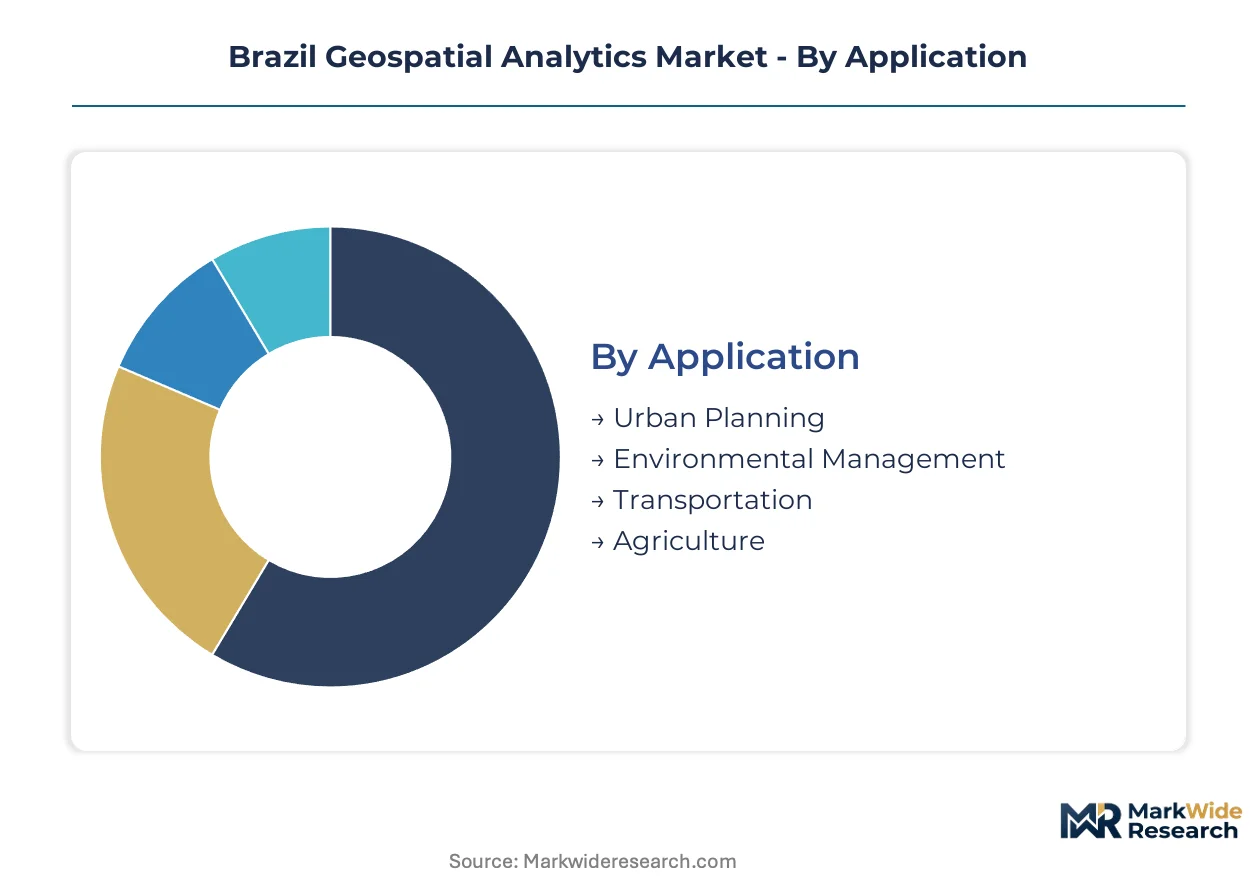
Segmentation in Brazil's geospatial analytics market reveals distinct procurement rhythms across federal agencies, state environmental bodies, and private agricultural operators. Each dimension—application, technology, end user, and solution—exhibits different contract renewal cycles and technology refresh rates that shape vendor strategy.
Application:
Urban planning contracts turn over on electoral cycles while environmental monitoring operates on continuous satellite refresh schedules.
- Urban Planning:Municipal master plans and cadastral updates drive recurring demand from São Paulo and Belo Horizonte metropolitan authorities. IBGE interoperability certification requirements extend procurement timelines for vendors seeking federal eligibility.
- Environmental Management:CAR satellite verification mandates from INCRA generate sustained federal contracting volume for deforestation monitoring and rural parcel documentation. Amazon basin enforcement obligations position specialized providers for long-term service agreements.
- Transportation:State infrastructure departments in Minas Gerais and Rio de Janeiro deploy corridor optimization analytics for freight routing.
- Agriculture:Mato Grosso soybean operators receive sub-24-hour crop health assessments through real-time processing pipelines.
Urban planning dominates installed base. Environmental management is where expansion concentrates.
Technology:
Cost tiers separate capital-intensive sensor hardware from software-only deployments with minimal upfront investment.
- Remote Sensing:INPE's proprietary satellite constellation feeds agricultural and deforestation monitoring pipelines with raster resolutions from sub-meter imagery. Domestic solution providers face concentration risk in upstream data supply from the national space research institute.
- Geographic Information System:Vector dataset handling with topological integrity rules anchors cadastral analytics and land tenure verification workflows. IBGE certification mandates reengineer platform architectures for federal procurement eligibility.
- Global Navigation Satellite System:Centimeter-grade positioning supports drone survey convergence for infrastructure monitoring contracts.
- Data Visualization:Cloud-native dashboards displace legacy desktop installations across SEBRAE-backed municipal digital transformation programs.
Remote sensing commands premium pricing. Data visualization is climbing the fastest.
End User:
Volume concentration varies sharply between centralized federal procurement and fragmented municipal adoption.
- Government:State and municipal planning agencies concentrate demand within infrastructure and environmental compliance verification. SEBRAE cloud migration subsidies reduce capital barriers for software-as-a-service delivery across regional governments.
- Defense:Data sovereignty requirements mandate on-premises installations with substantial security hardening expenditure. Critical infrastructure operators govern procurement through classified procurement channels.
- Retail:Location intelligence for supply chain optimization and site selection drives private sector adoption.
- Energy:Transmission corridor monitoring and renewable site assessment create specialized analytics demand from utilities.
Government holds the largest contract volume. Defense maintains the highest security premiums.
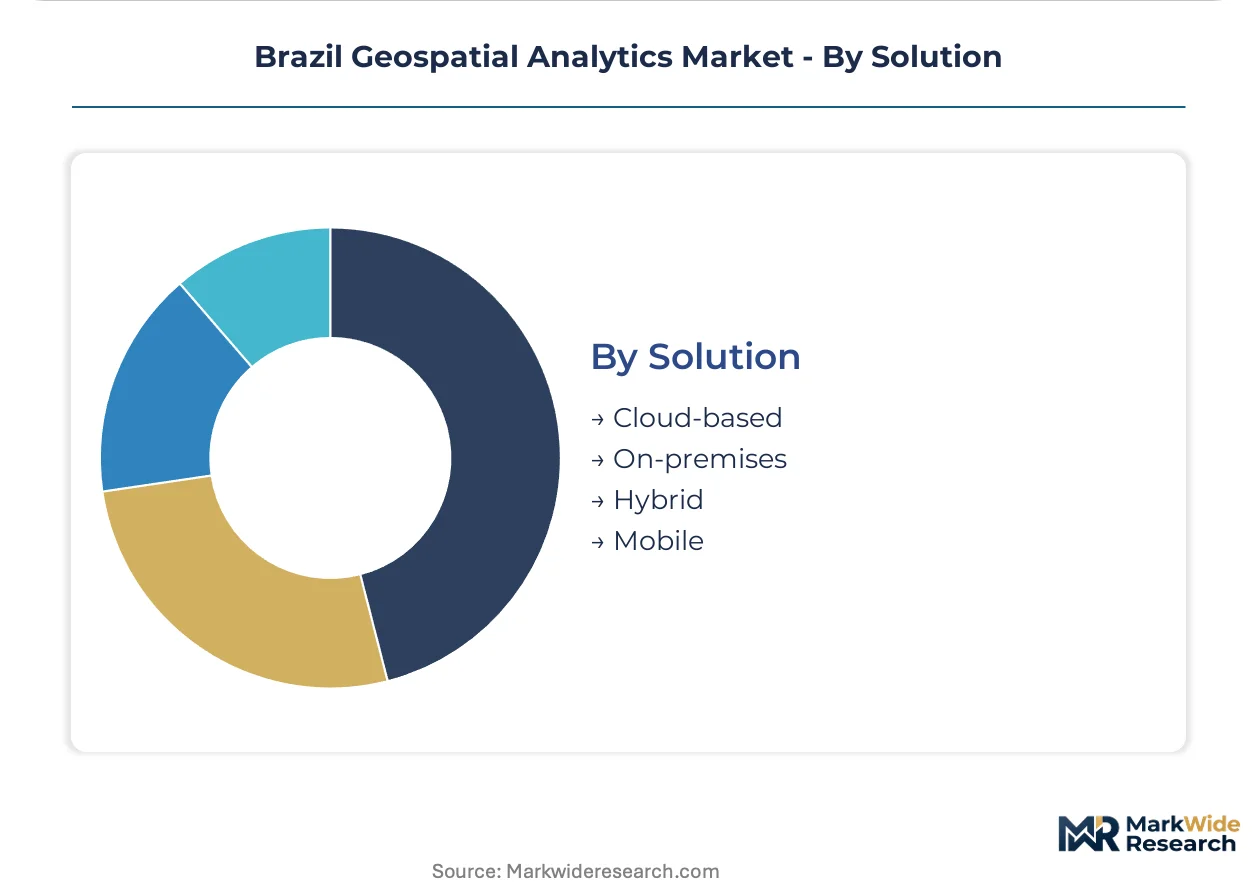
Solution:
Customer type determines deployment architecture—federal agencies favor flexibility while operators with sovereignty constraints require physical control.
- Cloud-based:Subscription economics reshape vendor-customer relationships through SEBRAE-backed programs lowering municipal entry barriers. Real-time satellite imagery processing pipelines collapse latency between data capture and agricultural insight.
- On-premises:Defense and critical infrastructure operators mandate localized server architecture governed by data sovereignty requirements. ANVISA patient privacy protocols similarly restrict health-geospatial integration to controlled environments.
- Hybrid:Split architectures accommodate sensitive processing on-site with public cloud visualization layers for inter-agency collaboration.
- Mobile:Field verification workflows for INCRA land regularization programs deploy smartphone-based georeferenced documentation.
On-premises retains entrenched positions in sovereign sectors. Cloud-based solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement budgets in Brazil's interior states exhibit acute price sensitivity, while federal agencies in Brasília and defense operators tolerate substantial premiums for sovereignty-compliant deployments.
São Paulo
Metropolitan planning authorities drive sustained demand for cadastral analytics and urban master plan updates. IBGE interoperability certification requirements extend vendor sales cycles as municipal governments prioritize pre-certified solutions. The São Paulo state environmental secretariat deploys satellite-based deforestation monitoring for Atlantic Forest remnants.
Minas Gerais
State infrastructure departments procure corridor optimization analytics for iron ore freight routing from the Quadrilátero Ferrífero mining district. SEBRAE cloud migration subsidies accelerate software-as-a-service adoption among mid-sized municipal governments. Belo Horizonte's metropolitan planning institute anchors regional demand for georeferenced parcel documentation.
Mato Grosso
Soybean operators receive sub-24-hour crop health assessments through real-time satellite imagery processing pipelines. INPE's proprietary remote sensing datasets feed agricultural monitoring platforms with concentration risk in upstream data supply. The Sorriso-Rondonópolis corridor concentrates precision agriculture technology deployment.
Pará
Federal environmental enforcement obligations generate sustained contracting volume for Amazon basin deforestation monitoring. IBAMA regional offices procure monitoring services as operational expenditure rather than capital investment. The Belém-Santarém axis anchors specialized analytics demand from sustainable supply chain verification programs.
Rio Grande do Sul
State water resource management agencies deploy hydrological modeling for Guaíba basin flood control. ANVISA patient privacy protocols restrict health-geospatial integration to on-premises installations with substantial security hardening. Porto Alegre's metropolitan planning consortium drives demand for climate adaptation infrastructure analytics.
Brazil Geospatial Analytics Market Competitive Landscape
Global platform providers and domestic data integrators split the market along the fault line of proprietary satellite constellation access versus localized regulatory compliance expertise. Concentration remains moderate, with federal procurement eligibility requirements creating certification barriers that favor established incumbents. Two strategic archetypes dominate: cloud-native imagery aggregators competing on developer ecosystem breadth, and hardware-software bundlers leveraging sensor manufacturing heritage for infrastructure monitoring contracts. Competitive dynamics center on IBGE interoperability certification achievement and deep embedding within municipal planning workflows.
Within the global platform tier, Esri Global, Inc. and Google LLC exemplify divergent approaches to the Brazilian public sector. Esri occupies a position anchored through cadastral database integration and municipal planning workflow embeddedness. Google represents the cloud-native imagery access archetype, competing aggressively on developer adoption across regional governments. Hexagon AB sits within the hardware-software bundler category, leveraging sensor manufacturing heritage for infrastructure monitoring contracts.
| Leading Market Players |
|---|
| Esri Global, Inc. |
| Google LLC (Alphabet Inc.) |
| Hexagon AB |
| Trimble Inc. |
| INPE (National Institute for Space Research) |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Leica Geosystems AG |
| Others |
Pricing and Supply Chain Analysis
INPE dataset dependency concentrates upstream supply risk for domestic solution providers, compressing margins on entry-level SaaS tiers while amplifying pricing power for vendors with alternative satellite imagery pipelines. This single-source vulnerability forces tiered pricing stratification across certification-grade platforms, with IBGE interoperability achievement separating premium federal-eligible offerings from commoditized municipal deployments.
Pricing Analysis
Platform support and extended implementation services drive lifetime value beyond initial subscription fees. Three-tier pricing structure across premium, standard, and economy levels separates IBGE-certified federal-eligible platforms from SEBRAE-subsidized municipal SaaS and basic data visualization tools. Price differentiation hinges on certification level and embeddedness within cadastral database workflows. Cost compression in the standard tier intensifies as Google LLC's cloud-native imagery access undercuts traditional enterprise pricing. Municipal governments in Brazil's interior states exhibit acute price sensitivity, while defense operators tolerate substantial premiums for sovereignty-compliant on-premises installations.
Supply Chain Analysis
Tariff exposure on sensor hardware imports from the United States and Germany elevates total cost of ownership for infrastructure monitoring contracts. Upstream manufacturing concentrates in China for drone components, the United States for GIS software licensing, and Brazil for INPE satellite data processing. Raw material dependencies include optical sensor arrays, cloud compute infrastructure, and centimeter-grade GNSS receivers. Single-source vulnerability in INPE's proprietary remote sensing datasets creates concentration risk for domestic platform providers. Distribution runs through direct federal procurement channels, SEBRAE-backed municipal digital transformation programs, and specialized systems integrators serving defense and critical infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IBGE interoperability certification mandates are shifting vendor selection authority toward platform-ecosystem dominance, rewarding deep embedding within municipal planning workflows over point-solution functionality. This inflection concentrates procurement power within certified incumbents while raising barriers for unvalidated entrants.
For Market Incumbents: Build switching-cost moats through cadastral database integration and multi-year municipal master plan contracts. Deepen vertical integration into drone survey hardware to capture infrastructure monitoring margin pools. Esri Global, Inc.'s workflow embeddedness exemplifies defensible positioning against Google's developer-ecosystem aggression. For New Entrants and Emerging Players: Brazil's northeastern municipal governments present underpenetrated demand for SEBRAE-subsidized cloud analytics. Target mid-sized environmental compliance verification providers lacking CAR satellite verification capabilities. Partner with INPE data resellers to bypass proprietary dataset access barriers. For Investors and Strategic Acquirers: ANVISA's evolving health-geospatial privacy protocols reshapes the acquisition landscape toward HIPAA-compliant platform architectures. Long-term viability favors vendors with hybrid cloud-on-premise deployment flexibility across federal and defense verticals. Monitor IBAMA's shift to outcome-based service contracting as the signal for sustained operational expenditure growth versus capital investment cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| IBGE Interoperability Certification Investment | Federal procurement eligibility unlocks Brasília agency contracts and multi-state municipal rollouts. |
| Drone-Satellite Data Convergence Platform | Centimeter-grade UAV integration with INPE imagery creates premium service tiers for Mato Grosso agribusiness. |
| SEBRAE Partnership Channel Development | Cloud migration subsidies lower municipal sales friction and accelerate subscription revenue conversion. |
| CAR Verification Workflow Embeddedness | INCRA land regularization mandates generate recurring environmental compliance analytics demand. |
| Defense Sector Sovereignty Certification | On-premises architecture clearance captures critical infrastructure premiums from data-localization requirements. |
Research Methodology
Cross-validation between primary interviews with municipal planning officers and secondary analysis of INPE data release schedules anchors the qualitative findings. The research combined discussions with state environmental secretariat directors, SEBRAE digital transformation leads, cadastral database administrators, and federal procurement contract officers. Secondary sources included IBGE technical standards documentation, INCRA CAR enforcement bulletins, ANVISA health data privacy protocols, and SEBRAE cloud adoption program disclosures. Bottom-up municipal budget analysis and top-down federal contracting pipeline assessment provided triangulation.
Calibration against historical subscription revenue recognition patterns and perpetual license conversion rates shaped the projection framework. Segmentation dimensions modeled include application type, deployment architecture, end-user tier, and geographic procurement cluster across the analysis window. CAGRs derived from technology refresh cycle analysis and electoral-cycle urban planning contract turnover. Forecast inputs incorporated SEBRAE subsidy allocation trajectories and INPE satellite constellation expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native pricing moves by hyperscaler entrants would shift outcomes toward accelerated SaaS conversion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Business Value Dashboard Market
Analytics
Data Wrangling Market
Analytics
In-Memory Analytics Tools Market
Analytics
Contact Center Intelligence Market
Analytics
Sales Intelligence Market
Analytics
Europe Mobile Analytics Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Cognitive Analytics Solutions Market
Analytics
Global Network Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
North America Location Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Data Preparation Market
Analytics
AI Performance Marketing Market
Analytics
Global Big Data Analytics in Telecom Market