
 South Korea Location-Based Services Market | 2026-2036
South Korea Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Location-Based Services Market Insights
Domestic telecom infrastructure investment is pivoting toward edge-computing-enabled positioning networks. SK Telecom leverages its 5G standalone architecture to deliver sub-meter accuracy for enterprise clients. Naver sustains dominance in consumer mapping through deep integration with its super-app ecosystem. Kakao competes by embedding location intelligence across ride-hailing, delivery, and payment services.
Location-Based Services encompass technologies that determine geographic coordinates of mobile devices through satellite, radio frequency, or sensor fusion methods, typically achieving accuracy between one and fifteen meters depending on environmental conditions and signal availability. These systems enable real-time spatial computation for commercial routing, asset monitoring, proximity marketing, and emergency dispatch. Navigation and mapping applications anchor revenue generation due to entrenched consumer habits and enterprise logistics dependency. Location analytics represents the fastest-expanding category as retailers and urban planners deploy footfall heat-mapping and dwell-time analysis. Bluetooth and Wi-Fi hybrid positioning gains share indoors where GPS signals attenuate, creating margin pools for venue-specific deployments.
MFDS guidelines intersect with healthcare location tracking for patient monitoring and pharmaceutical cold-chain verification. The Personal Information Protection Commission enforces geospatial data anonymization standards that constrain raw location monetization. KISA certification requirements for critical infrastructure positioning systems elevate compliance costs for new entrants. Stakeholders must weigh the trade-off between precision granularity and privacy-engineering investments as regulatory scrutiny intensifies.
Market Dynamics
Edge-computing-enabled positioning networks are compressing latency thresholds for real-time spatial applications, forcing infrastructure providers to densify compute nodes across Seoul, Busan, and Incheon metropolitan corridors.
Growth Catalysts
- 5G Standalone Architecture:Sub-meter accuracy requirements from logistics and autonomous vehicle developers are accelerating base station densification in Gyeonggi-do industrial zones.
- MFDS Healthcare Guidelines:Patient monitoring and pharmaceutical cold-chain verification mandates are expanding location tracking deployments in hospital networks and distribution centers.
- Seoul-Busan Retail Corridor:Indoor positioning investments bridging online-offline commerce are concentrating in flagship department stores and underground shopping complexes.
Market Restraints
- Geospatial Data Anonymization:The Personal Information Protection Commission's raw location monetization constraints are elevating privacy-engineering costs for analytics providers.
- KISA Certification Burden:Critical infrastructure positioning systems face mandatory security audits that extend commercialization timelines for new entrants.
- GPS Signal Attenuation:Indoor environments require Bluetooth-Wi-Fi hybrid overlays, fragmenting hardware procurement across venue-specific deployments.
Strategic Opportunities
- Gwangju-Daejeon Logistics Belt:Underpenetrated warehousing corridors between the Honam and Chungcheong regions present whitespace for asset tracking expansion.
- Super-App Convergence:Integration of ride-hailing, delivery, and payment location intelligence is creating unified spatial data platforms for consumer services.
- Urban Planning Analytics:Footfall heat-mapping and dwell-time analysis demand from municipal governments is opening public-sector procurement channels.
Industry Challenges
- Sensor Fusion Expertise Gap:Shortage of engineers proficient in radio frequency, inertial measurement, and computer vision integration is constraining product development cycles.
- Legacy Fleet Integration:Retrofitting existing logistics vehicles with positioning hardware requires custom middleware development for heterogeneous telematics systems.
- Cross-Platform Standardization:Proprietary indoor mapping formats from competing venue operators are fragmenting data interoperability for third-party application developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Location-Based Services Market |
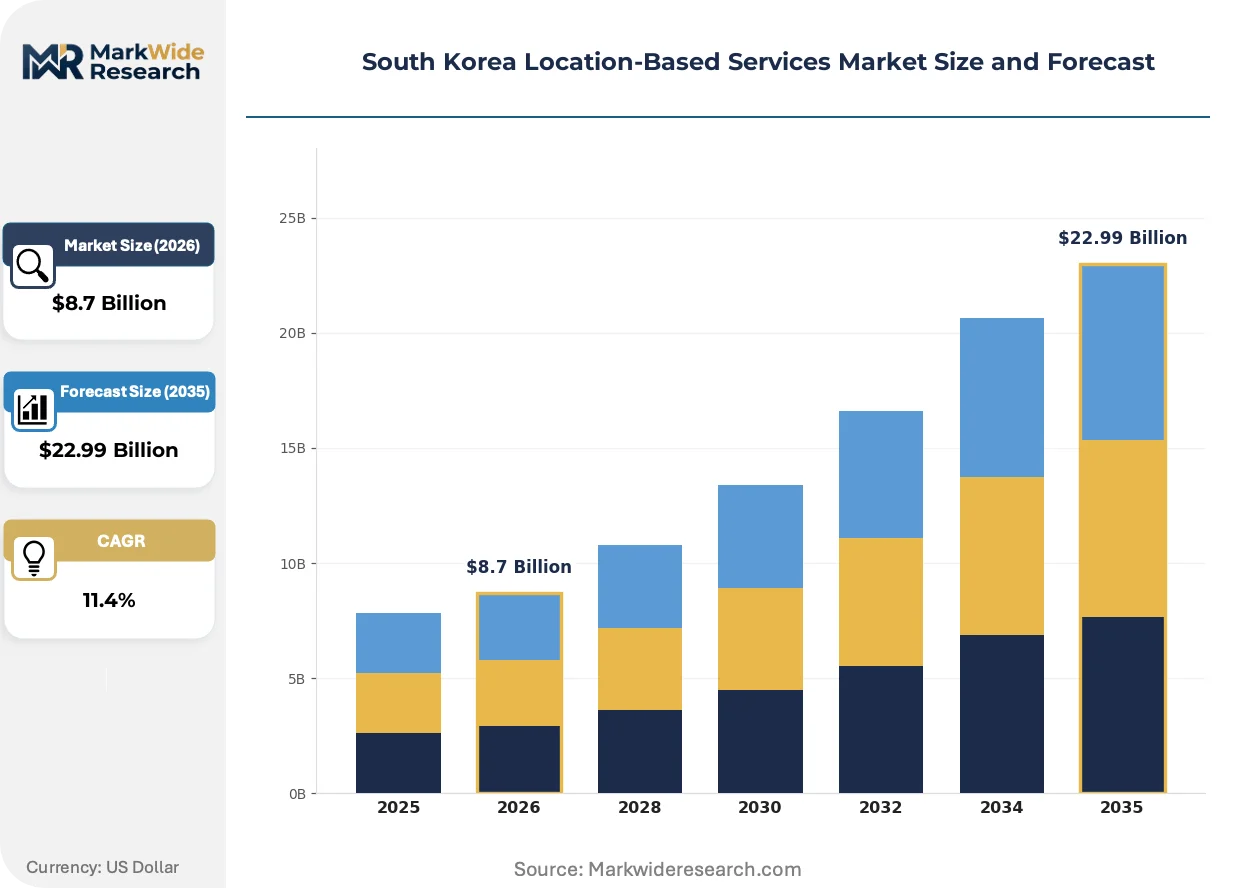
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation, Tracking, Mapping, Location Analytics Technology: GPS, Bluetooth, Wi-Fi, Cellular End User: Retailers, Transportation, Hospitality, Healthcare Application: Advertising, Fleet Management, Emergency Services, Friend Locator |
| Companies Covered | LG Uplus, Tmap Mobility, Naver, Daum Communications, Korea Telecom, Kakao, Samsung, Coupang, SK Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Location-Based Services Market Trends and Innovations
Spatial computing architectures are fragmenting into specialized layers, with distinct technology stacks emerging for consumer navigation, enterprise asset tracking, and regulatory-compliant healthcare monitoring.
Ultra-wideband chipsets are modularizing indoor positioning infrastructure. High-precision asset tracking deployments in semiconductor fabrication facilities and pharmaceutical warehouses are adopting UWB anchor networks at accelerating rates. This technology is modularizing hardware procurement decisions, separating precision-grade infrastructure from commodity Bluetooth alternatives.
The Personal Information Protection Act amendments are tightening geospatial data consent requirements. Industrial consequence includes mandatory anonymization pipelines that degrade raw coordinate utility for advertising applications. Retail analytics providers are responding by pivoting toward aggregated pattern recognition and differential privacy techniques.
Buyer procurement for location intelligence is compressing toward integrated platform subscriptions. Discrete point solutions for mapping, routing, and analytics are consolidating under single-vendor contracts in transportation and logistics segments. This concentration is most visible in the Seoul-Incheon corridor, where third-party logistics operators are standardizing on unified spatial data stacks.
South Korea Location-Based Services Market Segmentation
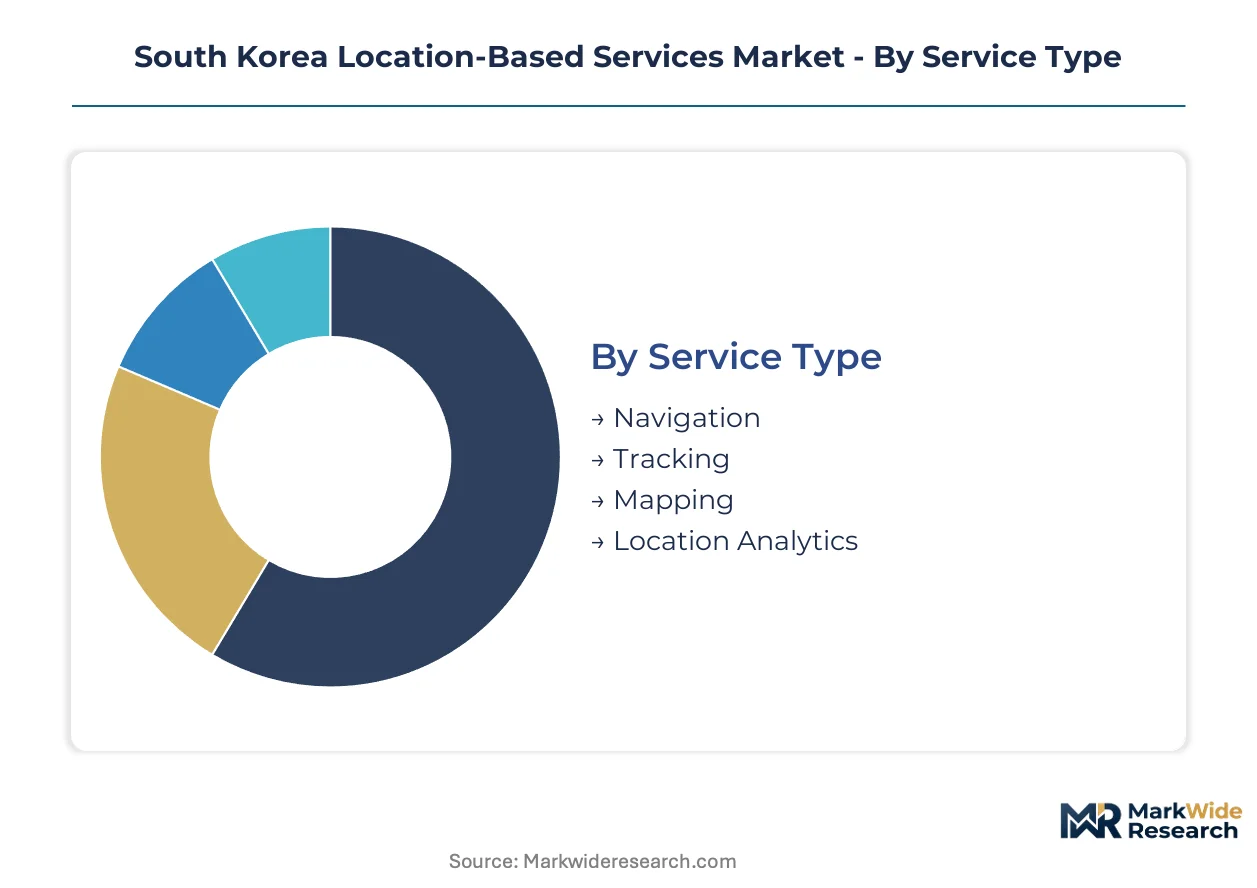
Segmentation in the South Korean market reflects distinct integration architectures. Some services operate as standalone consumer applications while others embed deeply into enterprise operational systems. Understanding this layering exposes where procurement budgets concentrate and where vendor competition intensifies.
Service Type:
Navigation and mapping services function as standalone consumer platforms, whereas tracking and location analytics embed into enterprise backend infrastructure with deeper system integration requirements.
- Navigation:Satellite and radio-frequency positioning systems deliver turn-by-turn routing for consumer mobility and commercial logistics. Demand clusters in the Seoul metropolitan corridor where congestion pricing and real-time traffic optimization drive subscription renewals. SK Telecom's sub-meter 5G positioning elevates accuracy expectations for enterprise fleet contracts.
- Location Analytics:Footfall heat-mapping and dwell-time computation platforms process aggregated spatial signals for retail and municipal planning. Busan department stores and Seoul underground shopping complexes deploy these systems to bridge online-offline commerce attribution. The Personal Information Protection Act's anonymization mandates force differential privacy investments that elevate platform engineering costs.
- Tracking:Real-time asset and vehicle monitoring systems serve logistics operators across the Incheon-Gyeonggi-do industrial belt.
- Mapping:Base cartographic data layers power consumer super-apps and enterprise geographic information systems.
Volume placements concentrate in Navigation; the faster expansion belongs to Location Analytics.
Technology:
Technology selection hinges on environmental signal availability, with outdoor and indoor deployments requiring fundamentally different hardware architectures and procurement approaches.
- GPS:Satellite-based positioning achieves 1-15 meter accuracy in open-sky conditions but attenuates severely in urban canyons and indoor structures. Seoul's dense high-rise districts and underground transit networks limit standalone GPS utility, forcing hybrid system procurement.
- Bluetooth:Low-energy beacon networks enable sub-meter indoor positioning for retail proximity marketing and asset tracking. Pharmaceutical warehouses and semiconductor fabrication facilities in Gyeonggi-do deploy Bluetooth-Wi-Fi hybrid overlays where GPS signals fail.
- Wi-Fi:Fingerprinting and trilateration methods leverage existing infrastructure for indoor positioning without dedicated hardware deployment.
- Cellular:5G standalone architecture delivers sub-meter accuracy through network-based positioning for enterprise clients requiring wide-area coverage.
Cellular networks capture the largest infrastructure investment; Bluetooth deployments are climbing the fastest as indoor positioning demand accelerates.
End User:
End-user procurement patterns diverge sharply between consumer-facing platforms and operational technology investments in regulated industries.
- Transportation:Third-party logistics operators and fleet managers across the Seoul-Incheon corridor procure unified spatial data stacks for route optimization and asset monitoring. 5G standalone positioning contracts with domestic telecom providers dominate procurement budgets.
- Healthcare:Hospital networks deploy patient monitoring and pharmaceutical cold-chain verification systems under MFDS guideline compliance. Location tracking infrastructure must satisfy both clinical accuracy requirements and the Personal Information Protection Commission's geospatial data anonymization standards.
- Retailers:Department stores and shopping complexes invest in indoor positioning to unify online-offline customer journeys.
- Hospitality:Hotels and tourism operators leverage proximity services for guest experience personalization and operational efficiency.
Transportation commands the deepest platform investments; Healthcare shows the steepest expansion trajectory as regulatory mandates proliferate.
Application:
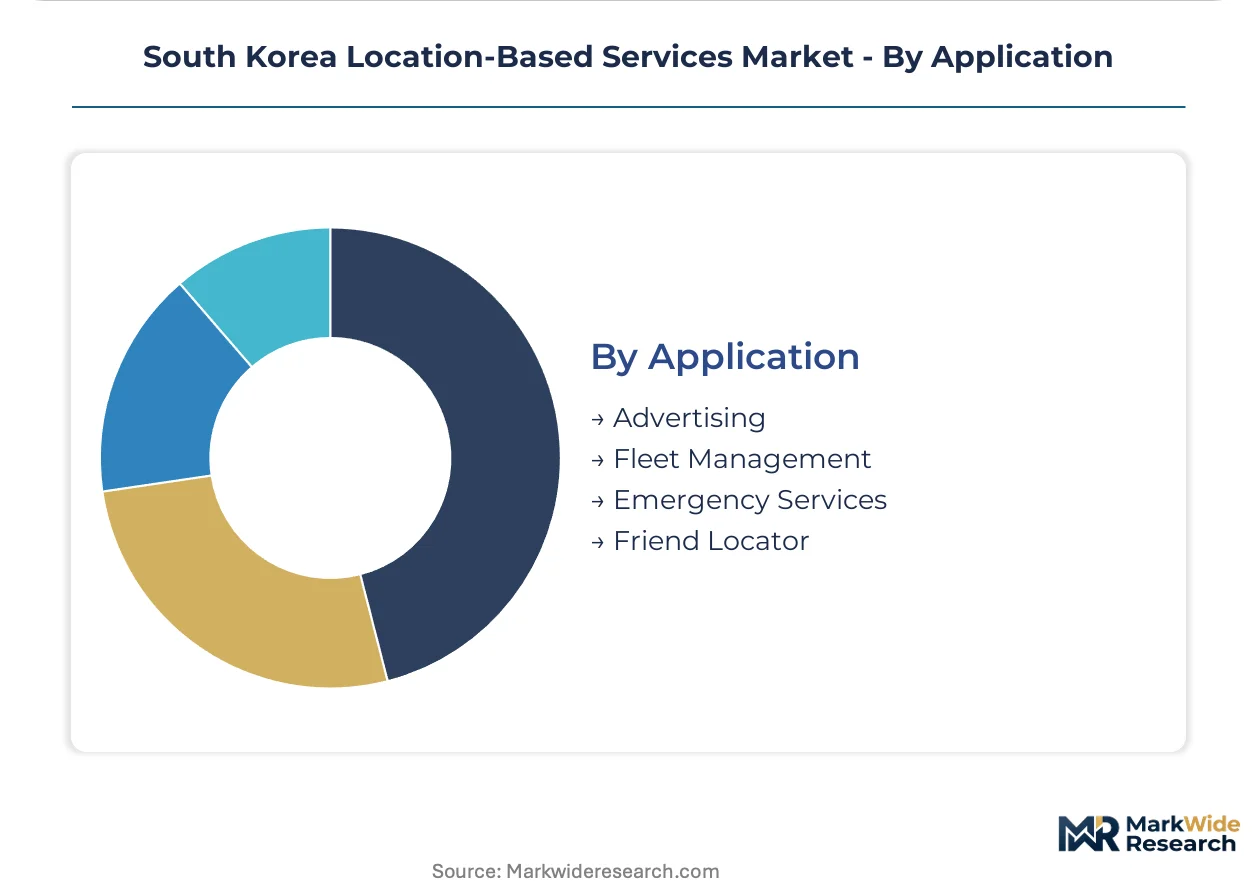
Application segmentation reveals diverging margin structures between advertising-dependent consumer services and operational efficiency tools with direct ROI measurement.
- Fleet Management:Vehicle telematics and driver behavior monitoring systems integrate positioning data with fuel consumption and maintenance scheduling. Logistics operators in the Gwangju-Daejeon warehousing corridor represent underpenetrated whitespace for asset tracking expansion.
- Emergency Services:Dispatch optimization and responder location systems require sub-second latency and high availability. KISA certification requirements for critical infrastructure positioning systems extend commercialization timelines but create vendor stickiness once deployed.
- Advertising:Proximity-triggered promotions and location-based audience targeting face raw location monetization constraints under amended privacy regulations.
- Friend Locator:Social coordination features embed in domestic super-app ecosystems as secondary utility functions.
Fleet Management absorbs the majority of enterprise software spending; Emergency Services infrastructure is gaining share fastest as municipal procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in Gyeonggi-do anchor South Korea's positioning infrastructure demand. Dense metropolitan corridors concentrate procurement budgets for sub-meter accuracy networks.
Seoul Capital Area
Third-party logistics operators deploy unified spatial data stacks across the Seoul-Incheon corridor for fleet optimization. The Personal Information Protection Commission enforces geospatial data anonymization standards that elevate privacy-engineering investments. Congestion pricing and real-time traffic management drive subscription renewals for navigation services in high-rise districts where GPS signals attenuate.
Busan-Ulsan
Flagship department stores and underground shopping complexes invest in Bluetooth-Wi-Fi hybrid positioning to bridge online-offline commerce. MFDS guidelines intersect with pharmaceutical cold-chain verification for distribution centers. The southeastern manufacturing belt generates demand for asset tracking in semiconductor and automotive component supply chains.
Daegu-Gyeongbuk
Healthcare networks deploy patient monitoring systems under tightening consent requirements from Personal Information Protection Act amendments. KISA certification mandates for critical infrastructure extend commercialization timelines for emergency dispatch positioning. The region's hospital procurement channels favor vendors with differential privacy capabilities.
Daejeon-Sejong
Public-sector urban planning analytics create procurement opportunities for footfall heat-mapping and dwell-time platforms. Government data localization policies shape vendor selection for municipal spatial intelligence contracts. The administrative city concentration accelerates standardization on integrated platform subscriptions over discrete point solutions.
Gwangju-Honam
Underpenetrated warehousing corridors present whitespace for logistics asset tracking expansion between Honam and Chungcheong regions. Agricultural cold-chain monitoring generates emerging demand for location verification outside metropolitan infrastructure zones. Regional development incentives are attracting edge-computing node investments for wide-area coverage.
South Korea Location-Based Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue healthcare compliance and indoor positioning specializations. The vendor base organizes around three archetypes: telecom infrastructure providers with 5G standalone positioning capabilities, super-app platforms integrating location intelligence across consumer services, and specialized analytics firms serving retail and municipal planning segments. Consolidation pressure intensifies as buyer procurement compresses toward unified platform subscriptions. Competitive moves center on strategic partnerships for sensor fusion expertise and geographic expansion into underpenetrated logistics corridors.
Within the telecom infrastructure tier, SK Telecom and Korea Telecom exemplify network-based positioning providers leveraging base station densification for enterprise sub-meter accuracy contracts. LG Uplus occupies a position emphasizing edge-computing-enabled architectures. Among super-app platforms, Naver and Kakao anchor consumer mapping dominance through deep ecosystem integration across ride-hailing, delivery, and payment services. These archetypes represent divergent strategic postures: infrastructure-heavy capex deployment versus software-layer user aggregation.
| Leading Market Players |
|---|
| LG Uplus |
| Tmap Mobility |
| Naver |
| Daum Communications |
| Korea Telecom |
| Kakao |
| Samsung |
| Coupang |
| SK Telecom |
| Others |
Pricing and Supply Chain Analysis
Captive integration into 5G infrastructure deployment anchors both supply positioning and pricing power for South Korean location-based services vendors, as SK Telecom and Korea Telecom leverage proprietary base station densification to command premium enterprise contracts while constraining new entrant hardware procurement options.
Pricing Analysis
Warranty and service bundling separates premium-tier positioning contracts from unbundled commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by KISA certification grade and after-sales technical support depth. Cost compression in standard-tier Bluetooth beacon deployments is intensifying because of commoditized hardware from Chinese suppliers. Third-party logistics operators in the Seoul-Incheon corridor exhibit the highest price sensitivity, while semiconductor fabrication facilities in Gyeonggi-do prioritize accuracy over cost.
Supply Chain Analysis
Regional distribution centers in Gyeonggi-do and Incheon anchor hub-and-spoke patterns for positioning hardware fulfillment. Component sourcing draws from Taiwan for UWB chipsets, China for Bluetooth modules, and domestic facilities for 5G network equipment. Single-source vulnerability concentrates in ultra-wideband semiconductor supply. Distribution runs through telecom-authorized system integrators with direct enterprise sales relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fusion engineering capacity constraints prop pricing premiums for qualified vendors, as the shortage of radio frequency and computer vision integration specialists limits scalable product development.
For Market Incumbents: Extend platform consolidation strategies to capture compressed procurement budgets across transportation and logistics segments. SK Telecom and Kakao should deepen backward integration into edge-computing node deployment to defend against emerging cloud-native positioning entrants. KISA certification investments create switching costs that protect recurring revenue streams. For New Entrants and Emerging Players: MFDS guidelines in South Korea open a window for healthcare-compliant location tracking specialization. White-space targets include pharmaceutical cold-chain verification in Busan-Ulsan distribution corridors and patient monitoring systems in Daegu-Gyeongbuk hospital networks. A direct-to-healthcare-system sales model bypasses telecom channel gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisition by domestic super-app operators seeking unified spatial data stacks. Long-term viability favors vendors with differential privacy capabilities and municipal procurement relationships. Watch for inflection when Seoul metropolitan government accelerates footfall analytics standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies mapping, routing, and analytics under single-vendor contracts for logistics operators. |
| Strategic Partnership | Combines SK Telecom's 5G positioning with Naver's consumer mapping ecosystem. |
| Acquisition of Specialist Firm | Targets indoor positioning analytics providers with retail heat-mapping capabilities. |
| Geographic Expansion | Penetrates Gwangju-Daejeon warehousing corridors for asset tracking deployment. |
| Product Launch | Introduces UWB anchor networks for semiconductor fabrication facility tracking. |
Research Methodology
SEC filings, MFDS regulatory submissions, and KISA certification databases formed the secondary backbone for this analysis. Primary interviews with telecom infrastructure planners, healthcare IT procurement managers, retail operations directors, and logistics fleet managers validated demand assumptions. Bottom-up and top-down triangulation reconciled vendor-reported positioning deployment volumes with end-user procurement survey data.
Bottom-up modeling anchored volume estimates across service type, technology, end user, and application dimensions, while top-down checks referenced telecom capex disclosures and municipal spatial intelligence budgets. CAGRs were derived from fitted growth curves against historical positioning infrastructure deployment patterns. 5G standalone network rollout schedules and Personal Information Protection Act compliance timelines served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for ultra-wideband indoor positioning would alter the outlook if Bluetooth-Wi-Fi hybrid systems achieve comparable accuracy at lower deployment cost. Forecasts reflect stated assumptions regarding regulatory enforcement intensity and edge-computing infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Location Based Advertising Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market