
 Digital Elevation Model Market | 2026-2036
Digital Elevation Model Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Elevation Model Market Analysis
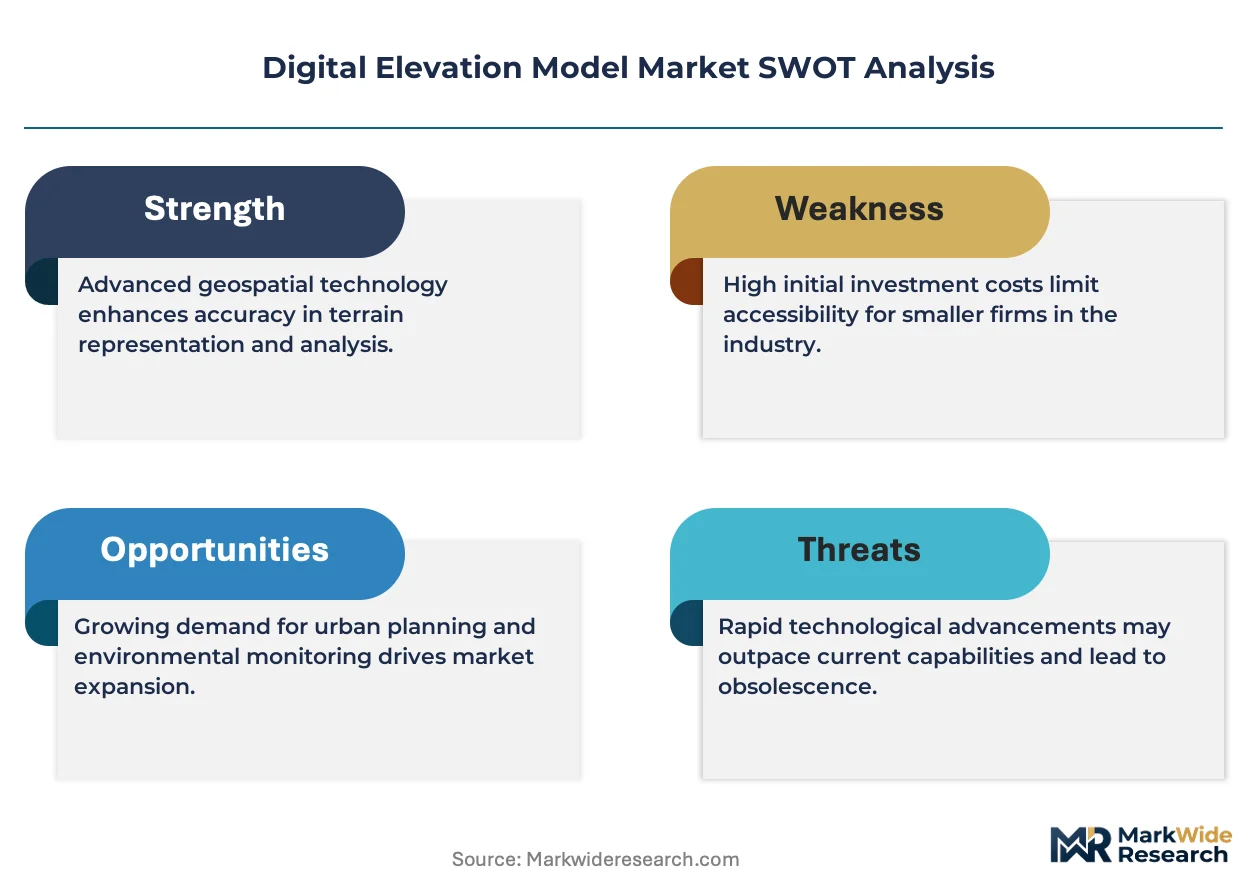
The EU Green Deal's biodiversity monitoring mandates and the CSRD disclosure requirements for natural capital accounting are expanding the addressable base for geospatial terrain data. Hexagon leverages its sensor-to-software integration to sustain premium positioning across European environmental compliance workflows. Esri dominates the GIS platform layer, while Airbus competes through sovereign satellite constellation control and direct government channel access.
A Digital Elevation Model represents a structured representation of terrain surface height above a reference datum, typically generated through interferometric synthetic aperture radar, photogrammetric stereo-pair extraction, or LiDAR point cloud gridding with vertical resolutions ranging from sub-meter to tens of meters depending on source sensor and processing level. Its primary commercial purpose spans engineering-grade topographic mapping, hydrological flow modeling, and line-of-sight analysis for infrastructure design. LiDAR-derived products command the highest accuracy tier and associated margin pools in urban planning applications, while satellite imaging sustains the broadest geographic coverage for resource exploration and environmental monitoring at lower unit economics. Government agencies represent the most contract-intensive end user category, with procurement cycles tied to national mapping agency refresh schedules and disaster preparedness appropriations.
The US Geological Survey's 3D Elevation Program and the EU's INSPIRE directive collectively shape product standards for interoperability, vertical accuracy certification, and open-data dissemination obligations that determine market access conditions for private providers. Japan's METI pushes similar standardization through JIS frameworks for disaster management applications, while India's CEA mandates DEM integration for hydropower project clearance processes. Stakeholders must monitor how sovereign data localization requirements and dual-use export controls on high-resolution terrain products reshape competitive boundaries between domestic and cross-border suppliers.
Market Dynamics
Defense procurement cycles for high-resolution terrain data are compressing as NATO member states modernize mission planning systems, while commercial satellite operators race to deliver sub-meter vertical accuracy through shorter revisit intervals.
Growth Catalysts
- FEMA flood mapping mandates:Federal infrastructure resilience programs in the United States sustain multi-year data acquisition contracts for hydrological modeling applications.
- INSPIRE directive compliance:European Union spatial data infrastructure obligations force member states to refresh national elevation datasets on accelerated timelines.
- Interferometric SAR advances:Satellite imaging technology improvements enable all-weather terrain capture that photogrammetry cannot match in cloud-persistent regions.
Market Restraints
- LiDAR sensor cost volatility:Aerial survey platforms face input pressure from specialized laser scanner components with concentrated manufacturing bases.
- Sovereign data localization:India's CEA mandates domestic processing for hydropower clearance DEMs, fragmenting cross-border service delivery.
- Photogrammetric accuracy ceilings:Stereo-pair extraction cannot achieve engineering-grade vertical precision for urban corridor design without ground control point augmentation.
Strategic Opportunities
- EU Green Deal biodiversity monitoring:Natural capital accounting disclosure requirements under CSRD expand addressable demand for terrain change detection services.
- AI-driven point cloud classification:Machine learning convergence with LiDAR gridding automates feature extraction for infrastructure asset inventories.
- Cloud-native delivery platforms:Subscription-based access models replace perpetual license sales for environmental consultancy SMEs in Germany and France.
Industry Challenges
- Geodetic datum harmonization:National mapping agencies maintain incompatible vertical reference systems that complicate cross-border project integration.
- Certified surveyor scarcity:Licensed professionals capable of validating sub-decimeter accuracy claims remain concentrated in legacy markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Elevation Model Market |
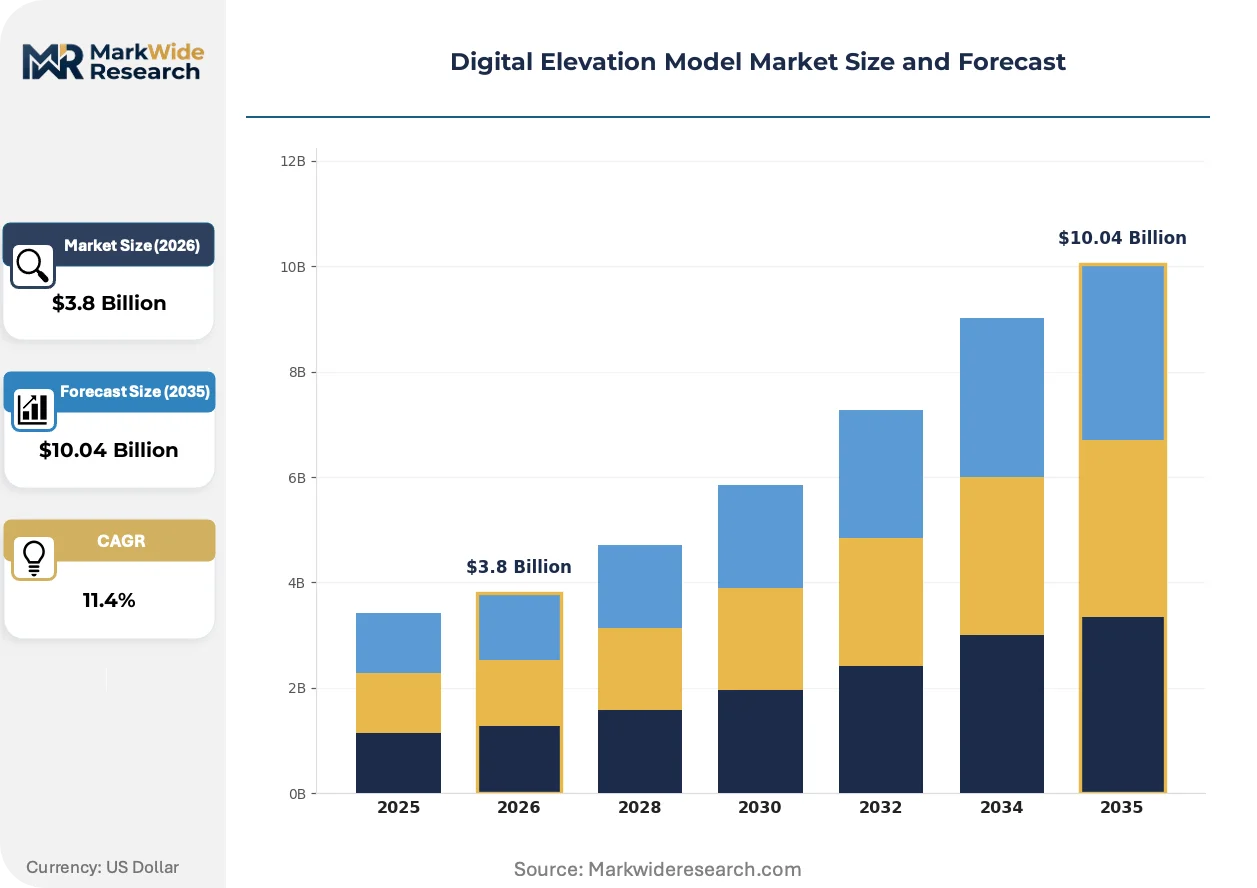
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Raster, 3D Vector, LiDAR, Contour Lines Application: Urban Planning, Disaster Management, Resource Exploration, Environmental Monitoring End User: Government Agencies, Research Institutions, Urban Developers, Environmental Consultants Technology: Remote Sensing, Photogrammetry, Satellite Imaging, GIS Software |
| Companies Covered | Intermap, Bentley Systems, LuxCarta, SAM, Esri, Airbus, Hexagon, AirWorks Solutions, Vexcel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Elevation Model Market Emerging Trajectories
Sensor-to-software integration is compressing the value chain as platform vendors capture margin pools previously held by specialized processing houses. Three developments are restructuring competitive positioning.
Multi-sensor fusion architectures are unifying LiDAR, photogrammetric, and radar inputs into single elevation products that adapt resolution to application requirements. Engineering consultancies in the Netherlands and Switzerland now specify these hybrid datasets for linear infrastructure design. The technology is unifying procurement categories that buyers previously sourced through separate contracts.
Japan's METI has mandated JIS-compliant elevation standards for all disaster management applications, forcing domestic suppliers to recertify legacy datasets. Municipal governments in Tokyo and Osaka face compliance deadlines that accelerate replacement cycles. Hydropower developers must now submit METI-validated terrain models for regulatory clearance.
Public-sector open-data programs in the United States and United Kingdom are disintermediating traditional value-added resellers. Commercial buyers now access USGS 3DEP products directly, compressing the addressable market for basic elevation derivatives. Environmental consultancies in California and Texas have built in-house processing capabilities that bypass third-party providers entirely.
Digital Elevation Model Market Segmentation
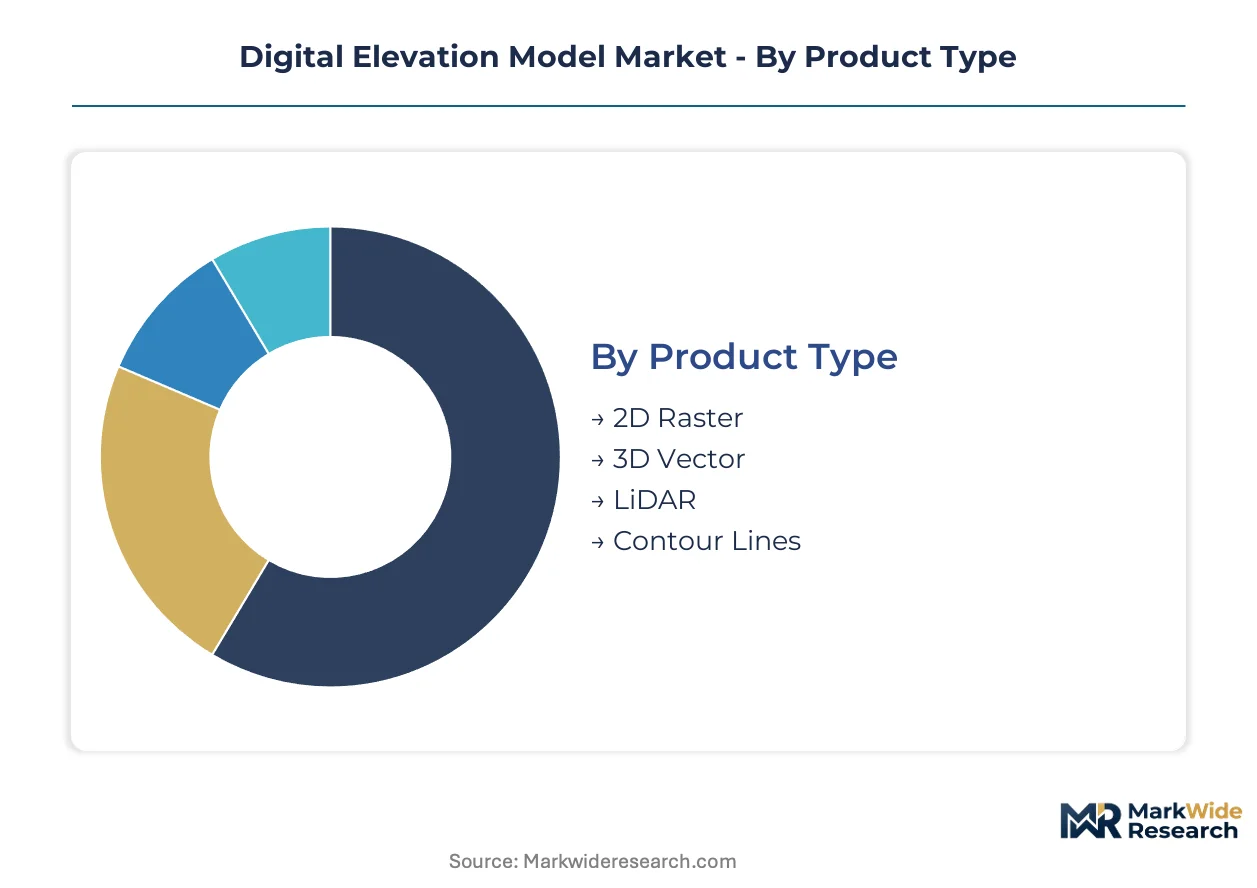
Digital Elevation Model procurement patterns diverge sharply between high-accuracy engineering applications and broad-coverage environmental monitoring. Product format, delivery technology, and end-user technical sophistication together determine contract value and renewal cadence.
Product Type:
Volume concentrates in legacy raster formats, while premium margins attach to vector and LiDAR deliverables.
- 2D Raster:Gridded elevation matrices with uniform cell spacing dominate hydrological modeling and regional climate simulations. USGS 3DEP distributes these through open-data portals, compressing commercial pricing for basic derivatives. Mature deployment sits with 2D Raster. Newer deployment is concentrated in LiDAR.
- 3D Vector:Triangulated irregular networks and point-based representations enable precise surface interpolation for engineering-grade corridor design. Dutch and Swiss infrastructure consultancies specify these for rail alignment projects requiring sub-decimeter vertical accuracy.
- LiDAR:Laser-scanned point clouds command the highest accuracy tier. FEMA flood mapping mandates sustain multi-year aerial acquisition contracts across coastal US states.
- Contour Lines:Legacy topographic map derivatives persist in military mission planning systems and recreational navigation applications with minimal refresh requirements.
Procurement bifurcates between agencies refreshing national datasets and project-specific engineering contracts demanding certified accuracy.
Application:
Regulatory compliance timelines determine refresh velocity across use cases.
- Urban Planning:Municipal zoning authorities in Germany and France require high-resolution terrain data for stormwater management and building height restriction enforcement. EU Green Deal biodiversity mandates are expanding addressable demand.
- Disaster Management:Japan's METI enforces JIS-compliant elevation standards for tsunami inundation mapping, forcing municipal recertification cycles in Tokyo and Osaka.
- Resource Exploration:Mining operators in Australia and Canada commission satellite-derived DEMs for pit optimization and haul road design at lower unit economics than aerial survey alternatives.
- Environmental Monitoring:CSRD disclosure requirements for natural capital accounting are climbing the fastest, driving terrain change detection subscriptions among European environmental consultancies.
Defense and emergency response applications sustain premium pricing. Commercial resource extraction operates on compressed margins.
End User:
Contract intensity varies with procurement authority and technical staffing depth.
- Government Agencies:National mapping authorities in the United States, United Kingdom, and Japan maintain scheduled refresh programs tied to appropriations cycles. INSPIRE directive compliance forces accelerated European timelines.
- Research Institutions:Academic geoscience departments access public-sector open data, bypassing commercial providers for baseline elevation products.
- Urban Developers:Real estate investment trusts and infrastructure funds commission project-specific LiDAR surveys for site feasibility analysis.
- Environmental Consultants:German and French SMEs are shifting toward cloud-native subscription platforms, displacing perpetual license procurement.
Direct government contracting retains the longest payment cycles. Environmental consultancies represent the fastest customer acquisition opportunity.
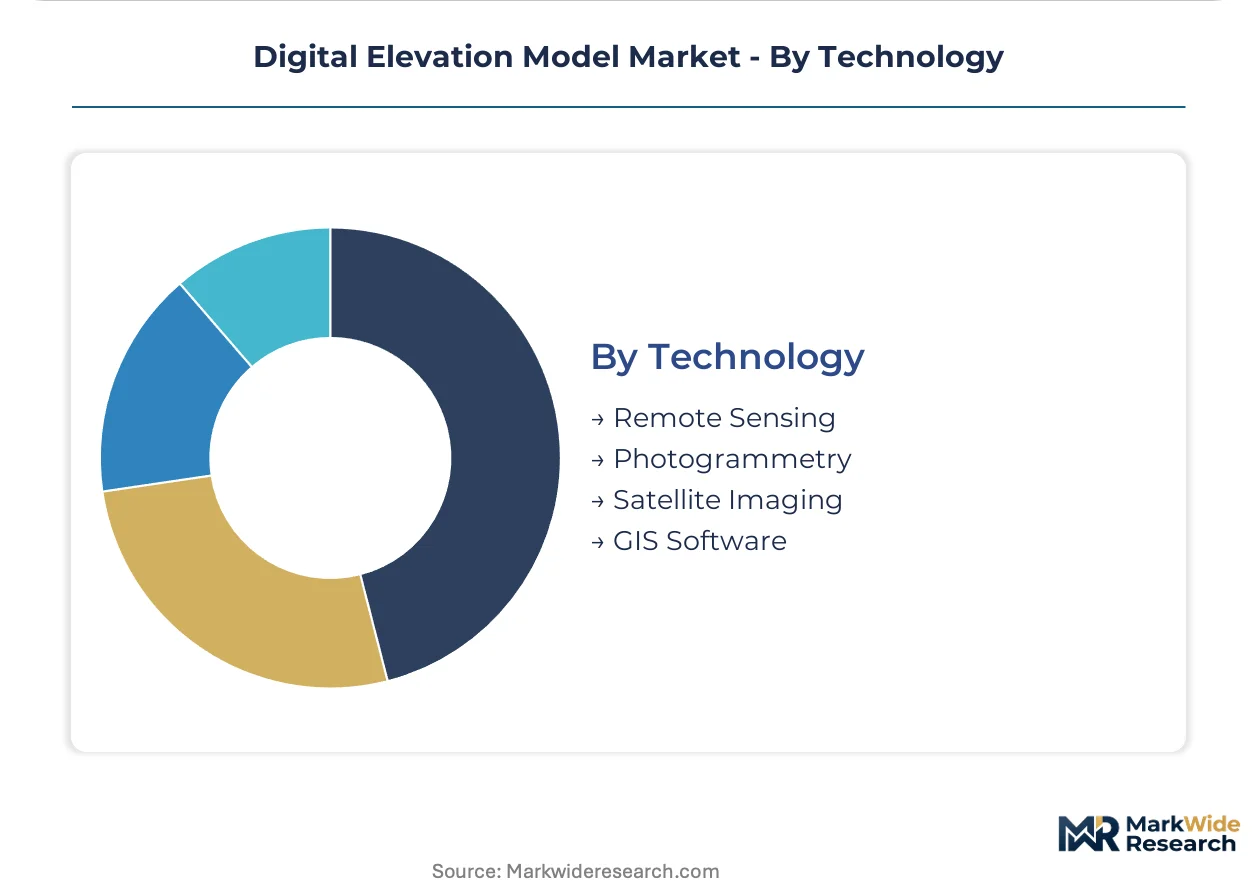
Technology:
Sensor-to-software integration is compressing the value chain as platform vendors capture processing margins.
- Remote Sensing:Interferometric SAR enables all-weather terrain capture in cloud-persistent tropical regions where photogrammetry fails.
- Photogrammetry:Stereo-pair extraction from aerial imagery cannot achieve engineering-grade precision without ground control point augmentation.
- Satellite Imaging:Airbus and Vexcel are compressing revisit intervals while improving vertical accuracy thresholds.
- GIS Software:Esri's platform layer dominates enterprise deployment, though open-source alternatives gain traction among research users.
Proprietary platform integration locks in government users. Open-source tools expand access among undercapitalized research programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. anchors federal geospatial procurement through USGS 3DEP program offices, while Denver and St. Louis house the operational centers executing national elevation data acquisition contracts.
United States
FEMA flood mapping mandates and USGS 3DEP modernization sustain multi-year aerial LiDAR contracts across coastal states. The FAA regulates commercial drone operations for terrain survey missions under Part 107 waivers. Engineering consultancies in Houston and Miami commission high-accuracy DEMs for storm surge modeling and infrastructure resilience planning.
Germany
EU Green Deal biodiversity monitoring and CSRD natural capital disclosure requirements expand demand for terrain change detection services. The country's federal cartography office enforces INSPIRE directive compliance deadlines for national elevation dataset refreshes. Environmental consultancies in Munich and Stuttgart are migrating toward cloud-native subscription platforms for hydrological modeling workflows.
Japan
METI-mandated JIS-compliant elevation standards for disaster management accelerate municipal recertification cycles in tsunami-prone zones. The regulator enforces strict vertical accuracy certification for all terrain models submitted with hydropower project clearances. Tokyo and Osaka municipal governments face compressed timelines for updating legacy elevation databases.
India
CEA mandates domestic processing for hydropower clearance DEMs, fragmenting cross-border service delivery and creating captive demand for local survey providers. The Central Electricity Authority regulates terrain data localization requirements for infrastructure project approvals. Survey operations concentrate in Himalayan states where run-of-river hydropower development drives repeat acquisition contracts.
Australia
Mining operators in Western Australia and Queensland commission satellite-derived DEMs for pit optimization and haul road design at scale-driven unit economics. Geoscience Australia maintains national elevation coverage programs that compete with commercial providers for basic derivatives. Perth-based resource consultancies integrate terrain data into automated mine planning systems.
Digital Elevation Model Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the accuracy-certification dimension, with LiDAR-derived products commanding engineering-grade pricing while satellite imaging sustains broad-coverage environmental monitoring at compressed economics. The vendor base stratifies into three tiers: sensor-integrated platform vendors capturing processing margins, specialized aerial survey operators serving project-specific contracts, and open-data aggregators disintermediating basic elevation derivatives. Dominant competitive moves include sensor-to-software integration compressing value chain positions and cloud-native delivery platforms displacing perpetual license sales among SME consultancies.
Among North American geospatial technology providers, Esri and Bentley Systems exemplify platform-layer dominance through enterprise GIS deployment, while Intermap represents the specialized terrain data operator archetype serving defense and infrastructure verticals. European competitors occupy distinct positioning: Hexagon anchors the sensor-integrated tier through its measurement technology heritage, and Airbus exemplifies sovereign satellite constellation control enabling direct government channel access. Vexcel occupies a position bridging aerial imaging acquisition and software processing workflows.
| Leading Market Players |
|---|
| Intermap |
| Bentley Systems |
| LuxCarta |
| SAM |
| Esri |
| Airbus |
| Hexagon |
| AirWorks Solutions |
| Vexcel |
| Others |
Supply Flow & Price Mechanics
Laser scanner component indices from German and Swiss precision optics manufacturers cascade through aerial survey operator cost structures, compressing margins at the high-accuracy tier while satellite imaging providers capture scale advantages through shorter revisit cycles.
Pricing Analysis
Certified vertical accuracy thresholds anchor value-based pricing, with sub-decimeter LiDAR products commanding project-based contracts tied to engineering outcomes while satellite-derived rasters sell through subscription tiers. Price differentiation separates FEMA-mandated flood mapping procurements from open-data USGS 3DEP derivatives. Cost compression in basic raster tiers is intensifying because public-sector open-data programs disintermediate value-added resellers. Environmental consultancies show highest price sensitivity; defense agencies demonstrate lowest sensitivity due to mission-critical requirements.
Supply Chain Analysis
Photogrammetric camera assemblies rest on Japanese and German precision manufacturing clusters, while interferometric SAR sensor production concentrates in France and Germany. Specialized laser scanner components, aerial platform airframes, and geodetic ground control equipment constitute critical input dependencies. Single-source vulnerability in LiDAR sensor supply creates procurement risk for aerial survey operators. Distribution runs through direct government contracting channels and cloud-native platform subscriptions for SME environmental consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-to-software integration is forcing consolidation as specialized processing houses lose margin share to platform vendors with captive sensor fleets.
For Market Incumbents: Lock in government channel access through INSPIRE directive certification investments and JIS-compliant elevation standard recertification programs. Deepen upstream control over aerial platform fleets to defend against satellite imaging substitution in broad-coverage applications. For New Entrants and Emerging Players: Begin with cloud-native subscription platforms targeting German and French environmental consultancy SMEs displaced from perpetual license models. Hydrological modeling workflows for EU Green Deal biodiversity monitoring represent the most penetrable white-space segment. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized aerial survey operators with FEMA contract backlogs in US coastal states. Long-term viability hinges on sovereign data localization mandates expanding captive demand. Watch for CEA-style domestic processing requirements spreading to additional Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Software Integration | Hexagon and Esri capture processing margins previously held by independent vendors. |
| Cloud-Native Platform Launch | Subscription models displace perpetual licenses among German environmental consultancies. |
| Sovereign Constellation Control | Airbus leverages direct government channel access for defense procurement cycles. |
| AI-Driven Point Cloud Classification | Machine learning automates feature extraction for infrastructure asset inventories. |
| Multi-Sensor Fusion Architecture | Dutch engineering consultancies specify hybrid datasets for linear infrastructure design. |
Methodological Framework
National mapping agency procurement databases, USGS 3DEP program disclosures, and EU INSPIRE directive compliance filings formed the secondary backbone. Primary interviews with aerial survey operations managers, GIS platform procurement officers at engineering consultancies, defense geospatial intelligence leads, and environmental consultancy technical directors combined with secondary validation. Bottom-up and top-down triangulation anchored market sizing.
Bottom-up modeling tracked product type, application, end user, and technology dimensions across the projection horizon. CAGRs derived from segment-level growth trajectories weighted by contract value concentration. Forecast inputs included national mapping agency refresh schedules, FEMA appropriations cycles, and satellite imaging revisit interval improvements.
Underlying measurement precision varies by segment; LiDAR-derived products carry tighter precision than satellite imaging derivatives. Forecasts reflect assumptions about defense procurement acceleration and CSRD disclosure timeline adoption. Regulatory shifts in sovereign data localization and dual-use export controls warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market