
 Artificial Intelligence of Things (Aiot) Market | 2026-2036
Artificial Intelligence of Things (Aiot) Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence of Things (Aiot) Market Outlook
Cloud-to-edge distribution channels are rewriting how AIoT solutions reach industrial buyers. Microsoft leverages its Azure IoT stack to anchor enterprise deployments across manufacturing verticals. IBM Corporation competes through Watson IoT specialization in predictive maintenance workflows. Intel sustains silicon-level dominance at the edge with its neural compute architectures.
Artificial Intelligence of Things denotes networked physical devices that execute machine learning inference locally or stream telemetry to cloud AI engines for real-time decisioning, typically operating at sub-100 millisecond latency thresholds for closed-loop control. Its primary purpose spans predictive asset maintenance, autonomous process optimization, and contextual automation across operational environments. Smart Sensors and Industrial Equipment capture the dominant margin pools in product type segmentation, while Edge Computing outpaces Cloud AI in technology growth velocity due to bandwidth constraints and sovereignty requirements. Smart Cities applications lag Smart Home and Industrial Automation in monetization maturity but represent the largest untapped deployment base.
The EU AI Act classifies high-risk AIoT systems in healthcare and transport, compelling conformity assessments that reshape vendor go-to-market costs. China's SAMR enforces GB standards for connected device data handling, creating divergent certification paths for multinational suppliers. FDA scrutiny of AI-enabled diagnostic wearables tightens clinical validation requirements in the US healthcare segment. Stakeholders must calibrate regulatory compliance investments against regional revenue concentration before committing to platform standardization.
Market Dynamics
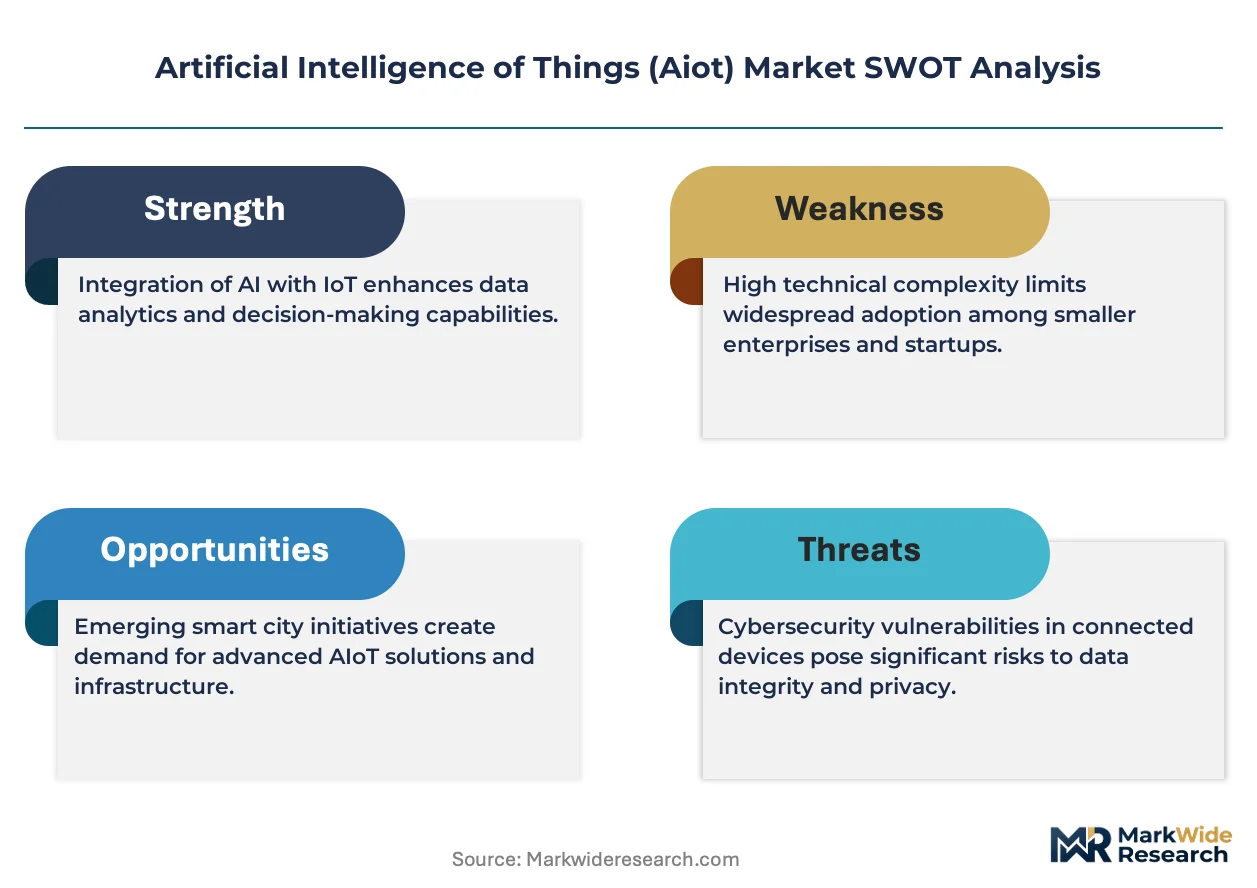
The Artificial Intelligence of Things market is undergoing a fundamental restructuring as edge computing architectures displace centralized cloud inference for latency-sensitive industrial workloads, forcing vendors to rebuild software stacks for distributed deployment.
Growth Catalysts
- EU AI Act compliance mandates:High-risk system classifications in manufacturing and healthcare are compelling enterprises to upgrade legacy monitoring infrastructure with certified AIoT platforms that satisfy conformity assessment requirements.
- Smart manufacturing adoption:Automotive and electronics producers across Germany's industrial corridor are deploying predictive maintenance networks to minimize unplanned downtime in capital-intensive assembly operations.
- Neural compute silicon advancement:Purpose-built inference accelerators are enabling sub-50 millisecond decision loops for robotic control systems that previously required human-in-the-loop oversight.
Market Restraints
- GB standards fragmentation:China's SAMR enforcement of divergent data handling certification paths creates duplicate engineering costs for multinational suppliers serving both Asian and European markets.
- Edge hardware cost structure:Industrial-grade AI accelerators carry 3-5x premiums over consumer silicon, compressing project ROI timelines for mid-sized manufacturing facilities.
- Specialized talent scarcity:The intersection of embedded systems engineering and machine learning operations remains severely under-supplied across all major deployment regions.
Strategic Opportunities
- Smart Cities infrastructure:Municipal governments in India's emerging urban corridors are soliciting integrated traffic-pollution-safety platforms with 10-year concession frameworks.
- Digital twin convergence:Real-time physics simulation fused with live sensor streams is opening new revenue pools in process industries previously served by static modeling software.
- US IRA manufacturing incentives:Domestic production tax credits for clean technology components are accelerating greenfield facility builds requiring comprehensive AIoT environmental monitoring.
Industry Challenges
- OT-IT integration complexity:Brownfield manufacturing sites operate decades-old SCADA architectures that resist seamless API connectivity with modern AI inference engines.
- Clinical validation timelines:FDA scrutiny of AI-enabled diagnostic wearables extends certification cycles to 18-24 months, freezing working capital in pre-revenue product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence of Things (Aiot) Market |
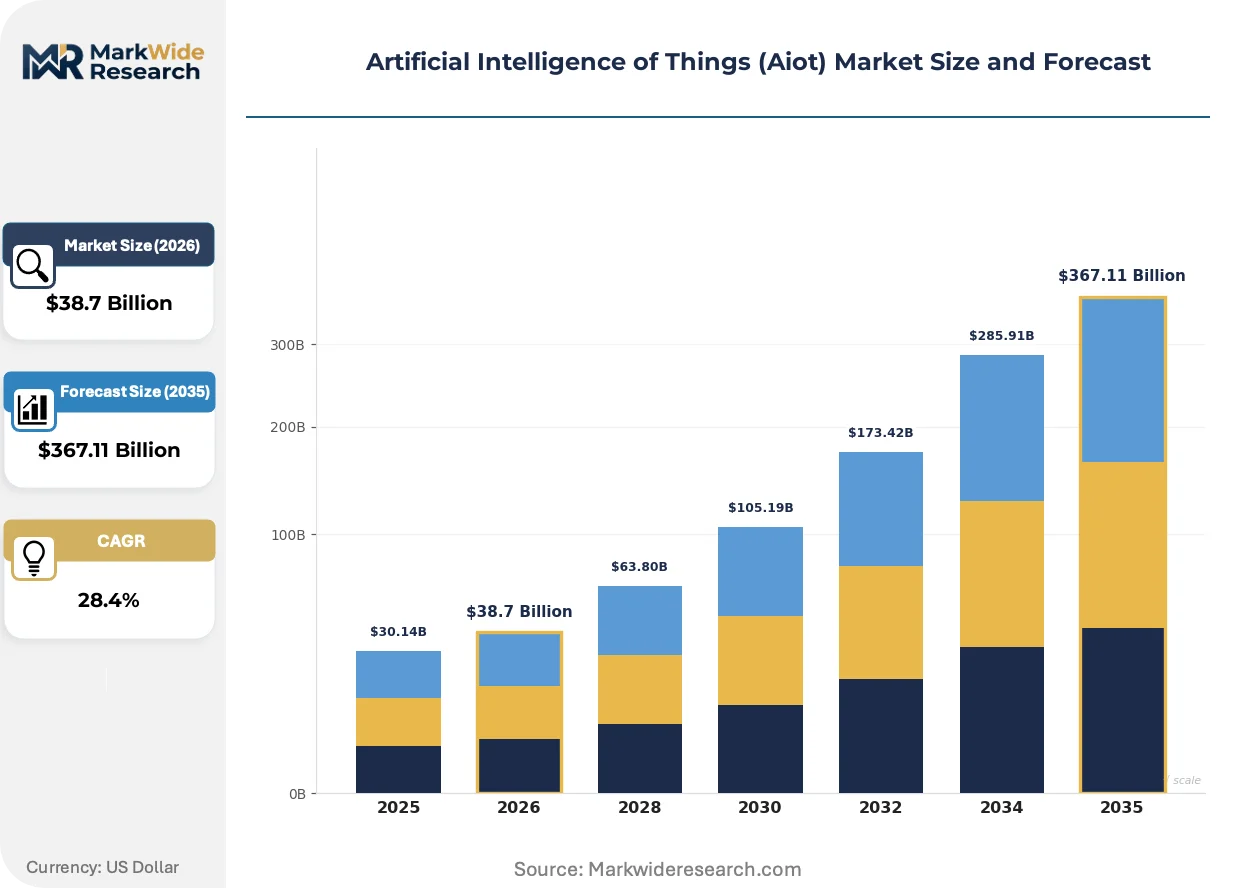
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $367.11 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Smart Appliances, Wearable Devices, Industrial Equipment Technology: Machine Learning, Edge Computing, Cloud AI, Robotics Application: Smart Home, Industrial Automation, Healthcare, Smart Cities End User: Manufacturing, Retail, Healthcare Providers, Enterprises |
| Companies Covered | Amazon Web Services, Microsoft, Google LLC, IBM Corporation, Cisco Systems, SAP SE, Oracle, Intel, AxiomTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence of Things (Aiot) Market Strategic Shifts
Federated learning architectures are redistributing where model training occurs, while regulatory pressure on algorithmic transparency is rewriting vendor disclosure obligations. These forces are compressing traditional competitive moats built on proprietary data accumulation.
On-device transformer inference is rendering obsolete the assumption that industrial AI requires continuous cloud connectivity. Automotive tier-one suppliers are qualifying neural processing units capable of running billion-parameter models in engine control modules. This shift is compressing data egress costs and enabling real-time anomaly detection in bandwidth-constrained mining and maritime environments.
The EU AI Act's high-risk system classification is forcing conformity assessment investments that favor established industrial automation vendors over software-native entrants. Medical device and autonomous transport applications face mandatory third-party auditing that extends sales cycles by 6-12 months. German industrial buyers are now requiring CE-marked AI components as a procurement precondition, effectively filtering non-compliant Asian suppliers from critical infrastructure tenders.
Buyer preference is pivoting toward outcome-guaranteed service contracts that bundle hardware, software, and predictive accuracy commitments. Industrial purchasers in the US Great Lakes automation belt are unbundling traditional CapEx equipment sales in favor of per-asset uptime pricing. This reconfiguration favors vendors with captive service networks over pure-play technology licensors lacking field engineering density.
Artificial Intelligence of Things (Aiot) Market Segmentation
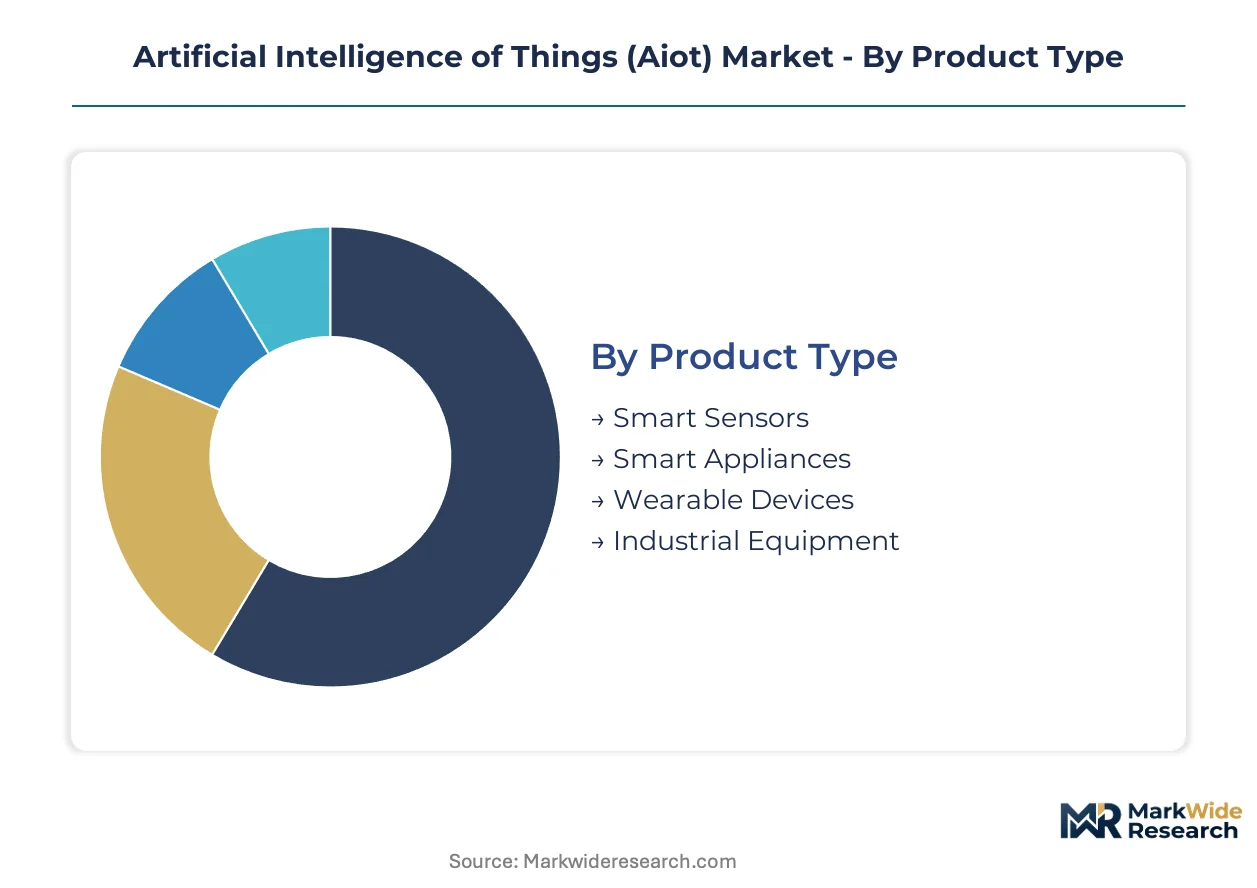
AIoT segmentation reveals divergent margin structures and service intensity requirements across hardware, software, and integration layers. Vendors must align portfolio investments with segments showing sustainable pricing power and recurring revenue potential.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with field-deployed industrial assets demanding multi-year maintenance contracts while consumer wearables rely on minimal-touch support models.
- Smart Sensors:Microelectromechanical systems with embedded inference engines capture telemetry from vibration, temperature, and acoustic signatures. Demand clusters in Germany's automotive supplier network for predictive quality monitoring, driven by EU AI Act conformity requirements for high-risk manufacturing systems.
- Industrial Equipment:Capital-intensive machinery with integrated AI controllers for autonomous process adjustment commands premium service attach rates. China's Yangtze Delta electronics assemblers are retrofitting legacy lines with certified edge nodes to satisfy SAMR GB standards for data sovereignty.
- Smart Appliances:Connected white goods with localized voice recognition and energy optimization algorithms. Korean appliance OEMs are embedding neural accelerators to reduce cloud dependency.
- Wearable Devices:Biosignal-monitoring form factors requiring FDA validation cycles for clinical-grade deployments. US healthcare systems are piloting remote patient monitoring with diagnostic-grade wristbands.
By volume, Smart Sensors leads. By growth pace, Industrial Equipment is ahead.
Technology:
Cost tier differentiation separates enterprise-grade deployments from mass-market implementations, with silicon and certification expenses creating distinct competitive arenas.
- Edge Computing:Distributed inference architectures processing data within 50 milliseconds of generation. Mining operations in Western Australia's Pilbara region are deploying ruggedized edge nodes where satellite bandwidth constraints prohibit cloud telemetry.
- Machine Learning:Statistical pattern recognition systems trained on operational datasets for anomaly detection. Japanese automotive tier-ones are qualifying on-device transformer models for engine control modules.
- Cloud AI:Centralized model training and batch inference services for non-latency-sensitive workloads. Indian smart city integrators are leveraging cloud orchestration for traffic-pollution correlation analytics.
- Robotics:Autonomous physical systems with closed-loop environmental response capabilities. German logistics hubs are deploying collaborative robots with certified safety-rated AI vision systems.
By installed base, Cloud AI dominates. By expansion trajectory, Edge Computing is climbing the fastest.
Application:
Customer maturity cycles determine sales cycle length and pilot-to-production conversion rates, with industrial buyers moving faster than municipal procurement.
- Industrial Automation:Factory-floor AI systems for predictive maintenance and quality assurance. US Great Lakes metalworking facilities are adopting per-asset uptime pricing models with guaranteed availability commitments.
- Smart Home:Residential AI ecosystems for climate, security, and entertainment orchestration. European utilities are bundling demand-response-enabled thermostats with dynamic electricity tariffs.
- Healthcare:Clinical AIoT for remote diagnostics and patient flow optimization. FDA scrutiny of AI-enabled diagnostic wearables extends certification timelines to 18-24 months.
- Smart Cities:Integrated urban infrastructure spanning traffic, pollution, and public safety. Indian municipal corporations are issuing 10-year concession frameworks for multi-sensor platforms.
By revenue concentration, Industrial Automation leads. By untapped deployment base, Smart Cities represents the largest opportunity.
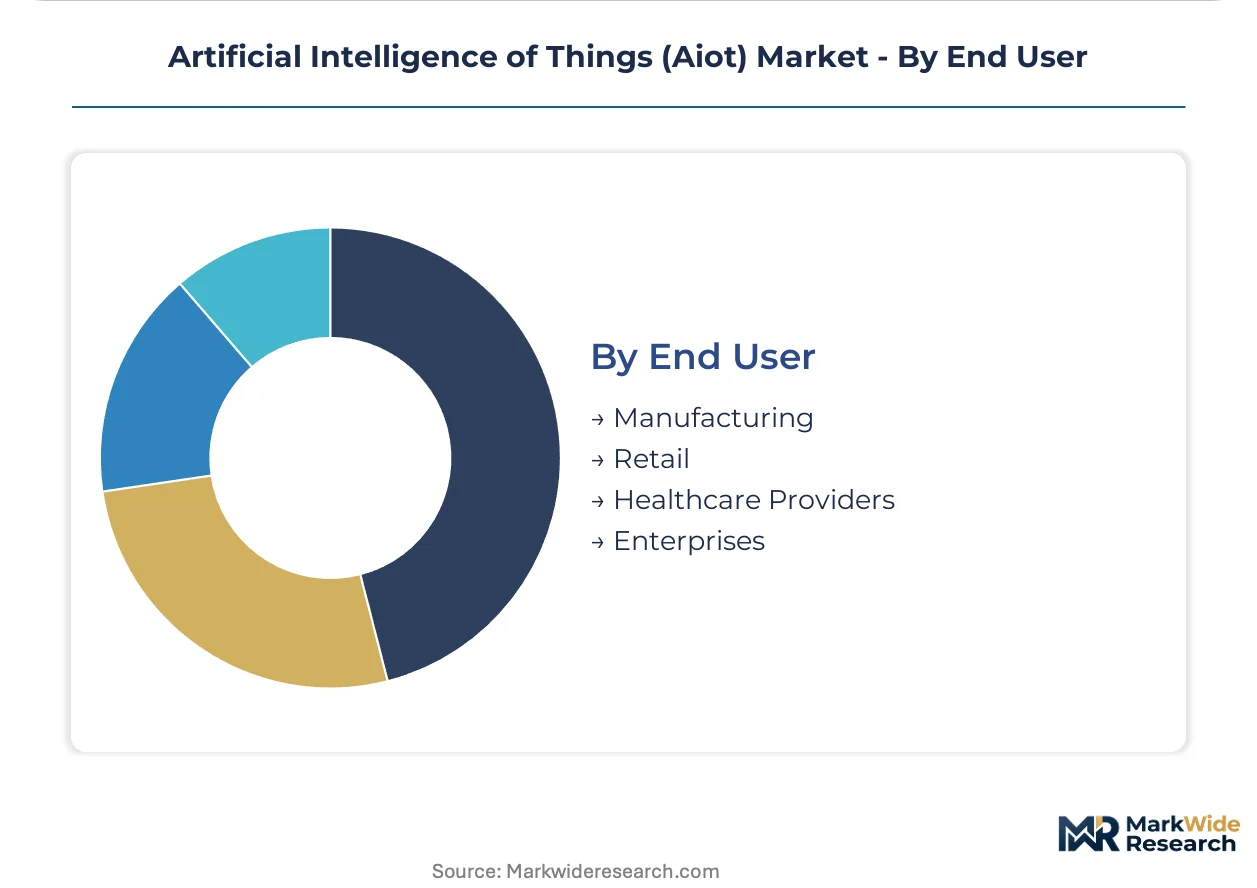
End User:
Supply concentration patterns favor vendors with vertical expertise in regulated industries over horizontal platform providers.
- Manufacturing:Asset-intensive producers deploying predictive maintenance networks. Automotive and electronics producers across Germany's industrial corridor are minimizing unplanned downtime through sensor fusion.
- Healthcare Providers:Hospital systems and clinics integrating AIoT for clinical workflow optimization. US health systems are freezing working capital in pre-revenue diagnostic wearable development.
- Enterprises:Cross-industry corporate adopters seeking facility and fleet optimization. Logistics operators are qualifying autonomous yard management systems.
- Retail:Store operators deploying inventory sensing and customer analytics. European grocers are piloting shelf-edge vision systems for automated replenishment.
By current spend, Manufacturing leads. By procurement momentum, Healthcare Providers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors regulatory gravity in Germany's industrial corridor, while SAMR's GB standards and the US IRA manufacturing incentives reshape deployment economics across three distinct governance zones.
Germany
Automotive suppliers and precision toolmakers demand CE-marked AI components for predictive quality systems. The EU AI Act mandates third-party conformity assessments for high-risk manufacturing applications. Stuttgart's supplier network retrofits legacy assembly lines with certified edge nodes to satisfy procurement preconditions.
China
Electronics assemblers in the Yangtze Delta accelerate edge computing retrofits to minimize unplanned downtime. SAMR enforces divergent data handling certification paths under GB standards for connected devices. Suzhou's semiconductor packaging hubs deploy neural accelerators to satisfy local data sovereignty requirements.
United States
Metalworking facilities across Michigan and Ohio adopt per-asset uptime pricing with guaranteed availability commitments. The IRA manufacturing incentives accelerate greenfield clean technology builds requiring comprehensive environmental monitoring. Cleveland's automation belt integrates AIoT platforms into decades-old SCADA architectures.
India
Municipal corporations in emerging urban corridors solicit integrated traffic-pollution-safety platforms with decade-long concession frameworks. The PLI scheme for electronics manufacturing attracts component suppliers building captive AIoT testing facilities. Pune's industrial corridor hosts pilot deployments for federated learning architectures in bandwidth-constrained environments.
Japan
Automotive tier-one suppliers qualify on-device transformer models for engine control modules under METI guidance. JIS standards for industrial IoT interoperability compress integration timelines for brownfield facilities. Nagoya's manufacturing cluster leads qualification of billion-parameter neural processing units for closed-loop robotic control.
Artificial Intelligence of Things (Aiot) Market Competitive Environment
Hyperscale cloud providers and industrial automation incumbents split the market along latency-sensitivity fault lines. Cloud-native platforms dominate non-time-critical workloads, while edge-specialized vendors capture sub-50 millisecond decision loops. Three archetypes define competitive positioning: hyperscale infrastructure orchestrators, silicon-level inference acceleration specialists, and vertical workflow optimization consultants. Capacity expansion in neural compute IP and strategic partnerships for OT-IT integration represent the dominant competitive vectors.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify infrastructure orchestration models that bundle edge software stacks with centralized training pipelines. IBM Corporation occupies a position bridging cloud services and industrial workflow specialization. Intel anchors the silicon-level acceleration archetype with purpose-built neural compute architectures. These three entities collectively represent the strategic poles—cloud dominance, vertical AI services, and edge hardware supremacy—that structure vendor rivalry across deployment scenarios.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Google LLC |
| IBM Corporation |
| Cisco Systems |
| SAP SE |
| Oracle |
| Intel |
| AxiomTek |
| Others |
Value Chain & Pricing Dynamics
EU AI Act conformity assessment chokepoints determine both tiered certification premiums and supplier qualification pathways, compressing margins for non-compliant vendors while concentrating procurement authority among CE-marked component specialists.
Pricing Analysis
Configured-to-order pricing for certified edge nodes commands 40-60% premiums over standard industrial sensors lacking EU AI Act documentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare wearables from commercial fitness trackers and unbranded commodity sensors. Cost compression in mid-tier industrial equipment is intensifying because Chinese suppliers are absorbing GB standards compliance costs to maintain Yangtze Delta market share. Automotive OEMs in Germany's industrial corridor show least price sensitivity due to downtime cost structures, while Indian municipal smart city buyers exhibit highest sensitivity with decade-long concession frameworks.
Supply Chain Analysis
Extended payment terms from German automotive tier-ones now stretch to 120 days, forcing Taiwanese neural accelerator foundries to utilize supply-chain finance facilities. Component sourcing draws from Taiwan for inference silicon, South Korea for advanced packaging, and China for MEMS sensor substrates. Single-source vulnerability concentrates in EU-certified edge node suppliers serving Stuttgart's supplier network. Distribution runs through hyperscale cloud marketplaces for software stacks and direct OEM contracts for industrial hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AIoT demand is recovering from a cyclical trough as manufacturing capital expenditure rebounds from pandemic-deferred automation investments.
For Market Incumbents: Build switching-cost moats through captive service networks embedding predictive maintenance algorithms directly into customer SCADA architectures. Deepen backward integration into neural compute silicon to offset Taiwanese foundry pricing power. Fortify against software-native entrants by bundling outcome-guaranteed uptime contracts that freeze working capital for pure-play competitors lacking field engineering density. For New Entrants and Emerging Players: Establish a beachhead in India's smart city infrastructure segment where 10-year concession frameworks favor agile integrators over entrenched industrial automation vendors. Target bandwidth-constrained mining and maritime environments where on-device transformer inference eliminates hyperscale cloud dependency. Lead with federated learning architectures that address data sovereignty requirements without requiring legacy OT-IT integration capabilities. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors vertical workflow specialists with certified regulatory positioning over horizontal platform providers. Long-term viability over a 5-10 year window rests on vendors capturing recurring service revenue from outcome-based contracts rather than transactional hardware sales. Watch for FDA pre-submission feedback letters as inflection indicators for diagnostic wearable market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Retrofit Deployment | Stuttgart automotive suppliers achieve EU AI Act compliance while minimizing brownfield disruption. |
| Neural Accelerator Supply Agreement | Taiwanese foundries secure multi-year offtake commitments from German industrial automation vendors. |
| Digital Twin Platform Integration | Process industry customers replace static modeling software with real-time physics simulation fused to live sensor streams. |
| Federated Learning Architecture Development | Indian smart city pilots address bandwidth constraints while satisfying local data sovereignty requirements. |
| Outcome-Based Service Contract Launch | US Great Lakes metalworking facilities shift from CapEx equipment sales to per-asset uptime pricing with guaranteed availability. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, OT-IT integration specialists, predictive maintenance directors, and semiconductor procurement leads at automotive tier-one suppliers and refined through secondary validation. Data synthesis combined regulatory filing analysis from FDA pre-submission databases and EU AI Act conformity assessment registries with hyperscaler capex disclosures and industrial automation vendor SEC filings. Bottom-up sensor shipment tallies and top-down manufacturing automation spend estimates were triangulated to anchor volume projections.
Demand-supply-balance modeling across the analysis window integrated edge computing deployment velocity, cloud AI inference cost curves, and regulatory certification timeline constraints. Segmentation dimensions included product type, technology architecture, application vertical, and end-user industry with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves adjusted for compliance-driven sales cycle extensions and federated learning adoption inflection points in bandwidth-constrained environments.
Stress conditions across EU AI Act enforcement intensity, GB standards fragmentation depth, and neural compute silicon supply availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding manufacturing capital expenditure recovery trajectories and smart city procurement pacing. Macroeconomic contraction, regulatory timeline acceleration, or on-device inference breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
US Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market