
 US Location-Based Services Market | 2026-2036
US Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Location-Based Services Market Insights
Asset-light SaaS delivery models is rewriting competitive entry dynamics for location-based platforms. Google LLC leverages its mapping data infrastructure to sustain dominance in consumer navigation layers. HERE Technologies anchors enterprise-grade fleet tracking through specialized geospatial engines. Esri competes in geographic information systems with deep analytical toolsets for government and utility clients.
Location-based services comprise spatial computing systems that determine, transmit, and act upon geographic coordinates through satellite triangulation, signal tower ranging, or proximity beacon detection, typically achieving positional accuracy within 3-10 meters under open-sky conditions. These systems enable real-time routing, geofenced automation, and proximity-triggered workflows across mobile and fixed assets. GPS technology leads in outdoor precision tracking while Bluetooth beacons capture fastest growth in indoor positioning for retail environments. Asset tracking applications command substantial enterprise spending as supply chain visibility becomes non-negotiable, whereas location analytics services concentrate margin pools through subscription-based intelligence platforms.
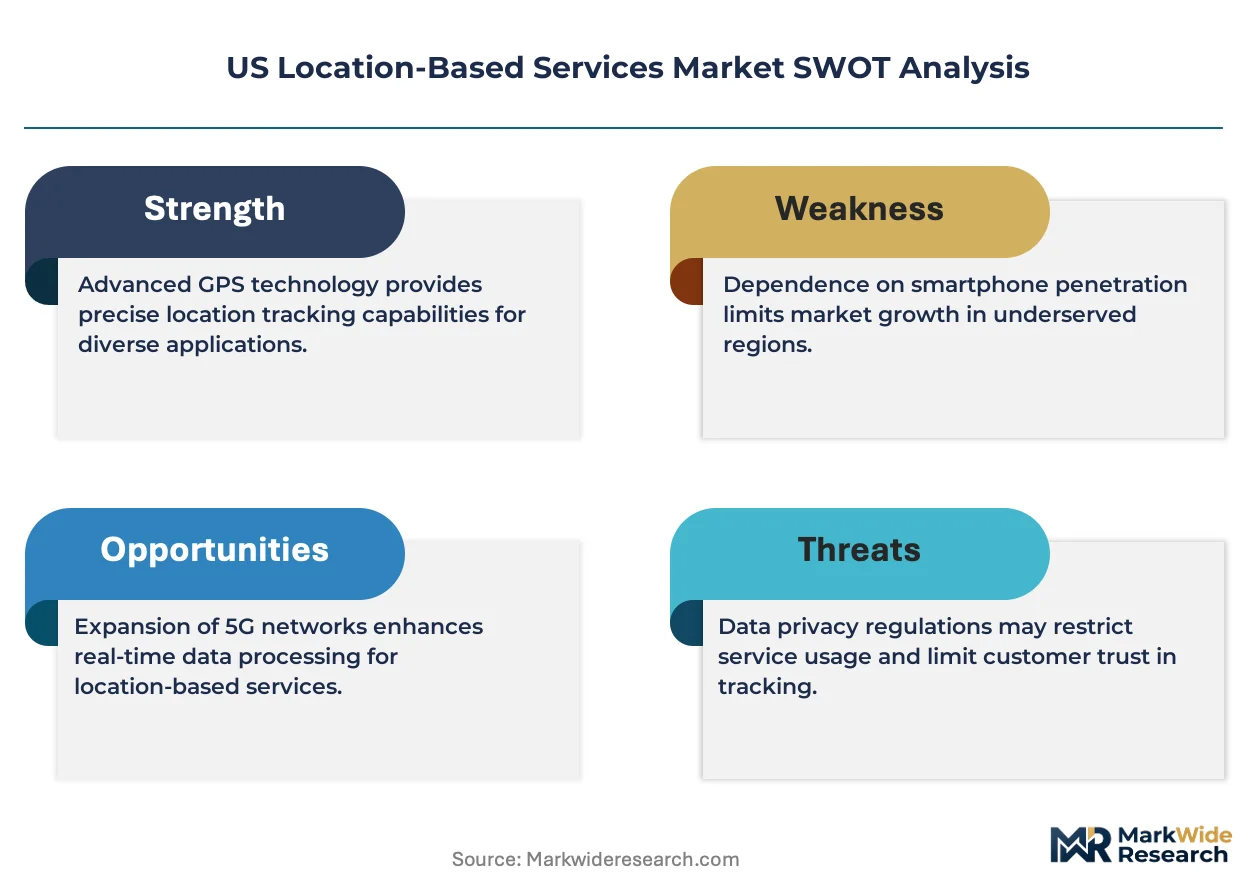
The FCC mandates location accuracy standards for wireless emergency calls, directly shaping carrier investment in network-based positioning infrastructure. FDA guidelines on medical device tracking influence healthcare adoption of real-time location systems for equipment and patient monitoring. State-level privacy frameworks, particularly California's Consumer Privacy Act provisions on geolocation data, compel platform operators to rearchitect consent mechanisms and data retention policies. Stakeholders must monitor evolving state privacy patchworks while calibrating product roadmaps between precision capabilities and regulatory compliance thresholds.
Market Dynamics
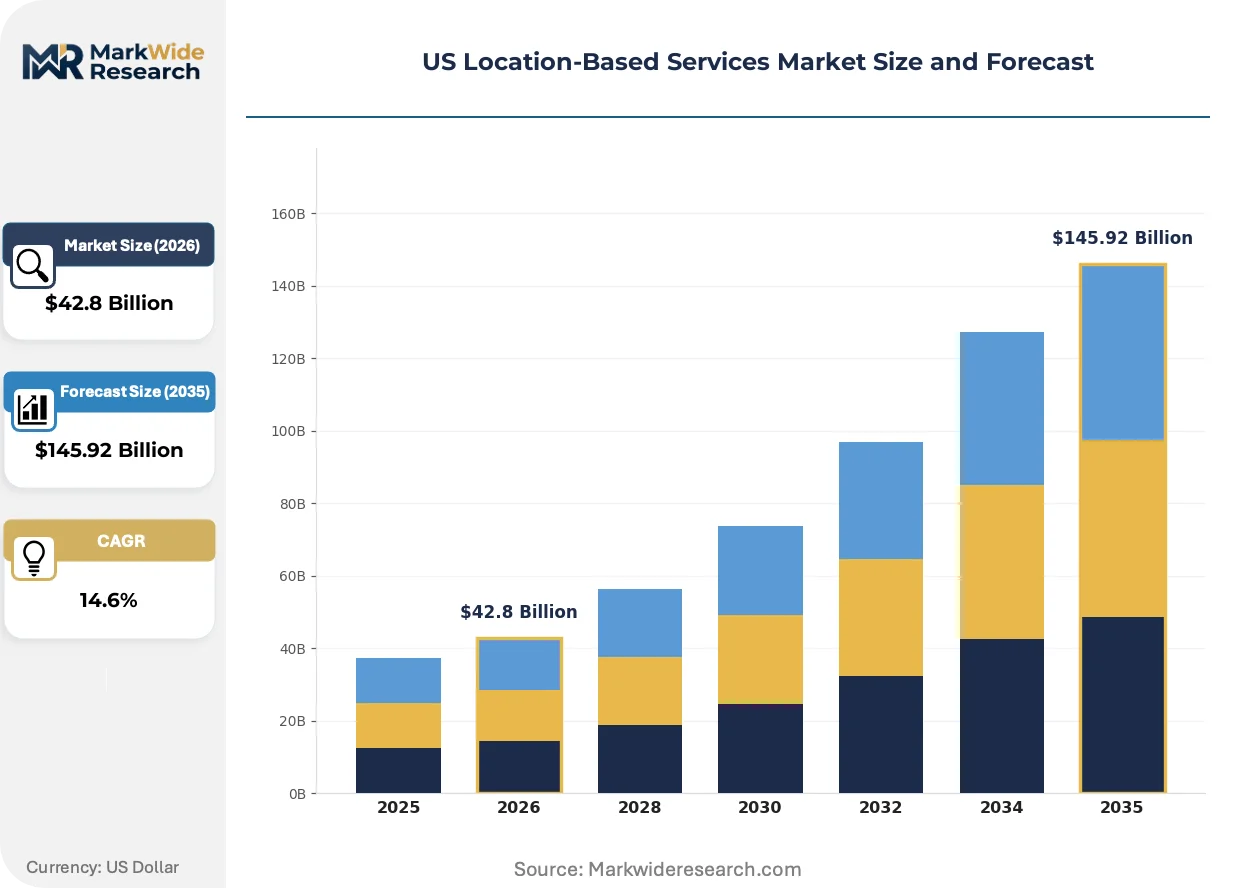
The FCC's Enhanced 911 mandate is forcing carriers to rebuild network positioning infrastructure, while fleet logistics operators scale real-time tracking deployments across Texas and California distribution corridors. This dual regulatory-commercial pressure is compressing vendor timelines and reshaping platform architecture requirements.
Growth Catalysts
- FCC Enhanced 911 Mandate:The regulation compels wireless carriers to invest in network-based positioning infrastructure, expanding the addressable market for location platform providers and precision hardware suppliers.
- Fleet Logistics Automation:Asset-heavy operators in Texas and California distribution hubs are deploying real-time tracking as supply chain visibility becomes non-negotiable for enterprise procurement.
- Bluetooth Beacon Proliferation:Retail environments across the US are adopting proximity beacon systems for indoor positioning, capturing foot traffic analytics and triggering location-based customer engagement.
Market Restraints
- Silicon Supply Concentration:GPS chipset fabrication concentrates among a limited supplier base, exposing platform vendors to allocation risk and extended lead times for precision positioning hardware.
- California Privacy Compliance Burden:The state's Consumer Privacy Act provisions on geolocation data compel operators to rearchitect consent mechanisms, adding engineering overhead and legal review cycles.
- Signal Degradation in Urban Canyons:Multipath interference in dense metropolitan environments limits GPS accuracy to 30-50 meters, constraining use cases requiring sub-meter precision without augmentation systems.
Strategic Opportunities
- Healthcare RTLS Expansion:FDA guidelines on medical device tracking are accelerating hospital adoption of real-time location systems for equipment and patient monitoring workflows.
- Midwest Manufacturing Corridors:Underpenetrated industrial zones in Ohio and Michigan present white space for asset tracking deployments as supply chain reshoring intensifies.
- 5G Positioning Convergence:The integration of cellular network timing with satellite triangulation is enabling indoor-outdoor seamless tracking without hardware handoffs.
Industry Challenges
- Geospatial Engineering Talent Scarcity:Platform operators face acute shortages of specialists combining signal processing expertise with cloud-native architecture skills.
- Legacy Fleet System Integration:Enterprise logistics customers require API bridges to decades-old telematics infrastructure, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Location-Based Services Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $145.92 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Wi-Fi, Bluetooth, Geofencing Application: Navigation, Asset Tracking, Emergency Services, Marketing End User: Retail, Healthcare, Transportation, Entertainment Service Type: Mapping Services, Location Analytics, Data Mining, Others |
| Companies Covered | Google LLC, IBM Corporation, Cisco Systems Inc., HPE Aruba Inc, Zebra Technologies Corporation, Esri, Apple Inc., HERE Technologies, AT&T Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Location-Based Services Market Trends and Innovations
Digital twin architectures are virtualizing physical asset management, while regulatory mandates on emergency positioning and privacy reshape platform requirements. These forces are compressing vendor roadmaps and fragmenting competitive moats.
Cloud-native location engines are virtualizing on-premise geospatial processing stacks. Enterprise fleet operators and smart city administrators are adopting these platforms at accelerated procurement cycles. The shift is virtualizing capital expenditure into operational spending models and enabling elastic scaling during peak tracking demand periods.
The FCC continues tightening location accuracy thresholds for wireless emergency calls, with Phase II mandates requiring horizontal precision within 50-300 meters and vertical floor-level identification. Carriers are deploying hybrid A-GPS and terrestrial beacon networks to satisfy compliance. Rural coverage gaps and indoor environments present the steepest compliance challenges, driving investment in network-based positioning overlays.
Subscription-based intelligence platforms are displacing perpetual-license geospatial software. Municipal governments and utility operators are shifting procurement toward metered analytics services with embedded data feeds. California water districts and Texas energy cooperatives represent the most visible adoption front, unbundling traditional GIS vendor relationships in favor of API-first location intelligence providers.
US Location-Based Services Market Segmentation
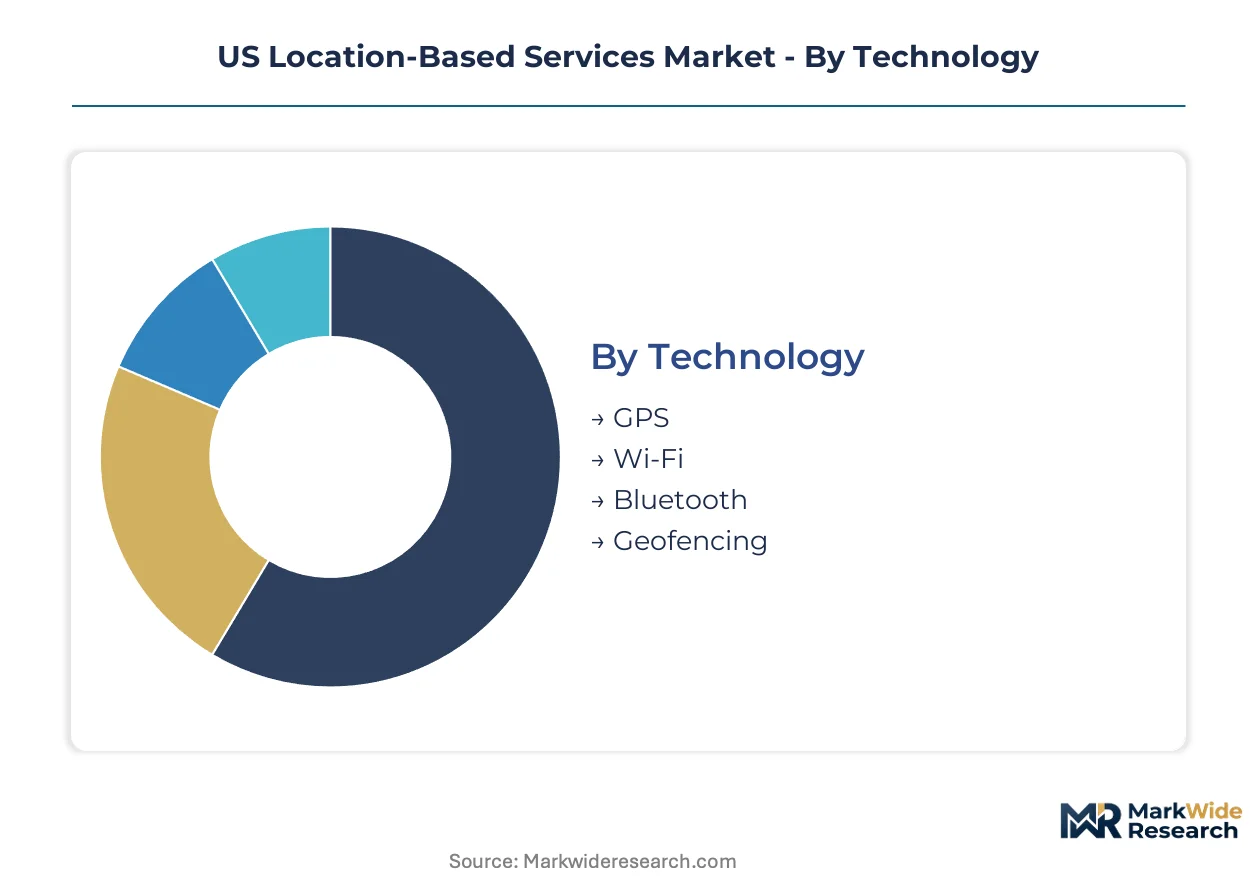
Technology choices in location-based services determine accuracy thresholds, infrastructure costs, and regulatory compliance paths. End-use concentration across Texas logistics corridors and California healthcare clusters shapes segment prioritization for platform vendors.
Technology:
Cost tier determines deployment scale and precision capability across outdoor and indoor environments.
- GPS:Satellite triangulation achieves 3-10 meter accuracy under open-sky conditions using constellations including NAVSTAR and Galileo. Fleet operators across Texas distribution hubs deploy GPS-dominant stacks for highway asset visibility, though urban canyon multipath degrades performance to 30-50 meters in downtown Dallas and Houston.
- Bluetooth:Proximity beacon systems transmit at 2.4 GHz for indoor positioning with 1-3 meter precision using received signal strength indicators. California retailers in Los Angeles and San Francisco metro areas are scaling beacon networks for foot traffic analytics and proximity-triggered engagement, capturing the steepest expansion trajectory among positioning technologies.
- Wi-Fi:Fingerprinting techniques leverage existing access point infrastructure for indoor localization without dedicated hardware deployment.
- Geofencing:Virtual perimeter triggers enable automated workflows when assets cross defined boundaries, common in construction site safety and fleet dispatch systems.
GPS holds installed capacity. Bluetooth is rotating up the share rankings.
Application:
Volume concentration separates mission-critical infrastructure from discretionary marketing spend.
- Asset Tracking:Real-time monitoring of mobile and fixed assets through continuous coordinate transmission enables supply chain visibility. Texas logistics operators in the Dallas-Fort Worth corridor deploy these systems as procurement requirements harden, with FCC mandates on commercial vehicle location logging adding compliance pressure.
- Emergency Services:Network-based positioning satisfies FCC Enhanced 911 mandates requiring horizontal accuracy within 50-300 meters and vertical floor-level identification. Carriers are rebuilding infrastructure to meet these thresholds, with rural coverage gaps and indoor environments presenting the steepest compliance challenges.
- Navigation:Consumer routing and turn-by-turn guidance applications leverage crowd-sourced traffic data and predictive arrival modeling.
- Marketing:Location-triggered promotional delivery and foot traffic attribution serve retail and hospitality sectors with measurable conversion tracking.
Asset Tracking holds installed capacity. Emergency Services is rotating up the share rankings.
End User:
Customer type determines procurement cycle length and integration complexity for platform vendors.
- Transportation:Fleet logistics operators demand sub-minute location refresh rates and API bridges to legacy telematics systems. Texas and California distribution corridors concentrate enterprise spending as shippers mandate real-time visibility for contract eligibility.
- Healthcare:FDA guidelines on medical device tracking accelerate hospital adoption of real-time location systems for equipment and patient monitoring. California health systems in the Bay Area and Los Angeles basin lead deployment of RTLS for infusion pump and wheelchair location.
- Retail:Proximity marketing and inventory positioning applications serve brick-and-mortar operators competing with e-commerce fulfillment speed.
- Entertainment:Venue navigation and augmented reality experiences leverage indoor positioning for visitor engagement in theme parks and stadiums.
Transportation holds installed capacity. Healthcare is rotating up the share rankings.
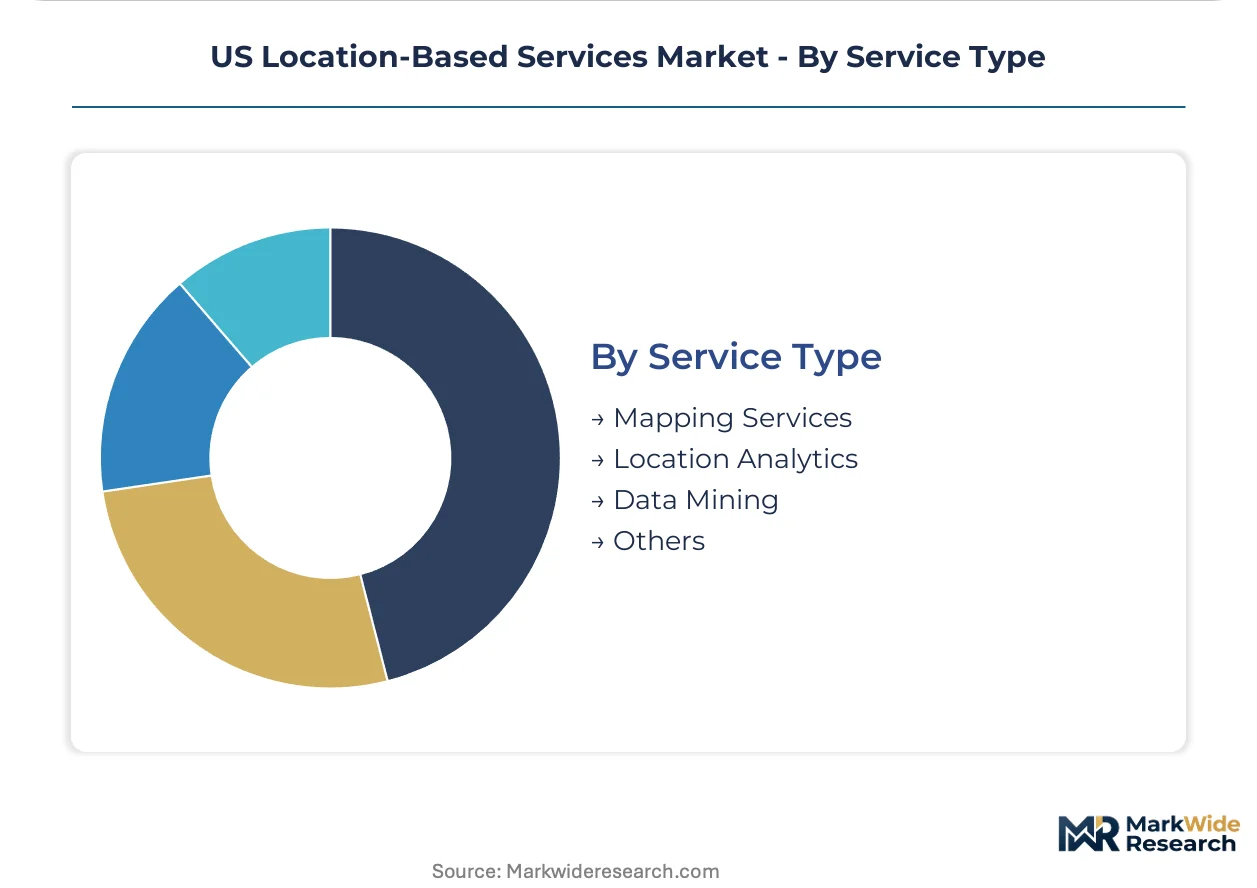
Service Type:
Margin structure separates commodity data feeds from analytical subscription platforms.
- Location Analytics:Subscription-based intelligence platforms aggregate coordinate streams into pattern recognition and predictive models. California water districts and Texas energy cooperatives are unbundling traditional GIS vendor relationships in favor of these API-first services with embedded data feeds.
- Mapping Services:Basemap rendering, geocoding, and routing engine APIs provide foundational location infrastructure for consumer and enterprise applications. Google dominates consumer layers while HERE Technologies anchors enterprise fleet tracking through specialized geospatial engines.
- Data Mining:Foot traffic pattern extraction and dwell time analysis convert raw coordinates into commercial intelligence for site selection and marketing optimization.
- Others:Specialized offerings including geofencing-as-a-service and custom positioning algorithm development serve niche vertical requirements.
Mapping Services holds installed capacity. Location Analytics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC mandates on emergency positioning accuracy and state-level privacy frameworks are redrawing infrastructure investment patterns across US sub-regions. Texas and California logistics corridors concentrate enterprise fleet deployments, while healthcare systems in the Northeast and Midwest accelerate real-time location system procurement.
California
Healthcare systems in the Bay Area and Los Angeles basin deploy real-time location systems for medical equipment tracking under FDA guidelines. The state's Consumer Privacy Act compels platform operators to rearchitect consent mechanisms and data retention policies. Technology corridor concentration in Silicon Valley anchors cloud-native location engine development for enterprise customers.
Texas
Fleet logistics operators in the Dallas-Fort Worth corridor scale real-time tracking deployments as shippers mandate visibility for contract eligibility. FCC commercial vehicle location logging requirements add compliance pressure to transportation procurement. Distribution hub density in Houston drives GPS-dominant stack adoption for highway asset visibility.
Northeast Corridor
Municipal governments in New York and Massachusetts shift procurement toward metered location analytics services with embedded data feeds. State privacy frameworks parallel California provisions, requiring geolocation consent mechanism redesign. Greater Boston's healthcare cluster advances hospital adoption of patient monitoring workflows using indoor positioning systems.
Midwest Manufacturing Belt
Industrial zones in Ohio and Michigan present underpenetrated white space for asset tracking deployments as supply chain reshoring intensifies. Manufacturing facility operators seek API bridges to legacy telematics infrastructure, extending deployment timelines. Chicago logistics hub concentration drives demand for sub-minute location refresh rates across intermodal freight operations.
Pacific Northwest
Smart city administrators in Seattle and Portland adopt cloud-native location engines at accelerated procurement cycles, virtualizing capital expenditure into operational spending models. State environmental regulations intersect with fleet electrification mandates, positioning location data as critical for charging infrastructure optimization. Technology workforce density supports geospatial engineering talent pipelines for platform operators.
US Location-Based Services Market Competitive Landscape
On the supply side, the industry is consolidating around mapping data infrastructure and specialized geospatial engines rather than fragmenting across point solutions. Platform vendors compete through subscription-based intelligence models displacing perpetual-license software relationships. Two strategic archetypes dominate: consumer navigation layer providers leveraging crowd-sourced data networks, and enterprise-grade fleet tracking specialists with customized geospatial engines. Competitive moves concentrate on API-first service unbundling and hybrid positioning technology convergence.
Within the enterprise tracking tier, HERE Technologies and Zebra Technologies Corporation exemplify specialized hardware-software integration approaches, while Google LLC occupies a position spanning consumer and commercial application layers. Esri represents the analytical toolset archetype serving government and utility procurement channels. These three anchors demonstrate how vendor strategies diverge between precision positioning hardware, cloud-native platform delivery, and deep analytical specialization for regulated verticals.
| Leading Market Players |
|---|
| Google LLC |
| IBM Corporation |
| Cisco Systems Inc. |
| HPE Aruba Inc |
| Zebra Technologies Corporation |
| Esri |
| Apple Inc. |
| HERE Technologies |
| AT&T Inc. |
| Others |
Pricing and Supply Chain Analysis
Dallas-Fort Worth distribution corridor cost dynamics reveal how GPS chipset supply concentration enables premium pricing for FCC-certified positioning stacks while commodity Bluetooth beacon modules face downward pressure from Asian manufacturing scale.
Pricing Analysis
Certification level creates the primary spread between emergency-grade positioning stacks and standard fleet tracking tiers. Subscription-based SaaS pricing dominates enterprise procurement, with FCC Phase II compliance tiers commanding premiums over basic commercial vehicle logging tiers. Price differentiation rests on accuracy guarantees and indoor-outdoor seamlessness rather than hardware specifications alone. Cost compression in standard GPS modules is intensifying because foundry allocation favors automotive-grade volumes, squeezing margins for mid-tier platform vendors.
Supply Chain Analysis
Export-control restrictions on precision timing components limit flows of atomic clock-grade oscillators and certain signal processing ASICs to Chinese equipment vendors. GPS chipset fabrication concentrates in Taiwan, South Korea, and the United States, while Bluetooth beacon assembly clusters in Shenzhen and Dongguan. Raw material dependencies include gallium arsenide substrates, rare-earth magnetics for antenna arrays, and high-purity silicon wafers. Single-source vulnerability around Taiwan Semiconductor's advanced-node capacity presents the most acute structural risk. Distribution runs through direct OEM partnerships for enterprise fleet contracts and electronics distributors for retail beacon deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform specialization is fragmenting the location services value chain, with FCC mandates and state privacy frameworks creating compliance-driven niches that reward focused engineering over horizontal breadth.
For Market Incumbents: Build data network effects through crowd-sourced traffic and indoor map contributions that compound with scale. Consolidate around hybrid positioning engines that fuse GPS, Bluetooth, and 5G timing without hardware handoffs to neutralize pure-play indoor specialists. The threat of cloud-native entrants with API-first delivery models demands defensive certification investment in FDA-grade healthcare tracking and FCC-compliant emergency positioning tiers.
For New Entrants and Emerging Players: Establish a beachhead in Midwest manufacturing corridors where supply chain reshoring is outpacing legacy telematics coverage. Target Ohio and Michigan industrial zones with asset tracking solutions purpose-built for legacy system API bridges that incumbents deprioritize. The most penetrable segment is mid-market manufacturers seeking subscription-based location analytics without perpetual GIS licensing overhead.
For Investors and Strategic Acquirers: Cloud-native location engine specialists with healthcare RTLS deployments represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on recurring revenue density and vertical-specific regulatory moats rather than horizontal user scale. Watch for inflection when 5G positioning convergence achieves indoor-outdoor seamless tracking without dedicated beacon infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Positioning Engine Development | FCC Phase II mandates require 50-meter horizontal and floor-level vertical accuracy without GPS augmentation. |
| Healthcare RTLS Partnership | FDA guidelines on medical device tracking accelerate hospital procurement cycles for equipment location systems. |
| API-First Platform Unbundling | California water districts and Texas energy cooperatives are displacing perpetual GIS licenses with metered services. |
| 5G Positioning Convergence Investment | Cellular network timing integration enables seamless indoor-outdoor tracking without hardware handoffs. |
| Privacy Compliance Architecture | California Consumer Privacy Act provisions compel consent mechanism rearchitecture across geolocation data flows. |
Research Methodology
The analysis maps GPS-dominant fleet tracking, Bluetooth beacon retail networks, Wi-Fi fingerprinting systems, and 5G positioning convergence layers, each validated through fleet logistics operators, healthcare system CIOs, retail technology directors, and FCC regulatory affairs specialists. Primary interviews with platform engineering leads and carrier network architects combined with secondary validation from FCC rulemaking dockets, FDA guidance documents, SEC filings of listed component vendors, and state legislative tracking databases. Bottom-up deployment estimates triangulate against top-down carrier infrastructure spending disclosures.
Assumptions held fixed include FCC Phase II compliance timelines, California Consumer Privacy Act enforcement patterns, and foundry allocation priorities for automotive-grade GPS chipsets; variables tested include 5G positioning standardization velocity and supply chain reshoring intensity across Midwest manufacturing. Segmentation dimensions modeled cover technology type, application criticality, end-user procurement cycle length, and service delivery model. CAGRs derive from deployment run-rate analysis across Texas and California logistics corridors calibrated against carrier capital expenditure guidance. Industry-specific inputs include fleet telematics refresh cycles and hospital RTLS procurement committee decision timelines.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or carrier infrastructure spending priorities would shift the trajectory. Forecasts reflect these documented assumptions without claiming predictive certainty. Material shifts in FCC mandate timing or state privacy framework expansion beyond California would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Mobile Mapping Market