
 Mobile Mapping Market | 2026-2036
Mobile Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Mapping Market Analysis
Subscription-based point cloud processing software is decoupling hardware sales from recurring revenue in mobile mapping. Trimble Inc. leverages its precision agriculture channels to cross-sell terrestrial scanning systems into construction workflows. Hexagon AB anchors its market position through captive sensor manufacturing at Leica Geosystems, while Google competes by integrating street-view capture into its cloud mapping stack.
Mobile mapping denotes the acquisition of geospatial data from moving platforms equipped with synchronized LiDAR, GNSS, and inertial measurement units, typically achieving absolute accuracies of 2-5 centimeters for corridor-scale surveys. The technology serves civil infrastructure lifecycle management, from as-built verification through predictive maintenance scheduling. LiDAR-based deployments command the dominant share of hardware value, though photogrammetry segments are expanding fastest where colorized mesh deliverables satisfy lower-precision use cases. Cloud-based deployment architectures are capturing margin pools previously retained by on-premises data centers, while route optimization applications within transportation end users exhibit the steepest adoption curves.
FAA regulations governing unmanned aerial system beyond-visual-line-of-sight operations directly constrain airborne mobile mapping missions across United States airspace. FCC spectrum allocations for L-band correction services shape GNSS accuracy tiers available to field crews. EPA stormwater management rules and FHWA bridge inspection standards both mandate georeferenced condition documentation that mobile mapping systems deliver. Stakeholders must weigh hardware refresh cycles against software subscription lock-in when structuring fleet procurement decisions.
Market Dynamics
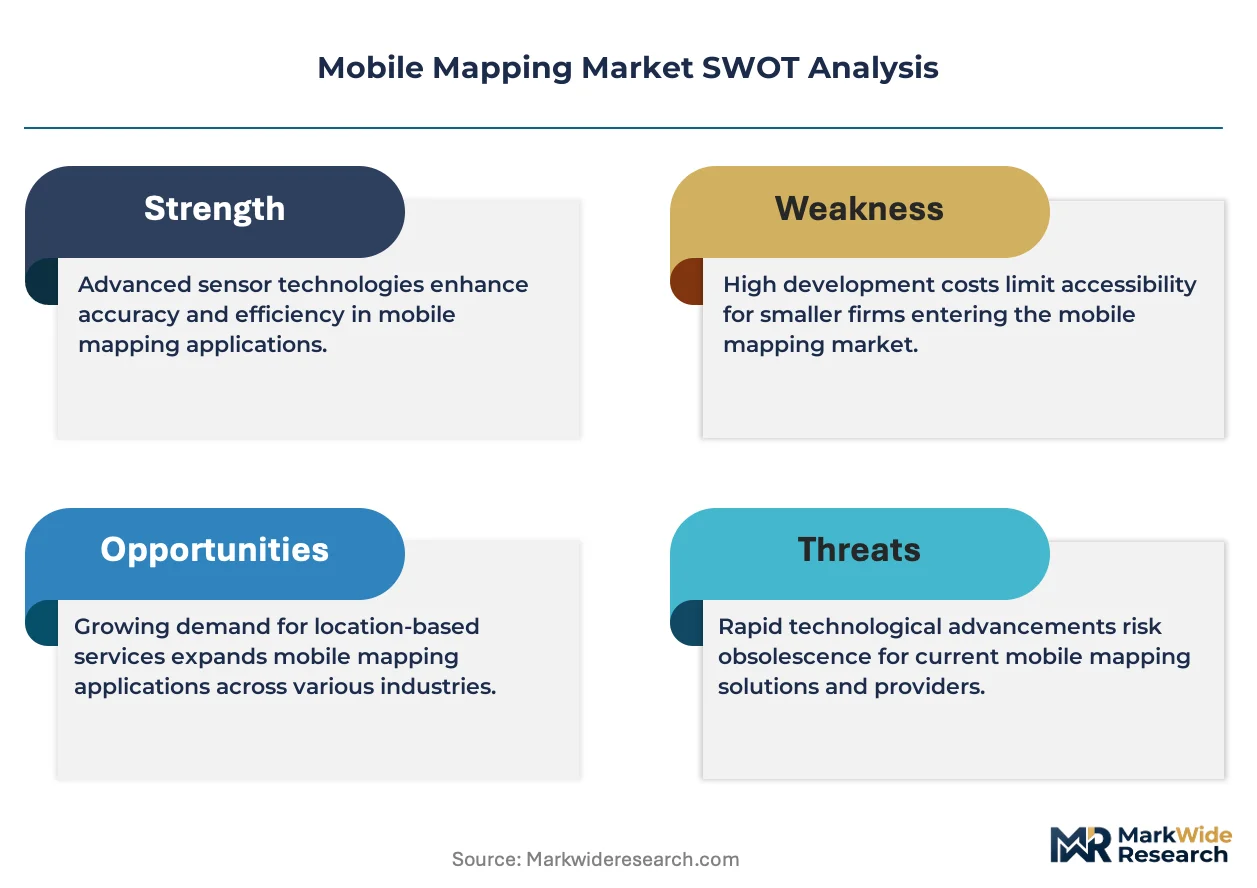
AI-powered point cloud classification is compressing survey timelines from weeks to days, forcing hardware vendors to bundle software subscriptions or lose margin to pure-play analytics platforms.
Growth Catalysts
- FHWA bridge inspection standards:Federal mandates for georeferenced condition documentation drive fleet-scale LiDAR procurement across state departments of transportation.
- Stormwater management rules:EPA requirements for impervious surface mapping accelerate municipal adoption of mobile mapping for asset inventory.
- Utility corridor digitization:Electric transmission and pipeline operators deploy terrestrial scanning to replace manual survey crews in vegetation management programs.
Market Restraints
- Sensor supply concentration:High-precision LiDAR emitters and MEMS inertial units depend on concentrated Asian component suppliers, creating vulnerability to trade restrictions.
- FAA beyond-visual-line-of-sight constraints:Unmanned aerial system regulations limit airborne mobile mapping missions across United States airspace, capping mission efficiency.
- Photogrammetry substitution:Lower-cost drone photogrammetry captures share in colorized mesh applications where 5-10 centimeter accuracy satisfies deliverable requirements.
Strategic Opportunities
- Predictive maintenance convergence:Mobile mapping data feeds AI-driven infrastructure deterioration models, opening recurring revenue streams from civil asset owners.
- German smart city procurement:Municipal governments accelerate street-level imaging system tenders for digital twin construction and traffic flow optimization.
- Cloud-native processing architectures:Browser-based point cloud visualization eliminates on-premises data center requirements, lowering barriers for mid-size survey firms.
Industry Challenges
- Geospatial AI talent scarcity:Survey firms struggle to hire machine learning engineers capable of training custom classification models for infrastructure feature extraction.
- Multi-sensor calibration complexity:Synchronizing LiDAR, GNSS, and inertial measurement units demands specialized technicians, extending deployment timelines and raising field labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Mapping Market |
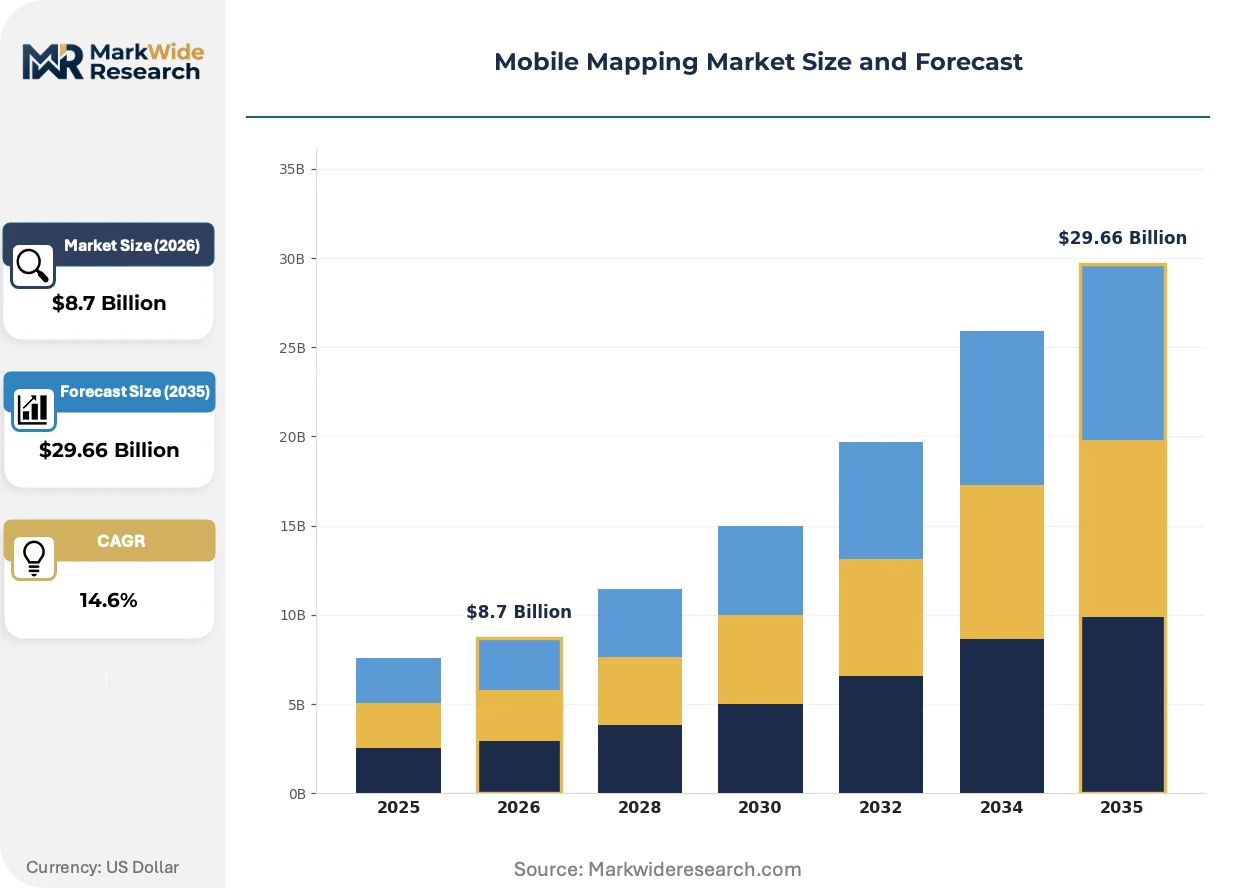
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, GPS, Photogrammetry, IMUs Application: Urban Planning, Asset Management, Disaster Response, Route Optimization End User: Construction, Transportation, Utilities, Environmental Deployment: Cloud-Based, On-Premises, Mobile Devices, Field Solutions |
| Companies Covered | Trimble Inc., Hexagon AB (Leica Geosystems), Topcon Corporation, Google (Alphabet Inc.), Teledyne Geospatial, Microsoft Corporation, RIEGL Laser Measurement Systems, TomTom International, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Mapping Market Emerging Trajectories
Software-defined data capture is dissolving the boundary between field hardware and cloud analytics, enabling real-time quality control and automated feature extraction that reshapes competitive positioning.
Solid-state LiDAR is consolidating market share in corridor-scale mobile mapping by eliminating mechanical spinning components that demand frequent recalibration. State transportation departments and rail operators adopt these sensors for continuous pavement condition monitoring. The technology is consolidating vendor margins into firmware and perception software rather than precision mechanics.
Japan's METI standards for infrastructure digital twins mandate open-format point cloud deliverables, preventing vendor lock-in and accelerating interoperability investments. Engineering firms must now structure contracts around IFC-compatible outputs rather than proprietary formats. Rail and highway operators in Japan face compressed procurement cycles as these standards take effect.
Survey contractors now unbundle data collection from analytics, selling raw point clouds to clients who process through subscription platforms. This disintermediates traditional full-service relationships and pressures hardware vendors to capture recurring revenue through software attach rates. The pattern is most visible in United States civil infrastructure, where federal funding volatility makes capital-light service models attractive to municipal buyers.
Mobile Mapping Market Segmentation
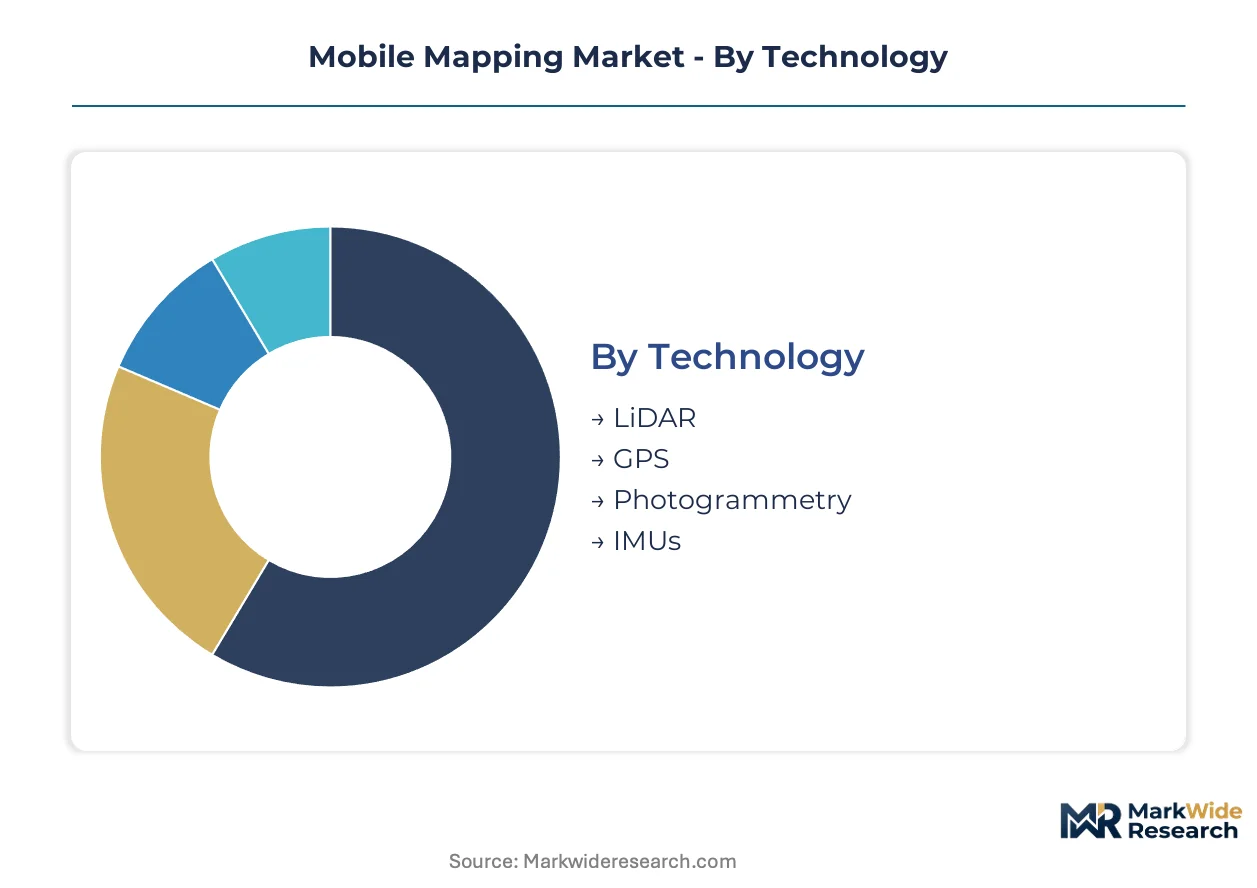
Mobile mapping systems integrate multiple sensor modalities and deployment architectures, each segment exhibiting distinct margin profiles and procurement cycles. Technology choices determine hardware capital intensity, while application focus shapes software attach rates and recurring revenue potential.
Technology:
LiDAR and photogrammetry segments diverge sharply in integration depth, with standalone terrestrial scanning commanding premium pricing against embedded drone-mounted alternatives.
- LiDAR:Solid-state emitters and mechanical spinning units generate dense point clouds with absolute accuracies of 2-5 centimeters. State transportation departments in the United States drive fleet-scale procurement for corridor-scale surveys under FHWA bridge inspection mandates.
- Photogrammetry:Multi-camera arrays capture colorized mesh deliverables where 5-10 centimeter accuracy satisfies lower-precision use cases. Drone operators in Germany substitute photogrammetry for LiDAR in vegetation management programs, compressing survey costs by eliminating inertial hardware.
- GPS:Multi-constellation receivers with L-band correction services provide georeferencing backbone for all mobile mapping platforms.
- IMUs:MEMS and fiber-optic inertial units maintain trajectory precision during GNSS signal degradation in urban canyons or forested corridors.
LiDAR leads volumes today; photogrammetry is gaining share fastest.
Application:
Application segments stratify by data refresh frequency, with continuous monitoring programs generating recurring revenue against one-time as-built documentation projects.
- Urban Planning:Street-level imaging systems feed digital twin construction for traffic flow optimization and zoning enforcement. Japanese municipal governments under METI open-format mandates accelerate procurement cycles for IFC-compatible deliverables.
- Asset Management:Predictive maintenance scheduling for civil infrastructure relies on repeated mobile mapping passes to train AI deterioration models. Electric transmission operators deploy terrestrial scanning to replace manual survey crews.
- Disaster Response:Rapid deployment kits enable post-event damage assessment where FAA beyond-visual-line-of-sight constraints limit airborne alternatives.
- Route Optimization:Last-mile logistics providers consume georeferenced road condition data to minimize vehicle wear and fuel consumption.
Asset management dominates current deployment value; route optimization shows the steepest expansion trajectory.
End User:
End user segments separate by procurement sophistication, with federal-mandated transportation agencies driving standardization against fragmented construction contractor purchasing.
- Construction:General contractors verify as-built conditions against design models, with precision agriculture channels cross-selling terrestrial scanning into earthmoving workflows.
- Transportation:Rail operators and state departments of transportation deploy continuous pavement monitoring systems. Solid-state LiDAR eliminates mechanical recalibration demands for trackside installations.
- Utilities:Pipeline operators map vegetation encroachment within corridor easements, integrating point clouds with SCADA systems.
- Environmental:EPA stormwater management rules mandate impervious surface mapping, accelerating municipal mobile mapping adoption for regulatory compliance documentation.
Transportation commands the largest procurement budgets; environmental compliance is expanding most quickly.
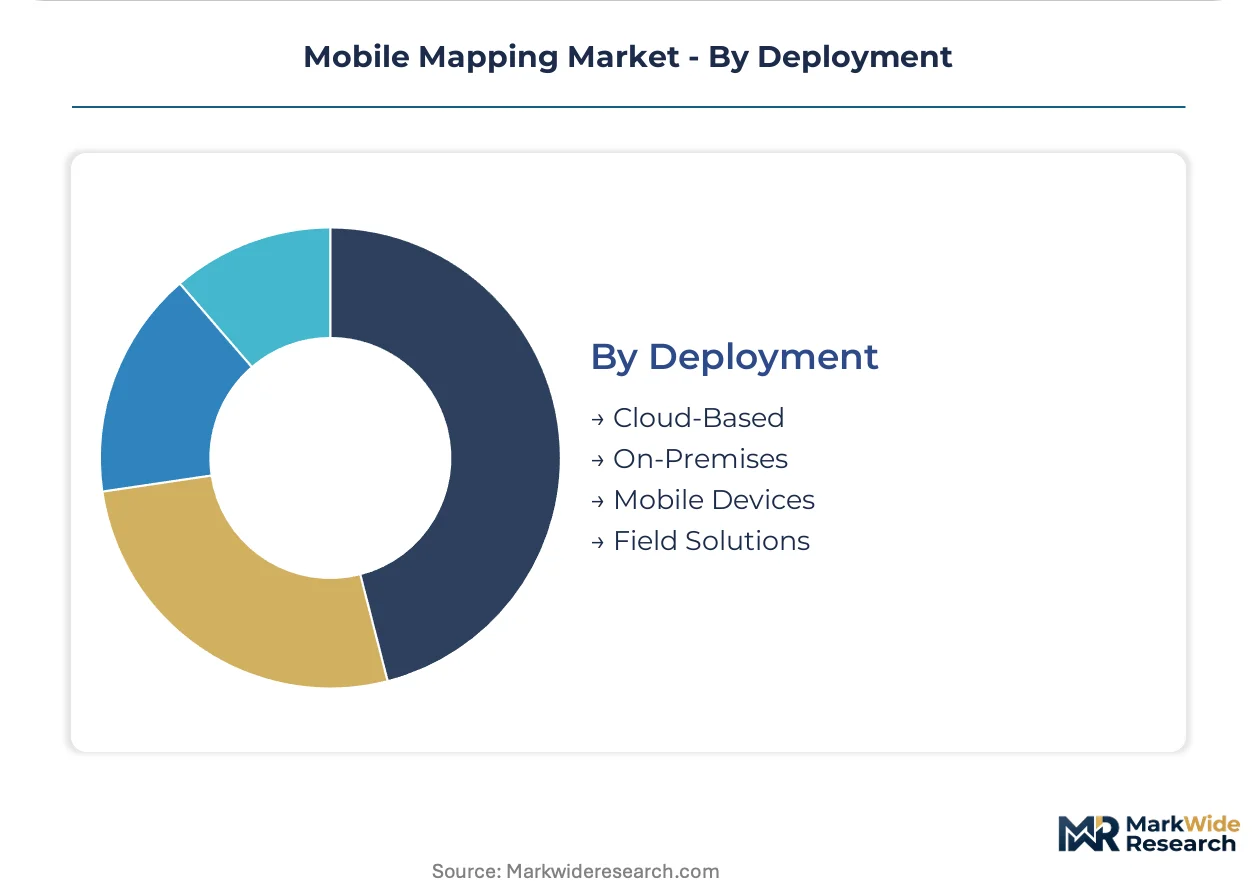
Deployment:
Deployment architectures determine capital structure, with cloud-native processing eliminating on-premises data center requirements for mid-size survey firms.
- Cloud-Based:Browser-based point cloud visualization and automated feature extraction compress survey timelines from weeks to days. Subscription models decouple hardware sales from recurring revenue streams.
- On-Premises:Large engineering firms retain sensitive infrastructure data within controlled environments, particularly for defense-adjacent projects.
- Mobile Devices:Tablet-based field applications enable real-time quality control during data capture, reducing return-to-site costs.
- Field Solutions:Ruggedized edge computing units process raw sensor streams without connectivity dependencies for remote corridor surveys.
Cloud-based deployment leads new contract value; mobile devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling mobile mapping procurement toward jurisdictions with clear digitization mandates and open-data standards, compressing deployment timelines where compliance costs are lowest.
United States
FHWA bridge inspection mandates and utility corridor mapping programs drive fleet-scale LiDAR procurement across state departments of transportation. FAA beyond-visual-line-of-sight regulations constrain airborne missions but accelerate terrestrial system adoption. California and Texas transportation agencies lead corridor-scale deployments for pavement condition monitoring.
Germany
Municipal governments accelerate street-level imaging tenders for smart city infrastructure and traffic flow optimization. KBA vehicle certification standards shape sensor integration requirements for automotive mobile mapping systems. The Ruhr industrial corridor concentrates terrestrial scanning service providers serving utility vegetation management contracts.
Japan
METI standards for infrastructure digital twins mandate open-format point cloud deliverables, preventing vendor lock-in and accelerating interoperability investments. Rail and highway operators in the Kanto region face compressed procurement cycles as these standards take effect. Osaka-based engineering firms restructure contracts around IFC-compatible outputs.
China
MIIT smart city initiatives and dual carbon goals drive municipal procurement of street-level imaging for urban planning and emissions monitoring. GB standards for geospatial data interoperability shape sensor integration requirements. The Yangtze River Delta concentrates domestic LiDAR manufacturers serving corridor-scale survey contracts.
United Kingdom
Ordnance Survey national mapping programs and infrastructure digital twin initiatives accelerate mobile mapping adoption for asset management. CE marking requirements for survey equipment shape procurement specifications for public sector contracts. The Southeast England corridor concentrates service providers serving rail network digitization projects.
Mobile Mapping Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision sensor vendors capturing hardware margins while cloud platforms absorb software value pools. The vendor base stratifies into three tiers: integrated sensor-software stacks, pure-play hardware fabricators, and analytics-only platforms. Consolidation pressure intensifies as AI-powered classification commoditizes point cloud processing. Dominant competitive moves include strategic partnerships between sensor vendors and cloud infrastructure providers, plus backward integration into captive LiDAR emitter manufacturing.
Among integrated sensor-software specialists, Trimble Inc. and Hexagon AB exemplify the full-stack archetype through precision agriculture and geospatial channels respectively. RIEGL Laser Measurement Systems occupies a position within the premium hardware tier, while Google represents the cloud-platform vector competing through mapping service integration. These three anchors illustrate divergent strategic postures: hardware margin defense, vertical integration, and platform-scale data aggregation.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB (Leica Geosystems) |
| Topcon Corporation |
| Google (Alphabet Inc.) |
| Teledyne Geospatial |
| Microsoft Corporation |
| RIEGL Laser Measurement Systems |
| TomTom International |
| Apple Inc. |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR manufacturing transitions are compressing production costs while redistributing value toward firmware development and perception software licensing. This shift simultaneously erodes mechanical component margins and concentrates supply leverage among semiconductor foundries serving emitter array production.
Pricing Analysis
Distributor margins on terrestrial scanning systems compress as direct-to-OEM channels capture fleet-scale transportation procurement. Three-tier pricing structure across premium, standard, and economy levels reflects sensor accuracy grades and software subscription attach rates. Cost compression in photogrammetry segments intensifies because drone operators substitute multi-camera arrays for inertial hardware. Municipal governments exhibit highest price sensitivity due to federal funding volatility, while electric transmission operators prioritize accuracy over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from state transportation departments, bypassing traditional survey equipment distributors. Component sourcing draws from Taiwan for MEMS inertial units, Japan for fiber-optic gyroscopes, and China for solid-state emitter arrays. Single-source vulnerability concentrates in high-precision LiDAR emitters where qualified suppliers number fewer than five globally. Distribution runs through systems integrators who bundle calibration services with hardware delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile mapping market functions as a stable compounder where infrastructure digitization mandates generate recurring replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Anchor market position through backward integration into captive LiDAR emitter manufacturing, eliminating dependency on concentrated Asian component suppliers. Deepen software attach rates by bundling AI-powered classification subscriptions with hardware refresh cycles, defending against pure-play analytics platforms disintermediating full-service relationships.
For New Entrants and Emerging Players: Enter via cloud-native processing architectures targeting mid-size survey firms lacking on-premises data center infrastructure. Target German municipal smart city procurement where open-format METI standards prevent incumbent vendor lock-in. Pursue route optimization applications for last-mile logistics providers as the steepest expansion trajectory with lowest competitive saturation.
For Investors and Strategic Acquirers: Roll-up economics work for regional survey service providers because fragmented contractor purchasing patterns resist national-scale consolidation. Five-to-ten year viability rests on predictive maintenance convergence creating recurring revenue streams from civil asset owners. Monitor FAA beyond-visual-line-of-sight regulatory relaxation as the signal indicating airborne mobile mapping mission efficiency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emitter Manufacturing | Captive supply of solid-state LiDAR arrays reduces exposure to Taiwan-Japan component concentration. |
| Cloud-Native Platform Launch | Browser-based point cloud visualization eliminates on-premises infrastructure barriers for mid-size survey firms. |
| AI Classification Subscription Bundling | Software attach rates capture recurring revenue streams disintermediated by pure-play analytics platforms. |
| Smart City Channel Partnership | German municipal procurement under KBA certification standards accelerates street-level imaging system tenders. |
| Predictive Maintenance Service Expansion | Repeated mobile mapping passes for infrastructure deterioration models generate recurring revenue from asset owners. |
Methodological Framework
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster. The approach combines structured interviews with state transportation procurement officers, municipal engineering directors, utility corridor survey managers, and LiDAR systems integrators alongside secondary validation from FHWA bridge inspection filings, METI open-format standard documentation, FAA UAS regulatory updates, and EPA stormwater compliance records. Bottom-up segment sizing triangulates against top-down infrastructure spending projections.
Granularity extends to sensor modality, deployment architecture, application frequency, and end-user procurement sophistication across each national market. CAGRs derive from infrastructure digitization mandate timelines, fleet replacement cycles, and software subscription attach rate trajectories. Solid-state LiDAR cost curves and photogrammetry substitution elasticities inform hardware value projections throughout the modeling period.
The model holds under continued federal and municipal infrastructure spending commitment; deviation in regulatory enforcement intensity or trade restriction severity would shift procurement timing. Forecasts reflect assumptions regarding FAA regulatory relaxation pace and METI standard adoption compliance rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market