
 Casein Glycomacropeptide Market | 2026-2036
Casein Glycomacropeptide Market Size, Share, and Industry Trends Forecast 2026-2036
Casein Glycomacropeptide Market Outlook
Multi-source whey fractionation is pivoting toward captive glycomacropeptide recovery as dairy processors seek margin protection against commodity protein volatility. Arla Foods Ingredients leverages its Scandinavian milk pool to secure raw material access for enzymatic separation. Glanbia Nutritionals anchors its sports nutrition vertical with specialized fractionation capacity in Ireland. FrieslandCampina competes through backward integration into Dutch cooperative milk supply, reducing third-party dependency for chromatographic purification feedstock.
Casein glycomacropeptide constitutes the C-terminal hydrophilic fragment released during chymosin-mediated κ-casein cleavage in cheese manufacture, bearing a distinctive branched glycan structure with sialic acid residues that confers prebiotic and appetite-modulating functionality. The powder segment dominates current volume owing to stability advantages in dry-blend sports nutrition and infant formula applications, while liquid concentrates capture expanding share in ready-to-drink formulations where solubility speed determines manufacturing economics. Nutraceuticals applications lead value generation due to peptide-specific health claims requiring clinical substantiation, whereas sports nutrition represents the fastest-growing application as endurance and strength athletes adopt evidence-based recovery protocols.
EFSA novel food assessments and EU dairy hygiene regulations shape product standards for glycomacropeptide concentrates entering European formulations, while FDA GRAS self-affirmation pathways govern US market access for sports nutrition and infant formula applications. The EU F-Gas Regulation indirectly affects processing economics through refrigeration-dependent ultrafiltration stages. Stakeholders must monitor evolving peptide-specific health claim frameworks across multiple jurisdictions to anticipate formulation investment requirements and preempt competitive displacement from alternative bioactive proteins.
Market Dynamics
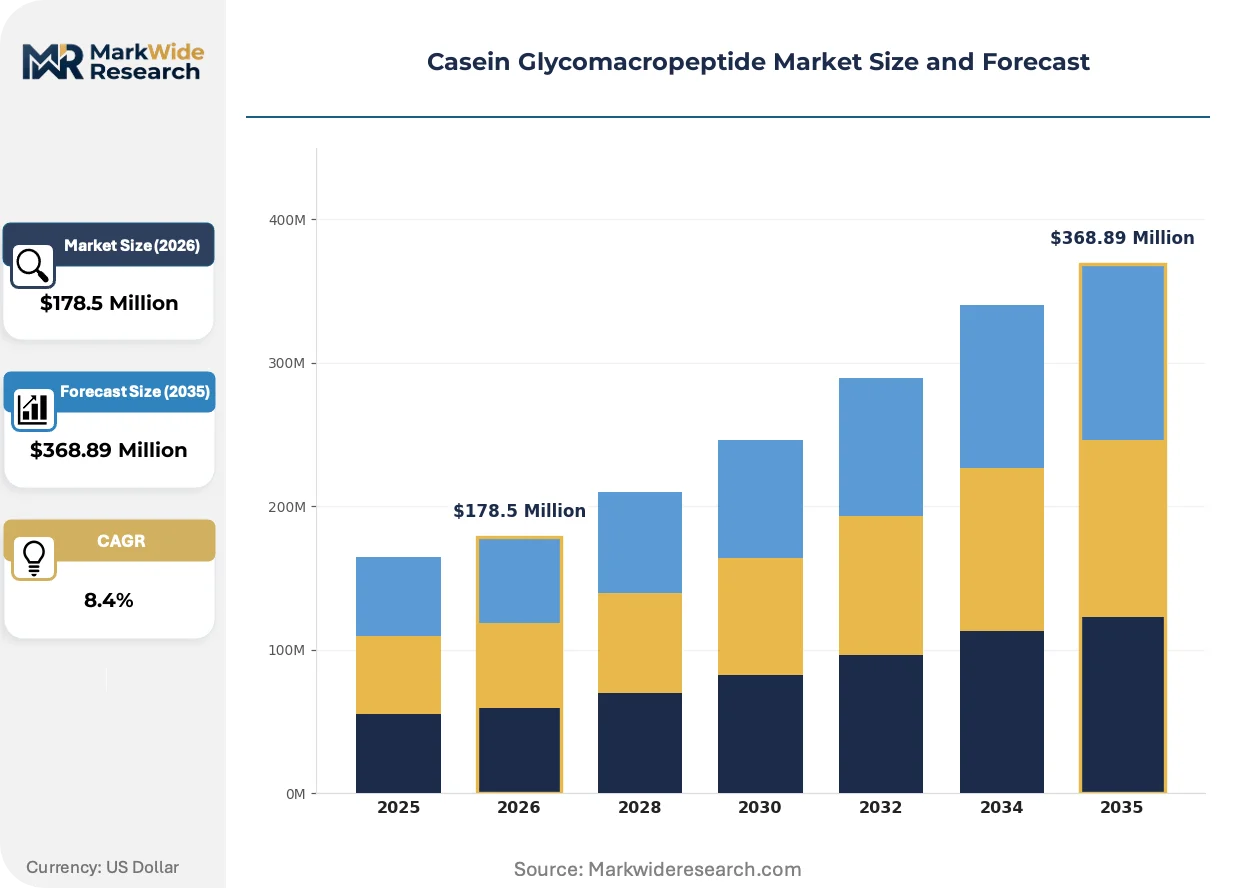
Dairy processors are pivoting captive whey streams toward glycomacropeptide recovery as enzymatic fractionation economics improve against commodity protein margin compression. This structural reconfiguration of cheese byproduct valorization is redrawing competitive boundaries between ingredient specialists and integrated cooperatives.
Growth Catalysts
- Sports Nutrition Formulation Demand:Endurance athletes and strength training protocols are incorporating bioactive peptides into recovery regimens, creating pull-through for sialic acid-enriched concentrates in dry-blend and ready-to-drink applications.
- EFSA Novel Food Pathways:The EU's tightening purity benchmarks for imported concentrates are accelerating investment in European captive production capacity to bypass third-country authorization delays.
- Chymosin-Mediated Separation:Advances in precision enzymatic cleavage of κ-casein are improving glycomacropeptide yield rates from cheese manufacture, lowering unit recovery costs for integrated dairy processors.
Market Restraints
- Chromatographic Purification Feedstock Costs:High-purity resin and solvent requirements for sialic acid retention create fixed cost barriers that disadvantage smaller fractionation operators.
- Scandinavian Milk Pool Concentration:Raw material access concentrates among cooperative structures in Denmark and Sweden, creating supply security risks for non-integrated formulators.
- Plant Protein Substitution:Fermentation-derived and legume-based bioactive alternatives are capturing share in appetite-modulation and prebiotic positioning, pressuring peptide-specific premium pricing.
Strategic Opportunities
- German Functional Food Corridor:Manufacturing clusters around Munich and Cologne offer co-location advantages for just-in-time concentrate delivery to infant formula and medical nutrition producers.
- EU F-Gas Regulation Compliance:Refrigeration-dependent ultrafiltration operators investing in low-global-warming-potential cooling systems can secure operational continuity and preferential supply contracts.
- Clinical Substantiation Pathways:Peptide-specific health claims requiring randomized controlled trials create first-mover advantages for manufacturers with existing trial infrastructure in nutraceutical applications.
Industry Challenges
- Glycan Structure Analytical Talent:Specialized chromatography and mass spectrometry expertise for branched carbohydrate characterization remains scarce, extending quality control hiring cycles.
- GRAS Self-Affirmation Documentation:FDA pathway requirements for US sports nutrition market entry demand substantial toxicology and exposure assessment investment before commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein Glycomacropeptide Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $368.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Concentrate Application: Nutraceuticals, Food & Beverages, Sports Nutrition, Infant Formula End User: Pharmaceutical Companies, Health Food Stores, Restaurants, Fitness Centers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Arla Foods Ingredients, Agropur Ingredients, Glanbia Nutritionals, FrieslandCampina, Saputo Inc., Hilmar Ingredients, New Zealand Milk Products, Valio Ltd., Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein Glycomacropeptide Market Strategic Shifts
Fractionation technology is fragmenting into configurable unit operations that let processors scale capacity without greenfield construction. This modular architecture is compressing entry timelines and reshaping how dairy cooperatives defend margin positions against commodity volatility.
Membrane cascade systems with integrated diafiltration stages are modularizing glycomacropeptide recovery from cheese whey, allowing mid-scale processors to deploy skid-mounted units without centralized chromatography halls. Sports nutrition contract manufacturers in Ireland and the Netherlands are adopting these configurations to secure peptide supply independent of merchant concentrate markets. The technology is modularizing competitive entry barriers that previously required cooperative-scale milk intake volumes.
EFSA's evolving peptide-specific health claim frameworks are forcing clinical substantiation investments that favor manufacturers with existing trial infrastructure. The industrial consequence is a bifurcation between commodity-grade concentrates and premium-positioned ingredients with dossier-backed positioning. Nutraceutical applications in Germany and France are most affected, with formulators prioritizing suppliers with completed novel food authorizations over price-competitive alternatives.
Athlete procurement patterns are compressing switching cycles as evidence-based recovery protocols disseminate through professional team nutrition programs. Direct sourcing relationships between sports nutrition brands and fractionation operators are displacing traditional ingredient distributor intermediaries in high-volume contract manufacturing. This disintermediation is most visible in the UK and Scandinavian markets where team sponsorship deals create captive formulation demand.
Casein Glycomacropeptide Market Segmentation
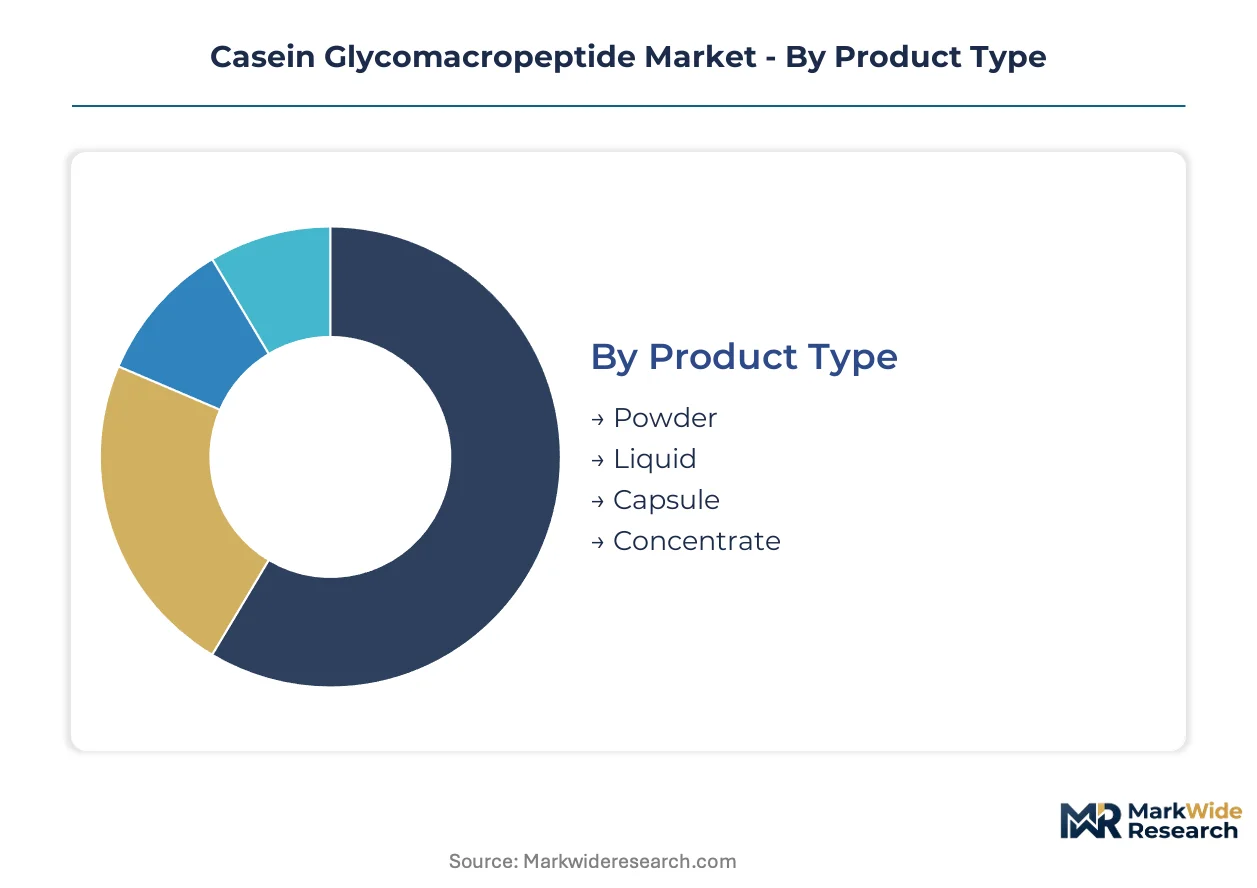
Casein glycomacropeptide fractionation yields distinct physical formats with divergent stability profiles and manufacturing economics. Application-driven purity requirements and end-user procurement sophistication create tiered demand patterns across the value chain.
Product Type:
Powder formats command volume leadership through extended shelf stability and dry-blend compatibility, while liquid concentrates trade handling convenience against refrigeration dependency.
- Powder:Spray-dried particulate with low moisture activity enables ambient storage and bulk transport efficiency. Demand concentrates in German infant formula manufacturing corridors where dry-blend operations prioritize flowability and dissolution speed.
- Liquid:Aqueous concentrates with preserved glycan integrity suit ready-to-drink sports nutrition applications. Irish contract manufacturers favor this format for just-in-time formulation where solubility speed determines line economics.
- Capsule:Encapsulated doses target precision supplementation protocols in clinical nutrition settings.
- Concentrate:Intermediate purity grades serve as feedstock for downstream fractionation and custom formulation.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
Application:
Clinical substantiation requirements separate premium-positioned nutraceutical claims from commodity sports nutrition volumes, with infant formula imposing the most stringent purity thresholds.
- Sports Nutrition:Recovery-focused formulations leverage sialic acid content for endurance athlete protocols. UK team sponsorship programs and Scandinavian fitness chains are pulling through concentrate demand as evidence-based regimens displace generic protein supplementation.
- Nutraceuticals:Peptide-specific health claims require EFSA novel food dossiers or FDA GRAS self-affirmation. French and German formulators prioritize suppliers with completed clinical trials for appetite modulation and prebiotic positioning.
- Infant Formula:κ-casein-derived glycopeptides target digestive comfort and gut microbiome development in early-life nutrition.
- Food & Beverages:Functional dairy applications incorporate glycomacropeptide for texture modification and satiety signaling in weight management products.
Established positioning dominates Nutraceuticals. Steepest expansion trajectory is concentrated in Sports Nutrition.
End User:
Procurement sophistication varies from institutional tender processes to direct consumer subscription models, reshaping supplier relationship structures.
- Pharmaceutical Companies:Medical nutrition divisions require batch documentation and pharmacopeial compliance for enteral feeding applications. Dutch and Belgian manufacturers lead peptide integration into disease-specific nutritional therapies.
- Health Food Stores:Specialty retail channels emphasize clean-label positioning and third-party certification for bioactive peptide supplements.
- Restaurants:Functional menu innovation in wellness-focused dining incorporates glycomacropeptide-fortified beverages and desserts.
- Fitness Centers:On-site retail and programmed nutrition coaching drive direct-to-consumer peptide adoption in high-performance training facilities.
Institutional procurement maturity sits with Pharmaceutical Companies. Direct-to-consumer experimentation is concentrated in Fitness Centers.
Distribution Channel:
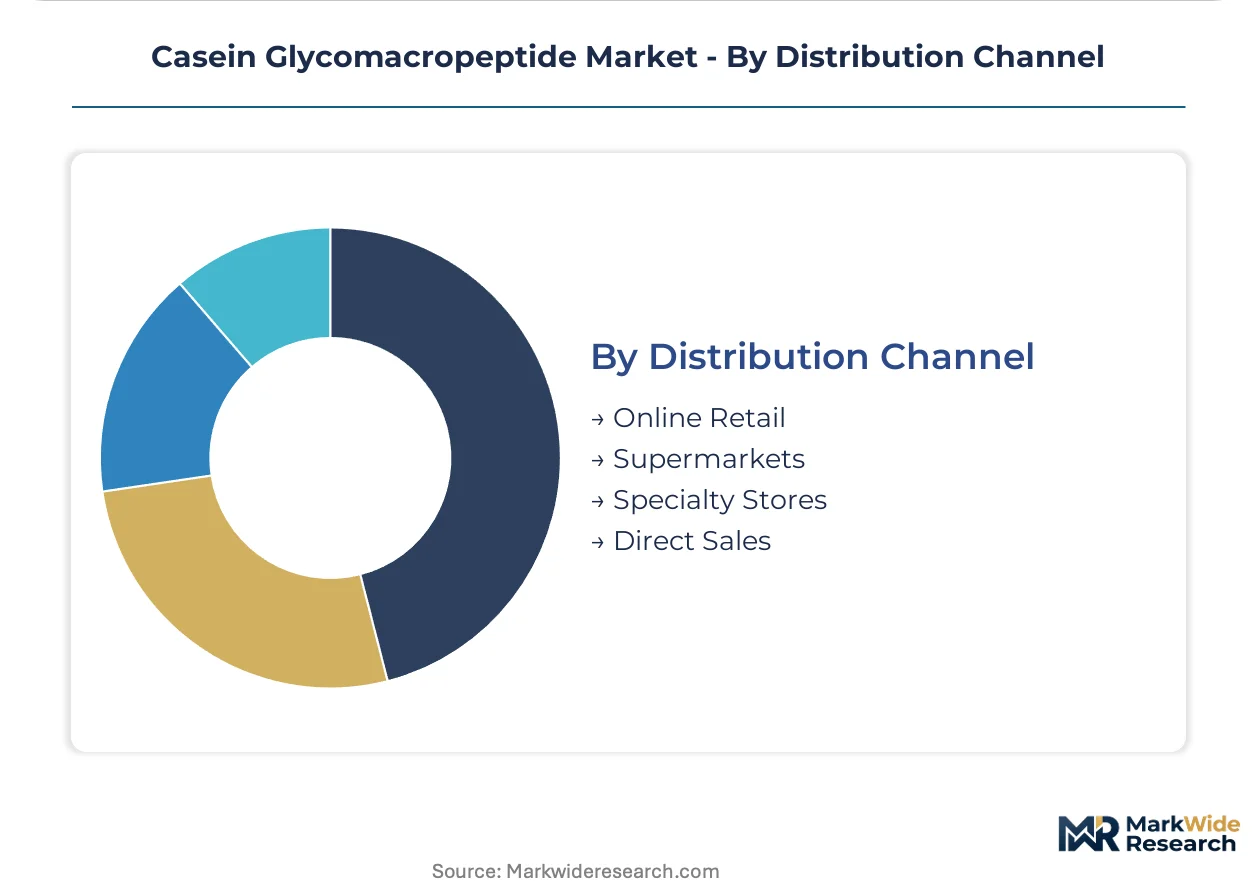
Channel selection reflects product format stability requirements and end-user purchasing behavior fragmentation across B2B and B2C pathways.
- Direct Sales:Long-term supply agreements between fractionation operators and formulation houses bypass distributor markups for high-volume sports nutrition contract manufacturing. Scandinavian cooperative structures favor this channel for captive supply security.
- Specialty Stores:Curated peptide assortments target educated consumers seeking novel food status verification and clinical substantiation transparency.
- Online Retail:E-commerce platforms enable subscription models and direct brand relationships for specialized bioactive ingredients.
- Supermarkets:Mass-market penetration remains limited due to peptide-specific labeling complexity and premium positioning requirements.
Relationship-based volume sits with Direct Sales. Digital experimentation is concentrated in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian milk pools anchor raw material access for enzymatic glycomacropeptide recovery, while German manufacturing corridors concentrate downstream formulation demand. National regulatory frameworks and industrial clustering patterns create distinct competitive terrain across major producing and consuming markets.
Germany
Infant formula manufacturers in Munich and Cologne drive concentrate procurement for digestive comfort applications. EFSA novel food authorization requirements under EU Regulation 2015/2283 impose purity documentation burdens on imported feedstock. The North Rhine-Westphalia dairy processing belt hosts captive fractionation investments bypassing third-country authorization delays.
United States
Sports nutrition brands in Utah and California pull through sialic acid-enriched concentrates for endurance athlete recovery protocols. FDA GRAS self-affirmation pathways govern market access for peptide ingredients in dietary supplements and infant formula. The Wisconsin-Idaho cheese manufacturing corridor generates whey feedstock for domestic enzymatic separation capacity.
Netherlands
FrieslandCampina's cooperative milk supply structure enables backward integration into chromatographic purification feedstock. EU F-Gas Regulation compliance requirements shape refrigeration-dependent ultrafiltration economics for Dutch processors. The Central Netherlands dairy cluster concentrates enzymatic fractionation capacity serving Benelux medical nutrition formulators.
Ireland
Contract manufacturing demand from UK sports nutrition brands drives liquid concentrate adoption for ready-to-drink applications. Irish dairy hygiene regulations align with EU baseline standards while offering streamlined enforcement for integrated processors. The Munster cheese manufacturing region supplies whey streams for glycomacropeptide recovery operations.
Denmark
Arla Foods Ingredients leverages cooperative milk pool access to secure raw material for Scandinavian export markets. Danish veterinary and food administration oversight coordinates with EFSA on novel food dossier preparation for peptide-specific health claims. The Jutland dairy processing belt concentrates enzymatic separation expertise serving German and French nutraceutical formulators.
Casein Glycomacropeptide Market Competitive Environment
Capacity expansion dominates the current landscape as integrated dairy processors defend margin positions against commodity protein volatility. The vendor base concentrates among cooperative-affiliated ingredient specialists and independent fractionation operators with captive milk supply. Three archetypes define competitive positioning: backward-integrated cooperatives with raw material control, specialized ingredient houses with clinical trial infrastructure, and contract manufacturers with modular recovery systems. M&A activity and geographic expansion represent the dominant competitive moves as players secure regional formulation partnerships.
Among cooperative-integrated specialists, Arla Foods Ingredients and FrieslandCampina exemplify the backward-integration archetype securing feedstock through member milk pools. Glanbia Nutritionals occupies a position representing the specialized ingredient house model with dedicated sports nutrition verticals. These three anchors demonstrate how competitive positioning stratifies between raw material control and clinical substantiation capabilities.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Agropur Ingredients |
| Glanbia Nutritionals |
| FrieslandCampina |
| Saputo Inc. |
| Hilmar Ingredients |
| New Zealand Milk Products |
| Valio Ltd. |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
EFSA novel food dossier requirements for peptide-specific health claims are forcing formulators toward suppliers with completed authorizations, compressing procurement options and elevating premium-grade concentrate pricing against commodity alternatives. This certification-driven buyer consolidation reshapes supplier bargaining power across German nutraceutical corridors and Irish sports nutrition contract manufacturing.
Pricing Analysis
After-sales technical support and clinical substantiation documentation are bundled into premium-tier concentrate contracts while standard grades trade on spot-market terms. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized suppliers from merchant market operators and residual whey processors. Pricing pressure stems from fermentation-derived bioactive alternatives capturing share in appetite-modulation applications. Sports nutrition brands exhibit highest price sensitivity due to volume procurement and direct sourcing relationships, while infant formula manufacturers prioritize purity certification over unit cost.
Supply Chain Analysis
Chromatographic resin supply rests on Japanese and German specialty chemical producers, with sialic acid retention media concentrated among a handful of purification technology houses. Raw material feedstock draws from Scandinavian and Dutch cooperative milk pools, while ultrafiltration membrane systems source from US and Danish engineering specialists. Single-source vulnerability in high-purity resin supply creates bottleneck risk for non-integrated fractionation operators. Distribution runs through direct long-term agreements between dairy processors and formulation houses, bypassing traditional ingredient distributors in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated processors with captive milk supply and clinical trial infrastructure, as EFSA authorization costs and chromatographic purification capital requirements force smaller fractionation operators toward acquisition or exit.
For Market Incumbents: To counter fermentation-derived bioactive protein substitution, Arla Foods Ingredients and FrieslandCampina should deepen backward integration into Scandinavian and Dutch cooperative milk supply while accelerating novel food dossier completion for peptide-specific health claims. Capacity expansion in Germany's North Rhine-Westphalia processing belt secures proximity to infant formula demand clusters. For New Entrants and Emerging Players: Capture white-space opportunity in liquid concentrate ready-to-drink applications serving UK and Irish contract manufacturers, where modular membrane cascade systems lower entry capital requirements. Target fitness center direct-to-consumer channels with encapsulated precision-dose formats, leveraging subscription models to bypass established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors fractionation operators with existing EFSA novel food authorizations and modular production technology. Mid-cap dairy processors with incomplete clinical substantiation pipelines represent acquisition targets for consolidation plays. Watch EFSA peptide-specific health claim framework evolution as inflection signal for premium-grade ingredient demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization Completion | Secures premium positioning in German and French nutraceutical formulations against unauthorized competitors. |
| Modular Membrane Cascade Deployment | Enables mid-scale Irish and Dutch processors to enter glycomacropeptide recovery without greenfield construction. |
| Backward Integration into Cooperative Milk Supply | Reduces third-party feedstock dependency for Danish and Dutch integrated processors amid raw material concentration. |
| Clinical Trial Infrastructure Investment | Creates first-mover advantage for appetite-modulation and prebiotic health claim substantiation in regulated markets. |
| Direct Sales Channel Expansion | Displaces traditional distributors in UK and Scandinavian sports nutrition contract manufacturing relationships. |
Study Parameters
Multi-period observation of EFSA authorization timelines, enzymatic fractionation yield rates, and sports nutrition brand procurement patterns anchored the trend analysis, supplemented by interviews with dairy processing executives, fractionation technology specialists, infant formula regulatory affairs leads, and sports nutrition contract manufacturing procurement directors. Secondary validation drew from EFSA novel food register entries, EU dairy hygiene regulation filings, customs trade data for whey concentrate imports, and SEC filings of publicly traded ingredient houses. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Segment-weighting approaches applied differential growth assumptions to powder versus liquid concentrate formats, nutraceutical versus sports nutrition applications, and pharmaceutical company versus fitness center end-user channels across the analysis window. CAGRs were derived from trajectory fitting to historical authorization completion rates and capacity expansion announcements. Industry-specific forecast inputs incorporated chymosin-mediated separation yield improvements and EU F-Gas Regulation compliance cost projections for refrigeration-dependent ultrafiltration operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA health claim framework evolution, fermentation-derived protein substitution rates, and Scandinavian milk pool supply disruptions. Forecasts reflect documented assumptions regarding regulatory pathway timelines and enzymatic fractionation technology diffusion. A small set of triggers—peptide-specific authorization rejections, major cooperative supply restructurings, and breakthroughs in precision fermentation economics—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mussel Oil and Powder Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Tannin Market
Ingredients
Revivable Yeast Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Beetroot Powder Market
Ingredients
Agave Inulin Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Canola Meal Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Icing Shortening Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Asia-Pacific Carrageenan Market