
 North America Plant Protein Ingredients Market | 2026-2036
North America Plant Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plant Protein Ingredients Market Analytics
Premium isolate grades is bifurcating the competitive landscape as buyers separate performance nutrition from mass-market formulations. Cargill leverages its oilseed processing infrastructure to secure upstream pea and soy supply chains. Ingredion sustains formulation partnerships with beverage brands seeking clean-label protein fortification. Burcon NutraScience specializes in novel extraction technologies that improve solubility and reduce off-flavors in plant-derived isolates.
Plant protein ingredients comprise refined or fractionated proteins extracted from legumes, oilseeds, and cereal grains, typically achieving protein concentrations of 80-90% in isolate form through aqueous or dry-fractionation methods. These ingredients function as functional emulsifiers, gelling agents, and nutritional fortifiers across formulated foods, supplements, and alternative meat matrices. Pea protein isolates command the strongest margin pools due to allergen-free positioning and neutral flavor profiles that suit dairy alternatives. Soy protein concentrates retain the largest volume footprint despite flattening growth in mature beverage applications. Rice and hemp proteins represent the fastest-expanding niche as brands target amino acid complementarity and sustainability narratives in premium positioning.
FDA nutrition labeling rules and USDA National Organic Program standards directly influence ingredient sourcing transparency and clean-label claims across North American product lines. Health Canada and PMRA jointly regulate novel protein ingredient approvals and pesticide residue thresholds for imported oilseed and legume feedstocks entering Canadian manufacturing facilities. Stakeholders must monitor evolving protein content verification protocols and state-level labeling precedents that could reshape competitive access across provincial and federal jurisdictions.
Market Dynamics
FDA nutrition labeling revisions and USDA organic certification tightening are compressing formulation timelines while simultaneously opening premium positioning for verified-clean supply chains. Ingredient buyers now demand batch-level transparency that extends back to specific agricultural cooperatives and processing facilities.
Growth Catalysts
- Clean-label fortification:Beverage brands seeking protein enrichment without synthetic additives are driving aqueous extraction technology adoption across Midwest processing facilities.
- FDA labeling transparency mandates:Updated serving-size definitions and added-sugar disclosure rules are forcing reformulations that favor single-source protein isolates over blended concentrates.
- Sports nutrition pivot:Performance brands in California's food-tech corridor are replacing whey with pea and rice protein combinations to capture lactose-intolerant athlete segments.
Market Restraints
- Input cost volatility:Yellow pea and non-GMO soybean prices fluctuate with drought cycles across the Canadian prairies and upper Midwest, squeezing margin stability for isolate producers.
- Technical limitation:Off-flavor compounds in hemp and pumpkin proteins resist current enzymatic masking techniques, restricting application in neutral-flavor dairy alternatives.
- Regulatory friction:Health Canada and PMRA joint approvals for novel protein fractions create 18-24 month lag times that deter rapid product iteration.
Strategic Opportunities
- Underpenetrated pet nutrition:Premium companion animal brands in Texas and Florida represent untapped demand for allergen-free protein fortification in veterinary formulations.
- USDA climate-smart incentives:Conservation Reserve Program enhancements and Partnerships for Climate-Smart Commodities grants are subsidizing regenerative agriculture transitions for organic pea and lentil growers.
- Precision fermentation convergence:Hybrid ingredients combining plant protein scaffolds with fermentation-derived flavor precursors are opening clean-label meat analog applications previously closed to pure botanical isolates.
Industry Challenges
- Specialized extraction talent scarcity:Food engineers with wet-fractionation expertise command premium wages that mid-tier processors struggle to match against Cargill and Ingredion recruitment budgets.
- Organic certification timeline compression:USDA National Organic Program inspector availability bottlenecks are extending facility approval cycles from 90 to 180 days, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plant Protein Ingredients Market |
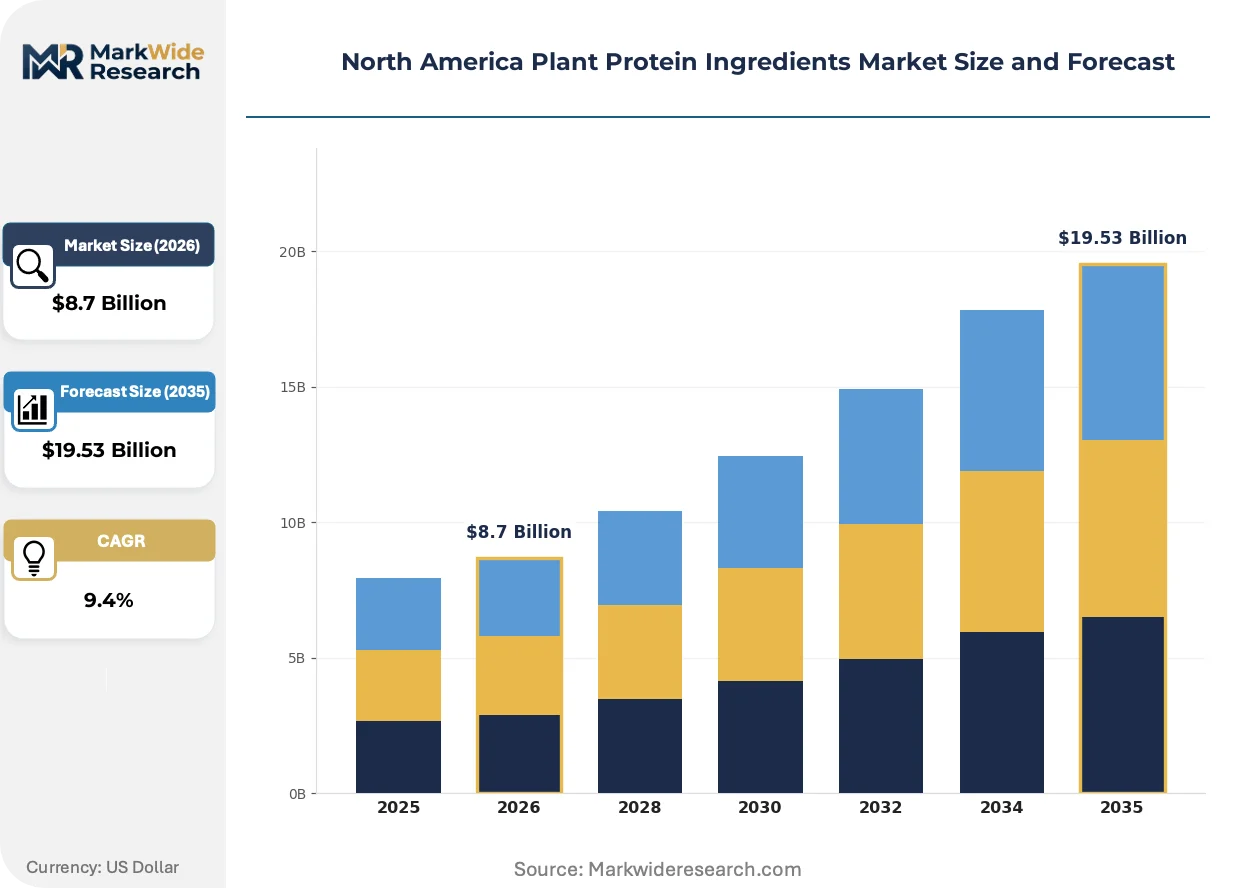
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein End Use: Food & Beverage, Dietary Supplements, Animal Feed, Personal Care Form: Concentrate, Isolate, Hydrolysate, Textured Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | International Flavors & Fragrances, Cargill, Archer Daniels Midland Company, The Scoular Company, Ingredion, Bunge Limited, Kerry Group, Burcon NutraScience, CHS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plant Protein Ingredients Market Evolving Landscape
Extraction technology advances are fragmenting the competitive landscape into performance-grade isolate specialists versus commodity concentrate suppliers. Simultaneously, regulatory verification protocols and procurement transparency requirements are reshaping how buyers evaluate supplier relationships.
Enzymatic debittering and membrane filtration integration is bifurcating the pea protein segment into premium isolates achieving 90%+ purity with neutral sensory profiles versus standard concentrates retaining 80% protein with detectable grassy notes. Sports nutrition and infant formula brands are migrating toward the premium tier, while mass-market bakery applications absorb the commodity surplus. This technical divide is compressing margins for mid-grade processors lacking capital to upgrade filtration infrastructure.
USDA National Organic Program enforcement actions against fraudulent import certifications are tightening traceability requirements for oilseed and legume feedstocks entering US manufacturing. The industrial consequence is mandatory blockchain or equivalent digital ledger adoption for organic supply chain documentation. Canadian facilities exporting to the United States are investing most heavily in compliance infrastructure, as cross-border shipments face heightened inspection protocols at Detroit and Buffalo ports of entry.
Direct-procurement relationships between CPG brands and agricultural cooperatives are displacing traditional ingredient distributor intermediaries in volume contracting. Large buyers in California and the Pacific Northwest now negotiate multi-year offtake agreements directly with Saskatchewan pulse growers and North Dakota soybean cooperatives. This channel compression is most visible in organic and non-GMO segments where identity preservation commands 15-20% price premiums and batch segregation requires specialized handling infrastructure.
North America Plant Protein Ingredients Market Segmentation
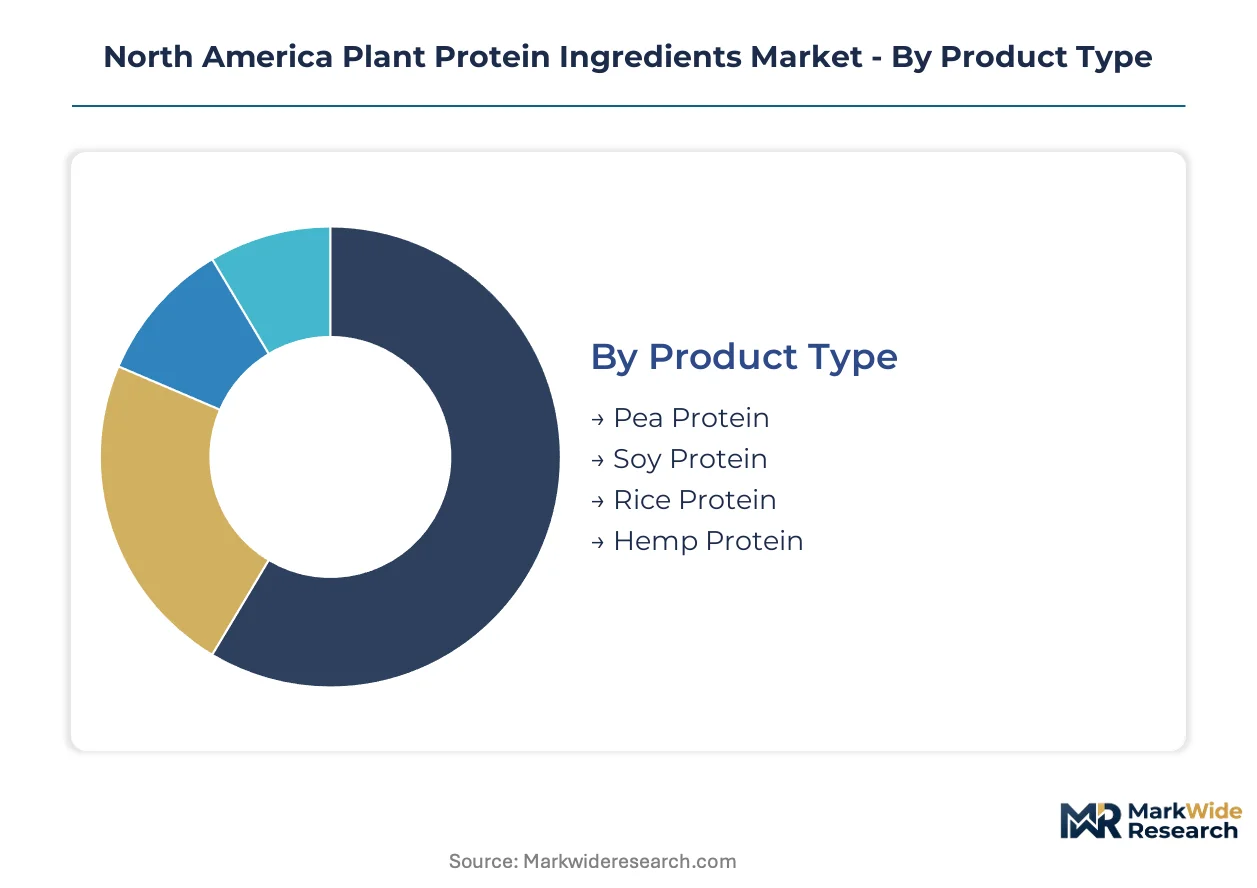
Ingredient buyers in North America segment plant proteins by functional performance, regulatory compliance burden, and supply chain traceability requirements. Substitution dynamics vary sharply across these dimensions, with some categories facing imminent displacement from precision fermentation alternatives while others deepen their moats through clean-label positioning.
Product Type:
Pea protein faces the most intense substitution pressure from emerging fermentation-derived alternatives, while soy protein confronts stagnation in legacy beverage applications and hemp protein battles persistent off-flavor technical barriers.
- Pea Protein:Isolate grades achieve 80-90% protein concentration through aqueous fractionation, delivering allergen-free positioning that commands 15-20% price premiums in California's dairy alternative corridor. Sports nutrition brands in the Pacific Northwest are consolidating procurement around specific Saskatchewan agricultural cooperatives to secure identity-preserved supply.
- Soy Protein:Concentrates and isolates retain the largest installed processing capacity across Midwest oilseed crushing infrastructure. Flattening demand in mature soy milk applications is redirecting volume toward textured grades for meat analog formulations in Texas and Illinois manufacturing facilities.
- Rice Protein:Hypoallergenic positioning and amino acid complementarity with pea protein are driving adoption in premium infant formula and clinical nutrition segments.
- Hemp Protein:Sustainability narratives and omega fatty acid content attract wellness brands, though grassy off-flavors restrict penetration in neutral-flavor dairy alternatives.
Soy protein anchors the volume base while pea protein gains share at the steepest rate.
End Use:
Application segments diverge by formulation complexity, with beverage fortification demanding the highest solubility specifications and pet nutrition presenting the lowest barrier to entry for new suppliers.
- Food & Beverage:Dairy alternatives, meat analogs, and bakery fortification require emulsification stability and neutral sensory profiles that favor pea and soy isolates. FDA labeling transparency mandates are forcing single-source protein declarations that disadvantage blended concentrates.
- Dietary Supplements:Sports nutrition powders and ready-to-drink formulations in California's food-tech corridor are replacing whey with plant-based combinations to capture lactose-intolerant athlete demand. Clean-label positioning requires aqueous extraction without hexane or synthetic additives.
- Animal Feed:Premium companion animal brands in Texas and Florida represent expanding demand for allergen-free protein fortification in veterinary formulations.
- Personal Care:Cosmetic applications leverage plant proteins for film-forming and conditioning properties in hair and skin products.
Food and beverage anchors the volume base while animal feed expands most quickly from a low penetration base.
Form:
Processing intensity creates three distinct cost tiers, with hydrolysates commanding the steepest premiums for pre-digested amino acid availability and textured forms requiring specialized extrusion infrastructure.
- Concentrate:70-80% protein content achieved through dry fractionation, serving mass-market bakery and cost-sensitive meat analog applications where functional performance tolerates lower purity.
- Isolate:90%+ protein purity through wet fractionation and membrane filtration, commanding premium positioning in sports nutrition and infant formula where solubility and sensory neutrality are non-negotiable.
- Hydrolysate:Enzymatically pre-digested proteins for rapid amino acid absorption in clinical nutrition and elite sports applications.
- Textured:Extruded protein structures mimicking muscle fiber organization for meat analog applications requiring chew and bite resistance.
Concentrate anchors the volume base while isolate climbs the fastest on premiumization trends.
Distribution Channel:
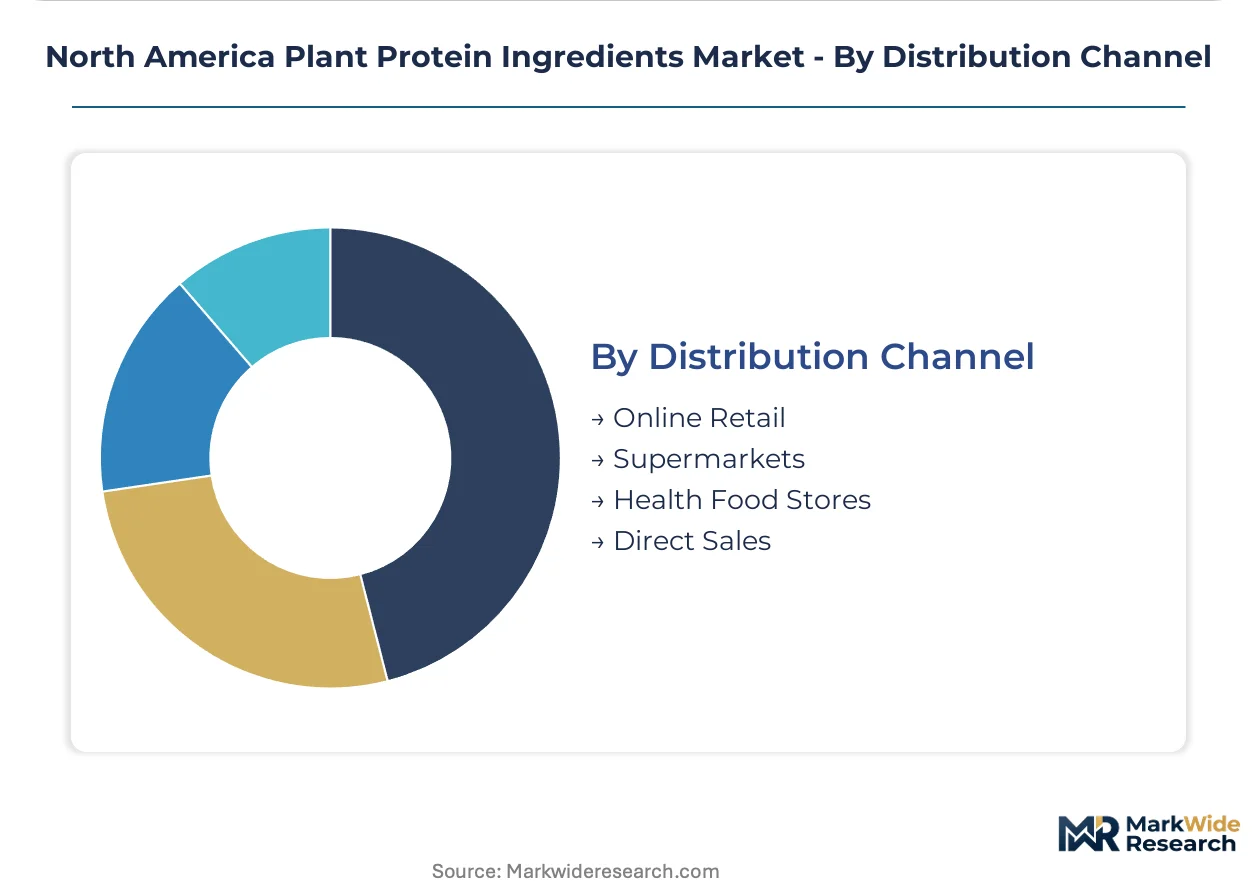
Channel structure reflects buyer scale and certification requirements, with direct procurement displacing intermediaries in organic and non-GMO segments where batch segregation demands specialized handling.
- Online Retail:E-commerce platforms serve small-scale buyers and specialty brands seeking rapid sampling and low minimum order quantities, particularly in hemp and rice protein niches.
- Supermarkets:Mass-market retail channels drive volume for commodity concentrates in conventional food and beverage applications.
- Health Food Stores:Specialty retail supports premium isolate grades with organic and non-GMO certifications targeting clean-label consumers.
- Direct Sales:Large CPG brands negotiate multi-year offtake agreements directly with Saskatchewan pulse growers and North Dakota soybean cooperatives, bypassing traditional distributors.
Supermarkets anchor the volume base while direct sales gains share fastest as procurement consolidates among large buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in California's food-tech corridor accept 15-20% price premiums for identity-preserved organic isolates, while mass-market processors in the Midwest agricultural belt prioritize cost-minimizing concentrate grades. This elasticity divide shapes procurement patterns across North American jurisdictions.
United States
Sports nutrition brands in California and the Pacific Northwest drive premium isolate demand through direct offtake agreements with Saskatchewan pulse growers. FDA nutrition labeling revisions and USDA National Organic Program enforcement actions are tightening traceability requirements for cross-border shipments. Midwest oilseed crushing infrastructure in Illinois and Minnesota anchors soy protein concentrate production for cost-sensitive meat analog applications.
Canada
Prairie province agricultural cooperatives in Saskatchewan and Manitoba supply identity-preserved yellow pea feedstocks to US isolate processors. Health Canada and PMRA joint approval protocols for novel protein fractions create 18-24 month regulatory lag times that deter rapid product iteration. Cross-border processing facilities near Detroit and Buffalo ports face heightened USDA inspection protocols for organic certification documentation.
Mexico
Emerging demand from beverage fortification and bakery applications in Mexico City Metro drives concentrate imports from US Midwest processors. Mexican federal food safety regulations align with FDA guidelines for imported protein ingredients, streamlining cross-border supply chains. Northern border states concentrate distribution infrastructure serving maquiladora operations producing export-oriented food products.
North America Plant Protein Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American plant protein ingredients market. The vendor base separates into multinational agribusiness conglomerates with captive oilseed processing infrastructure, mid-tier specialists in novel extraction technologies, and regional distributors serving niche organic and non-GMO segments. Dominant competitive moves include backward integration into agricultural cooperatives for identity-preserved supply chains and strategic partnerships with beverage brands seeking clean-label formulation support.
Within the multinational agribusiness tier, Cargill and Archer Daniels Midland Company exemplify scale-driven positions anchored in Midwest oilseed crushing and fractionation infrastructure. Ingredion occupies a specialist position in formulation partnerships with CPG brands, while Burcon NutraScience represents the technology-focused archetype developing novel extraction methods. These three companies illustrate the competitive spectrum from commodity volume leadership through premium isolate specialization.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Cargill |
| Archer Daniels Midland Company |
| The Scoular Company |
| Ingredion |
| Bunge Limited |
| Kerry Group |
| Burcon NutraScience |
| CHS Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day organic certification inspection backlogs at USDA-accredited facilities compress supplier liquidity while amplifying price premiums for identity-preserved isolates. This inventory friction concentrates pricing power among processors with captive Saskatchewan pulse supply and multi-year offtake contracts with California beverage brands.
Pricing Analysis
After-sales formulation support contracts with CPG brands drive lifetime value beyond commodity protein sales. Three-tier pricing structure across premium isolate, standard concentrate, and economy feed-grade levels stratifies the market. Pricing pressure stems from drought-driven yellow pea cost volatility across the Canadian prairies. Mass-market bakery buyers exhibit highest price sensitivity, while infant formula brands accept steep premiums for allergen-free certification.
Supply Chain Analysis
Sixty-day cross-border documentation delays at Detroit and Buffalo ports strain organic inventory buffers for Canadian exporters. Supply concentrates in Saskatchewan yellow pea, North Dakota non-GMO soybean, and Manitoba hemp seed. Processing draws from aqueous fractionation equipment, membrane filtration systems, and enzymatic debittering capacity. Single-source vulnerability persists in wet-fractionation engineering talent pools. Distribution runs through direct procurement relationships displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized food engineers with wet-fractionation expertise command wage premiums that fragment competitive capability across processor tiers. This talent scarcity constrains rapid capacity scaling and compresses margins for mid-tier facilities competing against multinational recruitment budgets.
For Market Incumbents: Shield margin pools by securing multi-year offtake agreements with Saskatchewan agricultural cooperatives before drought cycles tighten feedstock availability. Accelerate backward integration into regenerative organic acreage through USDA Partnerships for Climate-Smart Commodities grants. Invest in enzymatic masking R&D to neutralize hemp and pumpkin protein off-flavors before precision fermentation alternatives capture clean-label meat analog share. For New Entrants and Emerging Players: USDA National Organic Program inspector fast-tracks through accredited third-party certifiers open channel entry for premium isolate positioning. Target Texas and Florida pet nutrition brands seeking allergen-free protein fortification in veterinary formulations. Lead with aqueous extraction technology partnerships that bypass hexane-dependent infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core protein fractionation assets amid portfolio rationalization. Five-to-ten year viability hinges on extraction technology moats and captive organic supply chain control. Monitor Health Canada and PMRA joint approval timelines as inflection signals for novel protein fraction commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captures USDA climate-smart subsidies while securing identity-preserved supply for California dairy alternative brands. |
| Enzymatic Debittering Technology Licensing | Opens neutral-flavor applications for hemp protein in premium beverage formulations previously closed to botanical isolates. |
| Direct Procurement Platform Development | Displaces traditional distributors by connecting CPG brands with Saskatchewan pulse cooperatives through blockchain traceability. |
| Precision Fermentation Hybrid Partnership | Combines plant protein scaffolds with fermentation-derived flavor precursors for clean-label meat analog applications. |
| Wet-Fractionation Talent Acquisition | Secures scarce food engineering expertise that determines isolate purity thresholds and membrane filtration yield rates. |
Research Methodology
A standing panel of extraction technology directors, organic certification auditors, CPG procurement leads, and agricultural cooperative managers provided ongoing calibration across the research window. Primary fieldwork combined structured interviews with secondary validation against USDA National Organic Program enforcement records, FDA nutrition labeling guidance documents, Health Canada novel food approval databases, and Saskatchewan agricultural export statistics. Bottom-up volume modeling from processor capacity utilization and top-down demand triangulation from CPG formulation pipelines converged on segment-level estimates.
Consistency checks against customs data for yellow pea and non-GMO soybean cross-border flows validated volume assumptions across the analysis window. The analytical framework modeled protein type, end-use application, form grade, and distribution channel dimensions. CAGRs derived from processor expansion announcements, agricultural acreage shifts, and CPG brand plant-based portfolio commitments. Forecast inputs included drought frequency projections for the Canadian prairies and FDA labeling rule implementation timelines.
Underlying assumptions cover stable regulatory enforcement intensity, with deviation risk concentrated in Health Canada approval delays and organic certification inspector availability. Commodity price volatility and precision fermentation substitution velocity represent additional revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Agave Inulin Market
Ingredients
Vegetable Extract Market
Ingredients
Potato Flour Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Baking Ingredients Market
Ingredients
Pea Peptones Market
Ingredients
Stock Cubes Market
Ingredients
Hen Egg White Protein Market
Ingredients
Corn Gluten Meal Market
Ingredients
Tapioca Pearls Market
Ingredients
Hops Derivative Market
Ingredients
Europe Gelatin Market
Ingredients
Commercial Flour Market
Ingredients
Non-GMO Oil Market