
 North America Fruit and Vegetable Ingredients Market | 2026-2036
North America Fruit and Vegetable Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fruit and Vegetable Ingredients Market Analytics
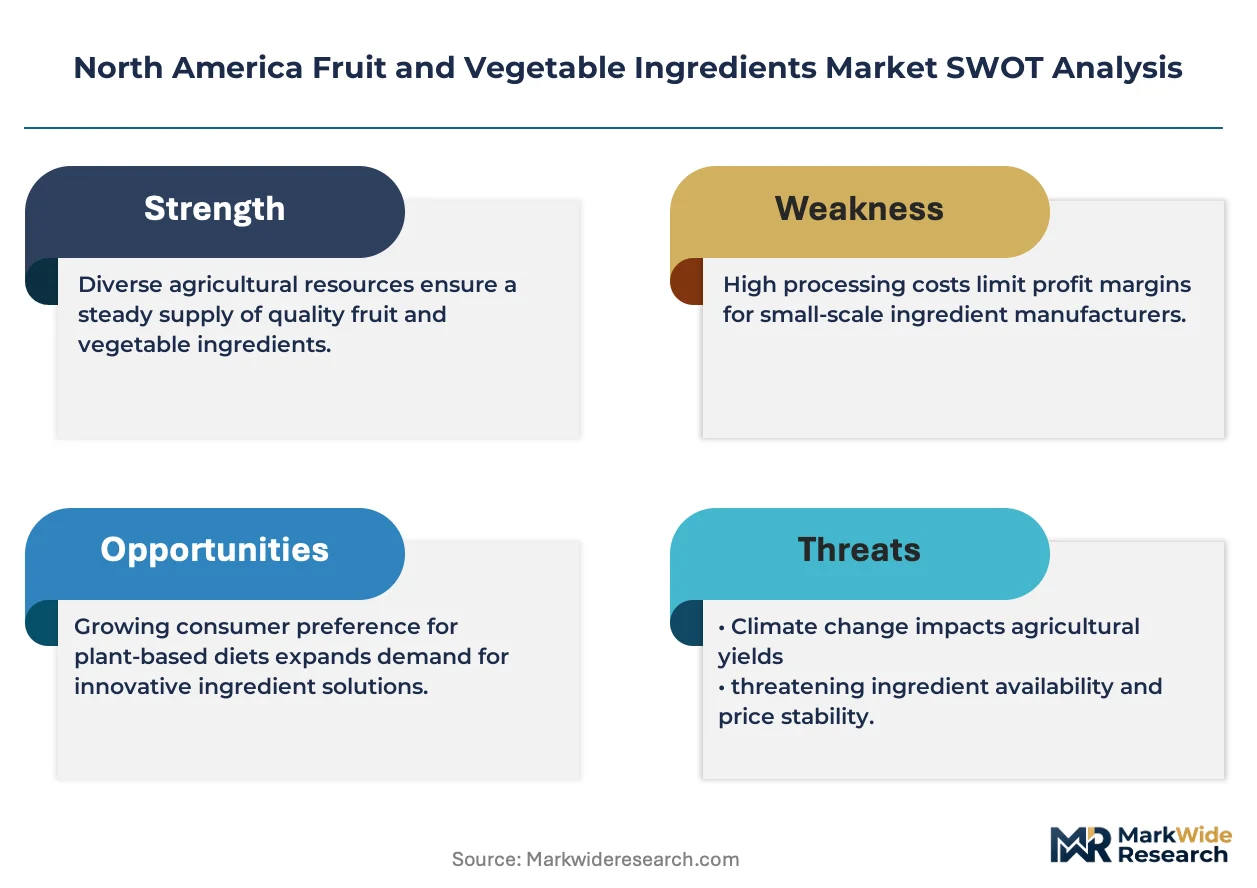
Asset-light toll processing and third-party contract manufacturing is reconfiguring capital deployment across the competitive landscape. SunOpta Inc leverages its vertically controlled organic supply chain to anchor premium positioning in North American retail channels. Ingredion Incorporated competes through deep R&D integration with beverage formulation labs, while Cargill Incorporated dominates agricultural origination and processing scale across the US Midwest and Canadian Prairie provinces.
North America fruit and vegetable ingredients encompass minimally processed plant-derived materials—typically standardized to Brix values, pH ranges, and microbiological specifications—that serve as flavor carriers, colorants, texturizers, and nutritional fortifiers in downstream food manufacturing. Production involves washing, sorting, thermal treatment, and concentration or dehydration to achieve shelf-stable formats with controlled water activity and preserved bioactive compound profiles. Purees and concentrates command the largest volume positions due to their integration into infant nutrition and smoothie applications, while dried products capture premium margin pools from snacking and bakery segments where low-moisture stability reduces logistics costs. Powdered formats are gaining share in sports nutrition and plant-based dairy alternatives where dispersibility and clean-label positioning drive reformulation.
The FDA enforces Food Safety Modernization Act preventive controls for human food, directly elevating hazard analysis and supplier verification requirements across the ingredient supply base. USDA National Organic Program standards and Health Canada's Safe Food for Canadians Regulations create parallel certification tracks that filter market access and shape procurement qualification criteria. Stakeholders must monitor evolving EPA pesticide tolerance revisions and state-level prop 65 litigation trends in California that threaten to disqualify conventional sourcing channels and redirect volume toward integrated organic supply networks.
Market Dynamics
Clean-label procurement mandates from beverage manufacturers are compressing formulation timelines and forcing ingredient suppliers to pre-certify organic and non-GMO credentials before contract execution.
Growth Catalysts
- USDA Organic Certification:Retail channel gatekeeping by mass-market grocers now requires organic ingredient documentation for shelf placement, accelerating supplier qualification investments.
- Beverage Sector Reformulation:Smoothie and ready-to-drink juice brands are specifying single-source fruit purees with traceable provenance to support front-of-package claims.
- California Central Valley Processing:Thermal concentration infrastructure clustering around Fresno and Modesto is reducing logistics costs for West Coast beverage manufacturers.
Market Restraints
- Input Cost Volatility:Water stress in California's agricultural regions is compressing fruit yields and amplifying seasonal price swings for strawberry and peach concentrates.
- Supply Concentration Risk:Mexico's Guadalajara concentrate belt handles a disproportionate share of tropical fruit processing, creating single-point vulnerability for mango and pineapple supply.
- Regulatory Friction:California Proposition 65 litigation over heavy metal content in natural ingredients is forcing costly testing protocols that conventional suppliers struggle to absorb.
Strategic Opportunities
- Plant-Based Dairy Alternatives:Oat and almond milk formulators are specifying vegetable-based colorants and flavor carriers to replace synthetic additives, opening new volume channels.
- Infant Nutrition Premiumization:First-stage baby food manufacturers are sourcing single-variety vegetable purees with documented micronutrient retention through low-temperature processing.
- Health Canada Organic Equivalency:Harmonized US-Canada organic certification is reducing border documentation burden and enabling unified North American procurement contracts.
Industry Challenges
- Microbiological Validation Timelines:FDA Food Safety Modernization Act preventive control documentation is extending batch release cycles from days to weeks for small-batch processors.
- Legacy Equipment Retrofit Costs:Thermal processing lines built for conventional concentrates require capital-intensive reconfiguration to handle organic certification segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fruit and Vegetable Ingredients Market |
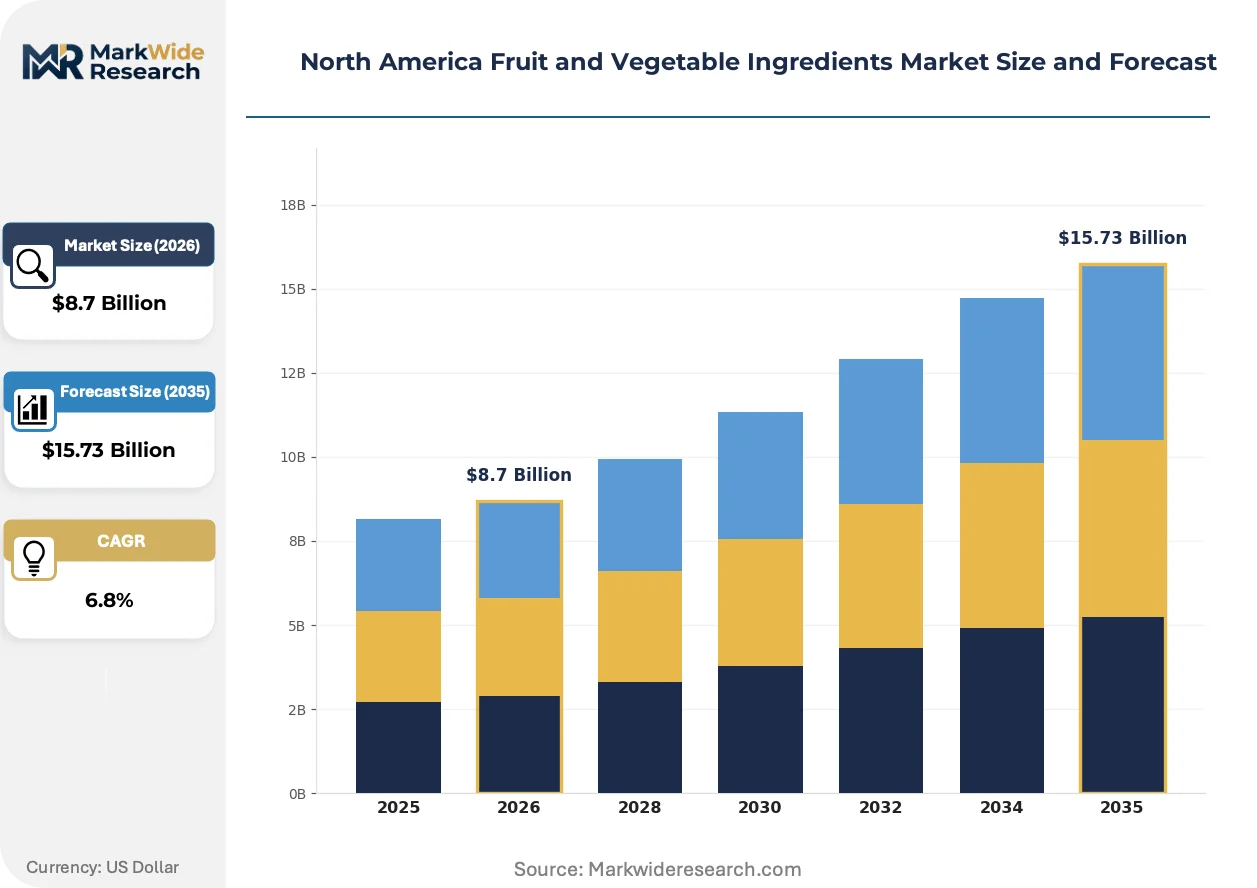
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Juices, Concentrates, Dried Products End User: Food & Beverage, Bakery, Dairy, Confectionery Form: Liquid, Powder, Frozen, Canned Application: Flavoring, Coloring, Nutritional Enhancement, Ingredient Replacement |
| Companies Covered | Ingredion Incorporated, SVZ International B V, SunOpta Inc, AGRANA Beteiligungs-AG, Döhler GmbH, Archer Daniels Midland Company, Sensient Technologies Corporation, Tate & Lyle, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fruit and Vegetable Ingredients Market Evolving Landscape
High-pressure processing and pulsed electric field technologies are displacing conventional thermal concentration, preserving heat-sensitive bioactives while meeting clean-label positioning requirements.
Cold-pressed extraction technology is collapsing the traditional trade-off between shelf stability and nutrient retention. Beverage formulators in the sports nutrition segment are specifying high-pressure processed fruit bases with verified polyphenol content. This compression of the stability-nutrition frontier is enabling refrigerated distribution models that bypass frozen concentrate logistics entirely.
FDA updated Nutrition Facts labeling rules are mandating added sugar disclosure that captures naturally occurring sugars in fruit concentrates. Infant nutrition and snack bar manufacturers are reformulating with whole fruit powders and reduced-Brix purees to manage label claims. The compliance burden falls heaviest on mid-sized suppliers lacking in-house regulatory affairs capacity.
Direct-procurement contracts between ingredient suppliers and retail private-label programs are disintermediating traditional broker networks. Mass-market retailers in the US and Canada are specifying origin-verified supply chains with blockchain documentation. This channel restructuring concentrates volume with vertically integrated processors capable of farm-to-facility traceability.
North America Fruit and Vegetable Ingredients Market Segmentation
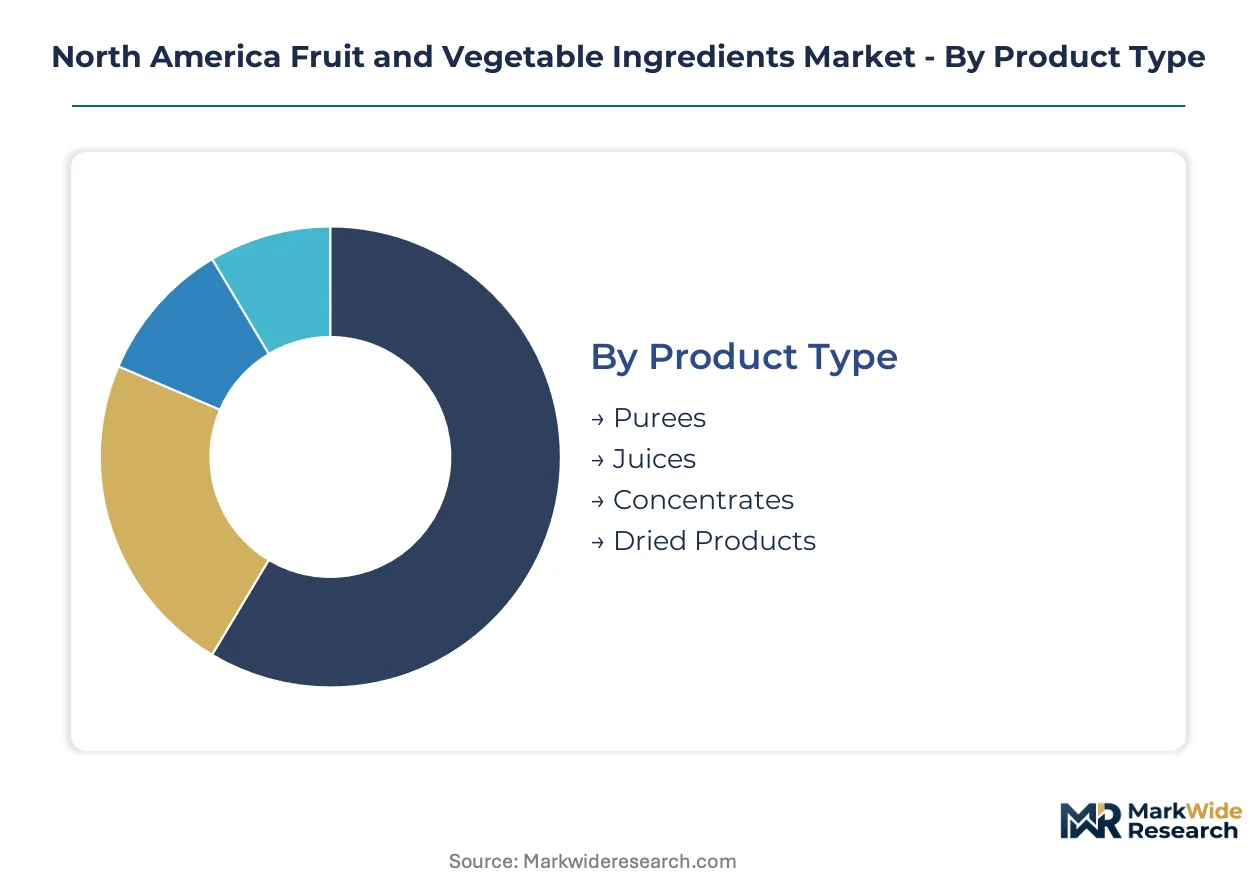
Ingredient buyers in North America specify fruit and vegetable inputs through multiple technical lenses simultaneously. Product type determines processing economics and shelf stability. End user requirements dictate certification thresholds and microbiological specifications. Form and application dimensions govern logistics configuration and reformulation complexity.
Product Type:
After-sales technical support intensity varies sharply across product categories, with concentrates and purees requiring sustained formulation partnership from supplier technical service teams.
- Concentrates:Thermally reduced fruit or vegetable extracts standardized to specific Brix values, typically 28-70 degrees Brix for beverage applications. California Central Valley processors supply West Coast smoothie manufacturers who demand rapid batch troubleshooting and on-site viscosity adjustment support. Water stress in Fresno County orchards is compressing seasonal availability windows.
- Purees:Finely comminuted fruit or vegetable pulp retaining fiber and particulate structure, processed through screening and homogenization. Infant nutrition manufacturers in Vermont and Quebec specify single-variety vegetable purees with documented micronutrient retention, requiring supplier investment in low-temperature processing validation and extended shelf-life studies.
- Juices:Single-strength or minimally concentrated liquid extracts filtered to specific clarity standards. Cold-pressed extraction lines serving sports nutrition brands demand refrigerated distribution partnerships.
- Dried Products:Dehydrated fruit or vegetable pieces, powders, or flakes with controlled water activity below 0.6. Snack bar manufacturers in the Pacific Northwest source low-moisture strawberry pieces for logistics cost reduction.
By volume, concentrates lead procurement contracts across North American beverage manufacturing. By growth pace, purees are climbing the fastest as infant nutrition brands premiumize ingredient provenance.
End User:
Cost tier stratification separates premium organic-certified supply from conventional commodity channels, with dairy and confectionery segments occupying opposite ends of the price-quality spectrum.
- Food & Beverage:Ready-to-drink juice and smoothie brands specifying traceable single-source fruit bases with blockchain documentation. Mass-market retailers are disintermediating broker networks through direct procurement contracts that demand farm-to-facility verification systems.
- Dairy:Plant-based milk formulators replacing synthetic additives with vegetable-derived colorants and flavor carriers. Oat and almond milk manufacturers in the Midwest are driving volume for neutral-colored vegetable concentrates that maintain clean-label positioning.
- Bakery:Commercial bakeries integrating dried fruit pieces and vegetable powders for moisture management and natural sweetness. Reduced-Brix purees help manage added sugar disclosure compliance under FDA updated Nutrition Facts rules.
- Confectionery:Candy manufacturers utilizing fruit juices and concentrated extracts for flavoring and acidulant functions. Mexican Guadalajara processors supply tropical fruit concentrates for gummy and hard candy applications.
Food and beverage channels command the largest procurement volumes. Dairy alternatives are expanding most quickly as plant-based formulation accelerates.
Form:
Customer type segmentation separates industrial-scale manufacturers with frozen storage infrastructure from emerging brands requiring ambient-stable powder formats for contract manufacturing flexibility.
- Liquid:Single-strength or reconstituted concentrates in aseptic or frozen distribution. Beverage toll processors in Texas and Ontario prefer liquid formats for rapid batch integration without hydration steps.
- Powder:Spray-dried or drum-dried fruit and vegetable extracts with specified dispersibility and particle size distribution. Sports nutrition brands specify high-dispersibility powders for instant beverage applications.
- Frozen:Blast-frozen purees and concentrates at -18°C for extended microbiological stability. California Central Valley cold storage infrastructure supports just-in-time delivery to West Coast manufacturing.
- Canned:Thermally processed and hermetically sealed products for ambient distribution. Smaller bakery operations without frozen storage capacity rely on canned formats for inventory flexibility.
Frozen formats dominate volume in beverage manufacturing corridors. Powders are gaining share fastest in sports nutrition and plant-based dairy segments.
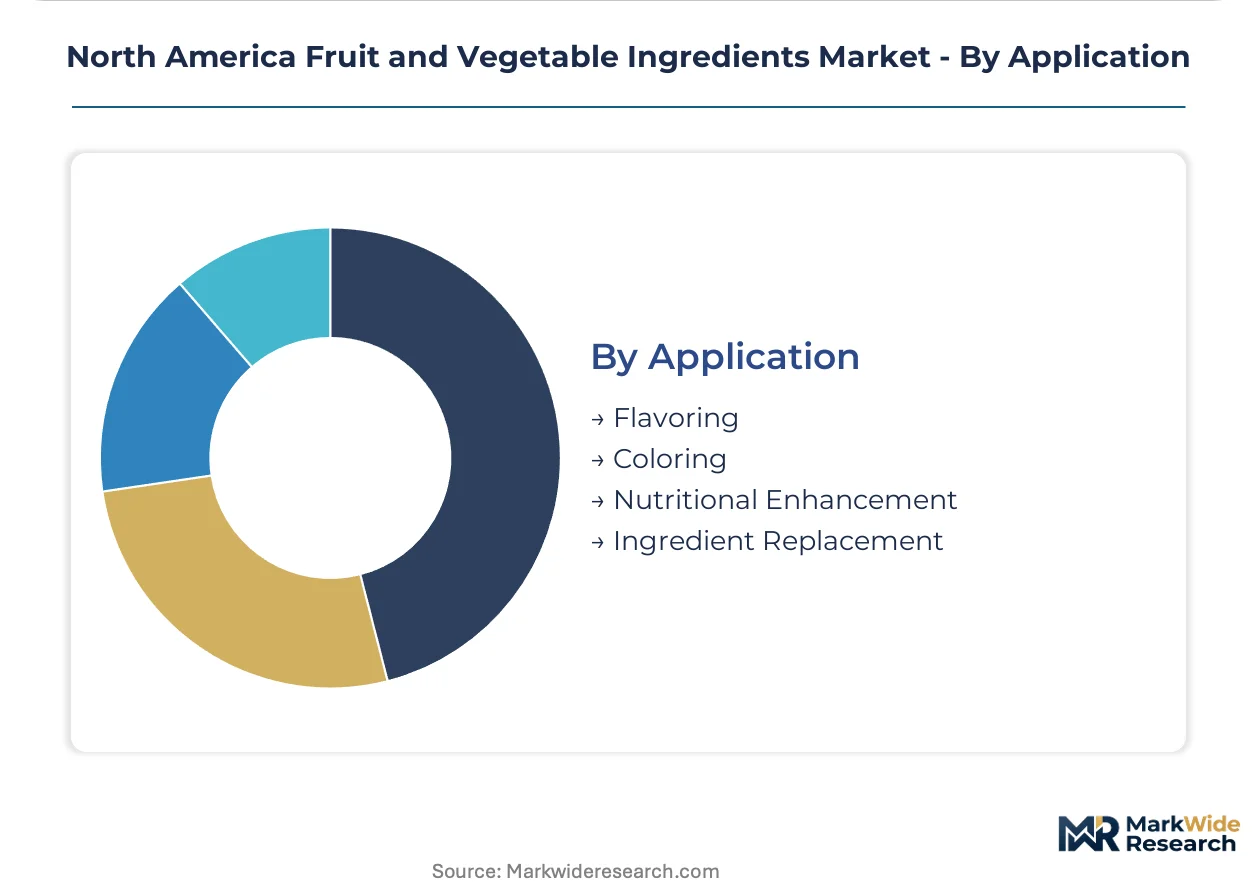
Application:
Supply concentration in California and Mexico shapes application-specific procurement, with flavoring and coloring functions drawing from distinct processing clusters and technical capabilities.
- Flavoring:Concentrated taste-active compounds and aromatic volatiles from specific fruit varieties. Guadalajara processors supply tropical fruit flavor bases for North American beverage brands seeking mango and pineapple profiles.
- Coloring:Pigment-rich extracts from beets, carrots, berries, and other chromogenic sources. Beet-derived betalains and carrot carotenoids replace synthetic dyes in clean-label confectionery.
- Nutritional Enhancement:Bioactive-fortified ingredients with verified polyphenol, vitamin, or fiber content. High-pressure processing preserves heat-sensitive compounds for sports nutrition positioning.
- Ingredient Replacement:Fruit and vegetable inputs substituting for synthetic additives, sugar, or artificial flavors. Reduced-Brix purees and whole fruit powders help infant nutrition manufacturers manage added sugar disclosure requirements.
Flavoring applications lead procurement volume across beverage manufacturing. Nutritional enhancement is advancing most quickly as bioactive verification becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage formulators and infant nutrition manufacturers concentrate procurement decisions in three distinct North American corridors. Each sub-region offers differentiated processing capabilities, regulatory environments, and supply chain configurations that shape ingredient sourcing patterns.
United States
California's Central Valley hosts thermal concentration infrastructure around Fresno and Modesto that supplies West Coast smoothie manufacturers. FDA Food Safety Modernization Act preventive controls govern batch release documentation requirements. Water stress in Fresno County orchards compresses seasonal availability for strawberry and peach concentrates.
Canada
Quebec and Ontario infant nutrition manufacturers specify single-variety vegetable purees with documented micronutrient retention. Health Canada's Safe Food for Canadians Regulations create parallel certification tracks with USDA organic standards. Toronto-area toll processors manage cross-border logistics for unified North American procurement contracts.
Mexico
Guadalajara's concentrate belt processes disproportionate volumes of tropical fruit for North American confectionery and beverage applications. Mexican agricultural regulators enforce phytosanitary standards that align with USDA import requirements. Jalisco-based processors supply mango and pineapple flavor bases under direct-procurement contracts with US retail private-label programs.
Pacific Northwest
Oregon and Washington snack bar manufacturers source low-moisture dried strawberry pieces for logistics cost reduction. EPA pesticide tolerance revisions threaten to disqualify conventional sourcing channels in this region. Portland-area cold-pressed extraction lines serve sports nutrition brands demanding refrigerated distribution partnerships.
US Midwest
Illinois and Michigan plant-based dairy formulators specify vegetable-derived colorants for oat and almond milk applications. USDA National Organic Program standards filter market access for ingredient suppliers serving this corridor. Chicago-area beverage toll processors prefer liquid concentrate formats for rapid batch integration.
North America Fruit and Vegetable Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive positions. Vertically integrated processors with farm-to-facility traceability systems capture direct procurement contracts from mass-market retailers. Mid-scale toll processors and regional concentrate specialists occupy fragmented positions between these poles. Dominant competitive moves include backward integration into organic orchards and strategic partnerships with beverage formulation laboratories.
Among North American headquartered operators, Ingredion Incorporated and Cargill Incorporated exemplify scale-driven agricultural origination positions. SunOpta Inc represents the vertically controlled organic supply chain archetype. European-based specialists including Döhler GmbH and AGRANA Beteiligungs-AG occupy premium-tier positions through deep technical service capabilities in concentrate standardization and application-specific formulation support.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| SVZ International B V |
| SunOpta Inc |
| AGRANA Beteiligungs-AG |
| Döhler GmbH |
| Archer Daniels Midland Company |
| Sensient Technologies Corporation |
| Tate & Lyle |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Fresno County's thermal concentration corridor shapes ingredient pricing power through water-stressed strawberry and peach harvests that compress seasonal availability windows. California Central Valley processors leverage just-in-time cold storage infrastructure to command premium positioning for West Coast beverage manufacturers facing compressed formulation timelines.
Pricing Analysis
Cost-plus contracts with indexed agricultural commodity benchmarks dominate procurement between California processors and beverage manufacturers. Three-tier pricing structure across premium organic, standard conventional, and economy commodity grades separates suppliers by certification tier and traceability depth. Pricing pressure stems from FDA Food Safety Modernization Act compliance costs that small-batch processors struggle to absorb. Mid-sized toll manufacturers exhibit highest price sensitivity due to legacy equipment retrofit requirements for organic segregation protocols.
Supply Chain Analysis
USDA phytosanitary import controls and FDA preventive control documentation limit cross-border flow velocity between Mexico's Guadalajara concentrate belt and US beverage corridors. Supply concentrates in California's Central Valley and Jalisco province, with raw material dependencies on water-intensive strawberry, peach, mango, and pineapple harvests. Single-source vulnerability runs through Guadalajara's tropical fruit processing cluster for North American pineapple and mango concentrate. Distribution runs through direct-procurement contracts with mass-market retailers that disintermediate traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement fragmentation creates specialist opportunities as beverage manufacturers disaggregate volume across multiple origin-verified suppliers rather than consolidating with commodity giants.
For Market Incumbents: Entrench market position through backward integration into organic orchards in California's Central Valley to secure captive supply against water stress volatility. Deepen FDA preventive control documentation capabilities to extend batch release cycle advantages over mid-scale competitors. Prioritize blockchain traceability infrastructure investment to meet mass-market retailer direct-procurement qualification thresholds. For New Entrants and Emerging Players: Mid-market organic toll processors in the US Midwest represent the most penetrable entry point for plant-based dairy alternative ingredient supply. Cold-pressed extraction lines serving Pacific Northwest sports nutrition brands offer second white-space target with lower capital barriers than thermal concentration. Lead with high-pressure processing technology partnerships that bypass frozen concentrate logistics entirely. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct-procurement contract concentration favors vertically integrated processors with farm-to-facility traceability systems. Target acquisition archetype: mid-scale organic-certified toll processors with existing Health Canada equivalency documentation. Monitor California Proposition 65 litigation volume as inflection signal for accelerated conventional-to-organic supply channel switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Orchards | Captive supply secures margin protection against Fresno County water stress volatility. |
| High-Pressure Processing Technology Deployment | Cold-pressed extraction lines bypass frozen concentrate logistics for sports nutrition brands. |
| Blockchain Traceability Infrastructure | Farm-to-facility documentation meets mass-market retailer direct-procurement requirements. |
| Health Canada Organic Equivalency Certification | Unified North American procurement contracts reduce cross-border documentation burden. |
| Low-Temperature Processing Validation Investment | Micronutrient retention documentation captures infant nutrition premiumization demand. |
Research Methodology
Cross-validation between executive interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Primary fieldwork encompassed ingredient procurement directors at beverage manufacturers, technical service leads at concentrate processors, infant nutrition formulators in Quebec and Vermont, and FDA compliance officers. Secondary sources included USDA National Organic Program certification databases, FDA Food Safety Modernization Act guidance documents, Health Canada Safe Food for Canadians Regulations, California Proposition 65 litigation dockets, and EPA pesticide tolerance revision notices. Bottom-up volume modeling from processor capacity utilization rates triangulates against top-down demand estimates from end-use segment consumption patterns.
Calibration against historical price volatility in California agricultural commodities and Mexico import flow data refines projection accuracy across the analysis window. Segmentation dimensions encompass product type hierarchy, end-use industry verticals, form factor logistics configurations, application function categories, and geographic processing cluster proximity. CAGRs derive from weighted average growth assumptions across infant nutrition premiumization, plant-based dairy expansion, and clean-label beverage reformulation vectors. Water stress indices for Fresno County and phytosanitary inspection throughput at Laredo border crossings inform supply-side constraint modeling.
Practitioners should monitor California drought severity indices and FDA preventive control enforcement intensity for early signals of supply disruption or compliance cost inflation. Forecasts reflect assumptions regarding sustained clean-label procurement mandates and stable US-Mexico agricultural trade protocols. Material shifts in California water allocation policy or USDA organic certification equivalency agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vital Wheat Gluten Market
Ingredients
South America Clean Ingredients Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
MCT Oil Market
Ingredients
Edible Oils and Fats Market
Ingredients
Botanical Ingredients Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Marine Peptides Market
Ingredients
Volatile Fatty Acids Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Wheat Gluten Market
Ingredients
Chlorella Ingredients Market