
 Hexane-Free Protein Market | 2026-2036
Hexane-Free Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hexane-Free Protein Market Outlook
USDA Organic certification is collapsing the supplier base for hexane-free protein as brands race to meet dual organic and solvent-free claims. Cargill, Incorporated leverages its North American oilseed infrastructure to anchor volume supply for food-grade hexane-free soy isolates. Kerry Group Plc competes through flavor-masked pea protein systems that reduce bitterness in finished applications. Axiom Foods, Inc. specializes in allergen-free rice protein concentrates that serve the infant nutrition and clinical segments.
Hexane-free protein denotes protein isolates and concentrates extracted through mechanical pressing, aqueous processing, or enzyme-assisted methods that yield residual hexane levels below detection thresholds, typically serving formulations where solvent residues conflict with clean-label positioning or organic eligibility. Pea protein dominates current volume due to its functional gelation and emulsification properties in meat alternatives, though rice protein claims the fastest trajectory as hypoallergenic positioning expands beyond pediatric into adult sports nutrition. Within applications, meat alternatives capture the deepest margin pools as brands pay premiums for texturized concentrates that replicate muscle fiber structure, while protein bars remain a high-volume but price-compressed channel.
The FDA maintains zero tolerance for hexane residues in organic-labeled products under National Organic Program rules, while the EU Green Deal's chemical sustainability targets push member states toward solvent-free extraction mandates. Health Canada's PMRA monitors imported protein concentrates for solvent residues, creating compliance friction for non-certified suppliers. Stakeholders must track evolving organic equivalence agreements between regulatory regimes to anticipate which extraction methods will retain market access across jurisdictions.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing solvent tolerance thresholds across European supply chains, forcing ingredient processors to abandon hexane extraction methods or forfeit organic certification eligibility in the bloc's largest protein markets.
Growth Catalysts
- Clean-label mandates:Sports nutrition brands in Germany and France now require solvent-free documentation for all protein concentrates, creating pull-through demand for mechanical extraction capacity.
- REACH chemical restrictions:ECHA's tightening classification of n-hexane as a Substance of Very High Concern is accelerating facility upgrades toward aqueous processing systems.
- Pea protein functionality:Gelation properties in meat alternatives now match soy isolates, enabling formulators to switch without texture compromise.
Market Restraints
- Input cost volatility:Organic yellow pea premiums fluctuate with Canadian prairie weather patterns, squeezing margin stability for European processors.
- Supply concentration risk:Mechanical pressing capacity clusters in northern Germany and eastern France, creating single-point vulnerability for EU-compliant volume.
- Technical yield gaps:Aqueous extraction recovers 12-18% less protein per ton of raw material versus legacy hexane methods, inflating unit economics.
Strategic Opportunities
- Underpenetrated adult hypoallergenic:Rice protein positioning beyond pediatric nutrition into German fitness channels offers first-mover expansion space.
- EU organic equivalence agreements:Mutual recognition pacts with Swissmedic and third-country certifiers open export pathways for solvent-free concentrates.
- Enzyme-assisted processing:Convergence of protease engineering with membrane filtration is collapsing energy intensity in isolate production.
Industry Challenges
- Specialized engineering talent:Food-grade mechanical pressing requires operators trained in both oilseed processing and organic audit protocols, a skill combination scarce in eastern European labor pools.
- Certification timeline compression:USDA Organic and EU organic dual certification now demands 14-18 month validation cycles, delaying new supplier market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexane-Free Protein Market |
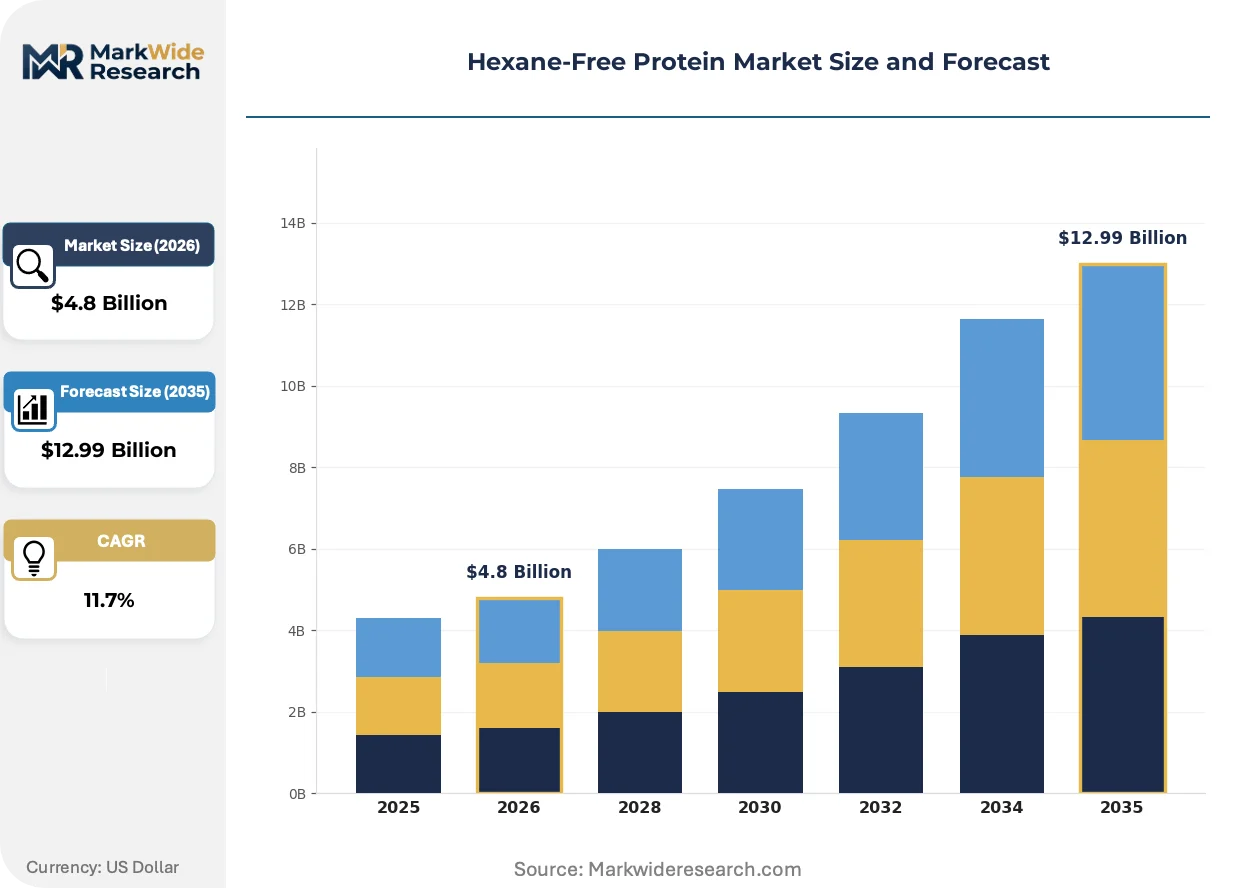
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Potato Protein End Use: Food & Beverage, Animal Feed, Nutraceuticals, Dietary Supplements Source: Plant-Based, Legumes, Grains, Others Application: Meat Alternatives, Protein Bars, Bakery Products, Smoothies |
| Companies Covered | Axiom Foods, Inc., Cargill, Incorporated, DuPont Nutrition & Health, Kerry Group Plc, Archer Daniels Midland Company, Wilmar International Ltd, Nutiva Inc., SunOpta Inc., Parabel USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexane-Free Protein Market Strategic Shifts
Extraction technology is bifurcating between capital-intensive enzyme systems and retrofitted mechanical presses, with regulatory pressure determining which pathway processors pursue. This divergence is reshaping supplier economics and buyer procurement criteria simultaneously.
Enzyme-assisted aqueous extraction is displacing legacy hexane-soy isolate production in North American organic supply chains. Meat alternative manufacturers in California and Illinois are adopting these concentrates at 40% volume premiums to secure clean-label positioning. The technology is displacing solvent-dependent capacity faster than rebuild timelines can accommodate, creating spot shortages for certified organic isolates.
The EU Green Deal's chemical sustainability targets are mandating solvent-free extraction across member state food manufacturing. EFSA residue monitoring now tests imported concentrates at Rotterdam and Hamburg entry points, rejecting shipments above detection thresholds. German ingredient processors are responding by integrating in-house mechanical pressing to guarantee supply chain compliance.
Buyer procurement is consolidating around dual-certified suppliers capable of documenting both organic and solvent-free claims through single audit trails. Protein bar manufacturers now specify aqueous-extracted concentrates in tender documents, displacing spot-market purchasing of uncertified isolates. This pattern is most visible in Netherlands and Belgium, where co-manufacturing networks serve pan-European brand distribution.
Hexane-Free Protein Market Segmentation
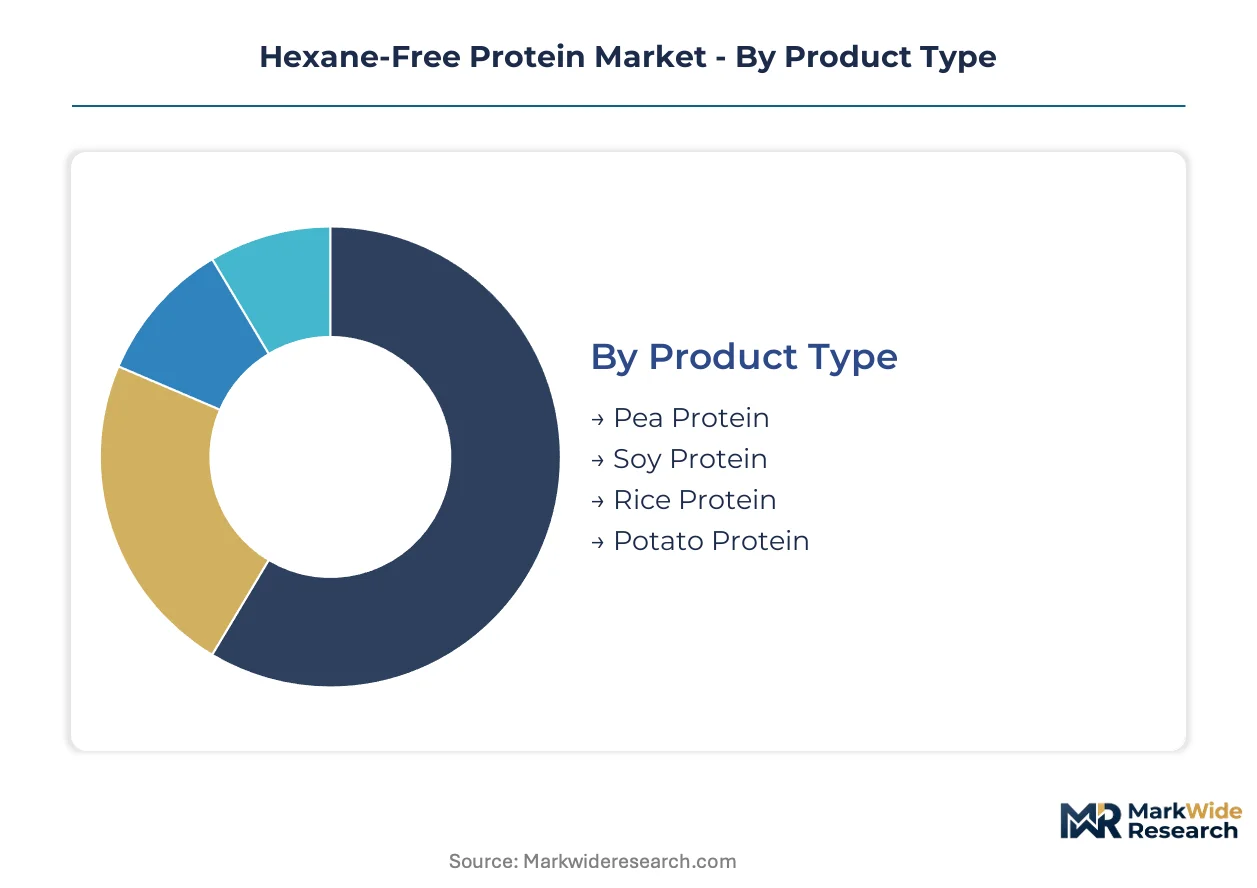
Hexane-free protein segmentation reveals where extraction technology investments align with clean-label premiums. Buyers sort suppliers by certification depth, functional performance, and end-use compliance requirements.
Product Type:
Pea protein commands the widest margin spreads due to its texturization advantages in meat alternatives, while soy protein retains volume leadership through established oilseed infrastructure.
- Pea Protein:Aqueous-extracted isolates achieve 80-85% protein content with gelation properties matching soy. German meat alternative manufacturers specify yellow pea concentrates for EU organic compliance.
- Soy Protein:Mechanical pressing of identity-preserved organic soybeans yields food-grade isolates with residual oil below 1%. North American crushing capacity serves dual-certified supply chains for export to European markets.
- Rice Protein:Hypoallergenic positioning drives pediatric and clinical nutrition demand. Brown rice enzymatic extraction produces 90% protein isolates with neutral flavor profiles.
- Potato Protein:Solanine-free concentrates from starch industry byproducts serve specialty pet food and limited-ingredient diet formulations.
The dominant share belongs to pea protein, while rice protein is closing the gap fastest.
End Use:
Application economics diverge sharply between premium-positioned human nutrition and commodity animal feed channels.
- Food & Beverage:Clean-label mandates from retail chains drive solvent-free documentation requirements. French dairy alternatives and German bakery applications specify aqueous-extracted concentrates in supplier agreements.
- Nutraceuticals:Capsule and tablet manufacturers require batch-level hexane testing below detection thresholds for organic certification eligibility. Swissmedic-registered facilities command pricing premiums.
- Dietary Supplements:Sports nutrition brands in Netherlands and Belgium now reject uncertified isolates, consolidating procurement around dual-audited suppliers.
- Animal Feed:Organic poultry and aquaculture operations use hexane-free meals to maintain residue-free meat and egg positioning for retail distribution.
Food and beverage captures the deepest margin pools, with nutraceuticals expanding most quickly as clinical positioning hardens.
Source:
Raw material provenance determines certification pathway complexity and organic equivalence recognition.
- Plant-Based:Broad category encompassing non-legume oilseeds and emerging sources like duckweed and algae. Novel protein developers pursue aqueous extraction to preempt regulatory scrutiny.
- Legumes:Yellow peas and fava beans dominate European mechanical pressing capacity. Canadian organic prairie production supplies German and French processors.
- Grains:Rice and oat proteins leverage existing starch industry infrastructure. Brown rice concentrates from Southeast Asia face EFSA residue testing at Rotterdam entry.
- Others:Sunflower and pumpkin seed proteins serve allergen-free positioning in premium snack applications.
Legumes anchor current supply volumes, though grains are gaining share fastest as hypoallergenic positioning broadens.
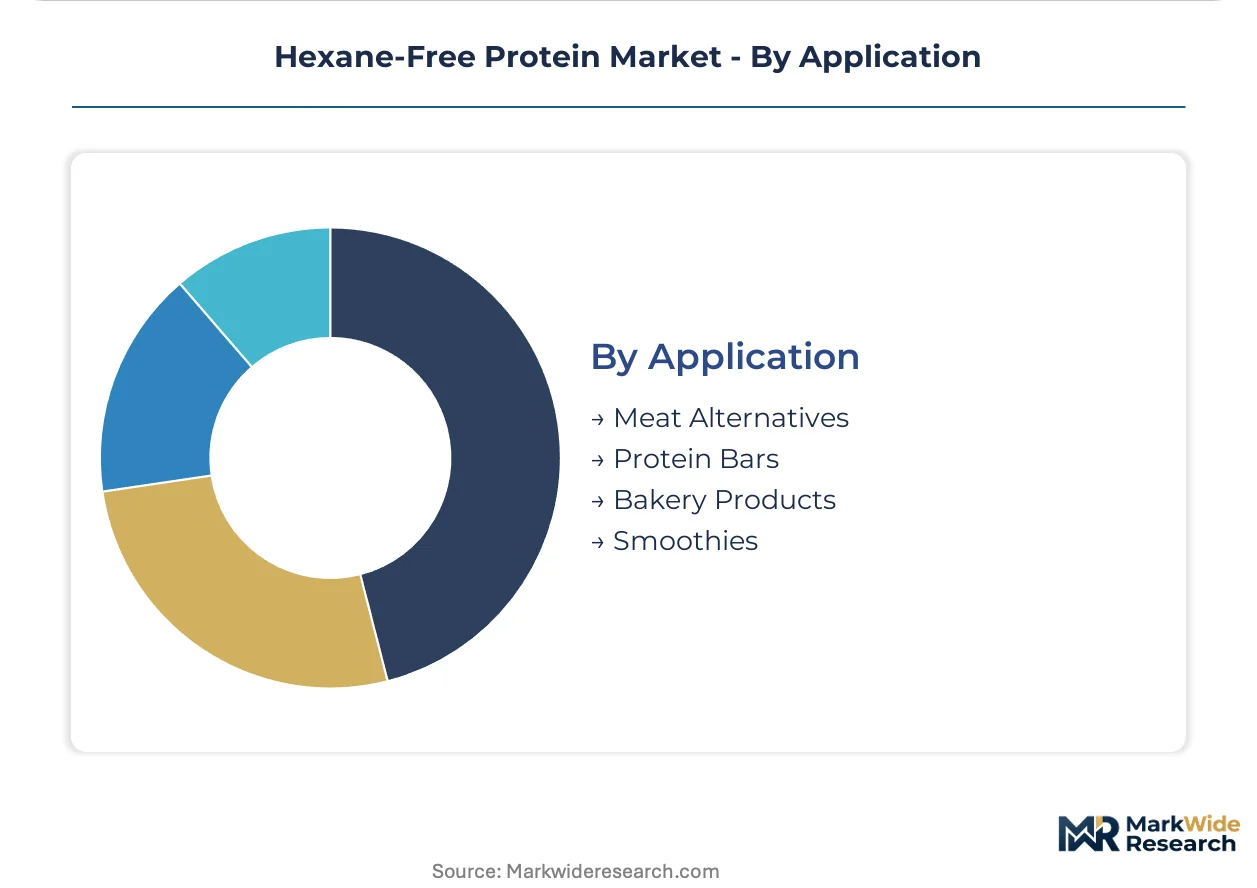
Application:
Functional requirements dictate protein specification, with texturization demands commanding the steepest premiums.
- Meat Alternatives:Texturized pea concentrates replicate muscle fiber structure through high-moisture extrusion. Brands pay 35-50% premiums for certified organic isolates with documented solvent-free extraction.
- Protein Bars:High-volume channel with compressed margins. Manufacturers specify minimum 80% protein content with flavor-masked systems to reduce bitterness.
- Bakery Products:Rice protein integrates into gluten-free formulations for improved crumb structure. German artisan bakers specify organic-certified concentrates.
- Smoothies:Ready-to-drink brands favor instantized rice and pea blends for dispersibility without sedimentation.
Meat alternatives command the highest unit economics, while protein bars move the largest absolute volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork strategy is tightening solvent residue limits across multiple jurisdictions, reshaping where hexane-free protein processing capacity concentrates and which extraction methods retain market access.
Germany
Meat alternative manufacturers in Hamburg and Berlin now mandate solvent-free documentation for all pea protein concentrates. ECHA's classification of n-hexane as a Substance of Very High Concern accelerates facility upgrades in Lower Saxony toward aqueous processing systems. Mechanical pressing capacity clusters in northern Germany serve both domestic food brands and export markets requiring EU-compliant certification.
United States
California and Illinois meat alternative manufacturers adopt enzyme-assisted aqueous concentrates at substantial premiums to secure clean-label positioning. FDA maintains zero tolerance for hexane residues in organic-labeled products under National Organic Program rules. North American oilseed infrastructure in the Midwest anchors volume supply for food-grade hexane-free soy isolates.
France
Dairy alternative and bakery applications in Paris and Lyon specify aqueous-extracted concentrates in supplier agreements. REACH chemical restrictions pressure processors to abandon hexane extraction methods or forfeit organic certification eligibility. French ingredient processors integrate in-house mechanical pressing to guarantee supply chain compliance with tightening residue thresholds.
Netherlands
Sports nutrition brands in Amsterdam and Rotterdam now reject uncertified isolates, consolidating procurement around dual-audited suppliers. EFSA residue monitoring tests imported concentrates at Rotterdam entry points, rejecting shipments above detection thresholds. Co-manufacturing networks serve pan-European brand distribution with documented solvent-free extraction.
Canada
Health Canada's PMRA monitors imported protein concentrates for solvent residues, creating compliance friction for non-certified suppliers. Organic yellow pea premiums fluctuate with prairie weather patterns, squeezing margin stability for processors. Canadian organic prairie production supplies German and French processors with raw material for mechanical pressing.
Hexane-Free Protein Market Competitive Environment
Listed leaders compete with private specialists across certification depth and extraction technology pathways. The supplier base concentrates around dual-certified processors capable of documenting both organic and solvent-free claims through single audit trails. Three archetypes dominate: diversified agribusiness conglomerates with oilseed infrastructure, specialty ingredient houses with flavor-masked systems, and allergen-free protein specialists serving clinical segments. Competitive moves center on backward integration into organic oilseed supply and geographic expansion of mechanical pressing capacity.
Within the diversified agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company represent scale-driven positions anchored in North American oilseed processing infrastructure. Kerry Group Plc exemplifies the specialty ingredient archetype, while Axiom Foods, Inc. occupies the allergen-free specialist position.
| Leading Market Players |
|---|
| Axiom Foods, Inc. |
| Cargill, Incorporated |
| DuPont Nutrition & Health |
| Kerry Group Plc |
| Archer Daniels Midland Company |
| Wilmar International Ltd |
| Nutiva Inc. |
| SunOpta Inc. |
| Parabel USA Inc. |
| Others |
Value Chain & Pricing Dynamics
USDA Organic dual-certification gates both supplier qualification and price differentiation simultaneously, compressing the addressable supplier base while stratifying concentrates into premium solvent-free tiers versus uncertified commodity isolates.
Pricing Analysis
Certification level creates the primary spread, with dual USDA-EU organic isolates commanding substantial premiums over single-certified or conventional alternatives. Three-tier pricing structure separates premium organic-solvent-free concentrates from standard organic isolates and economy-grade conventional proteins. Pricing pressure stems from yield gaps in aqueous extraction methods that inflate unit production costs. Protein bar manufacturers exhibit highest price sensitivity due to compressed margins, while meat alternative brands absorb premiums for texturization-grade concentrates.
Supply Chain Analysis
Rotterdam and Hamburg port congestion elevates inbound logistics costs for Southeast Asian rice protein and Canadian organic pea shipments entering EU markets. Mechanical pressing capacity concentrates in northern Germany, eastern France, and the US Midwest, drawing from organic prairie production in Canada and identity-preserved soybean programs in Iowa and Illinois. Supply chain risk centers on single-source vulnerability for aqueous processing enzymes and membrane filtration systems. Distribution runs through co-manufacturing networks in Netherlands and Belgium serving pan-European brand procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label ingredient procurement is shifting toward platform-economics dynamics where dual-certified suppliers function as interoperability hubs connecting brand R&D with compliant manufacturing capacity.
For Market Incumbents: Compound defensive positioning through backward integration into organic oilseed supply and captive mechanical pressing capacity in Germany or France. ECHA's Substance of Very High Concern classification for n-hexane accelerates facility upgrade timelines, threatening legacy solvent-dependent assets. Priority investment targets enzyme-assisted aqueous processing patents and flavor-masked protein systems that reduce formulation switching costs for meat alternative customers. For New Entrants and Emerging Players: Anchor in adult hypoallergenic sports nutrition channels in German fitness markets, where rice protein penetration lags pediatric positioning substantially. White-space expansion targets Swissmedic-registered nutraceutical facilities demanding batch-level hexane documentation. Go-to-market leverage rests on single-audit-trail documentation that collapses procurement complexity for brands seeking simultaneous organic and solvent-free claims. For Investors and Strategic Acquirers: The EU Green Deal's Farm to Fork solvent-free mandates reshape the acquisition landscape toward aqueous processing specialists with existing dual-certification infrastructure. Long-term viability favors targets with proven mechanical pressing engineering talent and established relationships with Canadian organic prairie suppliers. Signal to monitor: EFSA residue testing rejection rates at Rotterdam entry points as indicator of supply chain compliance friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Oilseed Supply | Cargill's North American infrastructure secures identity-preserved soybean streams for dual-certified isolate production. |
| Enzyme-Assisted Aqueous Processing Scale-Up | Kerry Group's protease engineering investments collapse energy intensity in pea protein isolate manufacturing. |
| Dual-Certification Audit Trail Consolidation | Axiom Foods' single-source documentation reduces procurement complexity for infant nutrition brands. |
| Flavor-Masked Protein System Development | Specialty ingredient houses reduce bitterness perception in high-concentration protein bar formulations. |
| Mechanical Pressing Capacity Expansion | German processors in Lower Saxony add aqueous processing lines to serve ECHA-compliant export markets. |
Study Parameters
A standing panel of ingredient procurement directors, organic certification auditors, meat alternative R&D formulators, and aqueous processing plant engineers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against USDA National Organic Program filings, ECHA REACH substance classifications, and EU Farm to Fork strategy implementation documents. Bottom-up volume modeling from processor capacity utilization triangulated against top-down demand estimates from end-use segment procurement patterns.
Consistency checks validated volume and value outputs against EFSA residue monitoring disclosure trends and organic oilseed trade flow data from Canadian prairie export statistics. The analytical framework segmented across protein source, extraction technology pathway, end-use application, and certification tier throughout the projection horizon. CAGRs derived from protein isolate production capacity expansion timelines and brand clean-label reformulation commitments. Industry-specific forecast inputs incorporated enzyme engineering patent filings and mechanical pressing equipment order backlogs.
Material uncertainties — prairie weather volatility affecting organic yellow pea supply, ECHA regulatory timeline acceleration, and enzyme cost curves in aqueous processing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification equivalence agreement stability and solvent-free extraction yield improvement trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein and Caseinates Market
Ingredients
India Olive Oil Market
Ingredients
Global Edible Oil Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Calendula Oil Market
Ingredients
Canada Soy Protein Market
Ingredients
United States Gelatin Market
Ingredients
Chicory Root Fiber Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Bouillon Cubes Market
Ingredients
Europe Amino Acid Market
Ingredients
Food Colors Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Global Natural Gum Market
Ingredients
Carotenes Market
Ingredients
Middle East and Africa Lipids Market