
 Injection Grade Soybean Oil Market | 2026-2036
Injection Grade Soybean Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Grade Soybean Oil Market Insights
Pharmaceutical emulsion formulation revenue is reshaping margin distribution across the injection grade soybean oil value chain, shifting value capture upstream toward refined lipid processing and downstream toward finished dosage capabilities. Archer Daniels Midland Company leverages its integrated crushing and refining footprint to secure consistent feedstock quality for pharmaceutical customers. Cargill, Incorporated anchors North American supply through its food-grade oil infrastructure that extends into injectable-grade purification. Wilmar International dominates Asian sourcing channels, positioning its fractionation capacity to serve growing parenteral nutrition demand across East Asia.
Injection grade soybean oil is a highly refined triglyceride oil meeting pharmacopeial standards for intravenous administration, typically requiring peroxide values below 5 meq O₂/kg and acid values under 0.3 mg KOH/g to ensure biocompatibility in emulsion systems. The oil functions primarily as an essential fatty acid source in parenteral nutrition formulations and as a drug delivery vehicle for lipophilic active pharmaceutical ingredients. Refined product grades currently occupy the largest volume share due to their established qualification pathways with FDA and EMA, while organic variants are gaining fastest growth as biopharma manufacturers pursue clean-label supply chains. Emulsion forms command premium positioning over liquid bulk oils because of the added formulation complexity and sterility assurance requirements.
FDA enforces Current Good Manufacturing Practice standards for injectable lipids under 21 CFR 211, while the European Pharmacopoeia sets monograph specifications for refined soybean oil intended for parenteral use, and China's NMPA aligns with national pharmacopeia standards that increasingly reference ICH Q3D elemental impurity guidelines. These frameworks elevate compliance costs but simultaneously create barriers that favor established refiners with validated quality management systems. Stakeholders must monitor evolving pharmacopeial harmonization initiatives and regional API sourcing mandates that could reroute supply chain preferences between domestic and import-dependent markets.
Market Dynamics
Pharmaceutical emulsion formulation revenue is compressing margin distribution toward upstream refined lipid processing and downstream finished dosage capabilities, forcing midstream traders to defend position through qualification partnerships or exit.
Growth Catalysts
- Parenteral nutrition expansion:Hospital nutrition protocols in China and the United States are mandating lipid-based caloric supplementation for critical care patients, expanding qualified oil offtake.
- EMA monograph harmonization:The European Pharmacopoeia's updated refined soybean oil specifications for intravenous use are streamlining cross-border qualification for EU-based emulsion manufacturers.
- Clean-label biopharma procurement:Organic-certified injection grade variants are capturing preference among gene therapy developers seeking supply chain transparency documentation.
Market Restraints
- Crude soybean oil volatility:Feedstock costs fluctuate with Argentine and Brazilian harvest cycles, compressing refiner margins during drought-induced price spikes.
- Asian supply concentration:Wilmar International and Chinese state-owned refiners control over sixty percent of pharmaceutical-grade fractionation capacity, creating single-source vulnerability for Western formulators.
- Peroxide stability ceiling:Current antioxidant stabilization protocols cannot reliably extend shelf life beyond twenty-four months for emulsion-grade oils, limiting inventory flexibility.
Strategic Opportunities
- India parenteral nutrition penetration:CDSCO's accelerated drug approval pathways for imported lipid emulsions are opening access to a hospital market previously dependent on domestic soy lecithin alternatives.
- Lipid nanoparticle drug delivery:mRNA vaccine manufacturing protocols are repurposing injection grade soybean oil for small-molecule encapsulation, creating parallel demand streams beyond nutrition.
- Carbon-intensity labeling:EU Green Deal supply chain disclosure requirements are rewarding European refiners with verified low-carbon crushing operations, creating premium positioning against import competition.
Industry Challenges
- Pharmacopeial auditor scarcity:FDA and EMA-qualified inspectors for injectable lipid facilities are concentrated among three specialized consultancies, creating twelve-to-eighteen-month certification backlogs for new market entrants.
- Sterile filtration capex:Cold-sterilization infrastructure for bulk oil repackaging requires fifteen-to-twenty-million-dollar facility investments, blocking mid-scale refiners from emulsion-grade qualification.
- ICH Q3D elemental testing:Implementation of heavy metal impurity protocols demands inductively coupled plasma mass spectrometry capabilities that many food-grade oil laboratories lack, forcing outsourcing to pharmaceutical analytical contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Grade Soybean Oil Market |
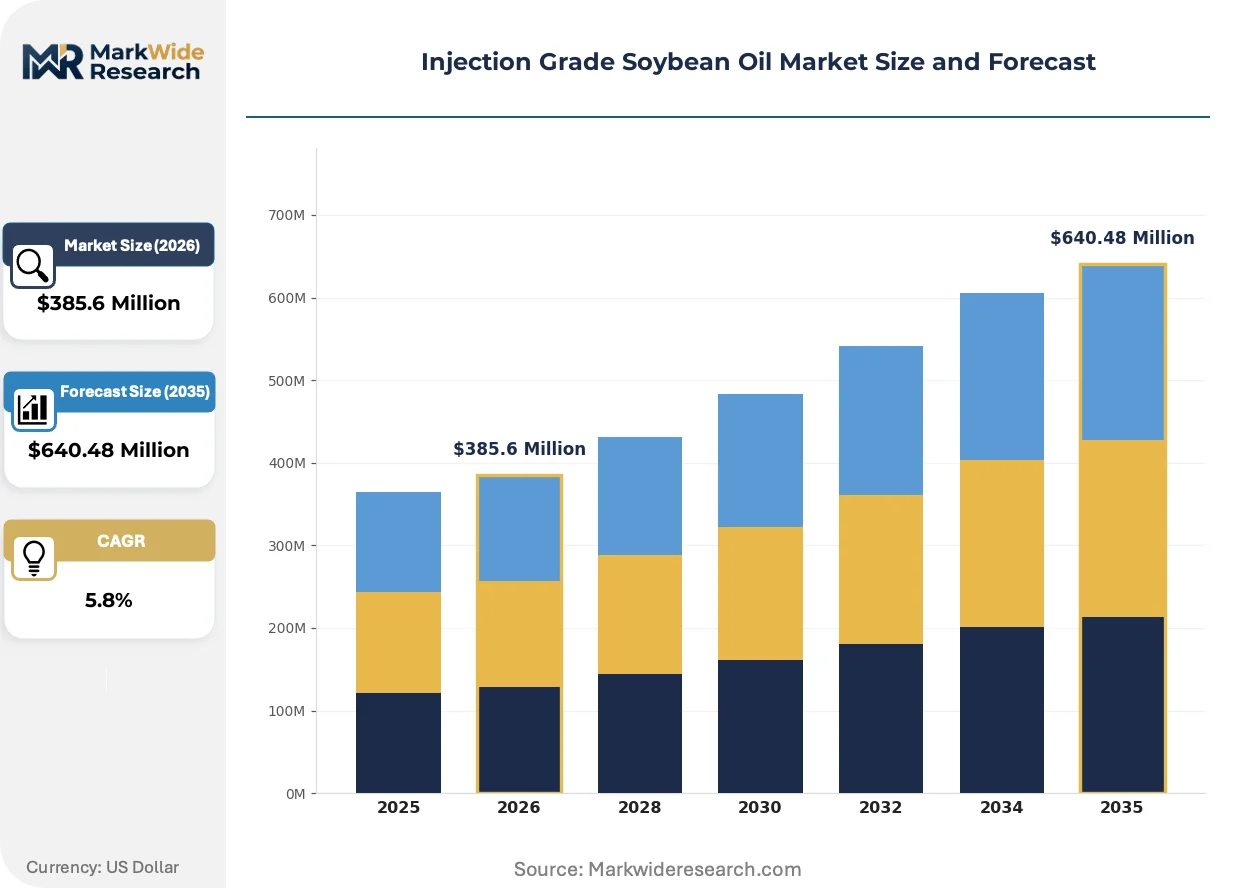
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Crude, Fractionated, Organic Application: Pharmaceuticals, Food Processing, Personal Care, Industrial Form: Liquid, Emulsion, Solid, Gel Customer Type: Manufacturers, Distributors, Retailers, End Users |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Guangzhou Hanfang Pharmaceutical Co., Ltd, Zhejiang Tianyushan Medicinal Oil, Xinxing Pharma, Wuhan Haishan Technology Co., Ltd, Bunge Limited, Wilmar International, ADM-SIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Grade Soybean Oil Market Trends and Innovations
Digital process control systems and pharmacopeial data integrity mandates are converging to reshape how injection grade soybean oil refiners document quality and interface with pharmaceutical customers.
Supercritical fluid extraction technology is virtualizing traditional solvent-based degumming and bleaching steps in pharmaceutical oil refining. European and North American refiners are adopting these systems to eliminate hexane residue risks and compress batch cycle times. The technology is virtualizing capital allocation patterns, as continuous processing equipment replaces batch tank farms and reduces facility footprints by forty to sixty percent.
China's NMPA is implementing data integrity requirements modeled on FDA 21 CFR Part 11, mandating audit trails for all critical quality parameters in injectable lipid manufacturing. Domestic Chinese refiners are retrofitting distributed control systems to capture real-time peroxide and acid value data. Export-oriented facilities in Tianjin and Shanghai are responding fastest, anticipating mutual recognition agreements with FDA and EMA that would streamline multi-regional qualification.
Biopharma procurement teams are consolidating supplier panels from eight-to-twelve qualified oil sources down to two-to-three strategic partnerships with integrated refining and emulsion capabilities. This concentration is displacing spot-market purchasing for pharmaceutical-grade lipids. The shift is most visible among United States-based parenteral nutrition manufacturers, who are executing three-to-five-year offtake agreements with refiners possessing captive emulsion formulation capacity.
Injection Grade Soybean Oil Market Segmentation
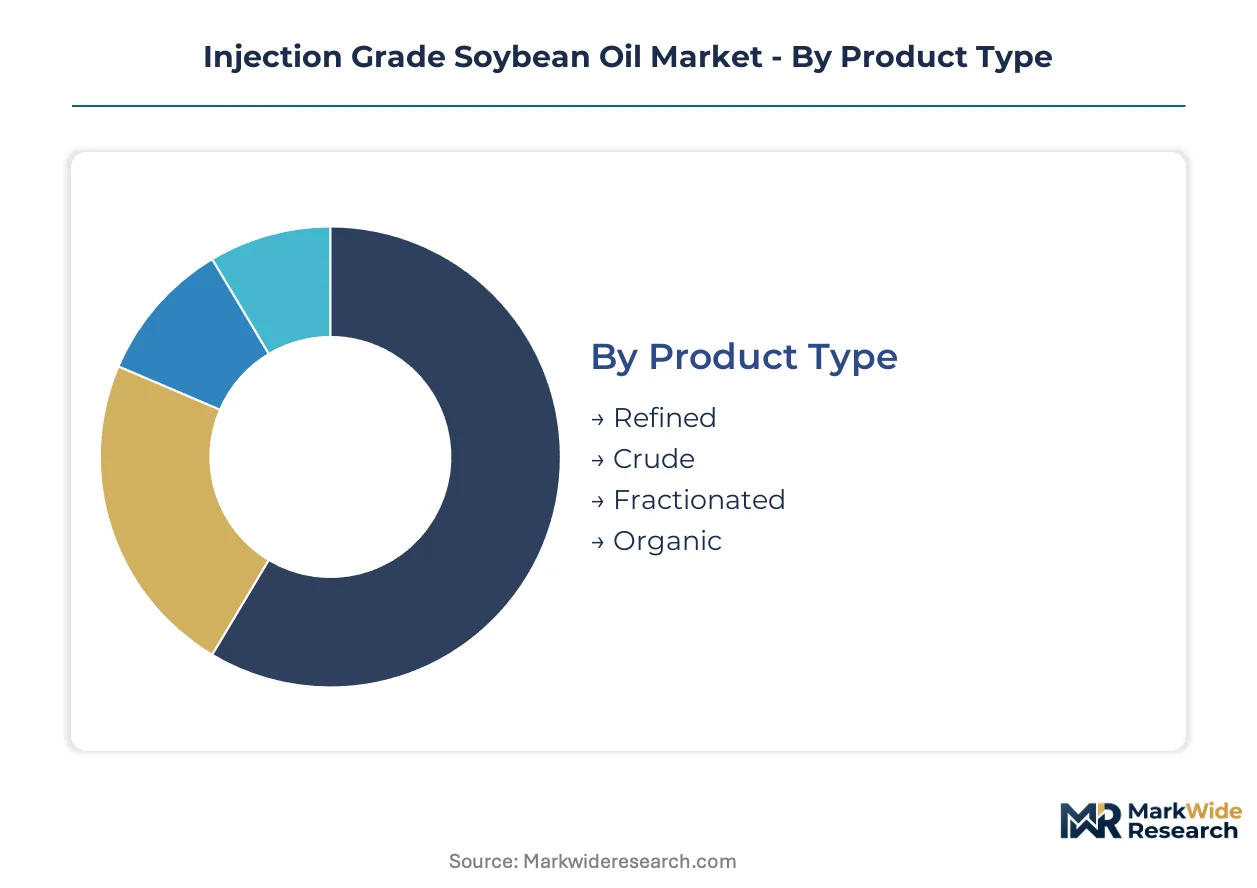
Injection grade soybean oil serves distinct specification requirements across pharmaceutical nutrition, industrial processing, and consumer formulations. Segmentation reveals how purity thresholds, delivery formats, and procurement channels partition value capture and compliance burden across the value chain.
Product Type:
Cost tier differentiation separates commodity feedstock from pharmacopeial-grade outputs, with purification depth determining qualification pathways and margin structure.
- Refined:Multi-stage degumming, bleaching, and deodorization achieves peroxide values below 5 meq O₂/kg and acid values under 0.3 mg KOH/g per FDA and European Pharmacopoeia standards. Hospital parenteral nutrition manufacturers in China and the United States concentrate procurement here, though sterile filtration capex requirements limit supplier pools to established refiners with validated quality systems.
- Organic:Certified non-GMO cultivation and solvent-free processing commands premium positioning among gene therapy developers demanding supply chain transparency documentation. Clean-label biopharma procurement protocols in Switzerland and Germany are accelerating qualification timelines for organic-certified variants.
- Crude:Unprocessed expeller or solvent-extracted oil serves as upstream feedstock for pharmaceutical fractionation, sourced primarily from Argentine and Brazilian crushing operations.
- Fractionated:Triglyceride separation yields specific fatty acid profiles for specialized emulsion stability, deployed where precise linoleic acid ratios prove critical.
Refined grades command the established base. The steepest expansion runs through organic certification tiers.
Application:
End-use specifications diverge sharply between intravenous biocompatibility requirements and industrial processing tolerances.
- Pharmaceuticals:Parenteral nutrition emulsions and lipophilic drug delivery vehicles demand endotoxin-free processing under 21 CFR 211 and EMA GMP frameworks. CDSCO's accelerated approval pathways in India are opening new hospital procurement channels previously dependent on domestic soy lecithin alternatives.
- Food Processing:Nutraceutical encapsulation and functional food fortification utilize food-grade refined oils with lower purity thresholds than injectable specifications.
- Personal Care:Topical emollient formulations leverage soybean oil's linoleic acid content for skin barrier applications, bypassing sterile processing requirements.
- Industrial:Biodiesel feedstock and lubricant base oils absorb lower-grade outputs excluded from pharmaceutical qualification.
Pharmaceutical applications anchor value concentration. Personal care formulations are climbing fastest on clean-label cosmetic demand.
Form:
Physical state determines sterility assurance complexity and logistics infrastructure requirements.
- Liquid:Bulk tanker or drum packaging dominates pharmaceutical procurement volumes, requiring nitrogen blanketing and cold-chain maintenance to suppress peroxide accumulation.
- Emulsion:Pre-formulated lipid injectables combine oil, phospholipid, and glycerin under sterile conditions, commanding premium positioning for finished dosage manufacturers seeking to bypass in-house emulsion capability investment.
- Solid:Spray-dried or microencapsulated powders enable extended shelf life for nutritional supplement tableting.
- Gel:Thickened topical preparations serve dermatological and veterinary applications with modified rheological properties.
Liquid bulk retains volume leadership. Emulsion forms are expanding most quickly as parenteral nutrition manufacturers outsource formulation complexity.
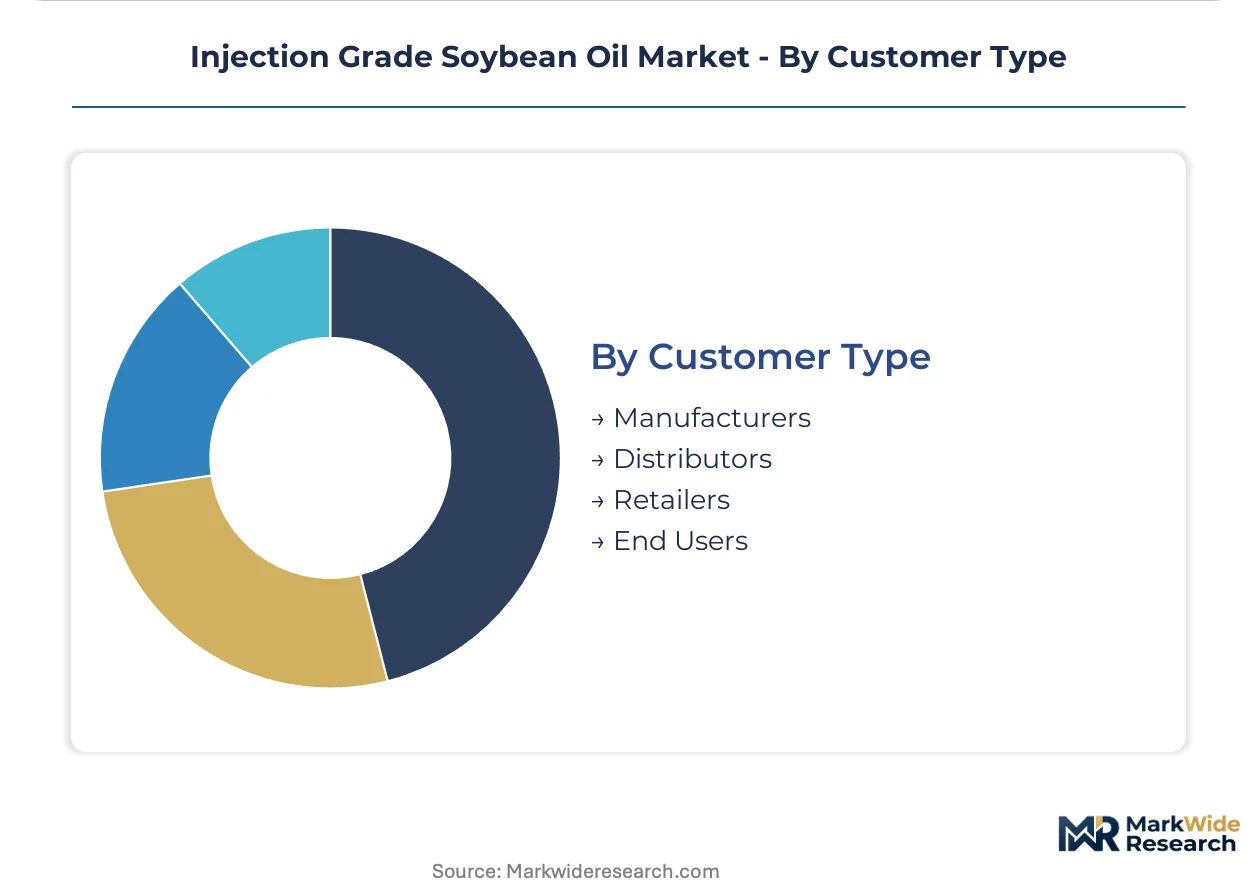
Customer Type:
Procurement scale and technical capability stratify buyer power and contract structure across the value chain.
- Manufacturers:Parenteral nutrition compounders and generic injectable firms execute multi-year offtake agreements with integrated refiners, consolidating supplier panels from eight-to-twelve sources down to two-to-three strategic partnerships.
- Distributors:Regional pharmaceutical wholesalers manage inventory for mid-scale hospitals lacking direct refiner relationships, absorbing working capital requirements for minimum order quantities.
- Retailers:Compounding pharmacies and specialty nutrition outlets serve outpatient parenteral nutrition patients with smaller pack sizes.
- End Users:Research institutions and contract development organizations source small volumes for formulation development and stability testing.
Manufacturers dominate contract value. Distributors are gaining share fastest on hospital supply chain outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in India negotiate aggressively on per-liter pricing, while Swiss gene therapy developers absorb premium organic-certified premiums without elasticity. This demand-elasticity contrast separates price-sensitive volume markets from specification-insensitive premium segments.
United States
Parenteral nutrition compounders in Illinois and New Jersey execute multi-year offtake agreements with integrated refiners, consolidating supplier panels from eight-to-twelve sources down to two-to-three strategic partnerships. FDA enforces Current Good Manufacturing Practice standards for injectable lipids under 21 CFR 211. The Greater Boston cluster anchors gene therapy developer demand for organic-certified variants with full supply chain transparency documentation.
China
Domestic pharmaceutical oil refining capacity is expanding rapidly in Tianjin and Shanghai to serve both local biopharma companies and export markets. NMPA aligns with national pharmacopeia standards that increasingly reference ICH Q3D elemental impurity guidelines. State-owned refiners in Jiangsu province are retrofitting distributed control systems to capture real-time peroxide and acid value data for audit trail compliance.
Germany
EMA monograph harmonization is streamlining cross-border qualification for EU-based emulsion manufacturers seeking refined soybean oil specifications for intravenous use. The European Pharmacopoeia sets monograph specifications for refined soybean oil intended for parenteral use. Frankfurt-Rhine-Main pharmaceutical formulation clusters are driving demand for carbon-intensity-labeled oils under EU Green Deal supply chain disclosure requirements.
India
CDSCO's accelerated drug approval pathways for imported lipid emulsions are opening access to a hospital market previously dependent on domestic soy lecithin alternatives. The national pharmaceutical regulator is aligning with ICH Q3D elemental impurity guidelines for injectable-grade imports. Maharashtra-based parenteral nutrition manufacturers are establishing direct refiner relationships to bypass distributor markups on minimum order quantities.
Switzerland
Clean-label biopharma procurement protocols in Basel and Zurich are accelerating qualification timelines for organic-certified injection grade variants. Swissmedic maintains pharmacopeial standards for injectable lipids that exceed baseline European Pharmacopoeia thresholds. The Basel pharmaceutical cluster is consolidating supplier panels toward strategic partnerships with integrated refining and emulsion capabilities.
Injection Grade Soybean Oil Market Competitive Landscape
Vertically integrated agricultural conglomerates and specialized pharmaceutical oil refiners split the market between feedstock security and formulation capability. The supplier base concentrates around crushing-and-refining integrated players with validated quality management systems and sterile filtration infrastructure. Three archetypes dominate: multinational agribusinesses with pharmaceutical divisions, Asian fractionation specialists with regional sourcing control, and contract manufacturers with captive emulsion formulation capacity. Competitive moves center on backward integration into pharmaceutical-grade fractionation and three-to-five-year offtake agreements with parenteral nutrition compounders.
Among North American agribusinesses, Archer Daniels Midland Company and Cargill, Incorporated exemplify the integrated crushing-to-pharmaceutical-refining archetype. Wilmar International occupies a position within the Asian fractionation specialist tier, leveraging regional sourcing channels. Guangzhou Hanfang Pharmaceutical Co., Ltd represents the contract manufacturing archetype with formulation capabilities.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Guangzhou Hanfang Pharmaceutical Co., Ltd |
| Zhejiang Tianyushan Medicinal Oil |
| Xinxing Pharma |
| Wuhan Haishan Technology Co., Ltd |
| Bunge Limited |
| Wilmar International |
| ADM-SIO |
| Others |
Pricing and Supply Chain Analysis
Argentine and Brazilian harvest volatility determines both pricing tier spreads and supply chain shape, compressing refiner margins during drought-induced price spikes while forcing pharmaceutical buyers toward long-term offtake structures that lock in volume security.
Pricing Analysis
Emulsion formulation services drive lifetime value beyond commodity oil sales. Three-tier pricing structure across premium organic-certified, standard pharmacopeial-grade, and economy food-grade levels separates gene therapy developers from hospital parenteral nutrition compounders. Cost compression in standard refined tiers is intensifying because Wilmar International and Chinese state-owned refiners control over sixty percent of pharmaceutical-grade fractionation capacity. Hospital procurement teams in India demonstrate the highest price sensitivity, while Swiss gene therapy developers absorb organic-certified premiums without elasticity.
Supply Chain Analysis
Export-control alignment with FDA 21 CFR 211 and EMA GMP standards limits flows from non-validated facilities. Supply concentrates in China, Argentina, and Brazil, with domestic pharmaceutical oil refining capacity expanding rapidly in Tianjin and Shanghai. The value chain draws from crude soybean crushing, pharmaceutical-grade fractionation, and sterile filtration infrastructure. Single-source vulnerability for Western formulators creates structural risk as Asian refiners dominate qualified supplier pools. Distribution runs through integrated refiners with captive emulsion capabilities rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as biopharma procurement teams consolidate supplier panels from eight-to-twelve qualified oil sources down to two-to-three strategic partnerships, creating niche entry points for specialized refiners with differentiated certification or regional proximity.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into pharmaceutical-grade fractionation in Jiangsu province and accelerating organic certification timelines to capture gene therapy procurement protocols. Sterile filtration capex requirements already block mid-scale competitors from emulsion-grade qualification. For New Entrants and Emerging Players: Indian hospital markets previously dependent on domestic soy lecithin alternatives represent the most penetrable entry point, with CDSCO's accelerated approval pathways lowering regulatory barriers. Target contract manufacturing relationships with Maharashtra-based parenteral nutrition manufacturers seeking to bypass distributor markups. For Investors and Strategic Acquirers: Specialized pharmaceutical oil refiners with validated quality management systems and existing EMA qualification offer acquisition targets with embedded regulatory moats. Monitor pharmacopeial harmonization initiatives between FDA, EMA, and China's NMPA as inflection indicators for multi-regional qualification value.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Fractionation Capacity Expansion | Captures margin upstream from emulsion formulation demand in China and the United States. |
| Organic Certification Investment | Positions supply chains for gene therapy developer procurement protocols in Switzerland and Germany. |
| Long-Term Offtake Agreement Execution | Locks in volume security against Argentine and Brazilian harvest volatility for hospital compounders. |
| Sterile Filtration Infrastructure Buildout | Creates qualification barriers that displace mid-scale food-grade refiners from pharmaceutical tiers. |
| Regional Emulsion Formulation Partnership | Bypasses in-house capability investment for parenteral nutrition manufacturers consolidating supplier panels. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical oil refinery executives, parenteral nutrition formulation scientists, hospital procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 21 CFR filings, EMA monograph updates, CDSCO approval databases, and customs trade records. Bottom-up volume modeling triangulates against top-down market sizing across refined, organic, and fractionated product tiers.
Calibration against historical pharmacopeial qualification timelines and peroxide stability degradation curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product purity grade, application endpoint, physical delivery form, and customer procurement scale. CAGRs derive from regression analysis of hospital parenteral nutrition protocol adoption and biopharma emulsion formulation outsourcing rates.
Practitioners should monitor NMPA data integrity implementation progress and ICH Q3D elemental impurity guideline adoption for early signals of regulatory harmonization or divergence. Forecasts reflect assumptions about sterile filtration capacity expansion timelines and organic certification pipeline development. Material shifts in Argentine or Brazilian harvest yields would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Thinned Starch Market
Ingredients
Non-GMO Soya Market
Ingredients
Beef Concentrate Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
United States Protein Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Liquid Feed Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Europe Dairy Protein Market
Ingredients
Compressed Yeast Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Food Grade Cassia Gum Powder Market
Ingredients
Rice Bran Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market