
 Anti-Aging Ingredients Market | 2026-2036
Anti-Aging Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Ingredients Market Analysis
ISO 16128 certification for natural and organic cosmetic ingredients is unwinding the competitive landscape, forcing raw material suppliers to revalidate sourcing claims and analytical methods. BASF leverages its integrated biotechnology platforms to control fermentation-derived peptide supply chains from strain development to commercial scale. Croda International anchors its position through lipid and surfactant expertise that underpins retinoid stabilization in finished formulations. Lonza Group specializes in synthetic peptide manufacturing, occupying a niche where pharmaceutical-grade purity standards intersect with cosmetic efficacy demands.
Anti-aging ingredients comprise biologically active compounds engineered to modulate skin cell signaling, collagen synthesis, and oxidative stress pathways, typically formulated at concentrations between 0.01% and 2% depending on molecular potency and irritation thresholds. Retinoids dominate prescription and clinical channels where bioactivity documentation supports premium pricing, while hyaluronic acid spans mass and prestige tiers through molecular weight differentiation that governs penetration depth and hydration mechanism. Peptides represent the fastest-expanding structural category as signal peptides and carrier peptides displace simpler collagen claims with targeted mechanistic narratives.
The EU Cosmetics Regulation and REACH compliance frameworks govern ingredient safety substantiation and nanomaterial classification across European supply chains, while the FDA's oversight of cosmetic safety and emerging Modernization of Cosmetics Regulation Act requirements shape U.S. market access protocols. China's NMPA registration pathways for imported cosmetic raw materials add a third jurisdictional layer that suppliers must navigate for Asia-Pacific commercialization. Stakeholders should monitor regulatory divergence between jurisdictions as a primary determinant of formulation strategy and geographic prioritization.
Market Dynamics
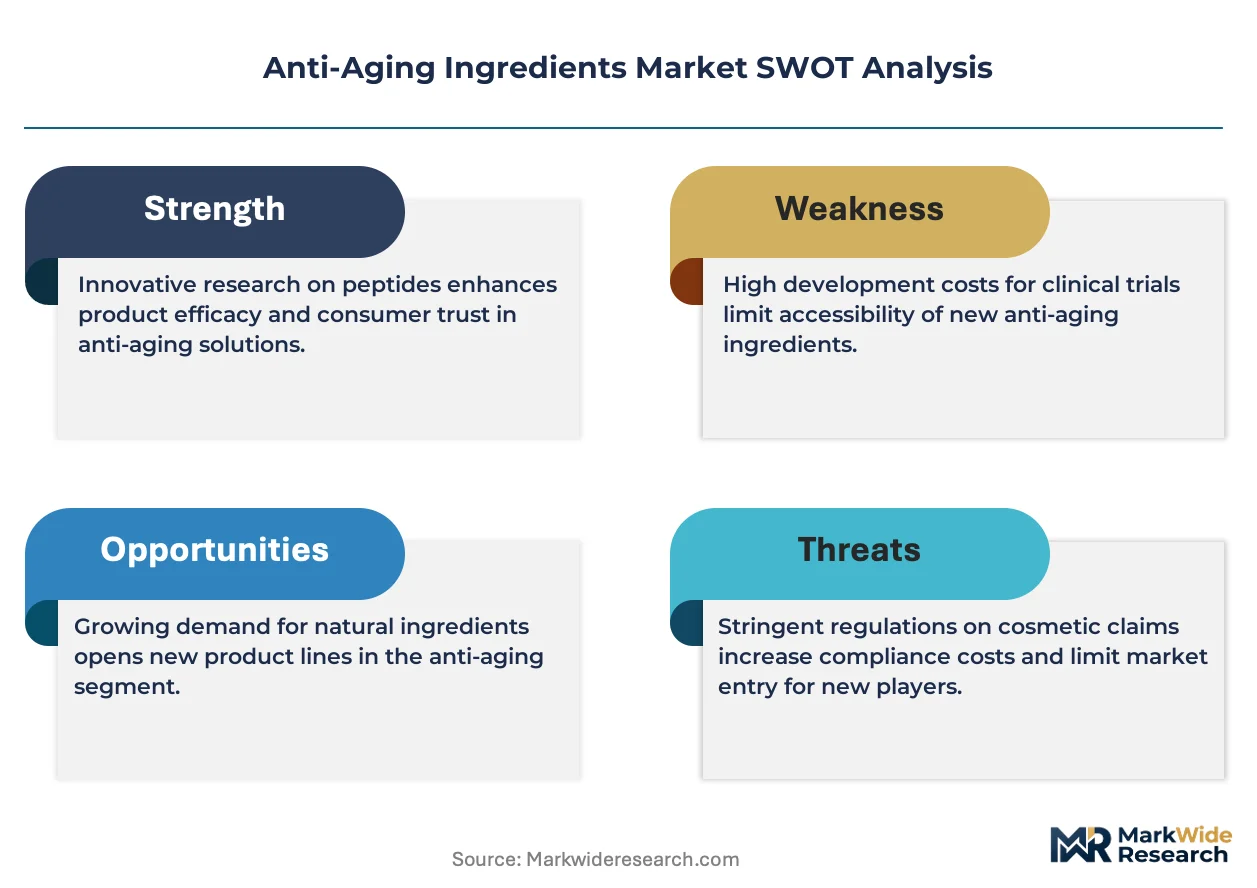
Peptide ingredient supply chains are consolidating around pharmaceutical-grade fermentation capacity, as cosmetic brands demand batch-to-batch consistency that only cGMP-certified facilities can deliver. This structural concentration is redrawing supplier qualification protocols across North America and Western Europe.
Growth Catalysts
- EU Cosmetics Regulation (EC) No 1223/2009:Mandatory ingredient disclosure and safety substantiation requirements are elevating demand for analytically validated active compounds with documented mechanistic pathways.
- Dermatology-backed direct-to-consumer channels:Clinician-endorsed brands in the United States are commanding premium positioning by specifying peptide and retinoid concentrations with clinical citation.
- Fermentation-derived peptide manufacturing:Biotechnology platforms producing signal peptides and carrier peptides are displacing simpler collagen claims with targeted cell-signaling narratives.
Market Restraints
- Retinoid raw material volatility:Isotretinoin and tretinoin precursor supply concentrates among three specialty chemical manufacturers, exposing formulators to input cost swings and allocation risk.
- REACH nanomaterial classification:The European Chemicals Agency's evolving criteria for nano-scale hyaluronic acid and lipid carriers are creating compliance friction and reformulation costs for suppliers serving EU markets.
- Hyaluronic acid commoditization:Mass-market molecular weight grades face price compression from Chinese fermentation capacity expansion, squeezing margin for non-differentiated suppliers.
Strategic Opportunities
- Men's grooming application expansion:Underpenetrated male skincare segments in Germany and the United Kingdom present whitespace for retinoid and peptide formulations positioned around barrier repair rather than anti-wrinkle claims.
- NMPA registration pathway optimization:China's National Medical Products Administration cosmetic raw material registration creates first-mover advantage for suppliers investing in Asia-Pacific compliance infrastructure ahead of competitor entry.
- Biotechnology-convergent personalization:Skin microbiome analysis combined with custom peptide blending services enables subscription-based models capturing lifetime value from high-engagement consumers.
Industry Challenges
- ISO 16128 analytical method validation:Natural and organic certification claims require suppliers to revalidate sourcing documentation and carbon-14 testing protocols, extending qualification timelines by 12-18 months.
- Peptide synthesis IP fragmentation:Overlapping patent estates covering signal peptide sequences and carrier peptide conjugation chemistry are complicating freedom-to-operate assessments and licensing negotiations.
- cGMP capacity scarcity:Qualified fermentation and synthetic peptide manufacturing slots at pharmaceutical-grade facilities command premium pricing and extended lead times, constraining brand launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Ingredients Market |
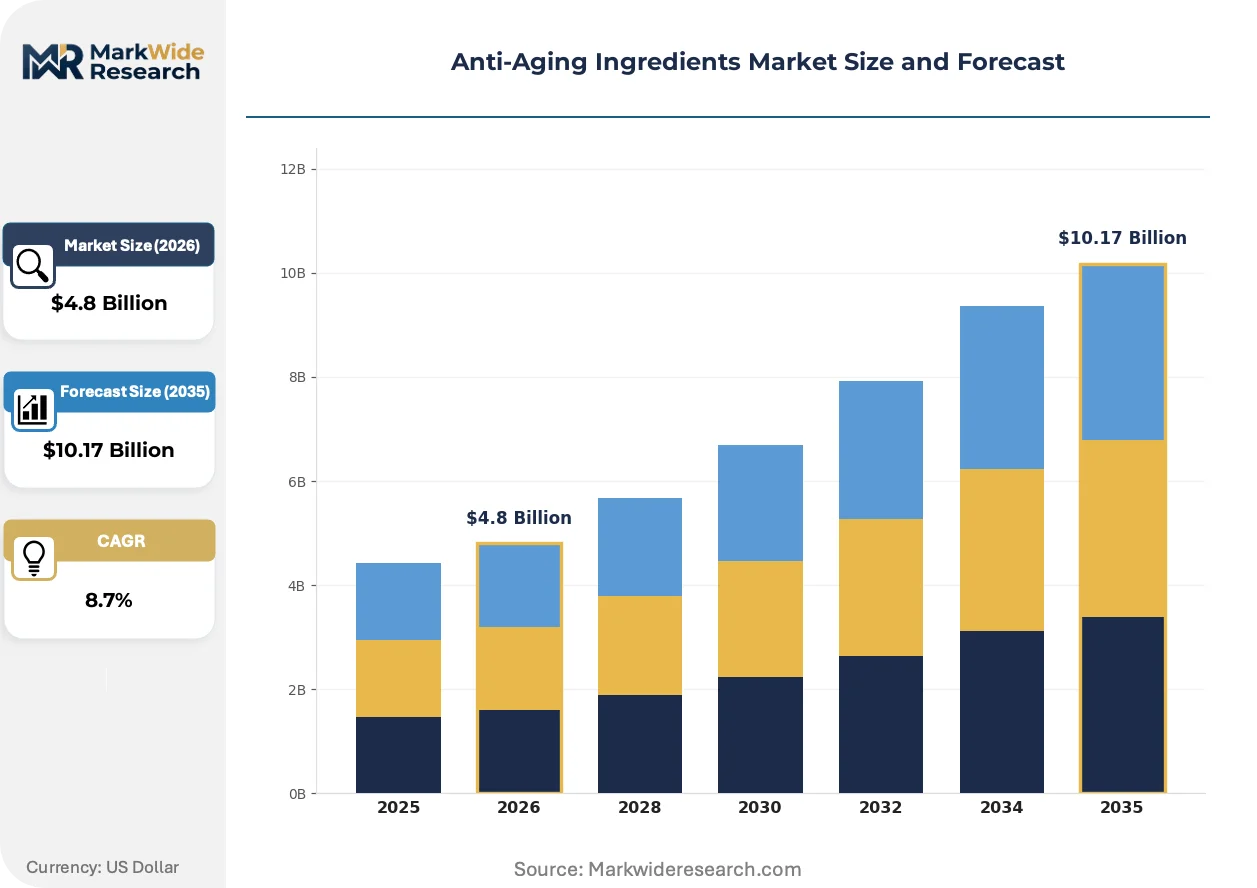
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinoids, Peptides, Antioxidants, Hyaluronic Acid Application: Skincare, Haircare, Makeup, Fragrance Formulation: Serum, Cream, Gel, Emulsion Consumer Type: Women, Men, Seniors, Teens |
| Companies Covered | BASF, Adeka Corporation, Contipro, BioThrive Sciences, Kao Corporation, Croda International, Wacker Chemie, Lonza Group, Dow Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Ingredients Market Emerging Trajectories
Active ingredient development is pivoting from generic collagen and hydration claims toward mechanistic narratives supported by ex vivo and clinical endpoint data. This evidentiary escalation is reshaping R&D investment priorities and supplier selection criteria across prestige and clinical channels.
Peptide ingredient portfolios are bifurcating between mass-market signal peptides with simple INCI names and sophisticated carrier peptides requiring pharmaceutical-grade purity documentation. Prestige brands in France and Switzerland are adopting the latter at accelerated procurement cycles, compressing competitive space for undifferentiated commodity suppliers. This technology divide is enabling premium pricing stratification based on analytical rigor rather than concentration alone.
The FDA's Modernization of Cosmetics Regulation Act of 2022 is imposing adverse event reporting and facility registration requirements that previously applied only to drugs. Cosmetic manufacturers importing retinoid and peptide actives into the United States must now maintain lot traceability and safety substantiation dossiers equivalent to pharmaceutical standards. Small and mid-sized brands lacking regulatory affairs infrastructure are outsourcing compliance to specialized consulting firms or withdrawing from the U.S. market.
Ingredient sourcing decisions now incorporate ECHA SCIP database obligations and emerging CSRD supply chain due diligence requirements. European formulators are requesting full substance origin documentation from peptide and retinoid suppliers, with Germany and the Netherlands leading implementation. This behavioral shift favors vertically integrated biotechnology platforms with captive strain development and fermentation capacity over distributed chemical synthesis networks.
Anti-Aging Ingredients Market Segmentation
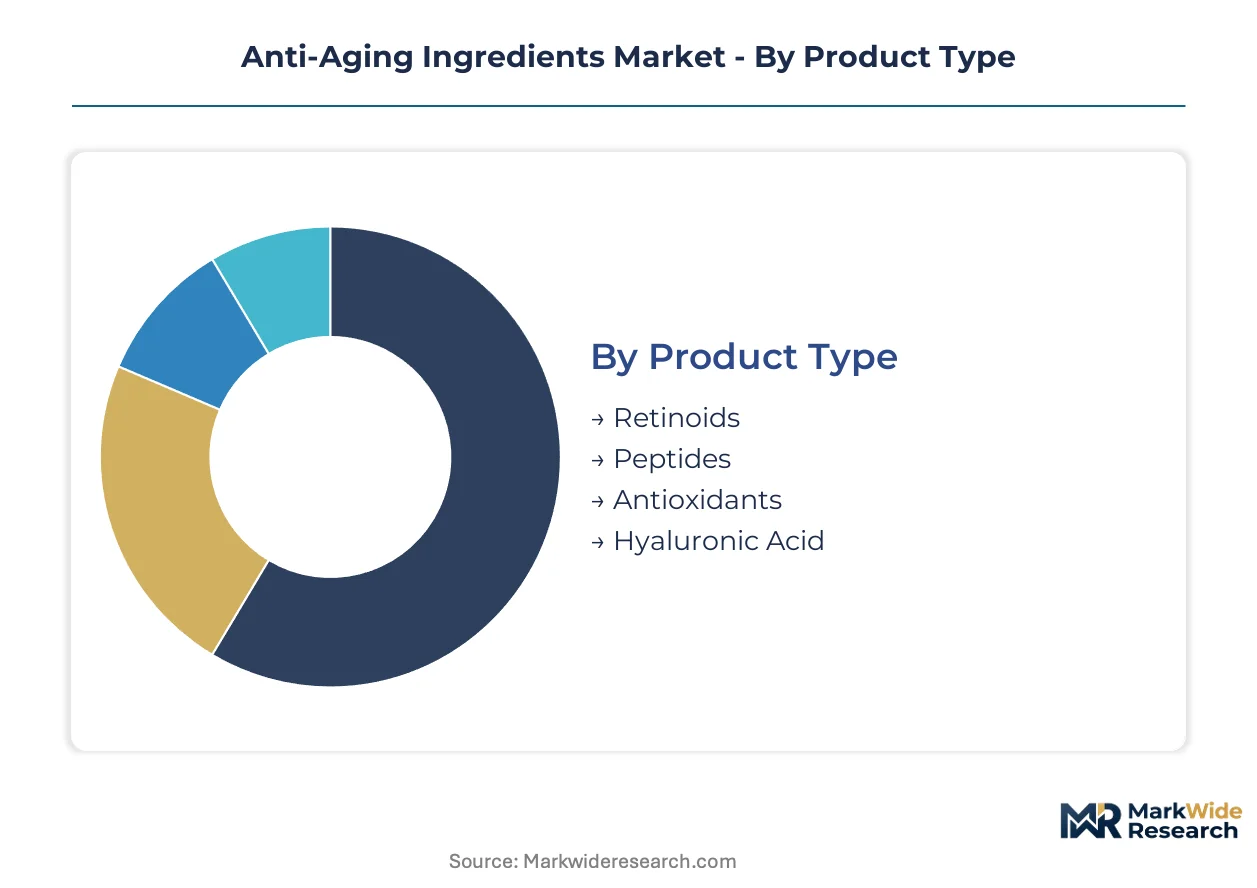
Ingredient classification in anti-aging formulations determines regulatory pathways, pricing architecture, and supplier qualification intensity. Segmentation by molecular mechanism, delivery vehicle, and end-user physiology exposes where substitution threats and margin compression concentrate most acutely.
Product Type:
Retinoid and peptide segments face the most acute substitution pressure from botanical extracts and fermented actives as clean beauty mandates harden formulation protocols.
- Retinoids:Vitamin A derivatives including retinol, retinaldehyde, and prescription-grade tretinoin that accelerate cell turnover through nuclear receptor modulation. Demand concentrates in United States dermatology clinics and prestige channels where FDA oversight of cosmetic-drug distinctions creates compliance moats. Substitution risk from bakuchiol and rambutan extracts is accelerating in EU markets under REACH scrutiny.
- Peptides:Short-chain amino acid sequences functioning as signal molecules, carrier compounds, or neurotransmitter inhibitors. Procurement in Switzerland and France favors pharmaceutical-grade fermentation-derived grades with documented mechanistic pathways. Carrier peptides displace simpler collagen claims fastest in clinician-endorsed brands.
- Antioxidants:Free-radical scavengers spanning ascorbic acid, tocopherol, and polyphenol complexes. Commoditization pressure from Chinese ascorbic acid capacity expansion compresses margin for undifferentiated suppliers.
- Hyaluronic Acid:Glycosaminoglycan with molecular weight-dependent hydration mechanisms. Cross-linked and low-molecular-weight grades face ECHA nanomaterial classification uncertainty in Germany and Netherlands.
Hyaluronic acid anchors the volume base while peptides gain share at the steepest rate.
Application:
Cost tier stratification separates clinical-grade actives from mass-market functional ingredients across end-use categories.
- Skincare:Facial and body formulations incorporating actives at concentrations between 0.01% and 2%. Peptide and retinoid procurement concentrates in United States direct-to-consumer brands and French pharmacy channels where concentration disclosure commands premium positioning.
- Haircare:Scalp treatments and anti-aging shampoos deploying peptides for follicle signaling. Niche positioning in Germany and United Kingdom targets barrier repair rather than cosmetic claims to navigate advertising restrictions.
- Makeup:Color cosmetics with infused skincare actives. Regulatory friction in China under NMPA registration requirements limits retinoid inclusion in imported finished goods.
- Fragrance:Scented products with ancillary skincare positioning. Minimal active ingredient loading due to volatility constraints and IFRA compliance costs.
Skincare dominates procurement spend while haircare applications expand most quickly in male grooming segments.
Formulation:
Delivery vehicle selection governs penetration depth, stability requirements, and manufacturing complexity for active ingredient integration.
- Serum:High-concentration aqueous or anhydrous formulations with minimal emulsifier content. Water-based peptide serums in United States prestige channels require sophisticated preservation systems to prevent degradation.
- Cream:Emulsion-based vehicles combining oil and water phases for sustained release. Retinoid creams in Germany demand lipid stabilization expertise from suppliers like Croda International to maintain potency.
- Gel:Hydrocolloid matrices favored for oil-control and acne-adjacent positioning. Lightweight texture appeals to teen and male segments in United Kingdom and France.
- Emulsion:Dual-phase systems enabling incompatible active co-delivery. Micro-emulsion technology for peptide-retinoid combinations attracts R&D investment from biotechnology platforms.
Serums command the highest active loading premiums while emulsions attract the most formulation patent activity.
Consumer Type:
Demographic targeting shapes concentration thresholds, claim substantiation requirements, and channel selection for finished goods distribution.
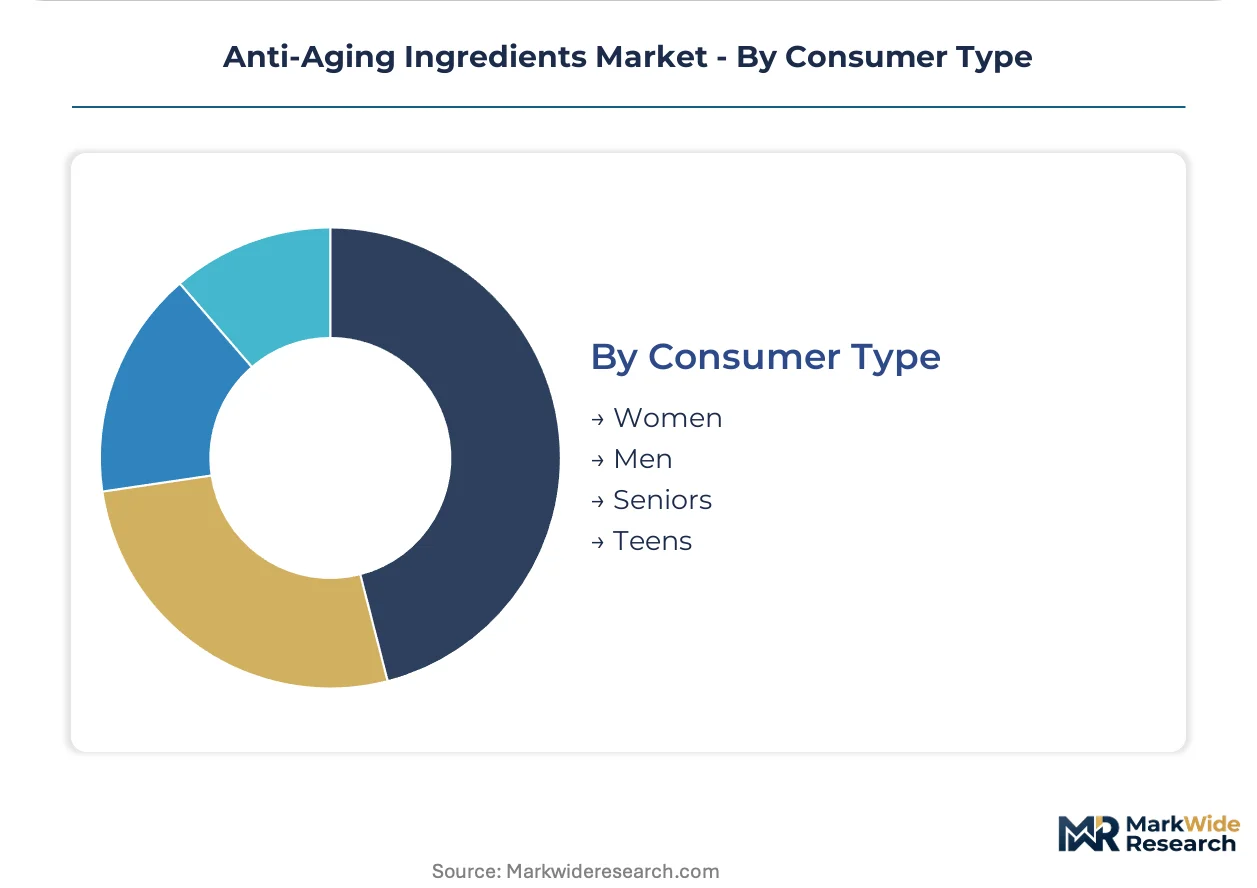
- Women:Core demographic driving peptide and retinoid innovation in prestige and clinical channels. United States women over 35 represent the most intensively targeted segment for dermatology-backed subscription models.
- Men:Underpenetrated segment where barrier repair and fatigue-recovery narratives outperform traditional anti-wrinkle positioning. Germany and United Kingdom present whitespace for peptide formulations in male grooming.
- Seniors:Consumers over 65 requiring gentler active concentrations and enhanced moisturization support. Regulatory caution in Japan under PMDA guidance limits retinoid strength in mass-market products.
- Teens:Preventive and acne-adjacent positioning with lower active concentrations. Social media influence drives rapid trial in United States and United Kingdom, though dermatological supervision remains limited.
Women anchor the revenue base while men represent the most underexploited expansion corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Cosmetics Regulation disclosure mandates and FDA Modernization of Cosmetics Regulation Act facility registration requirements are reshaping supplier qualification protocols across the United States, Germany, China, Japan, and France.
United States
Dermatology-backed direct-to-consumer brands in New York and California command premium positioning through peptide and retinoid concentration disclosure with clinical citation. FDA adverse event reporting requirements under MoCRA impose pharmaceutical-grade lot traceability standards on cosmetic manufacturers importing active ingredients. The Greater Boston biotechnology corridor anchors fermentation-derived peptide capacity serving prestige skincare brands.
Germany
REACH nanomaterial classification for nano-scale hyaluronic acid and lipid carriers creates compliance friction in Düsseldorf and Frankfurt formulation centers. ECHA SCIP database obligations force full substance origin documentation requests from peptide and retinoid suppliers. Bavaria's chemical manufacturing belt concentrates cGMP-certified fermentation capacity for pharmaceutical-grade active production.
China
NMPA registration pathways for imported cosmetic raw materials create first-mover advantage for suppliers investing in Asia-Pacific compliance infrastructure ahead of competitor entry. Shanghai and Guangzhou serve as entry hubs for peptide and retinoid actives requiring safety substantiation dossiers. The Yangtze River Delta anchors domestic fermentation capacity expanding into cosmetic-grade hyaluronic acid production.
Japan
PMDA guidance limits retinoid strength in mass-market products targeting consumers over 65, constraining formulation options for preventive skincare lines. METI standards govern cosmetic manufacturing facility registration and quality management systems. The Kanto region around Tokyo concentrates R&D investment in signal peptide development for clinician-endorsed brands.
France
ANSM oversight of cosmetic safety substantiation elevates demand for analytically validated active compounds with documented mechanistic pathways in Paris and Lyon pharmacy channels. CSRD supply chain due diligence requirements accelerate documentation requests from peptide suppliers. The Île-de-France region anchors prestige brand headquarters driving procurement of pharmaceutical-grade carrier peptides.
Anti-Aging Ingredients Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with biotechnology platforms, creating tiered competition between integrated fermentation operators and specialized peptide synthesis houses. BASF, Croda International, and Lonza Group anchor the top tier through captive strain development, lipid stabilization expertise, and pharmaceutical-grade purity standards respectively. Competitive moves concentrate on cGMP capacity expansion and ISO 16128 certification acquisition to meet EU natural and organic claim requirements.
Within the integrated biotechnology tier, BASF leverages fermentation-derived peptide supply chains from strain development through commercial scale. Croda International occupies a position where lipid and surfactant expertise underpins retinoid stabilization in finished formulations. Lonza Group sits within the synthetic peptide manufacturing niche where pharmaceutical-grade purity standards intersect with cosmetic efficacy demands. These three entities exemplify how vertical control over biological production platforms separates premium-tier suppliers from commodity-grade competitors facing hyaluronic acid price compression.
| Leading Market Players |
|---|
| BASF |
| Adeka Corporation |
| Contipro |
| BioThrive Sciences |
| Kao Corporation |
| Croda International |
| Wacker Chemie |
| Lonza Group |
| Dow Chemical |
| Others |
Supply Flow & Price Mechanics
Twenty-four to thirty-six month lead times for pharmaceutical-grade peptide qualification are compressing margin flexibility for brands without captive fermentation capacity or long-term offtake agreements with cGMP-certified suppliers. This inventory reality concentrates pricing power among biotechnology platforms with backward-integrated strain development, while forcing smaller formulators toward spot-market hyaluronic acid grades with thinner economic buffers.
Pricing Analysis
Certification level creates the primary spread between commodity-grade and pharmaceutical-tier active ingredients. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 16128 natural-origin verification, REACH nanomaterial compliance documentation, and FDA MoCRA facility registration status. Cost compression in mass-market hyaluronic acid is intensifying because Chinese fermentation capacity expansion outpaces prestige-grade peptide demand growth. Direct-to-consumer dermatology brands exhibit lowest price sensitivity due to concentration-disclosure premiums, while mass-market retailers in Germany and France drive hardest bargain on undifferentiated antioxidant grades.
Supply Chain Analysis
Strategic stockpiling of retinoid precursors and carrier peptide intermediates dominates procurement behavior among United States and Swiss prestige brands facing allocation risk from specialty chemical manufacturers. Supply concentrates in Germany for cGMP fermentation capacity, Switzerland for pharmaceutical-grade peptide synthesis, and China for hyaluronic acid fermentation feedstocks. Raw material dependencies include isotretinoin precursors, amino acid feedstocks for peptide synthesis, and lipid stabilizers for retinoid formulation. Single-source vulnerability in tretinoin precursor supply exposes formulators to input cost volatility. Distribution runs through regional formulation centers in Düsseldorf, Lyon, and New Jersey serving direct-to-consumer and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where cGMP certification and ISO 16128 analytical validation create switching costs that lock in incumbent supplier relationships across multi-year procurement cycles.
For Market Incumbents: Compound defensive positioning through captive strain development capacity in Bavaria and Greater Boston biotechnology corridors while accelerating ISO 16128 certification acquisition ahead of EU Cosmetics Regulation disclosure mandate expansion. Bakuchiol and fermented active substitution threats in European clean beauty channels demand mechanistic narrative investment to sustain retinoid and peptide premium positioning. For New Entrants and Emerging Players: Differentiate on microbiome-convergent personalization services and custom peptide blending capabilities targeting male grooming whitespace in Germany and United Kingdom where barrier repair claims face lower regulatory friction than traditional anti-wrinkle positioning. NMPA registration pathway optimization for China's Yangtze River Delta cosmetic manufacturing cluster offers first-mover advantage ahead of competitor infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade fermentation capacity as cGMP certification requirements extend qualification timelines and compress available manufacturing slots. Acquisition targets should demonstrate captive strain development pipelines, existing FDA MoCRA facility registration, and contracted offtake relationships with United States direct-to-consumer brands. Watch for ECHA nanomaterial classification rulings on cross-linked hyaluronic acid as signal for reformulation cost inflection across European supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Capacity Expansion | Pharmaceutical-grade fermentation slots at Bavarian facilities command eighteen-month advance booking premiums from peptide suppliers. |
| ISO 16128 Certification Acquisition | Carbon-14 testing protocol validation unlocks natural-origin claim premiums in French and German pharmacy channels. |
| NMPA Registration Pathway Investment | Shanghai compliance infrastructure enables first-mover supply relationships with Yangtze River Delta cosmetic manufacturers. |
| Backward Integration into Strain Development | Captive biotechnology platforms control peptide supply chains from gene sequence to commercial fermentation scale. |
| Microbiome-Convergent Personalization Launch | Skin analysis subscription models capture lifetime value through recurring custom peptide formulation services. |
Methodological Framework
A standing panel of fermentation process engineers, cosmetic regulatory affairs directors, peptide procurement managers at prestige brands, and dermatology clinic formulary specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance registration databases, FDA MoCRA facility registration filings, NMPA cosmetic raw material safety substantiation dossiers, and customs trade data on amino acid and retinoid precursor flows. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed capacity expansions at cGMP-certified manufacturing sites.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled ingredient type, molecular mechanism, delivery vehicle formulation, end-user demographic, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating prestige brand procurement cycle timing and mass-market channel inventory turnover patterns. Industry-specific forecast inputs included peptide synthesis patent estate expiration schedules and REACH nanomaterial classification ruling probabilities.
Material uncertainties — ECHA nanomaterial reclassification, NMPA registration pathway timeline shifts, retinoid precursor supply allocation disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding cGMP capacity expansion completion and ISO 16128 certification adoption rates without guarantee of regulatory body ruling consistency. Revision becomes warranted when carrier peptide IP litigation outcomes or FDA adverse event reporting threshold modifications cross materiality thresholds for supplier qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Trait Enhanced Oils Market
Ingredients
Mastic Gum Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Plant Based Thickener Market
Ingredients
Lime Seed Oils Market
Ingredients
Sesame Oil Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Orange Powder Market
Ingredients
Feed Premix Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Global Bioactive Ingredients Market