
 Asia-Pacific Fruit and Vegetable Ingredient Market | 2026-2036
Asia-Pacific Fruit and Vegetable Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fruit and Vegetable Ingredient Market Outlook
Market Context
The capital-intensity divergence between integrated processors and ingredient traders is bifurcating competitive dynamics across the region. Kerry Group plc leverages its spray-drying and extraction infrastructure to sustain long-term contracts with multinational beverage brands. Cargill, Incorporated anchors its position through backward integration into tropical fruit sourcing networks in Thailand and Indonesia. Sensient Technologies Corporation differentiates via colorant specialization, occupying premium slots in Japanese confectionery and dairy applications.
Technical Definition and Segments
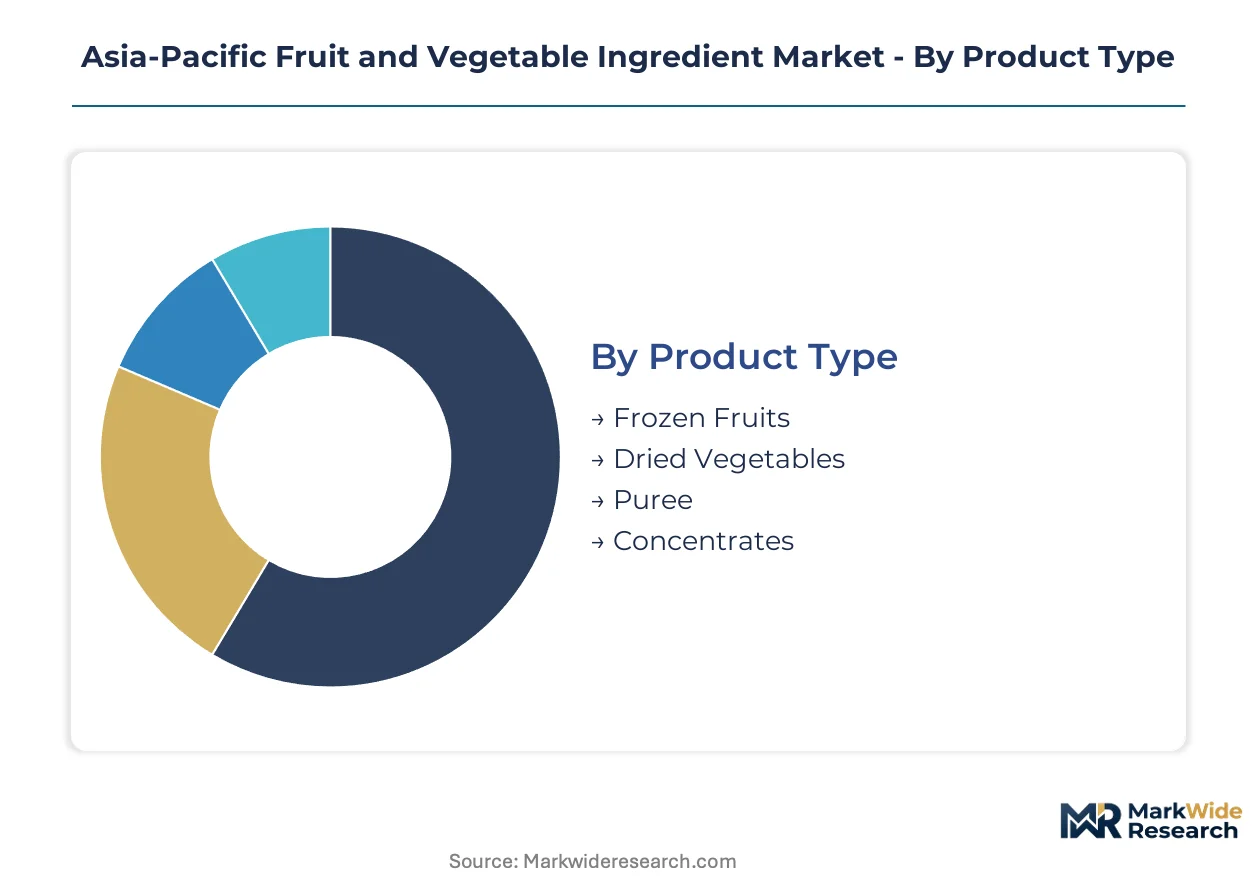
Asia-Pacific fruit and vegetable ingredients encompass minimally processed plant-derived inputs including frozen fruits, dried vegetables, purees, and concentrates, typically standardized to brix levels, particle size distributions, and microbiological specifications for industrial formulation. These ingredients serve as functional carriers of flavor, color, nutrition, and shelf-life extension in packaged foods and beverages. Concentrates command the deepest margin pools due to extraction complexity and transportation economics, while purees are gaining fastest in infant nutrition and smoothie formulations across Australian and Chinese markets. Frozen fruits retain structural leadership in bakery and dairy applications where cellular integrity determines finished product texture.
Regulatory Outlook
Japan's Ministry of Health, Labour and Welfare enforces stringent maximum residue limits for agricultural chemicals, while China's SAMR mandates comprehensive food ingredient registration and labeling transparency under revised food safety protocols. Australia's FSANZ and New Zealand's MPI coordinate trans-Tasman standards for novel fruit and vegetable extracts entering functional food categories. Stakeholders must monitor evolving alignment between ASEAN harmonized standards and individual member state import requirements to secure uninterrupted market access.
Market Dynamics
Traceability mandates from China's SAMR and Japan's positive list system are forcing ingredient processors to deploy blockchain-enabled batch tracking across tropical fruit sourcing networks in Thailand and Indonesia.
Growth Catalysts
- ASEAN Harmonized Standards:Regulatory alignment across Southeast Asian trade corridors reduces cross-border certification duplication for concentrate exporters serving Vietnamese and Philippine beverage plants.
- Infant Nutrition Reformulation:Chinese and Australian dairy processors are substituting synthetic additives with vegetable-derived colorants in follow-on formula production lines.
- Maharashtra-Gujarat Processing Corridor:India's food manufacturing belt concentrates demand for standardized fruit purees supplying domestic bakery and confectionery chains.
Market Restraints
- Monsoon-Dependent Mango Concentrate Supply:Indian and Thai processors face yield volatility from irregular rainfall patterns affecting Alphonso and Nam Dok Mai harvest cycles.
- Refrigerated Container Capacity Constraints:Port congestion at Tanjung Priok and Laem Chabang limits frozen durian and rambutan export volumes to Chinese mid-autumn festival demand windows.
- Enzymatic Browning Control Costs:Ascorbic acid and citric acid dipping protocols add processing overhead for fresh-cut tropical fruit suppliers serving Japanese retail channels.
Strategic Opportunities
- Vietnamese Cold Chain Expansion:Northern provinces around Hanoi lack blast-freezing infrastructure for lychee and longan exports to South Korean convenience store networks.
- South Korean Functional Food Channel:MFDS novel food approvals create entry paths for Australian native fruit extracts in beauty-from-within supplement formulations.
- Indonesian Palm Oil Substitution:Coconut and jackfruit fat fractions offer clean-label alternatives for bakery shortening applications in halal-certified product lines.
Industry Challenges
- Microbiological Validation Bottlenecks:Pathogen testing protocols for thermophilic spore-forming bacteria in tropical fruit purees extend batch release timelines at third-party laboratories.
- Legacy ERP Integration:Smallholder cooperative management systems in Indonesian papaya and pineapple supply chains resist interoperability with processor traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fruit and Vegetable Ingredient Market |
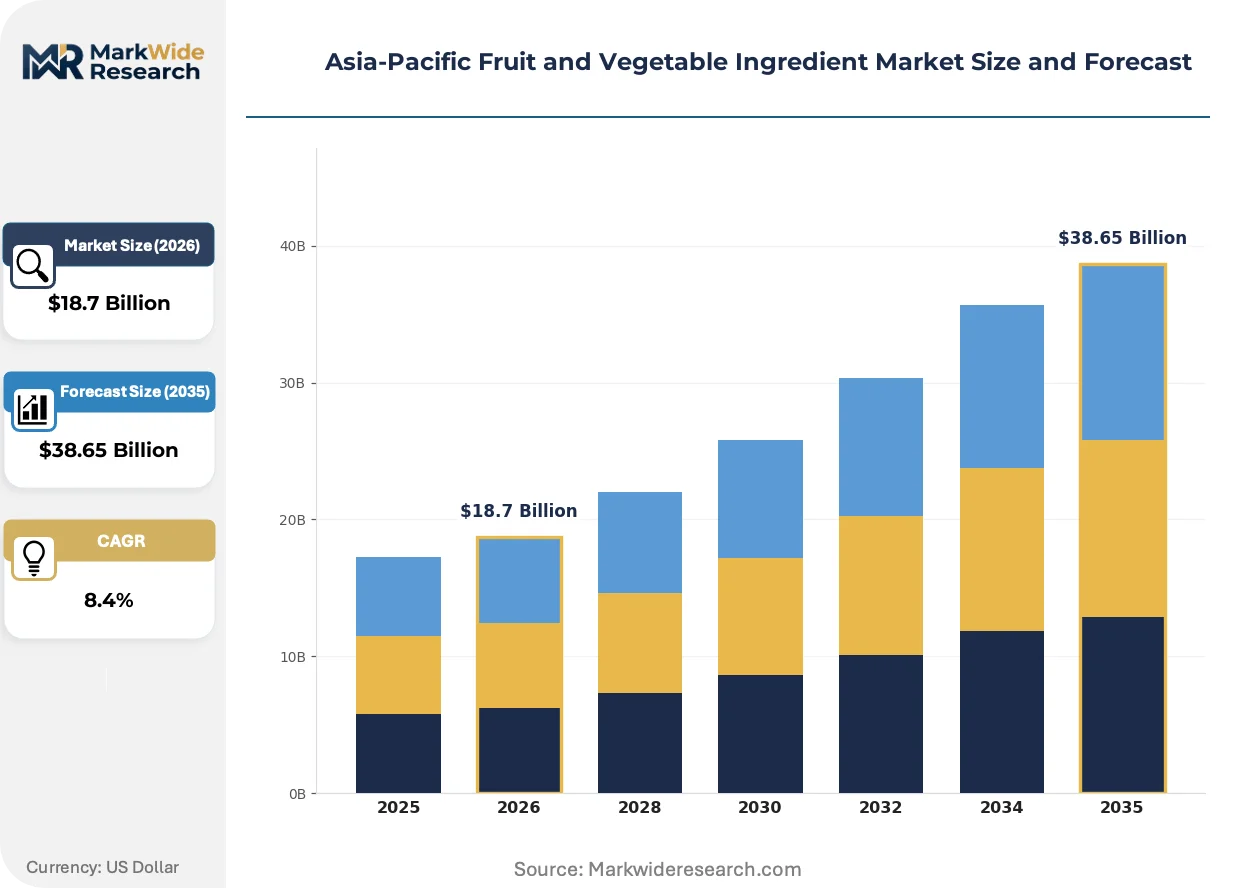
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fruits, Dried Vegetables, Puree, Concentrates End User: Food Processing, Bakery, Beverages, Dairy Application: Flavors, Nutritional Enhancers, Colorants, Natural Preservatives Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Kerry Group plc, SunOpta, Archer Daniels Midland Company, Yaax International, Sensient Technologies Corporation, AGRANA Beteiligungs-AG, Cargill, Incorporated, Kinoko-Tech, Döhler Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fruit and Vegetable Ingredient Market Strategic Shifts
Processing technology is compressing extraction timelines while regulatory pressure on residue testing intensifies specification stringency across the Asia-Pacific sourcing base.
High-pressure processing (HPP) equipment is miniaturizing from industrial-scale 600-liter vessels to 100-liter modular units suitable for regional juice co-packers in Malaysia and Thailand. Mid-tier beverage brands in Jakarta and Bangkok are adopting these systems to extend refrigerated shelf life without thermal degradation of volatile aromatic compounds. The technology is miniaturizing capital barriers, enabling contract manufacturers to offer toll-processing services that previously required integrated plant investments.
Japan's positive list system for agricultural chemicals now mandates testing for 1,015 active ingredients in imported fruit concentrates, expanded from 799 substances in prior protocols. Chinese exporters to Japanese confectionery houses must maintain dual-certified laboratories capable of detecting quinolone and neonicotinoid residues at parts-per-billion thresholds. Infant nutrition and premium dairy applications bear the heaviest compliance burden, with some processors diverting lower-grade concentrates to Southeast Asian markets with less stringent MRL enforcement.
Direct procurement relationships between Australian smoothie chains and Vietnamese dragon fruit cooperatives are displacing traditional trader intermediaries in Ho Chi Minh City's wholesale markets. End-users now conduct quarterly farm audits and pre-harvest contracting rather than spot-market purchasing. This pattern concentrates most visibly in Sydney and Melbourne's cold-pressed juice segment, where brands market provenance transparency as a competitive differentiator against mass-market concentrates.
Asia-Pacific Fruit and Vegetable Ingredient Market Segmentation
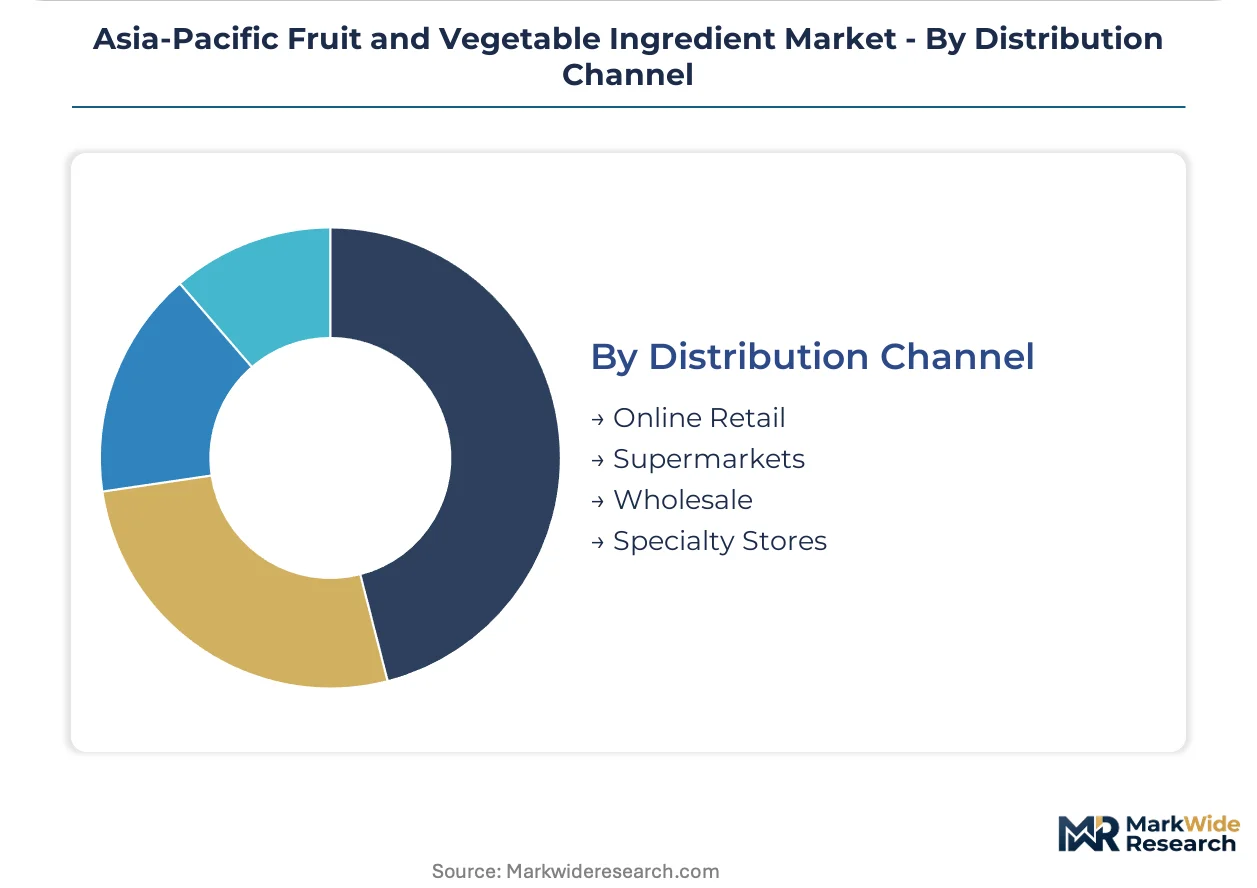
Channel configuration across the Asia-Pacific fruit and vegetable ingredient market determines how specification tiers reach end-users. Industrial buyers in beverage and dairy sectors favor direct procurement from processors, while smaller food manufacturers rely on wholesale intermediaries for standardized inventory.
Product Type:
Channel-mix dynamics vary sharply by processing intensity and shelf stability requirements. Frozen and refrigerated products flow through cold-chain-dependent routes to bakery and dairy manufacturers, while ambient-stable concentrates and dried formats penetrate broader wholesale networks serving regional food processors.
- Concentrates:Reduced-moisture extracts standardized to specific brix levels and acid ratios for industrial formulation. Japanese confectionery houses and Chinese dairy processors absorb premium-grade volumes, with residue testing protocols under Japan's positive list system filtering supplier eligibility. Margin concentration reflects extraction complexity and dual-certified laboratory requirements for export-grade certification.
- Puree:Single-strength or concentrated fruit and vegetable mashes retaining fibrous structure for texture-critical applications. Australian smoothie chains and Chinese infant nutrition manufacturers drive procurement, with direct farm relationships displacing traditional trader intermediaries in Vietnamese dragon fruit sourcing networks.
- Frozen Fruits:IQF-processed tropical and temperate varieties maintaining cellular integrity for bakery inclusions and dairy toppings. Port congestion at Tanjung Priok and Laem Chabang constrains export volumes to Chinese seasonal demand windows.
- Dried Vegetables:Dehydrated formats for soup bases, seasoning blends, and shelf-stable convenience foods. Maharashtra-Gujarat processing corridor concentrates domestic supply for Indian food manufacturing.
Concentrates dominate installed base. Puree is where expansion concentrates.
End User:
Cost-tier stratification separates formulation-grade ingredient buyers from commodity purchasers. Premium beverage and dairy processors absorb specification-intensive concentrates with full traceability documentation, while mass-market food processors prioritize price-stable dried and frozen formats.
- Beverages:Juice, nectar, and functional drink manufacturers requiring clarified concentrates and aromatic extracts. Southeast Asian procurement expansion concentrates in Thai and Indonesian tropical fruit networks, with blockchain-enabled batch tracking satisfying China's SAMR traceability mandates.
- Dairy:Yogurt, ice cream, and infant formula producers utilizing fruit preparations and vegetable-derived colorants. Chinese and Australian processors lead reformulation away from synthetic additives in follow-on formula production lines.
- Food Processing:Ready-meal, sauce, and condiment manufacturers sourcing standardized vegetable bases and fruit inclusions. ASEAN harmonized standards reduce cross-border certification duplication for corridor exporters.
- Bakery:Bread, pastry, and confectionery producers requiring moisture-controlled fruit pieces and fat fraction alternatives. Indonesian halal-certified product lines drive coconut and jackfruit substitution for palm oil-derived shortenings.
Beverage absorption leads volume. Dairy commands specification premiums.
Application:
Margin distribution tracks functional complexity and regulatory scrutiny intensity. Colorants and nutritional enhancers carry compliance burdens from Japan's MHLW residue limits and China's SAMR registration protocols, while natural preservatives compete on cost against synthetic alternatives.
- Colorants:Anthocyanin, carotenoid, and chlorophyll-derived pigments for visual appeal in confectionery and dairy. Japanese positive list expansion to 1,015 active ingredients elevates testing costs for concentrate exporters.
- Nutritional Enhancers:Vitamin, mineral, and fiber fortification systems for functional food positioning. South Korean MFDS novel food approvals create entry paths for Australian native fruit extracts in beauty-from-within formulations.
- Flavors:Volatile aromatic compounds and taste modulators for beverage and snack applications. High-pressure processing miniaturization enables regional Malaysian and Thai co-packers to extend refrigerated shelf life without thermal degradation.
- Natural Preservatives:Organic acid and plant extract systems for clean-label shelf-life extension. Enzymatic browning control costs for fresh-cut tropical fruit add processing overhead in Japanese retail channels.
Colorants anchor premium positioning. Nutritional enhancers gain share fastest.
Distribution Channel:
Customer-type segmentation separates industrial direct procurement from fragmented retail and foodservice routing. Large-scale manufacturers negotiate annual contracts with integrated processors, while mid-tier buyers depend on wholesale aggregation for inventory flexibility.
- Wholesale:Industrial distributors consolidating bulk volumes for food manufacturers across the Asia-Pacific sourcing base. Maharashtra-Gujarat corridor concentration supports Indian domestic bakery and confectionery chain supply.
- Online Retail:B2B platforms and ingredient marketplaces connecting small-batch buyers with regional processors. Vietnamese cold chain gaps around Hanoi limit lychee and longan export penetration to South Korean convenience networks.
- Supermarkets:Retail chains stocking consumer-format frozen and dried ingredients. Australian and Chinese urban markets concentrate premium positioning for provenance-marketed smoothie components.
- Specialty Stores:Gourmet and health-food retailers curating organic and native variety selections. Sydney and Melbourne cold-pressed juice segments market farm-audit transparency as competitive differentiation.
Wholesale commands industrial volume. Online retail captures emerging buyer fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific diverge sharply by end-use intensity. Chinese beverage manufacturers absorb concentrate volumes at scale, while Japanese buyers prioritize residue-tested grades for premium applications. Australian processors lead direct farm contracting for provenance-marketed formats.
China
Beverage and dairy sectors drive concentrate procurement through direct processor relationships. SAMR mandates comprehensive ingredient registration and blockchain-enabled traceability across tropical fruit sourcing networks. The Yangtze River Delta concentrates cold-pressed juice manufacturing where brands substitute synthetic additives with vegetable-derived colorants.
Japan
Confectionery and infant nutrition manufacturers command premium-grade concentrates with full agricultural chemical documentation. MHLW enforces testing for 1,015 active ingredients under expanded positive list protocols. Kanto region dairy processors divert lower-grade concentrates to Southeast Asian markets while retaining laboratory-certified volumes for domestic formulation.
India
The Maharashtra-Gujarat processing corridor concentrates demand for standardized fruit purees supplying domestic bakery and confectionery chains. FSSAI alignment with CODEX standards streamlines export certification for Alphonso mango concentrate shipments. Monsoon-dependent harvest cycles create yield volatility that processors hedge through pre-harvest contracting.
Vietnam
Dragon fruit and lychee cooperatives supply direct procurement relationships with Australian smoothie chains and South Korean convenience networks. Cold chain gaps around Hanoi limit blast-freezing infrastructure for longan exports. Ho Chi Minh City wholesale markets face displacement as end-users conduct quarterly farm audits and bypass traditional trader intermediaries.
Thailand
Nam Dok Mai mango and durian processors serve Chinese mid-autumn festival demand windows through refrigerated container shipments. Port congestion at Laem Chabang constrains frozen tropical fruit export volumes. Regional juice co-packers adopt miniaturized high-pressure processing equipment to extend refrigerated shelf life without thermal degradation.
Asia-Pacific Fruit and Vegetable Ingredient Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific fruit and vegetable ingredient market. The upper tier controls extraction infrastructure and maintains backward integration into tropical sourcing networks. Mid-scale players occupy niche positions in colorant specialization or regional co-packing services. Competitive moves concentrate on strategic partnerships for cold chain access and portfolio diversification into clean-label preservative alternatives.
Within the integrated processing tier, Kerry Group plc and Cargill, Incorporated exemplify capital-intensive infrastructure operators sustaining long-term contracts with multinational beverage brands. Sensient Technologies Corporation occupies a specialist position in colorant applications for premium confectionery and dairy segments. These three entities anchor distinct competitive vectors—integrated extraction networks, tropical sourcing control, and premium formulation-grade specialization—while smaller regional processors compete on toll-processing flexibility and direct farm relationship proximity.
| Leading Market Players |
|---|
| Kerry Group plc |
| SunOpta |
| Archer Daniels Midland Company |
| Yaax International |
| Sensient Technologies Corporation |
| AGRANA Beteiligungs-AG |
| Cargill, Incorporated |
| Kinoko-Tech |
| Döhler Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Thai mango processors and Chinese beverage manufacturers lock in both supply access and price visibility across the 8.40% CAGR expansion window, insulating buyers from monsoon-driven yield volatility while committing processors to residue-testing investments for Japan-bound grades.
Pricing Analysis
Long-term offtake agreements dominate concentrate procurement, with premium-mid-economy pricing differentiation separating laboratory-certified export grades from corridor-standard volumes. Price differentiation hinges on dual-certified testing capacity for Japan's positive list and volume scale commitments from Yangtze River Delta dairy processors. Cost compression in standard-grade purees is intensifying because Vietnamese cold-pressed juice brands bypass traditional trader markups through direct farm contracting. Mass-market food processors show highest price sensitivity, while infant nutrition manufacturers absorb specification premiums.
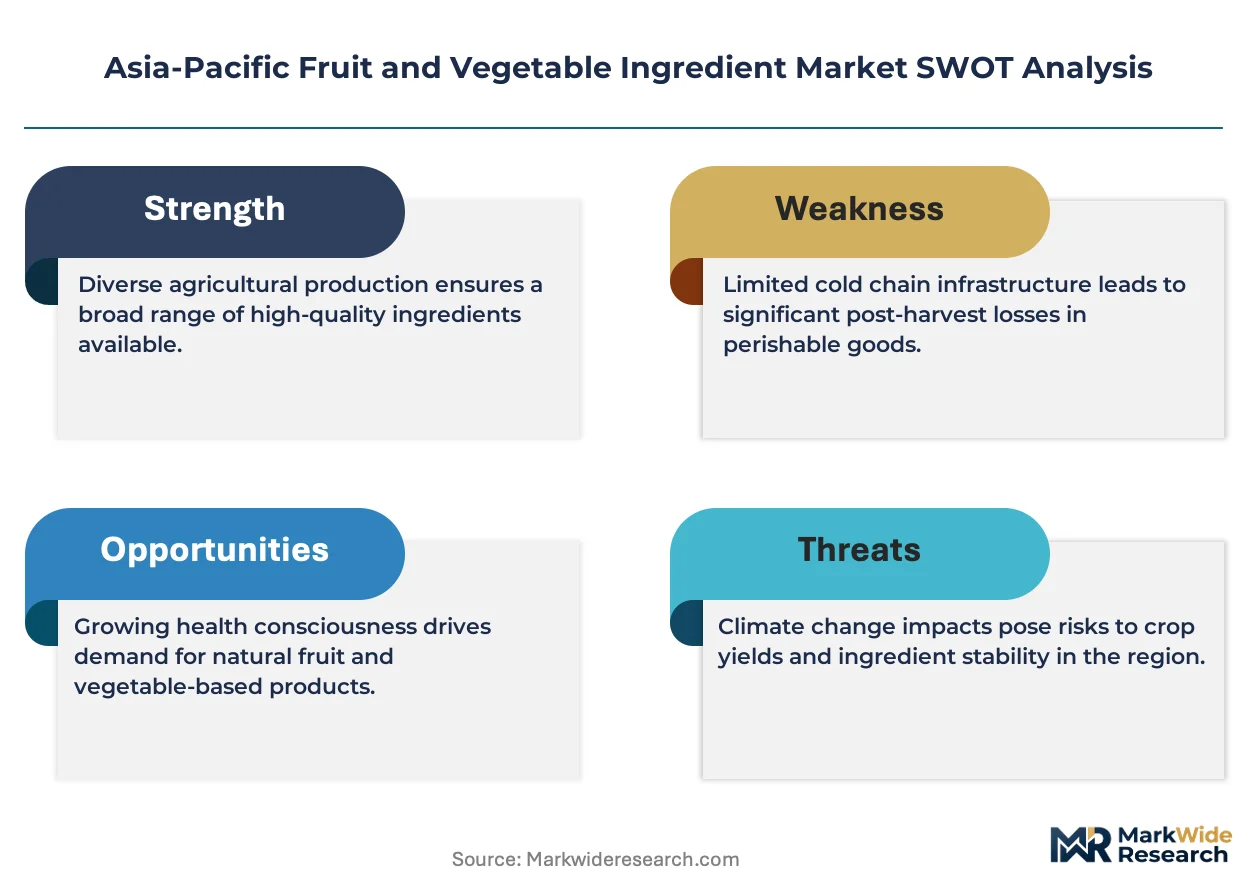
Supply Chain Analysis
Thailand and Indonesia anchor tropical fruit concentrate production, with India supplying Alphonso mango derivatives through the Maharashtra-Gujarat processing corridor. Raw material flows draw from Nam Dok Mai orchards, dragon fruit cooperatives around Ho Chi Minh City, and lychee plantations in northern Vietnam. Single-source vulnerability concentrates in refrigerated container capacity at Laem Chabang and Tanjung Priok. Distribution runs through direct processor relationships for industrial buyers and wholesale aggregation for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability mandates from China's SAMR are accelerating procurement restructuring, creating asymmetric advantage for processors with integrated laboratory certification and backward sourcing control.
For Market Incumbents: Fortify extraction infrastructure through spray-drying capacity additions in Thai and Indonesian sourcing networks. Invest in dual-certified testing laboratories to defend margin position against emerging regional co-packers adopting miniaturized HPP equipment. Channel control over cold-pressed juice toll-processing services represents the priority defensive lever.
For New Entrants and Emerging Players: FSSAI-CODEX alignment certification fast-tracks entry into Indian bakery and confectionery supply chains through the Maharashtra-Gujarat corridor. White-space concentrates in Vietnamese blast-freezing infrastructure gaps around Hanoi for lychee and longan exports. Target South Korean convenience store networks with direct farm audit capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Regional co-packers with modular HPP equipment and provenance-marketed direct farm relationships represent the optimal acquisition target archetype. Long-term viability over the analysis window hinges on clean-label substitution momentum in halal-certified bakery applications. Monitor MFDS novel food approval velocity for Australian native fruit extracts as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Sourcing | Cargill's Thai and Indonesian network control secures concentrate supply for multinational beverage contracts. |
| Dual-Certified Laboratory Investment | Kerry Group's residue-testing capacity satisfies Japan's expanded positive list for 1,015 active ingredients. |
| Modular HPP Equipment Deployment | Malaysian and Thai co-packers extend refrigerated shelf life without thermal degradation of volatile compounds. |
| Direct Farm Contracting Expansion | Australian smoothie chains displace Ho Chi Minh City trader intermediaries through quarterly farm audits. |
| Clean-Label Halal Certification | Indonesian coconut and jackfruit fat fractions substitute palm oil in bakery shortening applications. |
Study Parameters
The analysis maps concentrates, purees, frozen fruits, and dried vegetables, each validated through procurement directors at beverage and dairy processors, quality assurance leads at infant nutrition manufacturers, cold chain logistics coordinators, and regulatory affairs specialists at export-oriented cooperatives. Primary interview findings triangulate against customs and trade data from ASEAN member states, FSSAI export certification records, SAMR food safety protocol documentation, and MHLW positive list amendments. Bottom-up volume estimates from processor capacity utilization cross-check with top-down consumption projections from end-use sector absorption rates.
Consistency checks validate outputs against external benchmarks across the projection horizon, with segmentation modeling across product type, end user, application, and distribution channel dimensions. CAGRs derive from fitted growth curves incorporating monsoon yield volatility patterns, refrigerated container capacity constraints at major Southeast Asian ports, and enzymatic browning control cost trajectories. Industry-specific inputs include pre-harvest contracting penetration rates and blockchain traceability adoption curves among Thai and Indonesian sourcing networks.
Underlying assumptions cover regulatory alignment between ASEAN harmonized standards and member state import protocols, with deviation risk concentrated in MHLW positive list expansion velocity and SAMR blockchain mandate enforcement intensity. Recalibration cycles align with material shifts in tropical fruit harvest yields, cold chain infrastructure investments, and novel food approval pathways in South Korean functional food channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Grapes Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Organic Bananas Market