
 Hydrogenated Palm Oil Market | 2026-2036
Hydrogenated Palm Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenated Palm Oil Market Foresight
The divergence between premium and commodity tiers in hydrogenated palm oil is hardening as food manufacturers demand certified sustainable grades while bulk buyers prioritize cost efficiency. Wilmar International Limited leverages its integrated plantation-to-refinery footprint across Indonesia and Malaysia to secure supply continuity. Cargill Incorporated differentiates through specialty lipid formulations tailored to European bakery specifications. Musim Mas anchors its position with RSPO-certified output streams that command premium positioning in conscientious procurement channels.
Hydrogenated palm oil is refined, bleached, and deodorized palm oil subjected to catalytic hydrogenation, typically achieving iodine values below 35 to produce semi-solid or fully solid fats with enhanced oxidative stability and extended shelf life. The process saturates unsaturated fatty acids, yielding products with melting points between 35°C and 55°C suited to structured food applications requiring plasticity and heat resistance. Solid and semi-solid product types dominate volume throughput, though powder formats are gaining traction in industrial dry-mix applications where dispersion uniformity matters. Within applications, margarine and bakery products absorb the largest share of processed volumes, while confectionery represents a higher-margin segment where tempering precision justifies specialized hydrogenation protocols.
Malaysia's Department of Standards enforces MS 814 specifications for edible palm oil products, while Indonesia's National Agency for Drug and Food Control mandates trans-fat disclosure thresholds that reshape formulation choices across ASEAN processing facilities. The EU Deforestation Regulation imposes traceability burdens on exporters seeking access to European food manufacturers, compelling upstream documentation investments. Stakeholders must monitor evolving trans-fat restrictions in major import jurisdictions and calibrate hydrogenation intensity accordingly to preserve market access without sacrificing functional performance.
Market Dynamics
Trans-fat disclosure mandates across ASEAN and European import jurisdictions are forcing reformulation investments that split the hydrogenated palm oil market into compliance-grade and commodity-grade supply tiers.
Growth Catalysts
- EU Deforestation Regulation traceability:European food manufacturers now require documented supply chain provenance, creating premium demand for certified sustainable grades with full upstream documentation.
- Southeast Asian bakery expansion:Margarine and shortening producers in Indonesia and Malaysia are scaling semi-solid hydrogenated palm oil procurement to serve regional processed food manufacturing corridors.
- Interestified fat substitution:Enzymatic interesterification technology enables manufacturers to achieve equivalent functional properties with reduced hydrogenation intensity, preserving market access under tightening trans-fat thresholds.
Market Restraints
- Crude palm oil price volatility:Input cost swings tied to Malaysian ringgit fluctuations and Indonesian export levy adjustments compress margin predictability for refiners operating on fixed-price bakery contracts.
- Peninsular Malaysia supply concentration:Overreliance on processing clusters near Port Klang and Pasir Gudang creates geographic vulnerability to port congestion and localized logistics disruptions.
- High-oleic sunflower oil substitution:European confectionery manufacturers are piloting non-hydrogenated alternatives in premium chocolate applications where tempering precision requirements previously locked in palm-derived formulations.
Strategic Opportunities
- Indian FSSAI trans-fat limits:India's phased reduction of trans-fat content to below 2% by 2025 creates first-mover advantage for exporters with pre-certified low-IV hydrogenation protocols and established cold chain partnerships.
- Powder format industrial dry-mix:Instant noodle and baking premix manufacturers are adopting dispersible hydrogenated palm oil powders to eliminate melting and tempering steps in automated production lines.
- RSPO-certified premium channel expansion:Sustainability-conscious procurement channels in Northern European retail and foodservice segments command price premiums for segregated supply chain documentation.
Industry Challenges
- Specialized hydrogenation engineering talent:Catalytic process optimization and IV target precision require experienced technicians that Malaysian and Indonesian technical institutes are not producing at replacement rates.
- Dual certification timeline compression:Simultaneous pursuit of RSPO supply chain certification and national MS 814 or BIS-equivalent quality compliance strains quality assurance bandwidth at mid-scale refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenated Palm Oil Market |
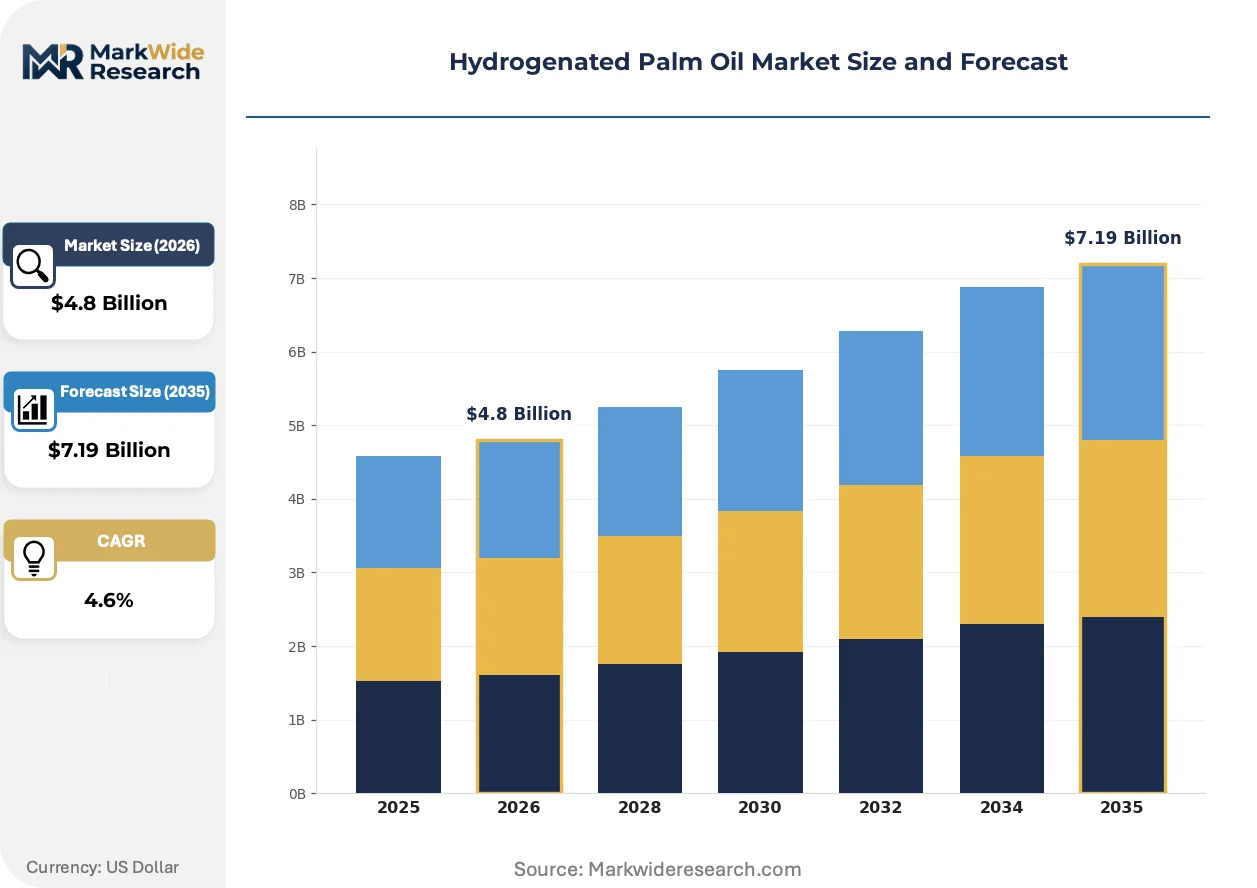
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Semi-Solid, Liquid, Powder Application: Food Processing, Bakery Products, Confectionery, Margarine End User: Food Manufacturers, Snack Producers, Restaurants, Catering Services Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Wilmar International Limited, Golden Agri-Resources Ltd, Kuala Lumpur Kepong Berhad, Sime Darby Plantation Berhad, Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, IOI Group, Musim Mas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenated Palm Oil Market Shifts & Advancements
Elective hydrogenation intensity reduction is becoming the dominant technical response to regulatory pressure, with manufacturers selectively saturating fatty acid profiles rather than maximizing oxidative stability.
Membrane filtration pre-treatment of crude palm oil is overtaking conventional degumming and bleaching sequences as the standard purification pathway. Specialty fat producers in Malaysia are installing ceramic membrane systems to reduce catalyst poisoning and extend hydrogenation reactor cycles. This technology is overtaking legacy refining configurations by enabling lower-temperature hydrogenation runs that preserve heat-sensitive micronutrients while achieving target melting profiles.
Indonesia's National Agency for Drug and Food Control has mandated front-of-pack trans-fat disclosure thresholds that exceed Codex Alimentarius baseline requirements. Domestic margarine manufacturers are reformulating toward iodine values between 35 and 45 to maintain plasticity while staying beneath disclosure triggers. Bakery chains operating across Jakarta and Surabaya are now specifying low-trans contractual grades in procurement tenders, compressing demand for traditionally hydrogenated solid fats.
Bulk buyers in Southeast Asian food manufacturing are consolidating supplier relationships around integrated plantation-refinery operators with captive olein and stearin streams. This concentration is displacing spot market purchasing for hydrogenated derivatives as processors prioritize supply continuity over price optimization. The shift is most visible in Indonesian noodle and biscuit manufacturing clusters where just-in-time fat delivery requirements have eliminated multi-source procurement strategies.
Hydrogenated Palm Oil Market Segmentation
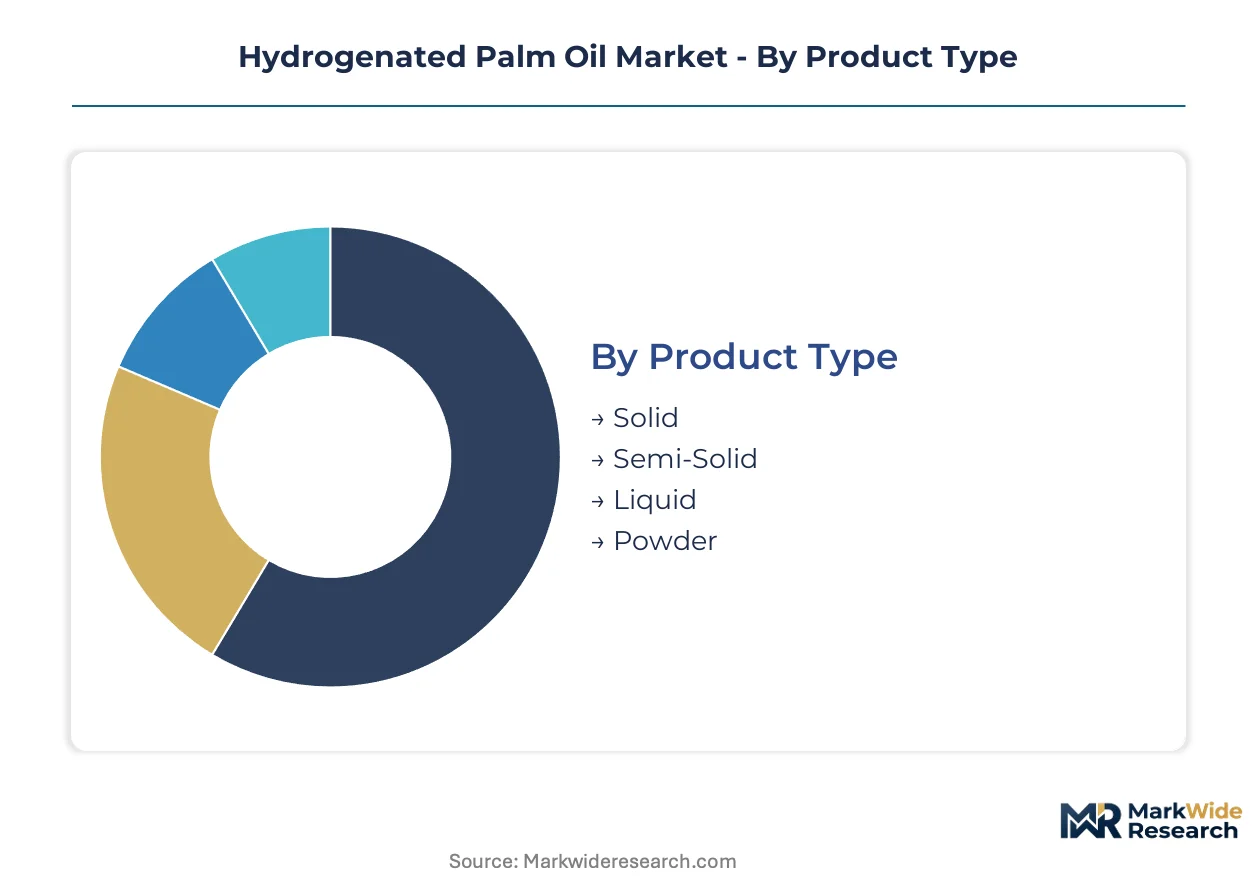
Hydrogenated palm oil markets stratify sharply across physical states and customer tiers, with commodity-grade volumes dominating throughput while certified-sustainable grades capture margin premiums. Understanding these divisions reveals where procurement power concentrates and where formulation specifications diverge most acutely.
Product Type:
Solid and semi-solid grades absorb the bulk of industrial procurement, yet powder formats are gaining traction in automated processing environments where dispersion speed matters.
- Solid:Fully hydrogenated palm oil achieves iodine values below 35, yielding crystalline fats with melting points between 50°C and 55°C. Margarine manufacturers in Indonesian processing corridors specify solid grades for stick formulations requiring sharp melt profiles and extended shelf stability.
- Semi-Solid:Partial hydrogenation produces plastic fats with iodine values between 35 and 55, delivering the workability that Southeast Asian bakery chains demand for laminated dough applications. Malaysian shortening producers near Port Klang are expanding semi-solid procurement to serve regional biscuit manufacturing clusters.
- Liquid:Minimally hydrogenated or fractionated liquid grades retain higher unsaturation for frying and coating applications where pourability at ambient temperatures is essential.
- Powder:Spray-dried and encapsulated formats eliminate melting steps in instant noodle seasoning and dry baking premix production lines, with Indonesian and Malaysian processors piloting automated dispersion systems.
Mature deployment sits with solid and semi-solid grades in conventional margarine and shortening applications. Newer deployment is concentrated in powder formats for industrial dry-mix and instant food manufacturing.
Application:
Volume throughput clusters in mass-market food processing, while confectionery commands specialized hydrogenation protocols that justify premium positioning.
- Food Processing:Broad-category demand spans frying fats, coating mediums, and texture modifiers across Southeast Asian snack and instant food manufacturing, with Indonesian noodle producers representing a concentrated procurement channel.
- Bakery Products:Laminated dough, biscuit, and cake applications require plastic fat functionality that semi-solid hydrogenated palm oil delivers at cost points below butter or tropical alternatives. Malaysian bakery chains operating across Kuala Lumpur and Penang are scaling semi-solid procurement for regional production expansion.
- Confectionery:Tempering-stable fats with precise melting curves enable chocolate and confectionery coating production where snap and gloss specifications are non-negotiable.
- Margarine:Table and industrial margarine formulations absorb substantial hydrogenated palm oil volumes, with reformulation pressures intensifying as Indonesia's National Agency for Drug and Food Control enforces stricter trans-fat disclosure thresholds.
Volume concentration remains heaviest in food processing and bakery applications. Steepest expansion trajectory is emerging in confectionery as European manufacturers seek documented supply chain provenance under EU Deforestation Regulation compliance requirements.
End User:
Procurement scale and specification stringency diverge between integrated food manufacturers and fragmented foodservice operators.
- Food Manufacturers:Integrated processors with captive refining relationships or direct plantation ties command volume pricing and supply continuity guarantees that spot-market purchasers cannot replicate.
- Snack Producers:Indonesian and Malaysian chip, cracker, and extruded snack manufacturers specify frying and coating fats with oxidative stability targets that hydrogenated palm oil meets at lower cost than alternative vegetable oils.
- Restaurants:Commercial frying operations in Southeast Asian urban centers prioritize cost efficiency and extended fry life over certification documentation, sourcing through wholesale distributors rather than direct refinery relationships.
- Catering Services:Institutional foodservice procurement emphasizes shelf-stable shortening and margarine for high-volume baking and food preparation, with specification flexibility enabling commodity-grade sourcing.
Contractual volume commitment is strongest among food manufacturers with integrated supply arrangements. Specification flexibility is widest in catering services where functional performance thresholds permit broader supplier qualification.
Distribution Channel:
Channel selection tracks customer scale and certification requirements, with direct sales capturing premium-tier demand and wholesalers serving price-sensitive volume buyers.
- Direct Sales:Refinery-direct relationships enable RSPO-certified supply chain documentation and customized iodine value specifications that European food manufacturers require for EU Deforestation Regulation compliance.
- Online Retail:E-commerce penetration in specialty and small-batch hydrogenated palm oil remains limited, constrained by bulk packaging requirements and temperature-controlled logistics complexity.
- Wholesalers:Regional distributors in Indonesian Surabaya and Malaysian Johor Bahru aggregate demand from mid-scale processors, offering standardized grades without the documentation burden of direct refinery contracts.
- Specialty Stores:Niche channels serving artisanal bakers and small confectionery producers stock premium and organic-certified grades at price points substantially above commodity benchmarks.
Documentation-intensive procurement flows through direct sales channels. Price-optimized volume purchasing concentrates in wholesaler networks serving Southeast Asian processing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port Klang and Pasir Gudang anchor Southeast Asian hydrogenated palm oil processing, with Malaysian refining corridors handling the majority of regional throughput for bakery and margarine applications.
Malaysia
Semi-solid grade procurement from Malaysian bakery chains operating across Kuala Lumpur and Penang is scaling rapidly. The Department of Standards enforces MS 814 specifications for edible palm oil products. Processing clusters near Port Klang and Pasir Gudang are expanding hydrogenation capacity to serve Indonesian and Thai cross-border demand.
Indonesia
Margarine manufacturers in Jakarta and Surabaya are reformulating toward lower iodine values to meet front-of-pack trans-fat disclosure mandates. The National Agency for Drug and Food Control enforces stricter thresholds than Codex Alimentarius baseline requirements. Noodle and biscuit manufacturing clusters in East Java are consolidating supplier relationships around integrated plantation-refinery operators.
India
FSSAI trans-fat limits are driving first-mover advantage for exporters with pre-certified low-IV hydrogenation protocols. The phased reduction to below 2% trans-fat content by 2025 is reshaping import procurement specifications. Cold chain partnerships from Malaysian and Indonesian refiners are concentrating in Mumbai and Chennai port corridors.
Netherlands
European food manufacturers require documented supply chain provenance under EU Deforestation Regulation traceability rules. Rotterdam serves as the primary entry point for RSPO-certified segregated supply chains destined for Northern European retail channels. Dutch margarine and confectionery formulators are specifying certified sustainable grades with full upstream documentation.
Germany
Bakery and confectionery manufacturers are piloting non-hydrogenated alternatives while maintaining palm-derived formulations for tempering precision applications. REACH and EU Deforestation Regulation compliance burdens are compressing demand for commodity-grade imports. Hamburg and Bremen port facilities are upgrading segregation infrastructure for certified sustainable fat handling.
Hydrogenated Palm Oil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability documentation intensity. The market structures into three tiers: integrated plantation-to-refinery operators with captive feedstock, specialty lipid formulators with customized iodine value capabilities, and commodity refiners serving spot-market bakery contracts. Strategic moves concentrate on backward integration into upstream olein and stearin streams and simultaneous pursuit of RSPO supply chain certification alongside national quality compliance.
Within the integrated operator tier, Wilmar International Limited and Kuala Lumpur Kepong Berhad exemplify plantation-refinery consolidation that secures supply continuity. Cargill Incorporated occupies a position among specialty formulators with European-facing capabilities. Musim Mas anchors the certified-sustainable vector with RSPO-segregated output streams commanding premium positioning in conscientious procurement channels.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Golden Agri-Resources Ltd |
| Kuala Lumpur Kepong Berhad |
| Sime Darby Plantation Berhad |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| IOI Group |
| Musim Mas |
| Others |
Supply & Pricing Matrix
EU Deforestation Regulation traceability mandates are forcing European food manufacturers to specify documented supply chain provenance, compelling Malaysian and Indonesian refiners to invest in upstream certification infrastructure that stratifies pricing across compliance-grade and commodity-grade tiers.
Pricing Analysis
Value-based pricing anchored to iodine value precision and oxidative stability outcomes dominates contract negotiations between Southeast Asian refiners and bakery manufacturers. Three-tier pricing structure across RSPO-certified premium, MS 814-compliant standard, and unlabeled economy grades reflects certification investment differentials. Cost compression in commodity spot markets is intensifying because Indonesian export levy adjustments and Malaysian ringgit volatility squeeze refiner margins on fixed-price bakery contracts. Food manufacturers with integrated plantation ties exhibit lowest price sensitivity, while fragmented catering services operators drive hardest bargaining on volume spot purchases.
Supply Chain Analysis
Indonesia's domestic-content preferences for locally processed palm derivatives and Malaysia's MS 814 enforcement are reshaping sourcing patterns toward integrated plantation-refinery operators with captive olein and stearin streams. Supply concentration centers on Malaysia, Indonesia, and Singapore, with processing clusters near Port Klang and Pasir Gudang handling majority regional throughput. Raw material dependencies rest on crude palm oil feedstock, nickel-based hydrogenation catalysts, and ceramic membrane filtration systems. Single-source vulnerability runs through Peninsular Malaysia's geographic concentration, exposing buyers to port congestion disruptions. Distribution runs through direct refinery contracts for certified grades and regional wholesaler networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration pre-treatment is displacing conventional degumming and bleaching sequences, creating asymmetric opportunity for operators with installed ceramic systems versus legacy refiners facing catalyst poisoning and shortened reactor cycles.
For Market Incumbents: Hedge against enzymatic interesterification substitution by securing backward integration into upstream olein and stearin fractionation capacity. Accelerate RSPO supply chain certification timelines to defend premium positioning as European procurement channels harden documentation requirements under EU Deforestation Regulation enforcement. For New Entrants and Emerging Players: Powder format hydrogenation technology offers entry wedge into instant noodle and baking premix manufacturing corridors where automated dispersion systems eliminate melting steps. Target Indonesian East Java processing clusters where supplier consolidation around integrated operators has displaced spot market relationships, creating white space for documented low-IV protocol specialists. For Investors and Strategic Acquirers: The window for entry favors mid-scale Malaysian refiners with partial certification progress and established Port Klang logistics access. Long-term viability hinges on hydrogenation engineering talent pipelines and dual-certification bandwidth. Watch for FSSAI enforcement acceleration in Indian port corridors as inflection signal for low-trans export demand.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Ceramic pre-treatment systems reduce catalyst poisoning and extend hydrogenation reactor cycles at Malaysian refineries. |
| RSPO Supply Chain Certification | Segregated documentation unlocks premium positioning in Northern European retail and foodservice procurement channels. |
| Low-IV Hydrogenation Protocol Development | Pre-certified iodine value precision preserves market access under tightening ASEAN trans-fat disclosure thresholds. |
| Integrated Plantation-Refinery Expansion | Captive olein and stearin streams secure supply continuity for Indonesian noodle and biscuit manufacturing clusters. |
| Cold Chain Partnership Investment | Temperature-controlled logistics from Malaysian and Indonesian refiners concentrate in Mumbai and Chennai corridors for Indian FSSAI compliance. |
Research Methodology
Independent corroboration across refinery operations managers, bakery procurement leads, and specialty lipid formulators underwrites the qualitative findings on hydrogenation intensity reformulation trends. Secondary validation draws from Malaysian Department of Standards MS 814 documentation, Indonesian National Agency for Drug and Food Control regulatory filings, and EU Deforestation Regulation implementation guidance. Bottom-up volume estimates from processing capacity utilization rates triangulate against top-down demand assessments from margarine and bakery manufacturer procurement surveys.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by physical state, application intensity, and certification tier. Modeled dimensions include solid versus semi-solid versus powder product grades, food processing versus bakery versus confectionery end-uses, and direct sales versus wholesaler channel structures. CAGRs derive from regression analysis of historical feedstock price elasticity and forward procurement contract terms. Industry-specific inputs incorporate hydrogenation reactor cycle efficiency trends and ceramic membrane adoption curves at Malaysian specialty fat producers.
Several conditions sit outside the modeled scope, including abrupt Indonesian export policy reversals, nickel catalyst supply disruptions, and unilateral trans-fat threshold accelerations beyond announced regulatory calendars. Forecasts reflect documented assumptions on membrane filtration cost curves and RSPO certification completion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Proteose Peptone Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
India Soy Protein Market
Ingredients
Resistant Starch Market
Ingredients
Feed Ingredients Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Icing Shortening Market
Ingredients
Soy Protein Isolate Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Almond Flour Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Native Starch Market
Ingredients
Omega 6 Market