
 Multi-Grain Premixes Market | 2026-2036
Multi-Grain Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Grain Premixes Market Foresight
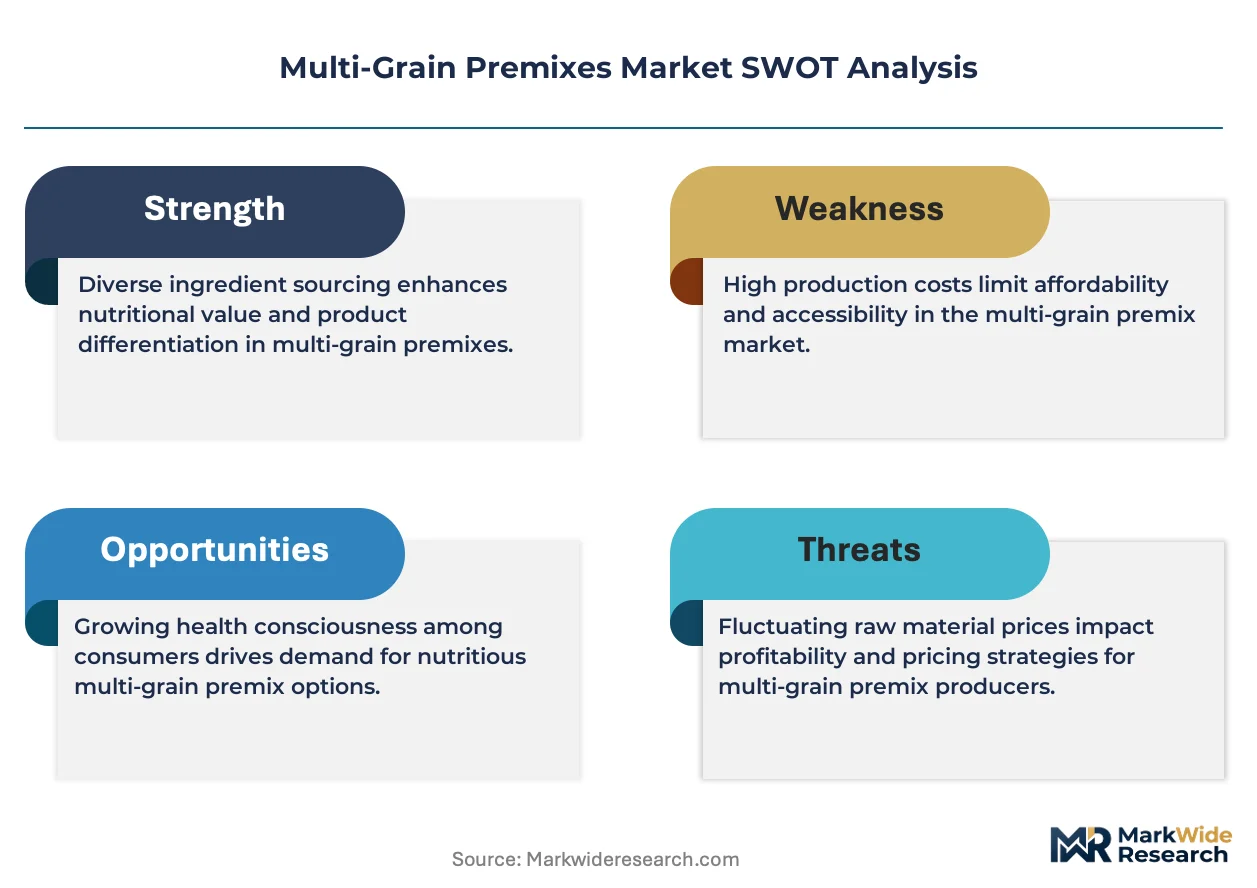
EU Green Deal sustainability criteria is hardening ingredient sourcing standards for multi-grain premix suppliers across Europe. Archer Daniels Midland Company leverages its global grain origination network to secure certified sustainable wheat and oat supplies for European bakery clients. Cargill competes through backward integration into regenerative agriculture programs that reduce Scope 3 emissions in its flour supply chain. Kerry Group differentiates via specialized enzyme technologies that improve whole-grain dough functionality without chemical additives.
Multi-grain premixes constitute pre-formulated dry blends containing two or more cereal grains—typically wheat, oats, rye, barley, or millet—combined with leavening agents, emulsifiers, and functional enzymes at specified ratios for reconstitution with water or dairy. These blends serve commercial bakeries and food manufacturers seeking consistent product quality, reduced batch-to-batch variation, and streamlined production workflows without proprietary formulation expertise. Bread mix and pancake mix categories anchor current revenue pools due to entrenched breakfast and sandwich consumption patterns across food service channels. Whole grains ingredient types are gaining share as clean-label mandates from retail grocery chains and institutional buyers displace refined-flour formulations in premium positioning.
FDA nutrition labeling requirements and USDA whole-grain-rich standards for school meal programs shape product formulation decisions in the United States, while EU REACH and EFSA food additive regulations govern emulsifier and enzyme approvals across European markets. India's FSSAI fortification guidelines and China's GB standards for cereal products add compliance layers for exporters targeting Asia-Pacific growth corridors. Stakeholders must monitor evolving whole-grain certification thresholds and regional fortification mandates to align R&D pipelines with procurement specifications that institutional buyers are rewriting.
Market Dynamics
EU Green Deal sustainability criteria are hardening ingredient sourcing standards, forcing bakery chains across Europe to rewrite procurement specifications for certified sustainable grain supplies while North American institutional buyers accelerate whole-grain-rich compliance for school meal contracts.
Growth Catalysts
- USDA whole-grain-rich standards:School meal programs in the United States mandate minimum whole-grain content, driving institutional bakeries toward pre-formulated multi-grain blends that guarantee compliance without in-house formulation expertise.
- Clean-label mandates from retail grocery chains:European supermarket banners are delisting refined-flour bread mixes, creating pull-through demand for certified clean-label multi-grain formulations with transparent supply chain documentation.
- Sprouted grain processing technology:Advanced enzymatic pre-treatment of sprouted wheat and barley improves dough functionality and nutrient bioavailability, enabling premium positioning in functional bakery segments.
Market Restraints
- Certified organic wheat supply concentration:North American organic grain origination concentrates in the Upper Midwest and Prairie provinces, creating geographic supply risk and price volatility during adverse growing seasons.
- EU REACH emulsifier approval timelines:Novel enzyme and emulsifier technologies face extended EFSA safety evaluation periods, delaying product launches by 18-36 months compared to conventional additive formulations.
- Almond and coconut flour substitution threat:Grain-free bakery mixes targeting paleo and ketogenic diet adherents capture premium shelf space in specialty retail, compressing addressable market for traditional multi-grain positioning.
Strategic Opportunities
- India FSSAI fortification mandates:Mandatory micronutrient fortification of staple cereals creates demand for pre-blended fortified multi-grain premixes among commercial bakeries serving government school feeding programs.
- E-commerce direct-to-bakery distribution:Digital procurement platforms bypass traditional food service distributors, enabling smaller artisan bakeries to access bulk premix formulations previously reserved for large-scale manufacturers.
- Regenerative agriculture certification alignment:EU Green Deal carbon farming incentives reward supply chains documenting soil health improvements, creating premium pricing tiers for regenerative-sourced grain premixes.
Industry Challenges
- Whole-grain dough technologist shortage:Commercial bakeries lack in-house expertise to troubleshoot hydration variability and fermentation timing in high-fiber formulations, increasing reliance on supplier technical service.
- Dual certification timeline compression:Simultaneous pursuit of organic certification and non-GMO verification creates overlapping audit requirements and documentation burdens for ingredient suppliers.
- Legacy ERP integration with traceability platforms:Batch-level grain provenance tracking required by EU sustainability disclosure rules conflicts with existing manufacturing execution systems designed for commodity flour sourcing.
Report Scope
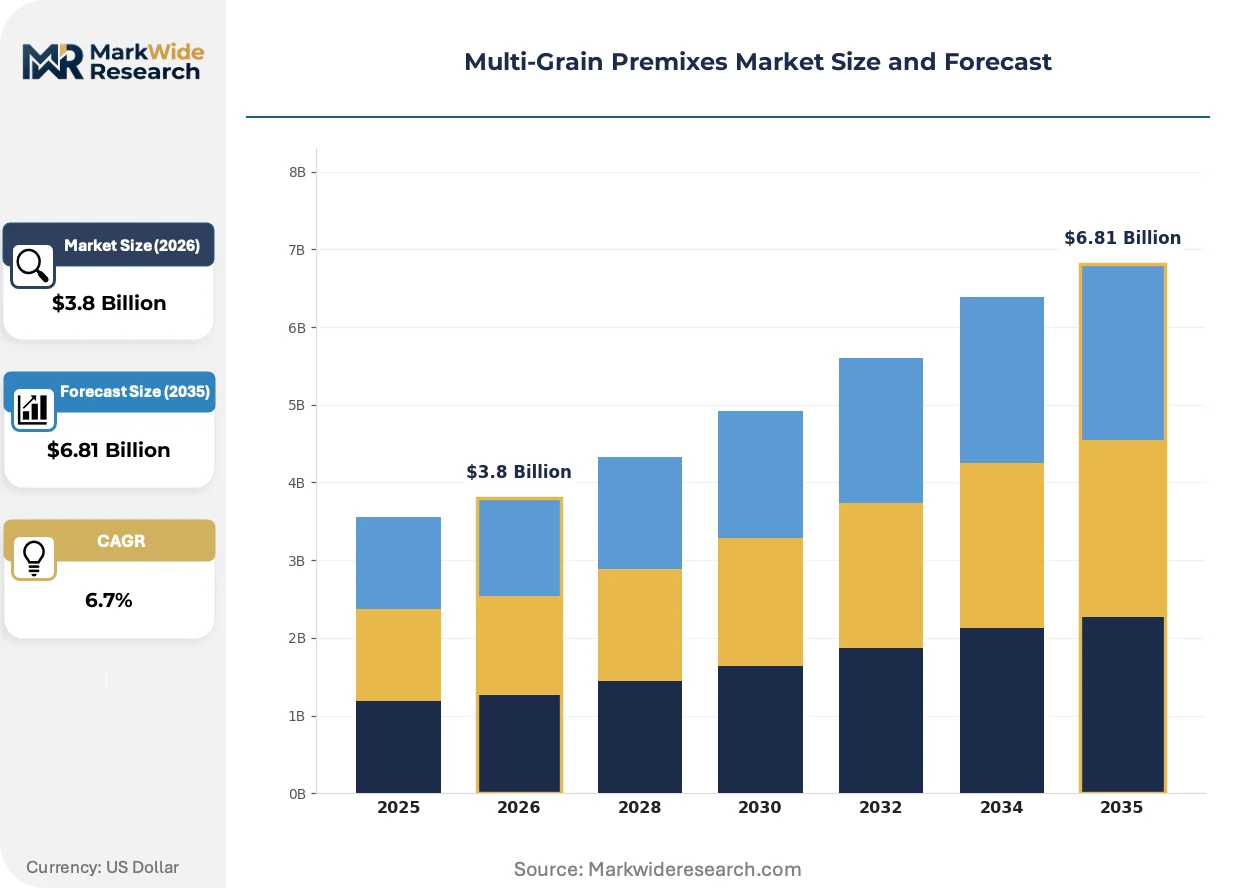
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Grain Premixes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancake Mix, Bread Mix, Muffin Mix, Pizza Dough Ingredient Type: Whole Grains, Flours, Seeds, Additives Packaging Type: Bags, Boxes, Pouches, Containers End User: Households, Restaurants, Bakeries, Food Services |
| Companies Covered | Archer Daniels Midland Company, Cargill, General Mills, Ingredion Incorporated, Kerry Group, Glanbia, Conagra Brands, Bunge Limited, Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Grain Premixes Market Shifts & Advancements
Active enzyme technologies and sustainable sourcing verification systems are reshaping competitive positioning in multi-grain premix formulation, while procurement digitization compresses traditional distributor intermediation.
Sprouted grain enzyme systems are absorbing moisture-binding inefficiencies that previously limited whole-grain bread volume yield. Artisan and mid-scale commercial bakeries in Germany and the Netherlands are adopting these systems at accelerating rates to maintain clean-label positioning. The technology is absorbing market share from chemically modified dough conditioners in premium bakery segments.
EU Green Deal corporate sustainability reporting requirements are mandating Scope 3 emission disclosures across agricultural supply chains. Flour millers and premix blenders must now document farm-level carbon intensity or face exclusion from European retail and food service contracts. Small-to-mid-sized German bakery chains are responding by consolidating supplier bases to verified regenerative agriculture partners.
Direct sourcing platforms are enabling bakery operators to contract grain origination and premix blending through unified digital interfaces. Traditional food service distributors in North America are losing volume to vertically integrated supplier portals that guarantee lot-level traceability. This channel compression is most visible among California and Pacific Northwest artisan bakeries serving farm-to-table restaurant accounts.
Multi-Grain Premixes Market Segmentation
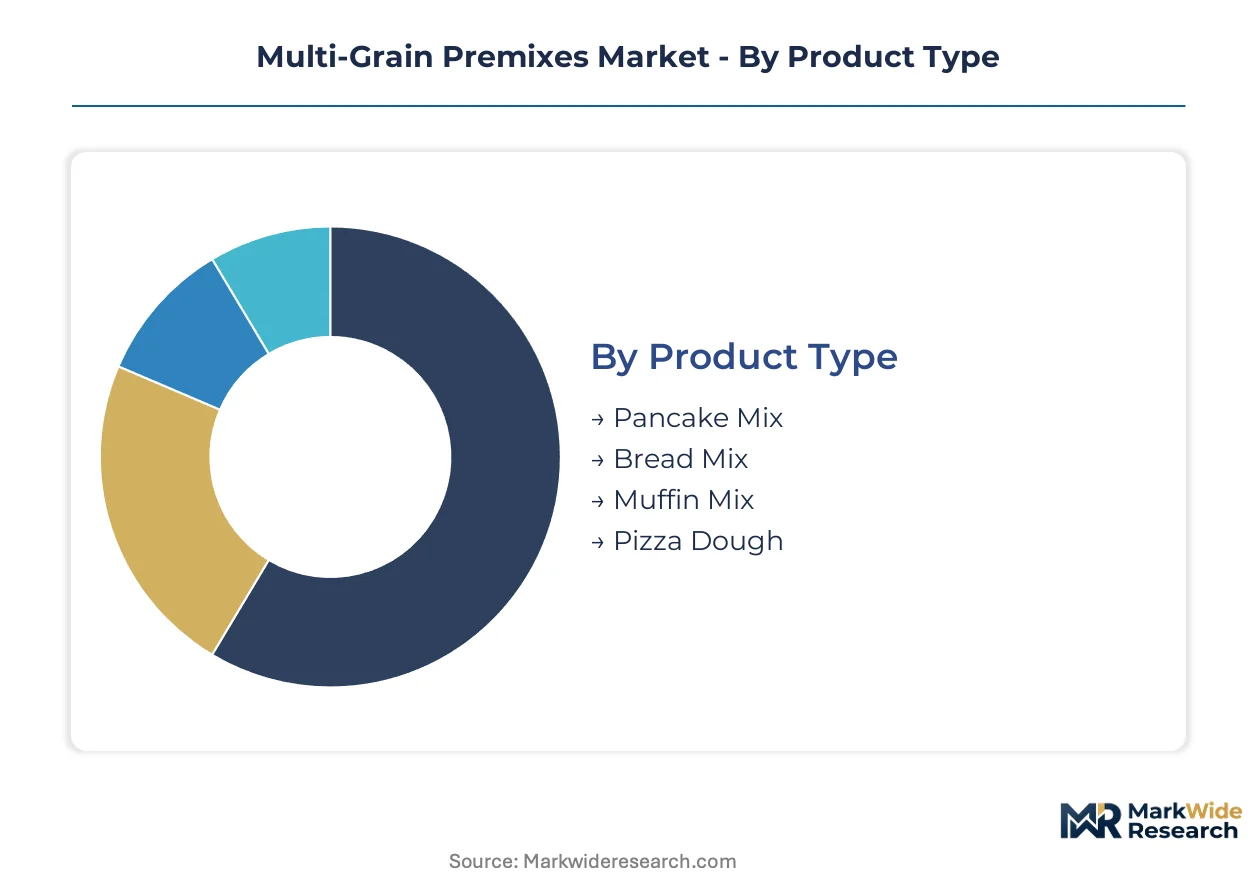
Segmentation in multi-grain premixes reveals how capital deployment, formulation complexity, and channel access determine competitive positioning. Each dimension carries distinct margin profiles and technical service requirements that shape supplier strategy.
Product Type:
Bread mix production demands the heaviest capital commitment, requiring specialized hydration control systems and fermentation staging infrastructure that pancake operations can bypass.
- Bread Mix:Formulations blend wheat, rye, and barley with enzymatic conditioners to manage high-fiber dough rheology. Demand clusters in German artisan bakeries and US institutional food service where USDA whole-grain-rich compliance is mandatory.
- Pancake Mix:Lower hydration specifications permit simpler dry blending equipment, though leavening stability across storage temperatures requires encapsulated acid technology. North American breakfast chains and European hotel food service drive procurement.
- Muffin Mix:Fat encapsulation and moisture retention chemistry differentiate commercial grades from commodity offerings.
- Pizza Dough:Gluten development and freeze-thaw tolerance specifications govern formulation complexity for food service distributors.
Most installed capacity flows through Bread Mix. Expansion is steepest in Pancake Mix.
Ingredient Type:
Whole grain sourcing ties up working capital in certified organic inventory and extended supplier qualification timelines that refined flour traders avoid.
- Whole Grains:Unrefined wheat, oat, and rye kernels retain bran and germ layers requiring modified milling protocols. EU Green Deal sustainability disclosure rules are forcing German and French bakery chains to document regenerative agriculture provenance.
- Flours:Refined milling outputs offer batch consistency and predictable hydration curves that industrial bakeries prioritize for throughput optimization.
- Seeds:Chia, flax, and sunflower inclusions add omega-3 positioning and textural differentiation for premium retail channels.
- Additives:Enzyme blends and emulsifiers face EFSA approval timelines that delay product launches versus conventional chemical conditioners.
Whole Grains command the tightest supply base. Seeds are gaining share fastest in clean-label positioning.
Packaging Type:
Flexible pouch converting lines require lower capital outlay than rigid container forming equipment, though barrier film specifications vary sharply by product moisture sensitivity.
- Bags:Multi-wall paper and plastic laminates dominate bulk food service procurement where portion control is handled downstream.
- Boxes:Retail shelf-ready formats with graphic panels support brand differentiation in European supermarket baking aisles.
- Pouches:Stand-up and flat formats with resealable features target household convenience positioning in North American and Asian e-commerce channels.
- Containers:Rigid plastic and composite cans preserve freshness in high-humidity climates for export markets.
Bags handle the largest volume tonnage. Pouches are climbing the fastest as direct-to-bakery digital procurement expands.
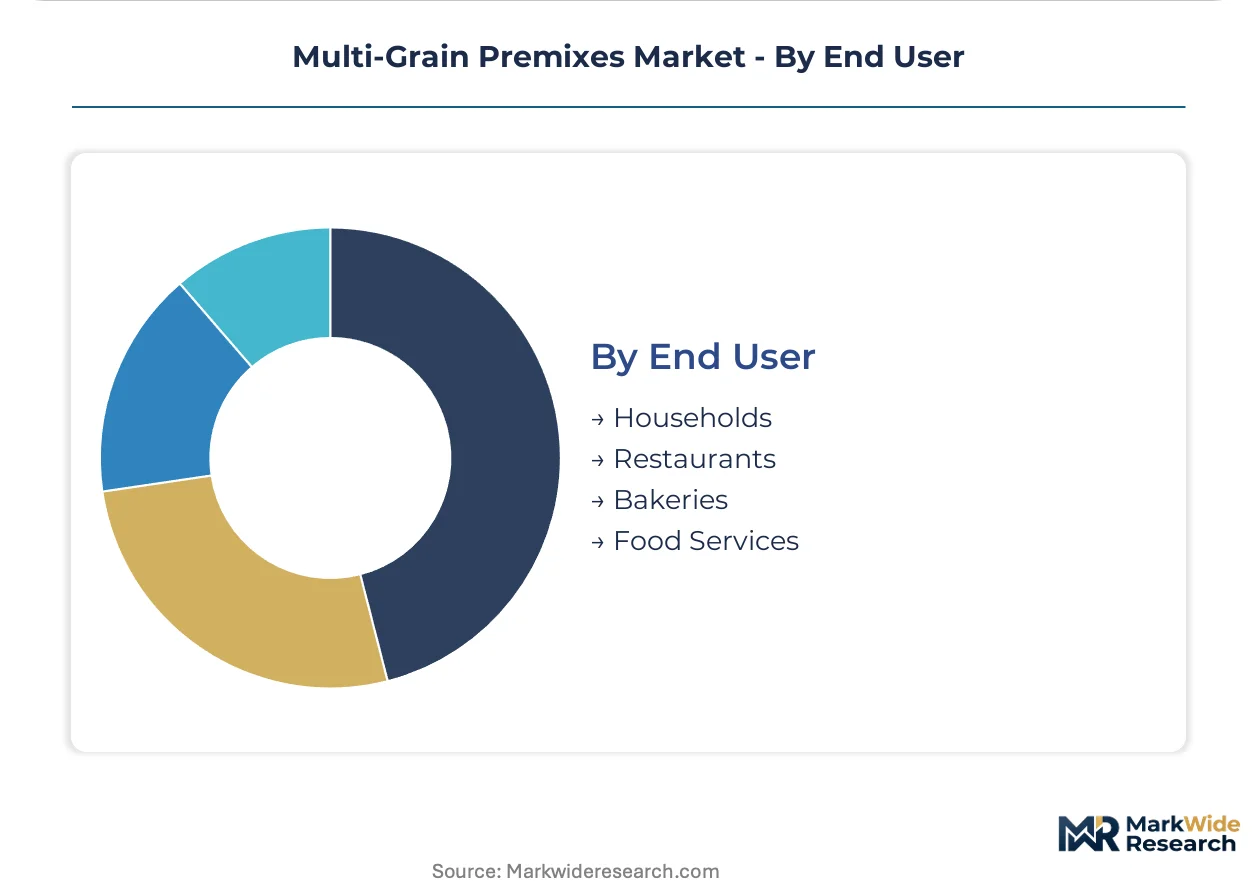
End User:
Food service accounts demand the most intensive technical support infrastructure, with field service chemists troubleshooting hydration variability that household consumers never encounter.
- Food Services:Institutional contracts with school districts and hospital networks require documented compliance with USDA whole-grain-rich standards or EU procurement sustainability criteria. Technical service intensity is highest here.
- Bakeries:Mid-scale commercial operators lack in-house formulation expertise and rely on supplier premix precision to reduce batch-to-batch variation.
- Restaurants:Chain and independent operators prioritize consistency and labor reduction over ingredient provenance transparency.
- Households:Retail package sizes and simplified preparation instructions target convenience-oriented consumers in supermarket and e-commerce channels.
Food Services absorb the most supplier technical resources. Bakeries are expanding most quickly as artisan segment professionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled food technologists and grain procurement specialists concentrate in Germany's Rhine-Ruhr corridor and the US Upper Midwest, anchoring formulation expertise for multi-grain premix development. These talent clusters shape regional competitive advantages in clean-label innovation and sustainable sourcing verification.
United States
Institutional bakeries serving K-12 school districts drive whole-grain-rich premix procurement under USDA meal pattern standards. FDA nutrition labeling requirements mandate gram-level whole-grain disclosure on retail packaging. Minneapolis-St. Paul hosts the densest concentration of organic grain traders and premix blenders supplying national food service distributors.
Germany
Artisan bakery chains in Bavaria and Baden-Württemberg prioritize regenerative agriculture certification for wheat and rye sourcing. EU Green Deal corporate sustainability reporting obligations force disclosure of Scope 3 emissions across agricultural supply chains. Hamburg's port infrastructure enables certified sustainable grain imports from Baltic and Black Sea origins.
China
Commercial bakeries in the Yangtze River Delta adopt fortified multi-grain premixes to meet GB standards for cereal product micronutrient enrichment. SAMR oversight of food additive approvals governs enzyme and emulsifier inclusion rates. Shanghai-based e-commerce platforms enable direct-to-bakery procurement bypassing traditional distribution layers.
India
Mid-scale commercial bakeries in Maharashtra and Gujarat source pre-blended fortified premixes to comply with FSSAI mandatory fortification guidelines for government school feeding programs. FSSAI registration requirements for imported grain additives create compliance complexity for multinational suppliers. Mumbai-Pune industrial corridor hosts emerging domestic premix manufacturers serving quick-service bakery chains.
United Kingdom
Supermarket baking aisles in London and the Southeast delist refined-flour mixes under clean-label procurement mandates from retail banners. FSA guidance on whole-grain health claims shapes product positioning for premium positioning. Manchester-Leeds corridor concentrates industrial bakery capacity transitioning to multi-grain formulations for food service export.
Multi-Grain Premixes Market Competitive Landscape
Capital-heavy grain processors compete with asset-light formulation specialists in multi-grain premix supply. Integrated agribusiness conglomerates control origination through captive milling infrastructure, while enzyme technology houses and regional blenders compete on formulation agility and technical service intensity. Three archetypes dominate: diversified grain traders with backward integration into regenerative agriculture programs, specialized enzyme and ingredient technology providers, and regional premix blenders serving artisan bakery clusters. Consolidation pressure intensifies through strategic partnerships between enzyme developers and sustainable grain certifiers, plus capacity expansion in sprouted grain processing infrastructure.
Among diversified agribusiness conglomerates, Archer Daniels Midland Company and Cargill occupy positions defined by global grain origination networks and regenerative agriculture program integration. Kerry Group exemplifies the specialized ingredient technology archetype, anchoring competitive positioning in enzyme-driven dough functionality solutions. These three entities represent distinct strategic approaches: upstream supply chain control, sustainable sourcing verification, and functional formulation innovation respectively.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| General Mills |
| Ingredion Incorporated |
| Kerry Group |
| Glanbia |
| Conagra Brands |
| Bunge Limited |
| Nutreco |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between regenerative-sourced and conventional grain premixes manifests in both pricing premiums and supplier consolidation patterns, as EU Green Deal disclosure rules force bakery chains to document Scope 3 emissions or face contract exclusion.
Pricing Analysis
Bundled technical service contracts command premiums over unbundled commodity premix sales, with food service distributors absorbing field chemist deployment costs into per-ton pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, from regenerative agriculture verification to basic organic compliance. Cost compression in economy-tier refined-flour formulations is intensifying because almond and coconut flour substitutes capture specialty retail shelf space. Institutional buyers under USDA whole-grain-rich mandates exhibit lowest price sensitivity, while artisan bakeries purchasing through direct-to-bakery platforms negotiate most aggressively on volume thresholds.
Supply Chain Analysis
Freight cost differentials between Upper Midwest grain origination and coastal processing hubs compress margins for non-integrated blenders serving Pacific Northwest artisan markets. Supply concentrates in the United States, Germany, and Canada, with certified organic wheat drawing from Prairie province and Upper Midwest elevators. Enzyme technologies, encapsulated leavening systems, and barrier packaging films constitute critical input dependencies. Single-source vulnerability in sprouted grain processing infrastructure creates bottleneck risk as German and Dutch bakeries accelerate adoption. Distribution runs through food service distributors for institutional accounts, while direct-to-bakery digital platforms disintermediate traditional channels for mid-scale commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier regenerative-certified premixes, where EU Green Deal procurement mandates and USDA compliance requirements shift buyer willingness-to-pay toward documented supply chain transparency.
For Market Incumbents: Anchor defensive positioning through captive regenerative agriculture program expansion and sprouted grain processing capacity addition in Germany and the US Upper Midwest. Kerry Group's enzyme technology specialization demonstrates how functional formulation IP creates switching costs against commodity premix competitors. Counter almond flour substitution threats by emphasizing whole-grain nutritional credentialing in institutional contract bidding. For New Entrants and Emerging Players: Begin with white-space targeting of Indian FSSAI-compliant fortified premixes for government school feeding programs, where multinational suppliers face registration complexity barriers. E-commerce direct-to-bakery distribution offers lowest customer acquisition cost versus traditional food service distributor penetration. Lead with technical service intensity to compensate for lack of grain origination scale. For Investors and Strategic Acquirers: Consolidation pressure builds where enzyme technology developers lack backward integration into certified sustainable grain supplies. Long-term viability favors vertically integrated platforms combining regenerative agriculture verification with formulation IP. Acquisition target archetype: regional premix blenders with established EU Green Deal documentation systems and artisan bakery customer concentration. Signal to watch: EU corporate sustainability reporting enforcement intensity accelerating contract consolidation toward verified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification Program | EU Green Deal disclosure rules reward documented soil health improvements with contract access. |
| Sprouted Grain Processing Capacity Expansion | Advanced enzymatic pre-treatment improves dough functionality for clean-label positioning in Germany. |
| Direct-to-Bakery Digital Platform Launch | E-commerce procurement bypasses food service distributors for Pacific Northwest artisan accounts. |
| Enzyme Technology Licensing Agreement | Kerry Group's functional formulation IP creates switching costs against commodity competitors. |
| Backward Integration into Organic Grain Origination | ADM and Cargill demonstrate how captive milling infrastructure secures certified supply. |
Research Methodology
Bottom-up bakery and food service procurement modeling reconciled against top-down grain origination and premix production tracking forms the analytical core of this study. Primary interviews with commercial bakery operations directors, food service distributor procurement leads, enzyme technology R&D heads, and certified organic grain traders were cross-validated against secondary sources including USDA school meal program procurement databases, EU Green Deal corporate sustainability reporting filings, FSSAI fortification guideline publications, and SEC 10-K disclosures from diversified agribusiness conglomerates. Triangulation between demand-side contract analysis and supply-side capacity mapping ensures segmentation integrity.
Input-output matrices linking grain origination volumes to premix blending capacity and end-use consumption patterns drive projection modeling across product type, ingredient certification tier, packaging format, and end-user channel dimensions. CAGRs were derived from regression analysis of historical procurement trends and policy-mandated demand inflection points, incorporating EU REACH emulsifier approval timelines and India FSSAI enforcement trajectories as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where EU Green Deal enforcement intensity, USDA whole-grain-rich standard revisions, or FSSAI import registration rule changes could materially shift the outlook. Forecasts reflect assumptions regarding sustained clean-label procurement mandate expansion and regenerative agriculture certification adoption rates. A model refresh is warranted upon material change in EU corporate sustainability reporting disclosure thresholds or US organic grain supply concentration following adverse growing seasons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Shortening Powder Market
Ingredients
Sweet Almond Oil Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Salt Market
Ingredients
Soybean Oil Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Cocoa Solids Market
Ingredients
Egg Free Premix Market
Ingredients
Pea Flour Market
Ingredients
Dry Molasses Products Market
Ingredients
India Olive Oil Market
Ingredients
Sodium Alginate Market
Ingredients
Textured Soy Protein Market
Ingredients
Plant Based Ingredients Market