
 Elecampane Root Market | 2026-2036
Elecampane Root Market Size, Share, and Industry Trends Forecast 2026-2036
Elecampane Root Market Foresight
Ingredient traceability revenue is rewriting margin allocation across the elecampane root supply chain. Mountain Rose Herbs leverages certified organic cultivation partnerships to anchor premium positioning in North American wholesale channels. Starwest Botanicals sustains bulk supply dominance through vertically controlled drying and milling operations. Gaia Herbs differentiates via DNA-verified botanical identity programs that command higher contract pricing from nutraceutical buyers.
Elecampane root denotes the dried rhizome of Inula helenium, containing up to 44% inulin alongside sesquiterpene lactones such as alantolactone, and undergoes controlled dehydration at sub-60°C to preserve volatile compounds for respiratory and digestive therapeutic applications. Powder and extract forms capture the dominant value share, with extracts commanding superior margins due to standardized alantolactone concentration requirements from German pharmacopeia-compliant buyers. Capsule formulations represent the fastest-growing product form as direct-to-consumer herbal brands expand e-commerce fulfillment infrastructure.
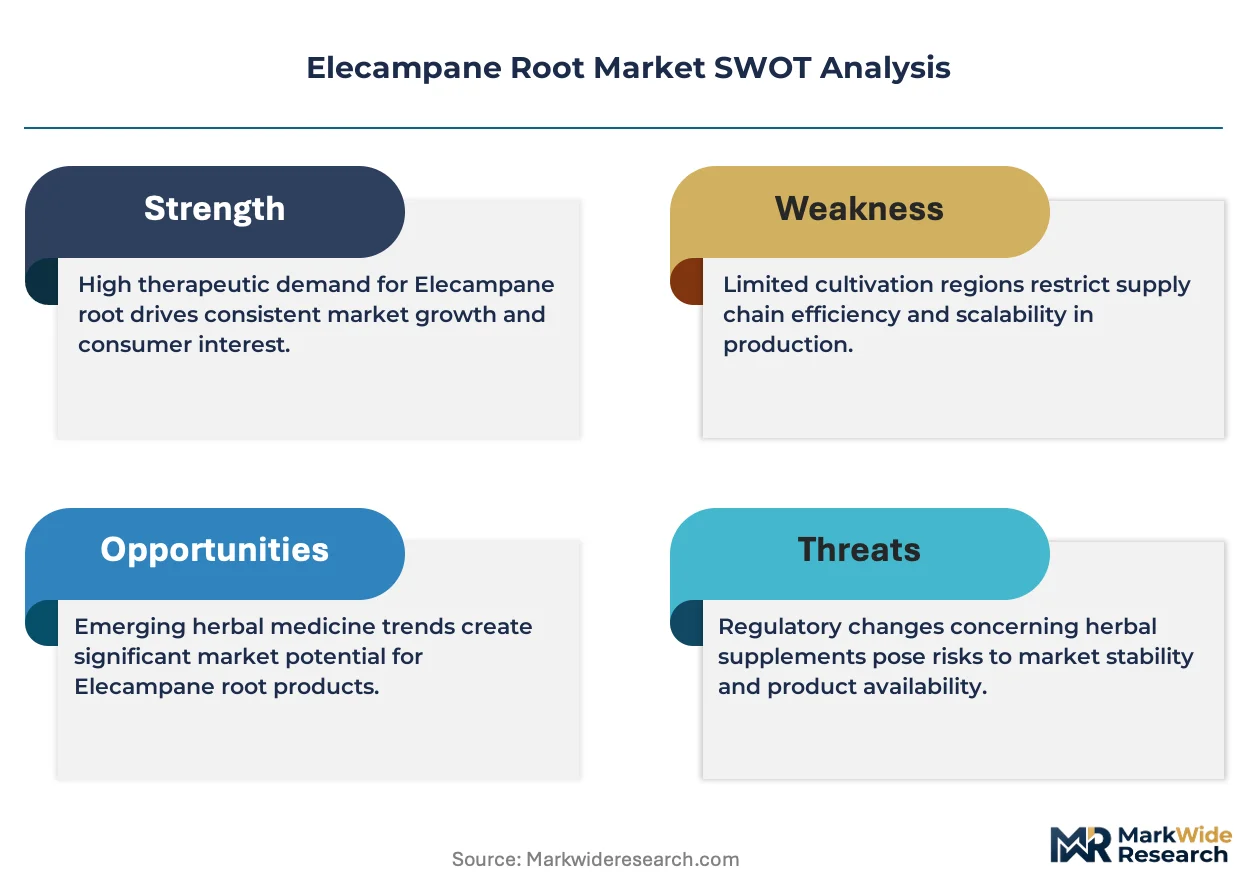
The FDA's Dietary Supplement Health and Education Act imposes Good Manufacturing Practice compliance on U.S.-based elecampane root processors, while the European Medicines Agency's Committee on Herbal Medicinal Products governs monograph standards for traditional-use registrations across EU member states. Germany's Commission E evaluations specifically recognize elecampane root for respiratory catarrh indications, creating preferential reimbursement pathways that other botanicals lack. Stakeholders must monitor evolving pharmacovigilance reporting requirements for herbal substances, as regulatory tightening in core European markets could reshape supplier qualification thresholds faster than cultivation capacity adjusts.
Market Dynamics
Pharmaceutical-grade inulin standardization requirements from German pharmacopeia authorities are compressing supplier margins while elevating entry barriers for uncertified cultivators across Eastern European sourcing zones.
Growth Catalysts
- Respiratory formulation demand:Nutraceutical manufacturers in North America are expanding elecampane root procurement for bronchial wellness supplements, creating sustained volume pull through contract cultivation agreements.
- EMA monograph harmonization:The European Medicines Agency's Committee on Herbal Medicinal Products is streamlining traditional-use registration pathways, reducing time-to-market for compliant extract suppliers.
- Sub-60°C dehydration technology:Controlled low-temperature drying protocols are preserving volatile sesquiterpene lactone profiles, enabling premium positioning for respiratory therapeutic applications.
Market Restraints
- Wild harvest dependency:Bulgarian and Romanian wild collection networks face seasonal yield volatility, constraining reliable feedstock for standardized extract production.
- Alantolactone quantification costs:HPLC-based sesquiterpene lactone assay requirements impose laboratory infrastructure burdens on mid-scale processors.
- Substitution by synthetic expectorants:Guaifenesin formulations in OTC cough medicines displace herbal alternatives in price-sensitive pharmacy segments.
Strategic Opportunities
- Polish organic cultivation expansion:Favorable agroclimatic conditions and EU organic certification subsidies position Polish farms to capture share from declining wild harvest volumes.
- Digestive microbiome applications:The 44% inulin content profile opens functional food positioning for prebiotic gut health formulations targeting wellness retailers.
- Direct-to-consumer capsule channels:E-commerce fulfillment infrastructure investments by herbal brands enable margin capture previously allocated to pharmacy distribution intermediaries.
Industry Challenges
- Botanical identity verification:DNA barcoding competency gaps in quality control laboratories delay batch release timelines for export shipments.
- Pharmacovigilance reporting infrastructure:German and French regulators require adverse event tracking systems that small-scale suppliers lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elecampane Root Market |
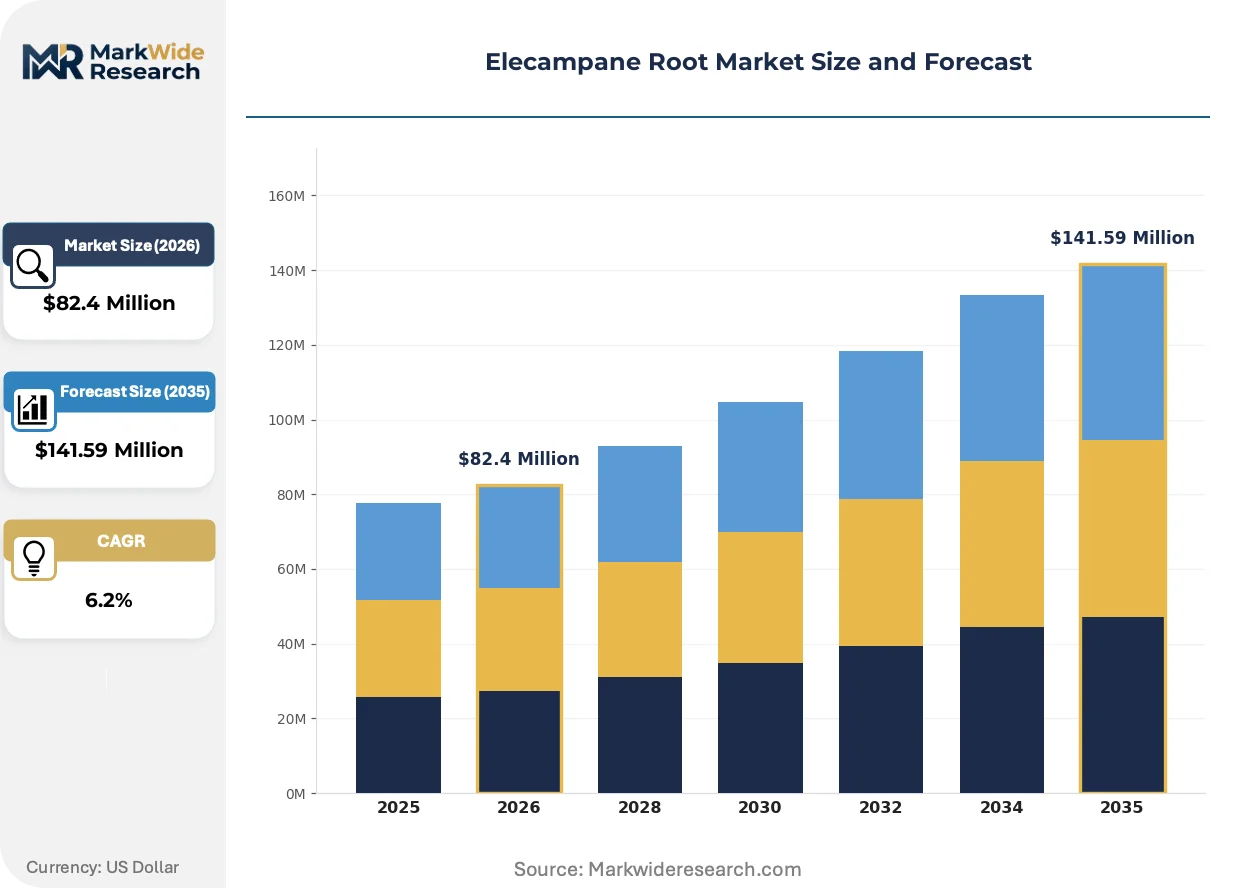
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $141.59 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Extract, Oil, Dried Slices, Capsules Application: Respiratory Support, Digestive Aid, Skin Care, Anti-inflammatory, Flavoring End User: Herbalists, Nutraceutical Companies, Cosmetic Manufacturers, Food & Beverage Producers Packaging Type: Plastic Bottles, Glass Jars, Sachets, Blister Packs, Bulk Bags |
| Companies Covered | Mountain Rose Herbs, Starwest Botanicals, Herb Pharm, Napiers Herbals, Monterey Bay Spice Company, Gaia Herbs, Nature's Way, Traditional Medicinals, Pacific Botanicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elecampane Root Market Shifts & Advancements
Digital traceability architectures and extraction technology advances are reconfiguring how elecampane root moves from field to finished formulation, compressing traditional quality assurance timelines.
Spectroscopic fingerprinting technology is virtualizing laboratory-based identity verification workflows. Mid-scale processors in Poland and the Czech Republic are adopting portable NIR devices for real-time inulin content screening at receiving stations. This distributed testing model is virtualizing centralized laboratory bottlenecks, accelerating batch release cycles from weeks to days for qualified suppliers.
Germany's Commission E evaluation framework for respiratory catarrh indications creates preferential reimbursement pathways unavailable to non-monographed botanicals. The BfArM's traditional-use registration requirements now mandate documented safety data spanning 30 years of medicinal use. Extract suppliers targeting pharmacy channels must align manufacturing records with these evidentiary standards, favoring established European processors over new market entrants.
Ingredient sourcing decisions now prioritize certified organic provenance over price minimization among North American contract manufacturers. Bulk buyers are consolidating supplier relationships around vertically integrated partners controlling cultivation through dehydration stages. This concentration pattern is most visible in Pacific Northwest procurement offices, where Mountain Rose Herbs and comparable distributors anchor preferred vendor status through transparent chain-of-custody documentation.
Elecampane Root Market Segmentation
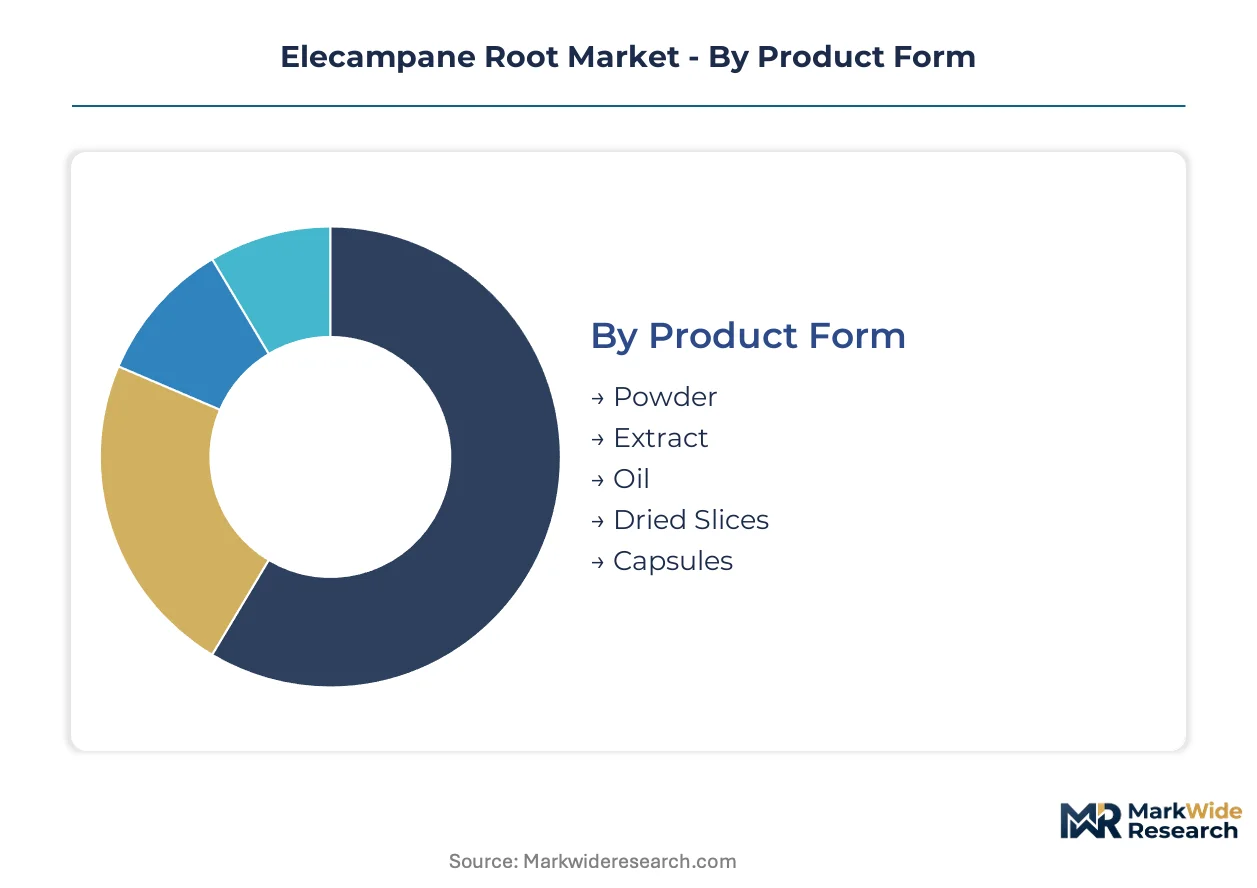
Elecampane root segmentation reveals divergent margin structures across therapeutic versus commodity applications. Processing intensity and pharmacopeia compliance requirements create distinct competitive arenas within each category.
Product Form:
Mature dehydration formats coexist with emerging extraction technologies, creating tiered value capture opportunities.
- Powder:Ground rhizome material standardized to particle size specifications serves bulk pharmaceutical and herbal tea channels. German pharmacopeia-compliant buyers in Bavaria and Baden-Württemberg drive volume through standardized inulin content requirements.
- Extract:Standardized sesquiterpene lactone concentrates command premium contract pricing due to alantolactone quantification protocols. North American nutraceutical manufacturers in Oregon and Vermont prioritize these inputs for respiratory supplement formulations.
- Oil:Steam-distilled volatile fractions target aromatherapy and topical applications.
- Dried Slices:Traditional herbalist channels prefer intact morphological structure for visual identity verification.
- Capsules:Direct-to-consumer brands are expanding e-commerce fulfillment infrastructure around this ready-to-dose format.
Powder retains volume leadership; capsules hold the steepest expansion curve.
Application:
Cost tier differentiation separates pharmacopeia-grade therapeutic positioning from commodity wellness applications.
- Respiratory Support:Commission E-monographed indications for bronchial catarrh create preferential reimbursement pathways unavailable to competing botanicals. German pharmacy distribution networks anchor demand concentration for validated extract suppliers.
- Digestive Aid:The 44% inulin content enables prebiotic functional food positioning targeting microbiome wellness retailers. Polish and Czech processors are developing certified organic supply chains for this emerging application.
- Skin Care:Cosmetic formulators leverage anti-inflammatory sesquiterpene fractions for sensitive skin topicals.
- Anti-inflammatory:Alantolactone research is expanding interest beyond traditional respiratory applications.
- Flavoring:Bitter principle compounds serve niche liqueur and digestive bitter markets.
Respiratory support commands premium pricing; digestive aid applications are climbing the fastest.
End User:
Customer type determines specification stringency and contract structure across the value chain.
- Herbalists:Small-batch practitioners prioritize morphological identity and provenance documentation over standardization metrics.
- Nutraceutical Companies:Volume buyers impose DNA verification and heavy metal testing protocols that favor vertically integrated suppliers.
- Cosmetic Manufacturers:Stability and odor profile specifications drive solvent selection in extraction processes.
- Food & Beverage Producers:Novel Food regulatory pathways in the European Union constrain ingredient approval timelines for this user category.
Nutraceutical companies dominate procurement volume; cosmetic manufacturers are gaining share fastest.
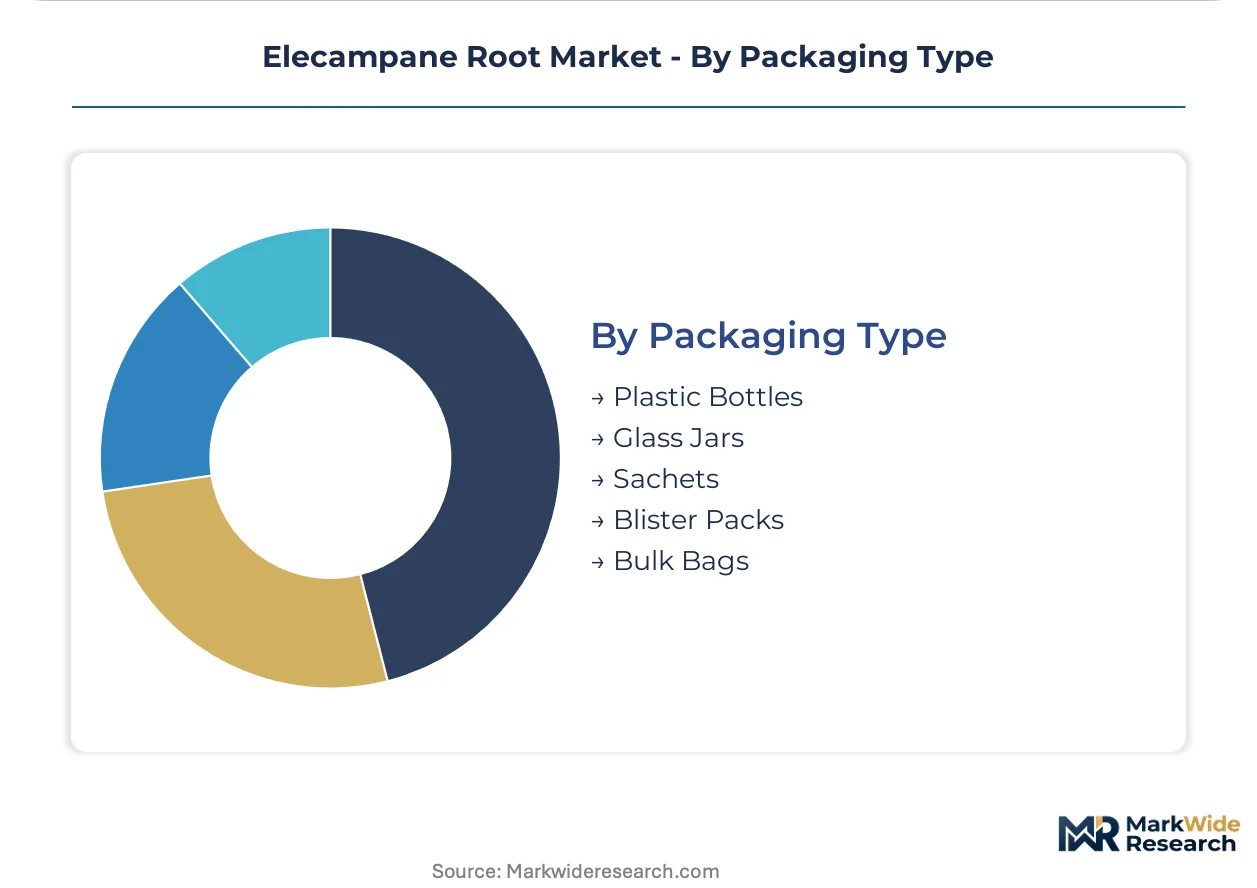
Packaging Type:
Supply concentration in certified organic channels shapes primary packaging selection.
- Plastic Bottles:Cost-sensitive retail channels favor HDPE containers for powder and capsule formats.
- Glass Jars:Premium positioning in natural product retail demands amber glass for light-sensitive compounds.
- Sachets:Single-serve convenience formats target travel and trial-size market development.
- Blister Packs:Pharmacy-channel compliance requires child-resistant unit-dose specifications.
- Bulk Bags:Super sack formats serve contract manufacturers with in-house encapsulation capabilities.
Bulk bags retain volume leadership; blister packs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes elecampane root predominantly through pharmacy-grade extracts for respiratory indications, while North American buyers favor direct-to-consumer capsules and functional food applications. This divergence in end-use patterns shapes supplier qualification requirements and pricing structures across sourcing regions.
Germany
Commission E monographs for bronchial catarrh create preferential reimbursement pathways that pharmacy distribution networks exploit. The BfArM mandates 30-year safety documentation for traditional-use registrations, elevating evidentiary burdens on extract suppliers. Bavarian and Baden-Württemberg processing clusters concentrate pharmacopeia-compliant manufacturing capacity for export to adjacent EU markets.
United States
Nutraceutical manufacturers in Oregon and Vermont expand contract cultivation agreements for respiratory supplement formulations. The FDA's Dietary Supplement Health and Education Act imposes Good Manufacturing Practice compliance on domestic processors. Pacific Northwest procurement offices consolidate supplier relationships around vertically integrated partners controlling chain-of-custody documentation.
Poland
Favorable agroclimatic conditions and EU organic certification subsidies position Polish farms to capture share from declining Bulgarian and Romanian wild harvest volumes. The country's national pharmaceutical regulator aligns with EMA monograph harmonization efforts for traditional-use registrations. Mazovia and Greater Poland regions develop certified organic supply chains for prebiotic gut health applications.
France
ANSM pharmacovigilance reporting requirements for herbal substances reshape supplier qualification thresholds faster than cultivation capacity adjusts. The country's national pharmaceutical regulator requires adverse event tracking systems that constrain small-scale supplier participation. Provence-Alpes-Côte d'Azur clusters concentrate cosmetic formulators leveraging anti-inflammatory sesquiterpene fractions for sensitive skin topicals.
Canada
Health Canada/PMRA oversight of natural health products creates distinct approval pathways for elecampane root formulations. British Columbia and Ontario procurement networks prioritize certified organic provenance over price minimization among contract manufacturers. Prairie Provinces agroclimatic conditions support experimental cultivation trials for respiratory therapeutic feedstock.
Elecampane Root Market Competitive Landscape
Capability concentration sits with certified organic cultivators and DNA-verified botanical identity programs; scale advantage sits with bulk dehydration and milling operations controlling vertical throughput. The market structures around three archetypes: premium-positioned organic specialists, volume-driven bulk suppliers, and integrated nutraceutical ingredient platforms. Consolidation pressures favor backward integration into cultivation stages and strategic partnerships with pharmacy-channel distributors.
Among North American wholesale distributors, Mountain Rose Herbs anchors certified organic cultivation partnerships for premium positioning. Starwest Botanicals exemplifies bulk supply dominance through in-house drying and milling operations. Gaia Herbs occupies a position within the DNA-verified botanical identity tier, commanding higher contract pricing from nutraceutical buyers seeking pharmacopeia-compliant documentation.
| Leading Market Players |
|---|
| Mountain Rose Herbs |
| Starwest Botanicals |
| Herb Pharm |
| Napiers Herbals |
| Monterey Bay Spice Company |
| Gaia Herbs |
| Nature's Way |
| Traditional Medicinals |
| Pacific Botanicals |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight dynamics compress supplier margins for Bulgarian and Romanian wild harvest shipments while amplifying price spreads between certified organic and conventional elecampane root grades. German pharmacopeia compliance costs and Polish organic certification subsidies reshape downstream price differentiation across European pharmacy and North American nutraceutical channels.
Pricing Analysis
Long-term offtake contracts dominate procurement between German extract manufacturers and Polish certified organic cultivators, locking in alantolactone-standardized supply at premium tiers while spot markets handle seasonal shortfalls from Bulgarian wild collection networks. Three-tier pricing structure across pharmacopeia-grade extracts, certified organic powders, and conventional dried material reflects German Commission E compliance status and DNA verification depth. Pricing pressure stems from HPLC assay infrastructure costs that mid-scale processors struggle to amortize. Contract manufacturers in Oregon and Vermont exhibit lowest price sensitivity due to downstream brand premium capture; commodity powder buyers in herbal tea channels face acute cost compression.
Supply Chain Analysis
Wild elecampane root populations in Bulgaria and Romania feed traditional harvest networks, while certified organic cultivation concentrates in Poland's Mazovia and Greater Poland regions with EU subsidy support. Raw material flows depend on seasonal rhizome maturity windows, sub-60°C dehydration capacity, and sesquiterpene lactone preservation technology. Single-source vulnerability runs through Bulgarian wild collection cooperatives facing yield volatility from climate stress. Distribution runs through vertically integrated North American wholesalers controlling organic certification documentation and German pharmacy distributors demanding BfArM-compliant traceability records.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elecampane root sits in early-cycle expansion as respiratory wellness formulations penetrate direct-to-consumer channels beyond traditional pharmacy networks, with Commission E monograph recognition creating tailwinds for validated extract suppliers.
For Market Incumbents: Harden supply security through backward integration into Polish organic cultivation partnerships before EU subsidy windows contract. Anchor pharmacopeia-compliant manufacturing records against BfArM's 30-year safety documentation requirements to defend against emerging DNA-verified botanical identity competitors. Consolidate dehydration and milling capacity in Bavarian processing clusters to capture export demand from adjacent EU markets seeking traditional-use registration alignment.
For New Entrants and Emerging Players: Establish a beachhead in prebiotic gut health applications leveraging the 44% inulin content profile, where Polish organic supply chains and wellness retailer channel development lag respiratory formulation saturation. Target digestive microbiome positioning for functional food manufacturers seeking Novel Food pathway alternatives to saturated respiratory supplement markets. Deploy portable NIR spectroscopy at receiving stations to compress batch release timelines against centralized laboratory incumbents.
For Investors and Strategic Acquirers: Certified organic mid-scale processors with captive Polish cultivation acreage and German pharmacopeia compliance infrastructure represent priority acquisition targets as consolidation pressures intensify. Long-term viability hinges on regulatory moat depth around traditional-use registrations and DNA verification competency gaps that delay competitor batch releases. Watch EMA pharmacovigilance reporting requirement tightening as the inflection signal for supplier qualification threshold elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captures EU organic certification subsidies in Poland while securing feedstock against wild harvest volatility. |
| DNA Verification Program Deployment | Commands premium contract pricing from Gaia Herbs-tier nutraceutical buyers seeking pharmacopeia-compliant documentation. |
| Sub-60°C Dehydration Capacity Expansion | Preserves volatile sesquiterpene lactone profiles for respiratory therapeutic premium positioning. |
| Direct-to-Consumer Capsule Channel Launch | Enables margin capture from e-commerce fulfillment infrastructure investments bypassing pharmacy intermediaries. |
| Traditional-Use Registration Alignment | Unlocks preferential reimbursement pathways through Germany's Commission E framework unavailable to non-monographed botanicals. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings in this study. Primary interviews with herbal product formulators, certified organic cultivation managers, pharmacy procurement officers, and nutraceutical contract manufacturing executives combined with secondary validation from EMA monograph databases, FDA Dietary Supplement Health and Education Act guidance documents, and German BfArM traditional-use registration records. Bottom-up cultivation volume estimates and top-down extract demand modeling triangulate market sizing across the analysis window.
Calibration against historical pharmacopeia compliance adoption curves and respiratory supplement category penetration patterns informs the projection framework. Segmentation dimensions span product form, application, end user archetype, and regional regulatory cluster. CAGRs derive from compound growth modeling of certified organic acreage expansion, dehydration technology adoption rates, and direct-to-consumer channel development velocity. Alantolactone standardization requirement evolution and pharmacovigilance infrastructure investment cycles serve as industry-specific forecast inputs.
Stress conditions across wild harvest yield volatility, EU organic certification policy shifts, and synthetic expectorant substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA monograph harmonization pace and North American nutraceutical contract cultivation agreement expansion. Cross-checking against German pharmacy distribution volume benchmarks and Pacific Northwest procurement office supplier consolidation patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Global Egg White Peptide Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Europe Pea Starch Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Stock Cubes Market
Ingredients
Plant Extracts Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Soy Lecithin Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Valerian Root Oil Market
Ingredients
Chickpea Flour Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Italy Soy Protein Market
Ingredients
Ben Oil Market
Ingredients
Sodium Reduction Ingredients Market