
 Plant Based Premix Market | 2026-2036
Plant Based Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Premix Market Analytics
The capability gap between scaled powder processing infrastructure and emerging precision-fermentation entrants is redrawing competitive boundaries in plant-based premix supply. Perfect Day Foods leverages its microbial dairy protein platform to sustain premium positioning in functional nutrition blends. Califia Farms anchors North American distribution through retail and foodservice channel control. Oatly competes on brand recognition, extending oat-derived premix applications beyond beverages into baking and smoothie segments.
Plant-based premix denotes a pre-formulated blend of isolated or concentrated proteins, fibers, vitamins, and emulsifiers designed for reconstitution in food and beverage manufacturing, typically requiring protein content between 15% and 85% depending on end-use specification. These formulations enable consistent functional performance in extrusion, baking, or beverage applications without downstream manufacturers managing multi-supplier ingredient sourcing. Protein powders dominate current volume flows, though baking mixes capture expanding margin pools as clean-label bakery demand rises across European retail. The powder form leads manufacturing economics through extended shelf stability and lower transport costs, while liquid premixes are gaining traction in ready-to-drink contract manufacturing.
The FDA governs GRAS self-affirmation pathways for novel plant proteins in the United States, while EFSA mandates comprehensive allergen risk assessments under EU regulation 1169/2011, shaping reformulation priorities and market access timelines for international suppliers. India's FSSAI has introduced plant protein labeling guidelines under draft notification standards, creating compliance complexity for exporters targeting its domestic nutraceutical channel. Stakeholders must monitor evolving protein quality scoring methodologies across jurisdictions, as PDCAAS and DIAAS adoption patterns will determine which ingredient systems qualify for nutritional claims in fortified food applications.
Market Dynamics
Precision fermentation infrastructure is bifurcating the supplier base between legacy powder processors and microbial protein platforms, forcing reformulation cycles as EFSA and FDA tighten labeling thresholds for nutritional claims.
Growth Catalysts
- EFSA Regulation 1169/2011:Mandatory allergen risk assessments for novel plant proteins accelerate certified premix adoption by European food manufacturers seeking compliant sourcing pathways.
- Flexitarian household spending:Retail shelf space expansion in Germany, the United Kingdom, and the United States concentrates demand for clean-label baking and beverage applications.
- Precision fermentation:Microbial dairy protein platforms enable functional nutrition blends with superior emulsion stability, attracting premium positioning in sports nutrition and infant formula adjacent segments.
Market Restraints
- Pea protein isolate supply concentration:Processing capacity clusters in Canada and northern France, exposing buyers to crop yield volatility and freight cost spikes.
- FSSAI draft notification complexity:India's evolving plant protein labeling standards create compliance friction for exporters targeting its nutraceutical channel, extending market access timelines.
- Technical protein quality scoring divergence:PDCAAS versus DIAAS adoption patterns across jurisdictions force dual certification investments, compressing margins on standard-grade premix formulations.
Strategic Opportunities
- Brazilian foodservice channel:ANVISA regulatory harmonization with CODEX standards opens contract manufacturing demand for ready-to-drink liquid premixes in institutional catering.
- Precision fermentation plus extrusion:Converging technologies enable texturized protein premixes with fibrous mouthfeel, displacing soy concentrate in European meat analog applications.
- EU Green Deal procurement mandates:Public sector foodservice contracts now require carbon footprint disclosure, favoring domestic oat and fava bean premix suppliers with verified lifecycle data.
Industry Challenges
- Formulation chemist scarcity:Protein-protein interaction expertise and emulsion stability optimization skills command premium compensation, constraining R&D throughput at mid-scale processors.
- GRAS self-affirmation timelines:FDA novel protein pathways require 18-24 month toxicology dossiers, delaying commercialization for emerging legume and algae-derived concentrates.
- Legacy extrusion asset retrofitting:High-moisture extrusion capacity designed for soy and wheat gluten requires capital-intensive screw and barrel modifications to process novel pulse proteins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Premix Market |
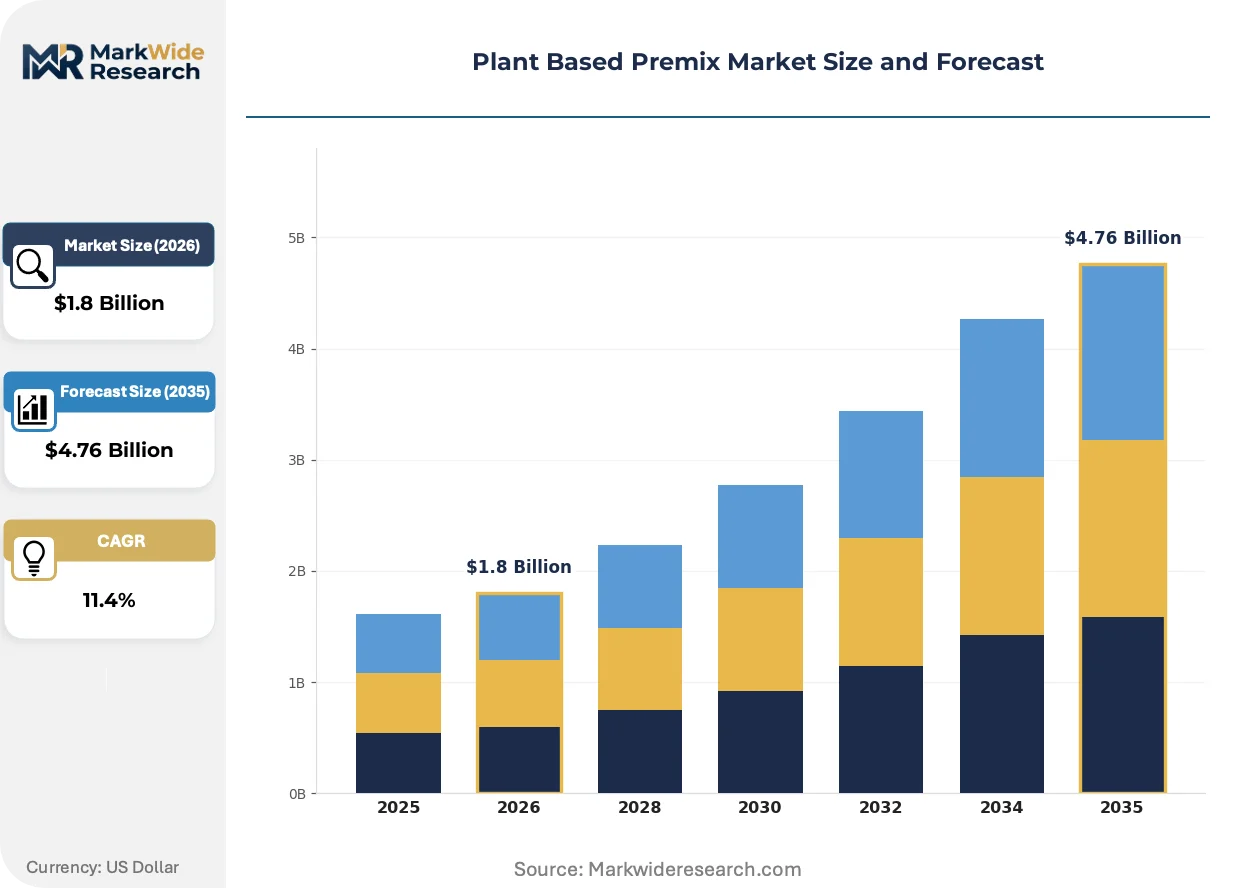
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Baking Mixes, Smoothie Mixes, Nutritional Supplements Form: Liquid, Powder, Granules, Capsules Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales End User: Fitness Enthusiasts, Vegans, Children, Elderly |
| Companies Covered | Just, Inc., TerViva, Perfect Day Foods, NovaMeat, C16 Biosciences, Califia Farms, Nobell Foods, GoodDot, Oatly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Premix Market Evolving Landscape
Active protein fractionation and microbial fermentation platforms are reshaping ingredient hierarchies, while regulatory convergence on protein quality metrics and procurement transparency standards accelerates certification investments across the value chain.
Enzymatic protein texturization is bifurcating the extrusion equipment market between legacy high-shear systems and low-temperature shear-cell platforms. European meat analog manufacturers are adopting shear-cell technology at pilot scale, compressing capital requirements for fibrous structure formation while reducing energy intensity versus conventional twin-screw extrusion.
EFSA's evolving guidance on protein quality claims under EU regulation 1924/2006 is forcing reformulation toward DIAAS-optimized amino acid profiles. Infant formula and sports nutrition premix suppliers are responding by blending multiple legume sources to achieve scoring thresholds that isolate proteins cannot meet independently.
Food manufacturers are consolidating supplier relationships around vertically integrated premix houses with in-house protein isolation and vitamin microencapsulation. This pattern concentrates procurement decision-making at headquarters level, displacing fragmented regional ingredient sourcing and favoring partners with dual US-EU regulatory dossiers.
Plant Based Premix Market Segmentation
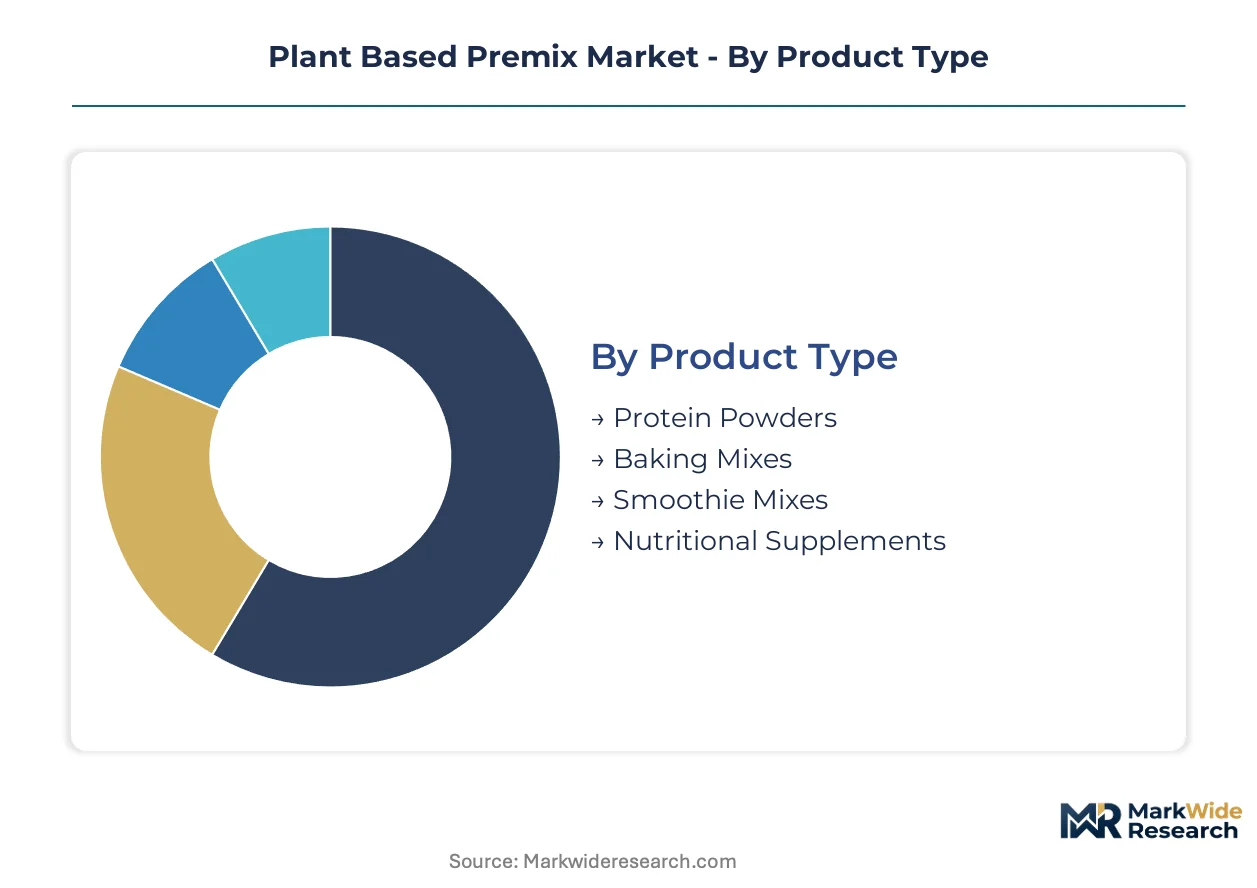
Plant-based premix segmentation reveals distinct supply chain configurations across product categories. Powder formulations dominate manufacturing economics through extended shelf stability, while liquid formats concentrate in foodservice contract manufacturing channels.
Product Type:
Export-led demand concentrates in protein powders and nutritional supplements, while baking mixes and smoothie mixes serve primarily domestic retail channels.
- Protein Powders:Isolated or concentrated protein blends with 50-85% protein content designed for sports nutrition and meal replacement applications. Demand clusters in Germany and the United States where fitness-oriented household spending drives premium positioning for DIAAS-optimized formulations.
- Baking Mixes:Pre-formulated blends incorporating plant proteins, fibers, and emulsifiers for clean-label bakery applications. European retail expansion in the United Kingdom and Germany captures flexitarian consumers seeking home baking convenience without multi-supplier ingredient sourcing.
- Smoothie Mixes:Ready-to-blend formulations targeting beverage contract manufacturers.
- Nutritional Supplements:Fortified premixes for elderly and pediatric nutrition segments.
Protein powders hold the largest share; momentum sits with baking mixes.
Form:
Manufacturing cost tiers separate powder economics from liquid processing infrastructure requirements.
- Powder:Dominant format enabling extended shelf stability, reduced transport costs, and flexible reconstitution ratios. European and North American food manufacturers prefer powder premixes for extrusion and baking applications where moisture control determines finished product texture.
- Liquid:Gaining traction in ready-to-drink contract manufacturing where high-moisture extrusion or beverage bottling lines require pumpable inputs. Brazil's ANVISA-harmonized institutional catering sector drives import demand for aseptic liquid premixes with validated microbial stability.
- Granules:Intermediate format for specific extrusion feed systems.
- Capsules:Precision-dosed format for nutraceutical applications.
Powder maintains volume leadership; liquid formats are climbing the fastest.
Distribution Channel:
Channel control patterns reflect customer procurement consolidation versus fragmented retail access.
- Online Retail:Direct-to-consumer platforms capture fitness enthusiast and vegan segments seeking specialized formulations unavailable through conventional retail. German and United Kingdom markets show strongest e-commerce penetration for subscription-based protein powder replenishment.
- Supermarkets:Clean-label baking mixes achieve shelf space expansion in Germany, the United Kingdom, and the United States as retailers respond to flexitarian household trial behavior.
- Health Stores:Premium positioning channel for certified organic and allergen-free formulations.
- Direct Sales:Institutional and foodservice contract manufacturing relationships.
Supermarkets hold the largest share; online retail shows steepest expansion trajectory.
End User:
Application requirements diverge sharply between performance nutrition and demographic-specific fortification needs.
- Fitness Enthusiasts:Sports nutrition segment demanding 20-30g protein per serving with rapid amino acid absorption profiles. Precision fermentation-derived microbial proteins enable premium positioning through superior emulsion stability in ready-to-drink applications.
- Vegans:Ethically motivated consumers requiring complete amino acid profiles from blended legume sources. EFSA Regulation 1169/2011 allergen labeling compliance drives certified premix adoption for this label-conscious segment.
- Children:Pediatric nutrition requiring DIAAS-optimized formulations meeting strict protein quality thresholds.
- Elderly:Sarcopenia-focused applications with enhanced leucine content and texture-modified delivery formats.
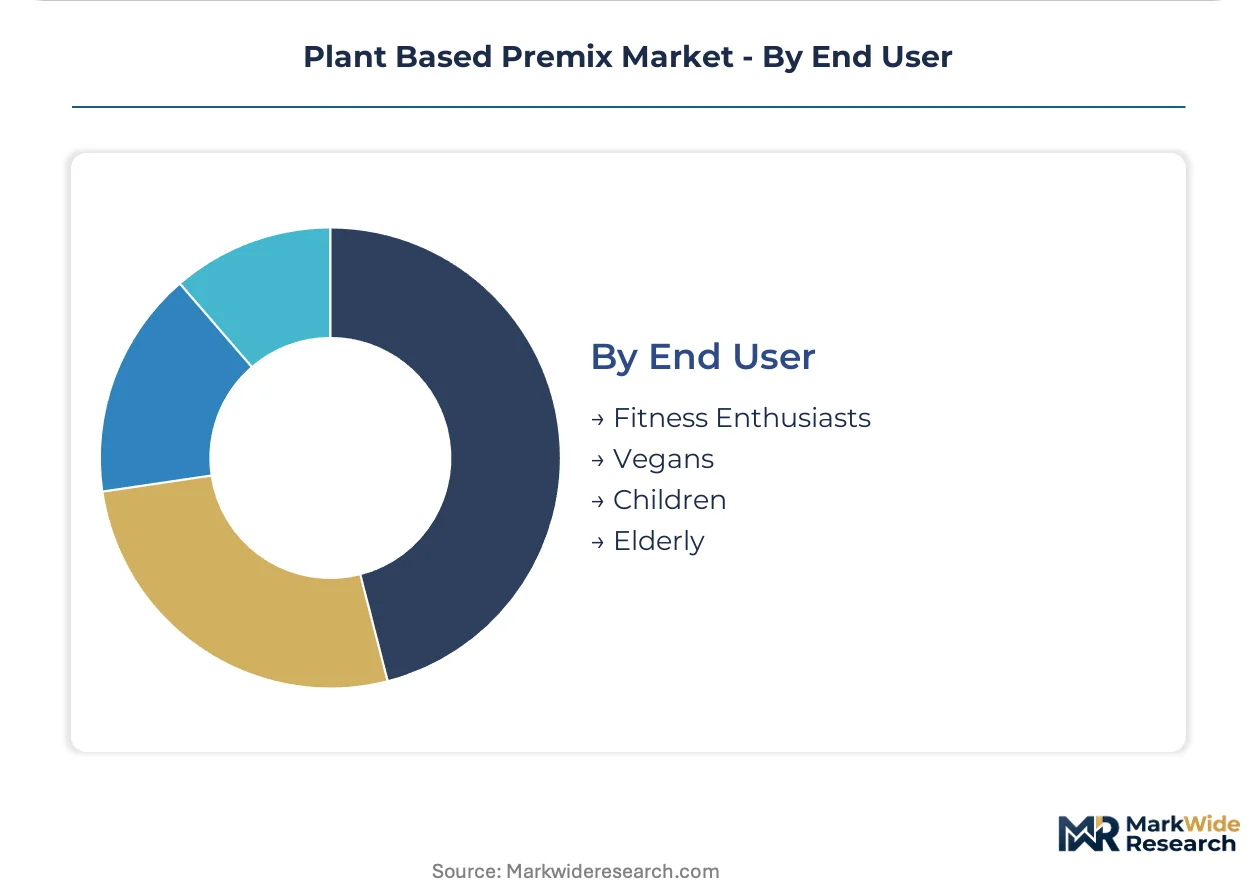
Fitness enthusiasts hold the largest share; momentum sits with vegan segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
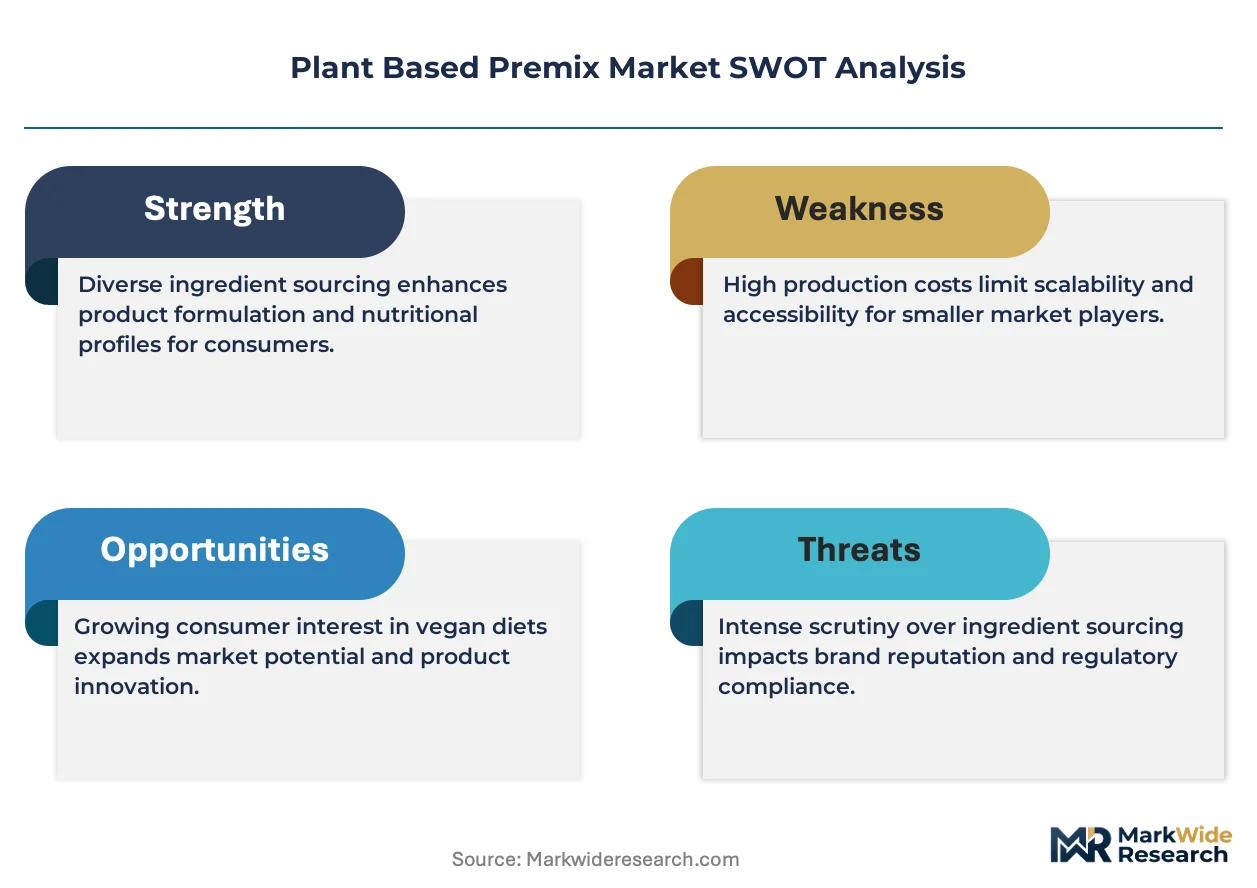
Pricing power concentrates in Germany where retail shelf expansion commands premium positioning, while India faces compliance friction that compresses export margins. The United States anchors precision fermentation investment volumes. Brazil's institutional catering channel opens liquid premix demand.
United States
Fitness-oriented household spending drives DIAAS-optimized protein powder demand in sports nutrition applications. FDA GRAS self-affirmation pathways for novel plant proteins require 18-24 month toxicology dossiers. California-based precision fermentation platforms anchor microbial dairy protein production for functional nutrition blends.
Germany
Flexitarian household trial behavior expands clean-label baking mix shelf space across retail networks. EFSA Regulation 1169/2011 mandates comprehensive allergen risk assessments for novel plant proteins. The Cologne-Düsseldorf corridor concentrates extrusion equipment manufacturing serving European meat analog producers.
United Kingdom
Subscription-based e-commerce channels capture vegan segment demand for specialized formulations unavailable through conventional retail. EU Green Deal procurement mandates now require carbon footprint disclosure in public sector foodservice contracts. London anchors headquarters-level procurement consolidation for vertically integrated premix houses.
India
Domestic nutraceutical channel expansion creates demand for fortified pediatric and elderly nutrition premixes. FSSAI draft notification standards for plant protein labeling extend market access timelines for international exporters. Maharashtra's food processing corridor concentrates mid-scale powder processing infrastructure.
Brazil
Institutional catering contracts drive import demand for aseptic liquid premixes with validated microbial stability. ANVISA regulatory harmonization with CODEX standards opens contract manufacturing pathways for ready-to-drink applications. São Paulo anchors foodservice distribution control for South American markets.
Plant Based Premix Market Competitive Landscape
Concentration sits with scaled powder processors and microbial protein platforms that have secured dual US-EU regulatory dossiers. The supplier base bifurcates between legacy extrusion-capable houses and precision fermentation entrants. Two strategic archetypes dominate: vertically integrated premix houses with in-house protein isolation, and technology licensors supplying microbial protein concentrates. Competitive moves center on capacity expansion in oat and fava bean processing, plus strategic partnerships to secure certified organic supply chains.
Among precision fermentation specialists, Perfect Day Foods exemplifies microbial dairy protein platform development, while Califia Farms anchors North American distribution control through retail and foodservice channel relationships. Oatly occupies a position extending brand recognition into oat-derived premix applications beyond traditional beverage segments. These three represent the convergence of ingredient technology and downstream channel access that defines current competitive positioning.
| Leading Market Players |
|---|
| Just, Inc. |
| TerViva |
| Perfect Day Foods |
| NovaMeat |
| C16 Biosciences |
| Califia Farms |
| Nobell Foods |
| GoodDot |
| Oatly |
| Others |
Value Network & Pricing Analysis
EFSA Regulation 1169/2011 allergen certification gates both supplier qualification and price differentiation, forcing European manufacturers to pay premiums for compliant premix sourcing while locking out uncertified competitors from flexitarian retail channels. This regulatory filter concentrates pricing power among dual US-EU dossier holders who capture margin premiums through certified supply security.
Pricing Analysis
Configured-to-order premix formulations command 15-25% premiums over standard-grade protein powders due to DIAAS optimization and custom emulsion stability requirements. Pricing stratifies across premium, standard, and economy tiers where certification grade and volume scale drive differentiation. Cost compression in standard-grade formulations is intensifying because pea protein isolate supply concentration exposes buyers to freight cost volatility. Foodservice contract manufacturers show highest price sensitivity, while infant formula adjacent applications demonstrate lowest elasticity due to quality liability exposure.
Supply Chain Analysis
Inventory cycles for novel pulse proteins stretch 8-12 weeks longer than legacy soy concentrates due to limited extrusion-ready stockpiles and just-in-time fractionation scheduling. Geographic supply concentration centers on Canada and northern France for pea protein isolate, with California and the Netherlands anchoring precision fermentation infrastructure. Raw material dependencies include yellow pea, fava bean, and microbial feedstock glucose. Single-source vulnerability runs through Canadian prairie crop yields exposed to drought frequency. Distribution runs through vertically integrated premix houses with captive protein isolation and vitamin microencapsulation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platform maturation constitutes a high-growth disruption reshaping ingredient hierarchies, with EFSA's evolving DIAAS scoring thresholds accelerating reformulation investments across the value chain.
For Market Incumbents: Shield market position by securing backward integration into oat and fava bean processing capacity in Germany and the United States, insulating against precision fermentation entrants disrupting protein powder margins. Accelerate dual US-EU regulatory dossier maintenance to defend against emerging microbial protein platforms capturing premium sports nutrition contracts. For New Entrants and Emerging Players: Liquid premix formulation services for Brazilian institutional catering represent a service-layer gap where incumbents under-serve due to ANVISA compliance complexity and aseptic processing capital requirements. Target this penetrable geography through foodservice channel partnerships with São Paulo-based distributors, leveraging regulatory harmonization momentum to displace powder-centric legacy suppliers. For Investors and Strategic Acquirers: EFSA's anticipated DIAAS scoring finalization reshapes the acquisition landscape toward precision fermentation platforms with validated amino acid optimization capabilities. Frame long-term viability around microbial protein production economics achieving cost parity with isolate processing. Target acquisition archetypes: shear-cell extrusion technology licensors with European meat analog pilot installations. Watch for FDA GRAS pathway acceleration for novel legume proteins as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Perfect Day Foods anchors microbial dairy protein production for functional nutrition blends. |
| Shear-Cell Extrusion Adoption | NovaMeat pilots low-temperature texturization reducing energy intensity versus twin-screw systems. |
| Dual Regulatory Dossier Investment | Califia Farms secures US-EU market access through synchronized FDA and EFSA compliance pathways. |
| Oat Protein Fractionation Expansion | Oatly extends brand recognition into baking premix segments beyond traditional beverage applications. |
| Carbon Footprint Certification Program | EU Green Deal procurement mandates favor domestic suppliers with verified lifecycle data disclosure. |
Research Methodology
The analysis maps protein powder, baking mix, smoothie mix, and nutritional supplement sub-sectors, each validated through formulation chemists, extrusion equipment manufacturers, retail category buyers, and foodservice procurement directors. Primary interviews with plant protein isolate processors and precision fermentation platform operators combined with secondary validation from EFSA guidance documents, FDA GRAS notifications, FSSAI draft standards, and customs trade flow data. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Consistency checks against external benchmarks validated projection outputs against disclosed capacity expansions and channel shipment patterns. The analytical framework segments by product type, form, distribution channel, and end user across the modeling period, with CAGRs derived from segment-level growth rate reconciliation. Forecast inputs include extrusion equipment order backlogs, precision fermentation facility commissioning timelines, and retail shelf space allocation data from German and United Kingdom supermarket networks.
Forecasts assume regulatory continuity in EFSA, FDA, and FSSAI regimes; material policy shifts such as accelerated DIAAS adoption or novel protein pathway streamlining would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Pea Flour Market
Ingredients
Almond Flour Market
Ingredients
Caramel Malt Market
Ingredients
Almond Ingredients Market
Ingredients
Egg Free Premix Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Yeast Autolysates Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Tapioca Pearls Market
Ingredients
Soy Peptones Market
Ingredients
Bean Ingredients Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Beverage Ingredients Market