
 Soy Protein Concentrate Market | 2026-2036
Soy Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Protein Concentrate Market Intelligence
The global framework for food allergen labeling, including mandates from the US FDA and the European Food Safety Authority (EFSA), is shifting the cost-of-entry calculus for new market participants. ADM leverages its extensive soybean sourcing and processing infrastructure to maintain a strong market position. Cargill competes on its integrated supply chain, supplying major food and beverage manufacturers. DuPont Nutrition & Biosciences differentiates through its focus on functional and specialty protein ingredients for high-value applications.
Soy protein concentrate is a refined soy product typically containing 65% to 70% protein content, produced by removing soluble carbohydrates from defatted soy flakes. Its primary function in food manufacturing is to enhance nutritional value, improve water retention, and provide emulsification properties. Textured soy protein concentrate leads the product type segment, driven by its essential role in formulating meat alternatives. Within applications, beverages represent a high-growth area as manufacturers seek to fortify drinks with plant-based protein.
Compliance with international food safety standards, such as ISO 22000 and guidelines from the World Health Organization (WHO), is fundamental for market access. National regulations, including China's GB standards and India's FSSAI rules, govern protein content claims and permissible applications. Strategic decisions for producers will center on managing the cost and supply chain complexities between non-GMO and conventional soybean sources to serve distinct consumer segments.
Market Dynamics
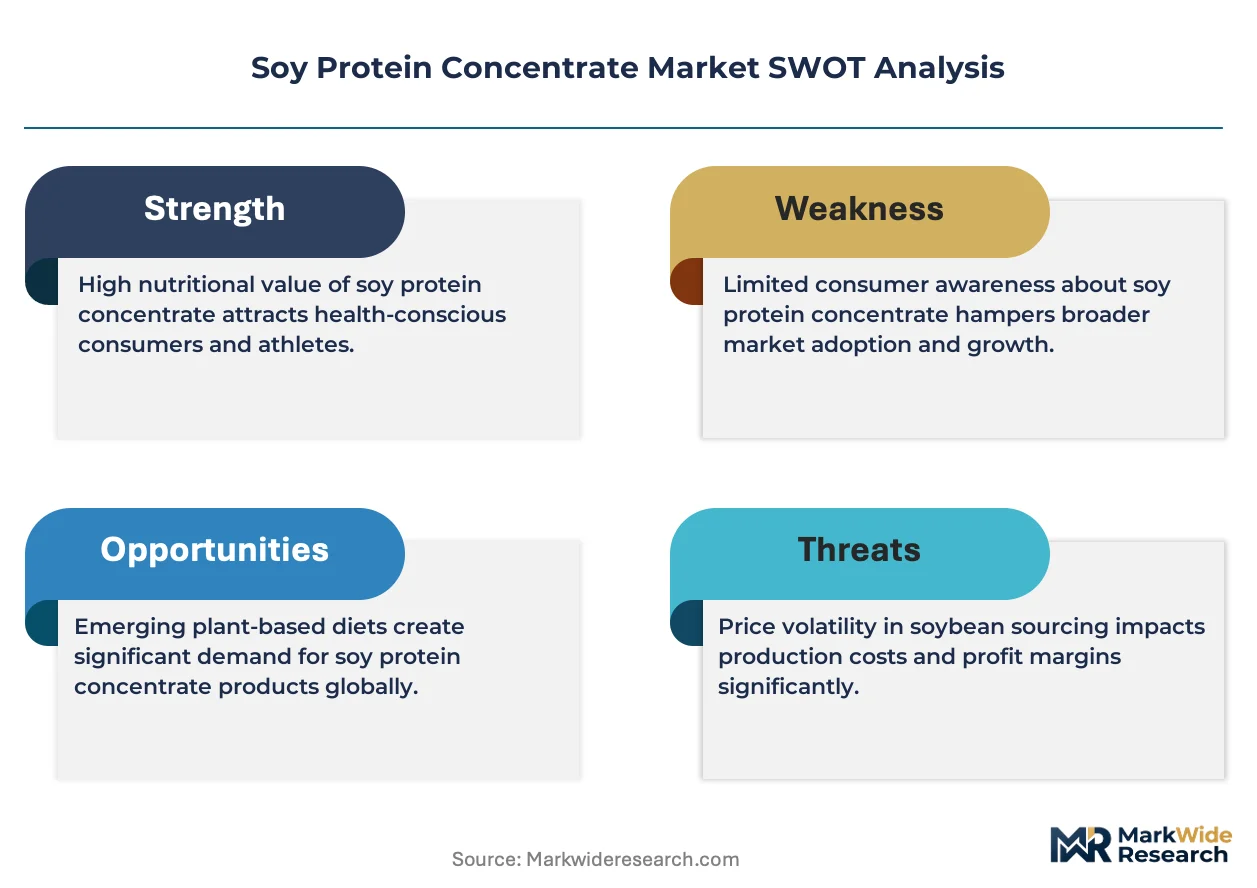
The central dynamic shaping the market is the bifurcation of supply chains between conventional and non-GMO soybeans. This split creates distinct cost structures and market access pathways, forcing producers to align sourcing strategies with specific end-user demands for clean-label or cost-effective formulations.
Growth Catalysts
- Meat Alternative Proliferation:Strong consumer preference for plant-based diets is driving significant uptake in the meat alternatives sector. Textured soy protein concentrate is a primary ingredient for creating meat-like textures in burgers, sausages, and other processed foods.
- Food Fortification Programs:National food fortification initiatives encourage the addition of protein to staple foods and beverages. India's FSSAI guidelines on protein content claims support its use in nutritional products sold across the country.
- China's Processing Industry:China's expanding food processing sector represents a major demand center. The country's GB standards for food ingredients are facilitating wider use of soy protein concentrate in domestically produced packaged foods.
Market Restraints
- Allergen Declaration Costs:Mandatory allergen labeling laws, such as those enforced by the US FDA and EFSA in Europe, increase compliance costs. This acts as a barrier for new entrants who must manage cross-contamination risks and stringent labeling protocols for soy.
- Soybean Price Fluctuations:The market is directly exposed to the price volatility of soybeans, a globally traded commodity. Weather events and trade policies impacting major producers like Brazil and the US create input cost instability for processors.
- Competition from Other Proteins:Pea, wheat, and fava bean proteins are gaining traction as alternatives in food formulation. Food manufacturers are diversifying their protein sources to mitigate allergen concerns and appeal to soy-free consumer segments.
Strategic Opportunities
- Beverage Fortification:The high-growth beverage sector presents a significant opportunity. Formulating soy protein concentrate for enhanced solubility and neutral taste can unlock applications in ready-to-drink protein shakes, dairy alternatives, and fortified juices.
- Southeast Asian Markets:Underpenetrated markets in Southeast Asia, such as Vietnam and Indonesia, offer expansion potential. Rising disposable incomes and a shift towards processed and fortified foods create new demand channels for protein ingredients.
- Functional Blends:Developing customized protein blends that combine soy concentrate with other plant proteins or hydrocolloids is an opportunity. These functional systems can offer superior emulsification or textural properties for high-value food applications.
Industry Challenges
- Non-GMO Traceability:Maintaining strict segregation and traceability for non-GMO soy from farm to final product is a significant operational challenge. It requires dedicated storage, transportation, and processing lines, adding complexity and cost compared to conventional supply chains.
- Navigating Global Standards:Adhering to a fragmented landscape of international food safety standards, including ISO 22000 and specific national rules like China's GB standards, demands substantial compliance resources, particularly for exporters targeting multiple regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Protein Concentrate Market |
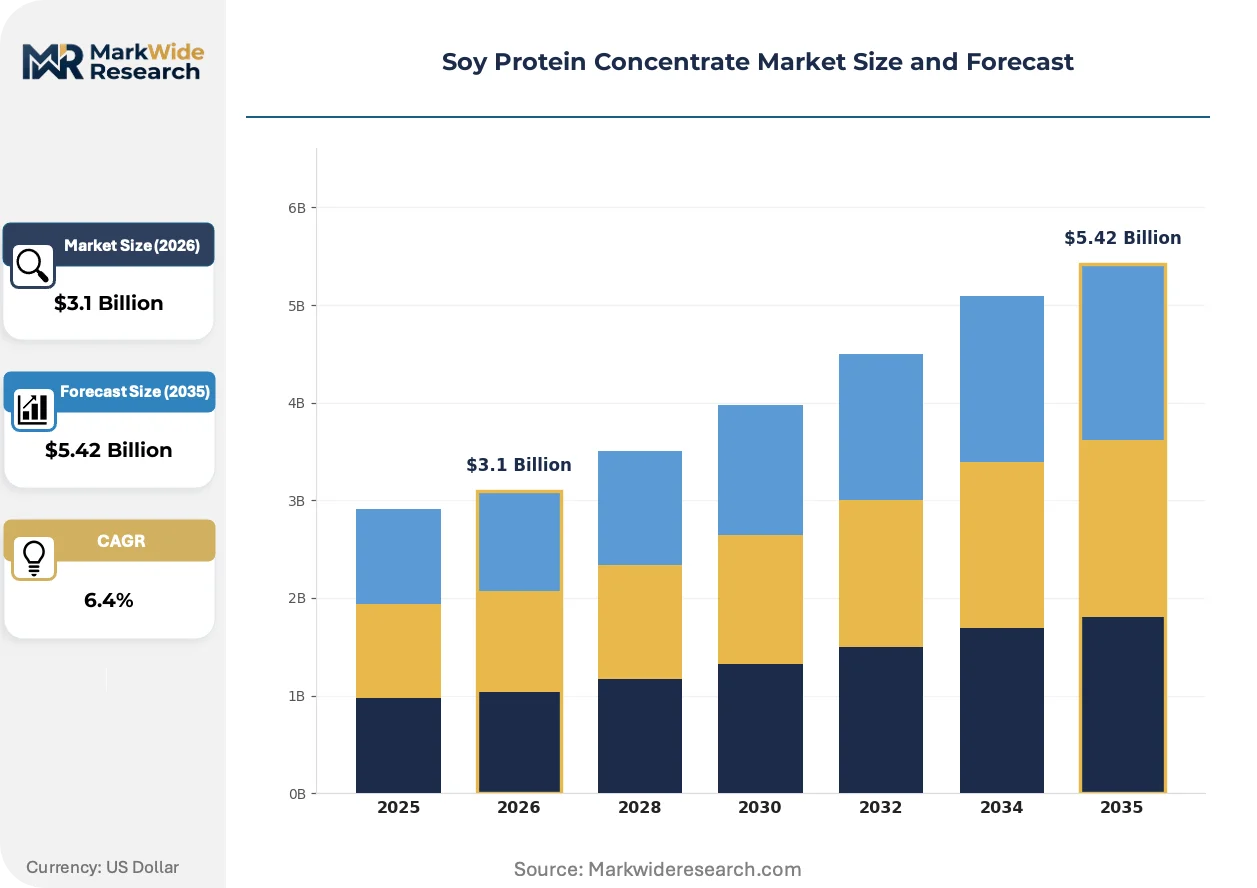
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured, Isolated, Defatted, Organic, Hydrolyzed Application: Beverages, Meat Alternatives, Bakery Goods, Confectionery, Dairy Substitutes End User: Food & Beverage Manufacturers, Nutraceutical Producers, Animal Nutrition, Sports Nutrition Brands, Cosmetic Industries Packaging Type: Bulk Bags, Sachets, Boxes, Drums, Vacuum Packs |
| Companies Covered | Bunge Limited, Kerry Group, ADM, Glanbia Nutritionals, CHS Inc., Cargill Inc., Wilmar International, Sotexpro, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Protein Concentrate Market Strategic Shifts & Innovations
Product innovation is centered on enhancing the functional properties of soy protein concentrate to meet specific formulation needs. This evolution is driven by parallel shifts in regulatory frameworks for food transparency and consumer demand for cleaner, more plant-forward product labels.
Advanced extrusion and texturization technologies are creating soy protein concentrates with more fibrous, meat-like structures. Food-tech startups and established CPG firms in the meat alternatives space are rapidly adopting these improved ingredients. This technological progress is rewriting the performance benchmarks for plant-based meat, enabling products that more closely mimic the sensory experience of conventional meat.
The proliferation of non-GMO verification standards, including the USDA Organic seal and EU organic regulations, is influencing ingredient sourcing. These frameworks mandate strict traceability, creating a premium segment for certified soy protein concentrate. Food manufacturers in North America and Europe increasingly specify these ingredients to meet clean-label demands from consumers.
A notable shift in purchasing behavior involves food manufacturers moving from single ingredients toward sourcing complete functional systems. This trend favors suppliers offering pre-formulated blends of soy protein concentrate with hydrocolloids or other proteins to achieve specific textural targets. This is most visible in the plant-based dairy and meat alternative categories, where speed-to-market is critical.
Soy Protein Concentrate Market Segmentation
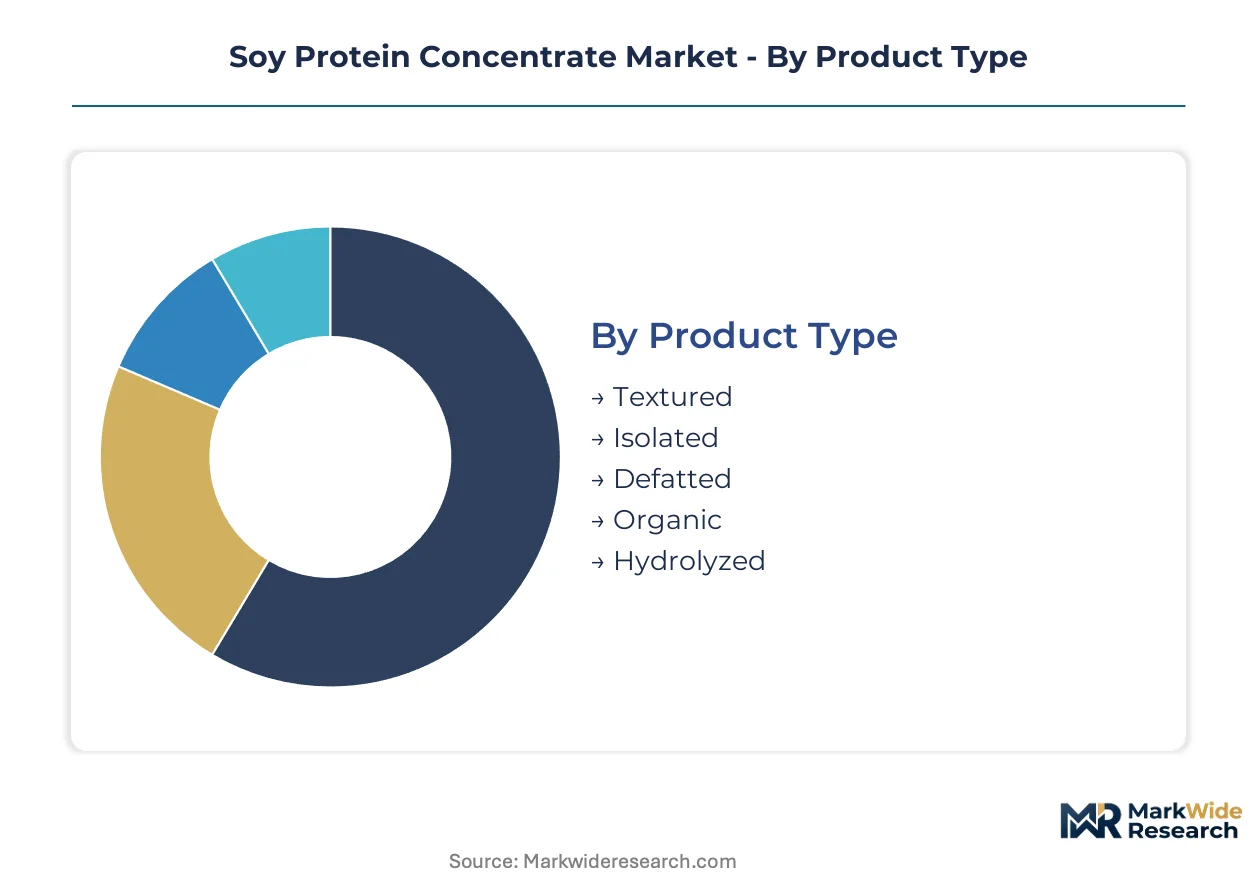
The segmentation analysis for the soy protein concentrate market illuminates the varied demand drivers and functional requirements across different product forms, applications, and end-user industries. Understanding these distinctions is crucial for producers to align their offerings with specific market needs and regulatory compliance.
Product Type:
The product type segmentation reflects the continuous upgrade cycle for ingredient functionality, driving demand for specialized soy protein concentrate forms.
- Textured:This product type is processed to create a fibrous, meat-like structure, making it indispensable for plant-based meat alternatives. Demand for textured soy protein concentrate is concentrating heavily within North America and European markets, driven by plant-forward dietary shifts.
- Organic:Certified organic soy protein concentrate adheres to strict non-GMO and clean-label standards, ensuring traceability from farm to finished product. Consumer demand for organic options is concentrating in Western markets, particularly among health-conscious buyers.
- Isolated:This refined form contains over 90% protein, suitable for high-protein applications like nutritional bars and shakes.
- Defatted:A basic form of soy protein concentrate, produced by removing oils, often used as a cost-effective protein source.
- Hydrolyzed:Undergoes enzymatic hydrolysis to improve solubility and digestibility, making it ideal for specialized nutritional products.
Volume placements concentrate in Textured soy protein concentrate; the faster expansion belongs to Organic variants.
Application:
Application areas delineate how soy protein concentrate is integrated into diverse food systems, each demanding specific functional attributes.
- Meat Alternatives:Soy protein concentrate is a foundational ingredient, providing texture, binding, and nutritional value to plant-based burgers, sausages, and other processed foods. Demand for this application is concentrating significantly in China's food processing industry and Western consumer markets.
- Beverages:Formulations for fortified drinks require soy protein concentrate with enhanced solubility and a neutral taste profile to avoid off-notes. This application represents a high-growth area as manufacturers fortify ready-to-drink protein shakes and dairy alternatives.
- Bakery Goods:Incorporates soy protein concentrate to boost protein content, improve dough elasticity, and extend shelf life in various baked products.
- Confectionery:Used to enrich snack bars, protein candies, and other sweet treats with plant-based protein.
- Dairy Substitutes:Provides protein and emulsification properties to plant-based milk, yogurt, and cheese alternatives.
Specific applications dictate formulation requirements, with Meat Alternatives requiring unique textural properties for consumer acceptance.
End User:
End-user categories highlight the diverse industries leveraging soy protein concentrate for product development and nutritional enhancement.
- Food & Beverage Manufacturers:This segment represents the largest consumer, utilizing soy protein concentrate across a broad spectrum of products for nutritional fortification and functional benefits. Demand from this end-user is concentrating in established markets like North America and Europe, alongside rapidly expanding regions such as China.
- Sports Nutrition Brands:These brands require highly soluble and digestible forms of soy protein concentrate for protein powders, bars, and ready-to-drink shakes catering to athletes and active individuals. Demand is concentrating in markets with high disposable incomes and a strong fitness culture.
- Nutraceutical Producers:Formulate dietary supplements, functional foods, and health-enhancing products using soy protein concentrate for its protein content.
- Animal Nutrition:Employs soy protein concentrate as a crucial protein source in feed formulations for livestock, poultry, and aquaculture.
- Cosmetic Industries:Utilizes soy proteins for their moisturizing, film-forming, and conditioning properties in skin and hair care products.
Each end-user segment presents distinct purchasing criteria, from bulk supply for Food & Beverage Manufacturers to specialty ingredients for Sports Nutrition Brands.
Packaging Type:
Packaging types reflect the logistical and preservation needs across the supply chain, from industrial volumes to consumer-ready formats.
- Bulk Bags:These large containers are preferred by industrial food processors for cost-effective transportation and storage of significant volumes of soy protein concentrate. Demand for bulk packaging is concentrating in large-scale manufacturing facilities globally.
- Sachets:Small, single-serving sachets cater to convenience-driven consumers and specific retail applications, emphasizing portion control and ease of use. Demand for sachets is concentrating in consumer-facing product lines and direct-to-consumer channels.
- Boxes:Intermediate packaging solutions for smaller industrial clients or commercial kitchens, offering manageable quantities.
- Drums:Used for specific volumes of soy protein concentrate, particularly for specialized or higher-value formulations requiring robust protection.
- Vacuum Packs:Provides extended shelf life and preserves product integrity for sensitive or premium soy protein concentrate variants.
The choice of packaging reflects operational scale and preservation needs, with Bulk Bags dominating industrial supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for soy protein concentrate is concentrating significantly in rapidly expanding food processing industries across Asia and established markets in the West. Global food manufacturers require diverse product forms for plant-based formulations and nutritional fortification. This geographic distribution reflects varying consumer preferences and regulatory landscapes.
China
China's expanding food processing sector drives substantial demand for soy protein concentrate, particularly for meat alternatives. The country's GB standards for food ingredients facilitate wider use in domestically produced packaged foods. Food manufacturers in the Yangtze River Delta utilize significant volumes for new product development and nutritional enhancement.
United States
United States consumers show strong preference for plant-based diets, fueling uptake in the meat alternatives sector. US FDA allergen labeling laws mandate clear declaration for soy, influencing ingredient selection by food manufacturers. Food-tech startups in California actively integrate textured soy protein concentrate into novel plant-based products.
Germany
German consumers increasingly seek plant-forward dietary options, driving demand for organic soy protein concentrate in Europe. EU organic regulations mandate strict traceability for certified ingredients, impacting sourcing strategies for food manufacturers. Food production hubs in North Rhine-Westphalia focus on clean-label formulations using high-quality soy proteins.
India
India's national food fortification initiatives encourage adding protein to staple foods and beverages across the country. The FSSAI guidelines on protein content claims support soy protein concentrate use in various nutritional products. Food manufacturers in Maharashtra integrate soy protein concentrate into fortified flours and protein-enriched snacks.
Brazil
Brazil's robust agricultural sector and growing domestic food processing industry create demand for soy protein concentrate. ANVISA regulations govern the use of food additives and nutritional claims, influencing product formulations. Food and beverage manufacturers in São Paulo utilize significant volumes for both local consumption and export-oriented protein products.
Soy Protein Concentrate Market Key Industry Players
North American and European producers anchor one tier, leveraging extensive soybean sourcing infrastructure; Asian specialists hold another, focusing on regional market needs. The market structure exhibits moderate consolidation, with a few large players dominating raw material supply and processing. Key strategic archetypes include integrated agri-food giants, specialized protein ingredient providers, and regional processors. Dominant competitive moves involve strategic partnerships for product development and capacity expansion to meet plant-based demand.
Among global agri-food conglomerates, ADM and Cargill Inc. exemplify large-scale, vertically integrated operations. These companies leverage extensive soybean sourcing and processing infrastructure to serve major food and beverage manufacturers worldwide. DuPont Nutrition & Biosciences represents a specialized protein ingredient provider, differentiating through its focus on functional and specialty protein ingredients. This firm occupies a position catering to high-value applications requiring advanced textural or nutritional properties in plant-based food formulation. Such players continuously refine their offerings to meet evolving clean-label requirements and diverse end-user specifications across the market.
| Leading Market Players |
|---|
| Bunge Limited |
| Kerry Group |
| ADM |
| Glanbia Nutritionals |
| CHS Inc. |
| Cargill Inc. |
| Wilmar International |
| Sotexpro |
| DuPont Nutrition & Biosciences |
| Others |
Cost & Logistics Intelligence
Non-GMO verification standards, as a production-method transition, simultaneously reshapes cost economics by adding segregation requirements and influences supply concentration by favoring producers with robust traceability infrastructure.
Pricing Analysis
Volume sales of defatted soy protein concentrate typically operate on thinner margins, while specialty organic and hydrolyzed variants command a premium. The market primarily utilizes a contract-based long-term offtake pricing model for industrial buyers. Price differentiation stems from the certification level, such as USDA Organic or non-GMO status, and the specific functional properties offered by specialized forms. Pricing softness runs through the conventional segment due to soybean price volatility and competition from other protein sources. Food & Beverage Manufacturers focused on cost-effective formulations exhibit the highest price sensitivity, whereas Sports Nutrition Brands prioritizing performance are less sensitive.
Supply Chain Analysis
Soy protein concentrate production relies heavily on the availability of defatted soy flakes, primarily sourced from major soybean-producing nations like Brazil and the United States. Supply concentration for processing centers in regions with established crushing facilities, including China and parts of Europe. Soybean price volatility represents a significant structural risk for the entire supply chain, directly impacting input costs for processors. Distribution runs through a network of integrated agri-food giants and specialized ingredient distributors, serving major food and beverage manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, where stringent US FDA allergen labeling laws create a barrier-to-entry moat for compliant players with robust quality control systems.
For Market Incumbents: Anchor market share through robust supply chain integration and investment in non-GMO processing capabilities. This defends against margin pressure from commodity price fluctuations and competition from alternative proteins. Leverage R&D to develop functional blends that address specific formulation challenges in plant-based applications.
For New Entrants and Emerging Players: Specialized functional beverage manufacturers represent an underserved buyer archetype seeking highly soluble and neutral-tasting protein ingredients. Target underpenetrated Southeast Asian markets with tailored product offerings, focusing on organic variants to meet rising clean-label demands. A go-to-market angle emphasizing customized functional blends for specific applications offers differentiation.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized protein ingredient providers given the sustained demand for functional, plant-based formulations. Acquisition targets should include regional processors with strong non-GMO sourcing and advanced texturization capabilities. A signal to watch is the increasing investment in extrusion technologies by food-tech startups, indicating future ingredient performance benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Meets rising demand from developing food processing industries in countries like Vietnam and Indonesia. |
| Backward Integration into Non-GMO Sourcing | Secures supply of certified raw materials, reducing price volatility and ensuring clean-label compliance. |
| Product Launch: Functional Blends | Offers customized solutions for specific textural and solubility needs in plant-based dairy and meat. |
| Geographic Expansion: China Processing Hubs | Captures significant demand from China's expanding food processing sector and its GB standards. |
| R&D in Advanced Extrusion Technologies | Enables the creation of more fibrous, meat-like structures for next-generation meat alternatives. |
Research Approach
Independent corroboration across USDA reports, EFSA publications, and FSSAI guidelines underwrites the qualitative findings of this study. Primary interviews with food technologists, procurement managers, regulatory affairs specialists, and R&D directors provided critical market insights. This was complemented by secondary validation from company annual reports and trade association publications, ensuring a comprehensive bottom-up and top-down triangulation of data.
Historical reference periods anchored the forecast window, establishing baseline growth rates for soy protein concentrate adoption. The analytical framework modeled segmentation across product type, application, end-user, packaging type, and regional regulatory compliance. Compound annual growth rates were derived from a synthesis of historical trends and projected market influences. Key industry-specific forecast inputs included soybean commodity prices and evolving plant-based food consumption trends.
Revisions become necessary when major weather events impact soybean harvests or unforeseen trade policies alter commodity flows. Forecasts reflect assumptions regarding consumer preference shifts and regulatory stability in key markets. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
European Brewing Enzymes Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Cocoa Derivatives Market
Ingredients
Chickpea Protein Market
Ingredients
Fermented Ingredients Market
Ingredients
Non-GMO Oil Market
Ingredients
Corn Steep Liquor Market
Ingredients
Egg White Powder Market
Ingredients
Halal Ingredients Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Europe Agar Market
Ingredients
Chewing Gum Base Market