
 Europe Electric Vehicle Battery Electrolyte Market | 2026-2036
Europe Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Electrolyte Market Insights
Fluorinated solvents are restructuring electrolyte formulations as manufacturers phase out conventional carbonate blends to improve thermal stability and high-voltage tolerance. BASF Corporation leverages its integrated chemical production network to secure precursor supply for lithium salts. Umicore anchors European refining capacity for battery-grade electrolyte additives. Samsung SDI competes through proprietary high-concentration formulations developed at its European R&D centers.
Europe Electric Vehicle Battery Electrolyte comprises ion-conducting media formulated from lithium salts dissolved in organic solvent blends, typically operating within a viscosity range of 2-5 mPa·s and ionic conductivity exceeding 5 mS/cm at room temperature to enable lithium-ion transport between cathode and anode during charge and discharge cycles. Liquid Electrolyte dominates current production volumes due to established manufacturing infrastructure and compatibility with conventional lithium-ion cell architectures, while Solid-State Electrolyte represents the fastest-expanding technology category as OEMs target energy density thresholds above 400 Wh/kg. Passenger Vehicles absorb the majority of electrolyte demand, though Commercial Vehicles are emerging as a concentrated growth vector driven by fleet electrification mandates in Germany and France.
EMA guidelines on cell chemistry safety and the EU Battery Regulation's carbon footprint scoring system are tightening compliance requirements for electrolyte suppliers seeking market access across member states. REACH chemical registration protocols govern solvent classifications and occupational exposure limits in European manufacturing facilities. Stakeholders must monitor solid-state pilot line yields and polymer electrolyte interface stability as these parameters determine which chemistry platforms achieve scalable cost parity with liquid systems.
Market Dynamics
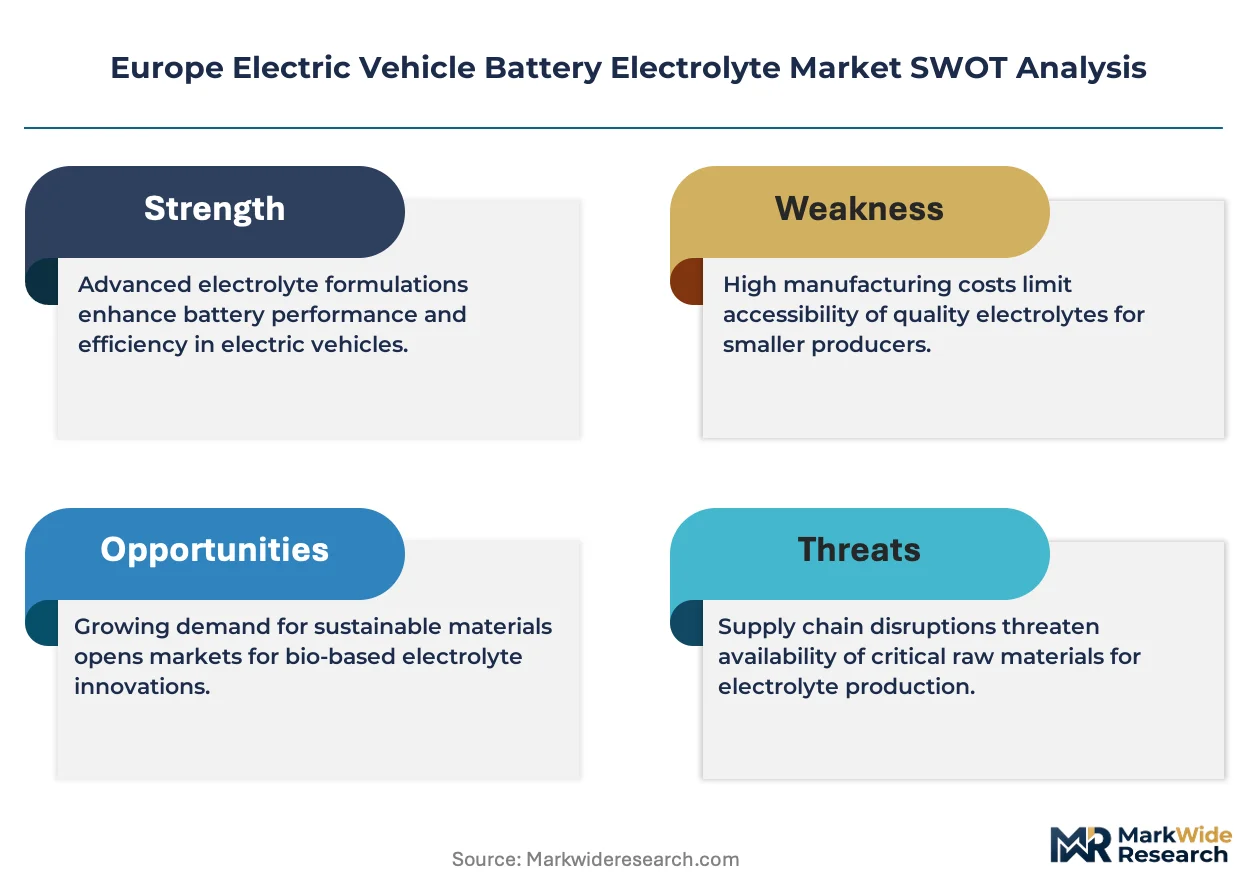
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are forcing electrolyte suppliers to restructure supply chains around European refining capacity and closed-loop solvent recovery systems.
Growth Catalysts
- Fleet Electrification Mandates:Germany's commercial vehicle electrification targets and France's ban on internal combustion engine sales are anchoring cell gigafactory investments across the Rhine-Ruhr and Hauts-de-France corridors.
- REACH Chemical Registration:Standardized solvent classifications under ECHA protocols are reducing regulatory fragmentation and accelerating cross-border electrolyte formulation approvals for suppliers operating multiple EU member state facilities.
- High-Voltage Cathode Chemistries:Nickel-rich layered oxide cathodes operating above 4.3V are demanding fluorinated co-solvent blends that conventional carbonate electrolytes cannot support, creating formulation upgrade cycles.
Market Restraints
- Lithium Hexafluorophosphate Concentration:Over 70% of LiPF6 precursor supply originates from Chinese chemical processors, exposing European formulators to input cost volatility and tariff exposure under evolving trade measures.
- Solid-State Pilot Line Yields:Polymer-ceramic composite electrolytes remain trapped at sub-scale manufacturing with interface impedance stability problems that liquid systems solved decades ago.
- F-Gas Regulation Phase-Down:Perfluorinated solvent additives face quota restrictions under the EU F-Gas Regulation, complicating thermal stability improvements for high-voltage formulations.
Strategic Opportunities
- Polish Battery Valley:LG Energy Solution and SK On are anchoring cell production in Lower Silesia where electrolyte blending capacity remains undersupplied relative to cathode and anode material investments.
- CSRD Supply Chain Disclosure:Corporate Sustainability Reporting Directive requirements are creating first-mover advantages for electrolyte suppliers with certified carbon footprint data and blockchain-tracked recycled content.
- Solid-Polymer Hybrid Architectures:Gel polymer electrolytes combining liquid ionic conductivity with solid-state mechanical stability offer a bridging technology for OEMs not ready for full ceramic conversion.
Industry Challenges
- Electrochemist Talent Scarcity:European universities produce insufficient battery-specific formulation PhDs to staff R&D centers in Stuttgart, Munich, and Tampere, forcing reliance on Asian-trained specialists.
- EU Battery Regulation Certification Timelines:Carbon footprint scoring and due diligence documentation requirements are extending product qualification cycles by 12-18 months for non-integrated suppliers.
- Legacy Cell Architecture Integration:Dry electrode coating processes being piloted by European OEMs demand electrolyte wetting profiles incompatible with conventional vacuum infiltration equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Electrolyte Market |
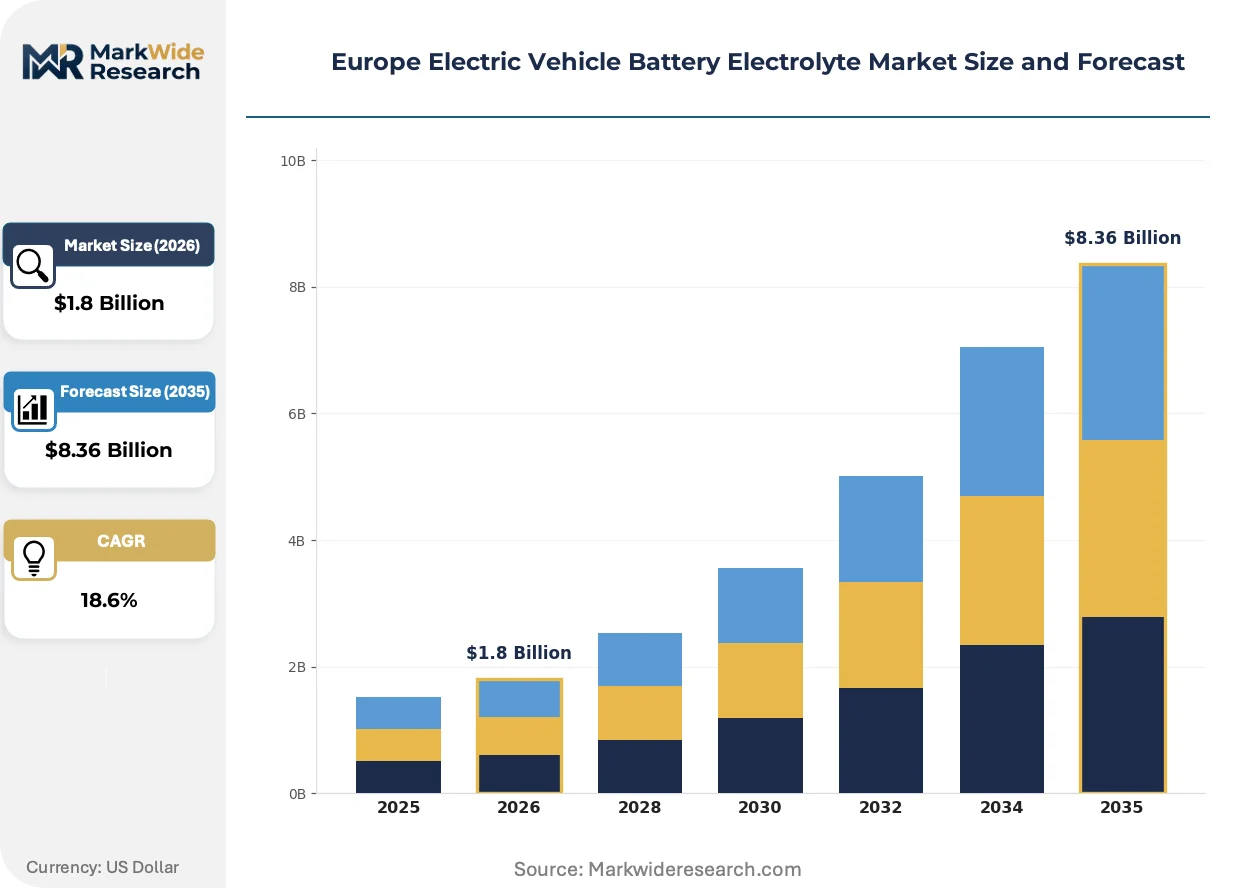
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolyte, Gel Electrolyte, Solid-State Electrolyte, Polymer Electrolyte Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes End User: OEMs, Aftermarket Providers, Fleet Operators, Manufacturers Technology: Conventional Lithium-Ion, Lithium-Sulfur, Solid-State, Hybrid Batteries |
| Companies Covered | 3M Company, Capchem, Targray Technology International Inc, Samsung SDI, LG Energy Solution, BASF Corporation, NEI Corporation, Umicore, Mitsubishi Chemical Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Electrolyte Market Trends and Innovations
Fluorinated solvent systems are unifying thermal stability and high-voltage tolerance in a single formulation platform, displacing the carbonate-dominated architectures that defined the last decade of lithium-ion commercialization.
Sulfone-based co-solvents with trifluoromethyl substituents are unifying oxidative stability above 5V with acceptable viscosity profiles for high-speed coating lines. Cell manufacturers in Germany's Baden-Württemberg cluster are qualifying these formulations for 800V architectures. This chemistry is unifying previously separate additive packages into streamlined binary-solvent systems, reducing formulation complexity and batch-to-batch variation.
REACH Annex XVII restrictions on volatile organic compound emissions are tightening solvent recovery requirements for European electrolyte blending facilities. ECHA's 2023 update to occupational exposure limits for ethylene carbonate is forcing capital investment in closed-loop purification systems. Suppliers with integrated solvent recycling operations in Belgium and the Netherlands are capturing margin advantages over toll-blending competitors.
Automotive OEM procurement departments are consolidating electrolyte supply agreements under multi-year, volume-guaranteed frameworks that displace spot-market purchasing. Tier-1 cell manufacturers in Hungary and Poland are locking in five-year contracts with fixed-price escalators indexed to lithium salt feedstock costs. This concentration is most visible at Northvolt's Skellefteå and Heidelberg facilities, where single-source electrolyte agreements now cover entire cell chemistry platforms.
Europe Electric Vehicle Battery Electrolyte Market Segmentation
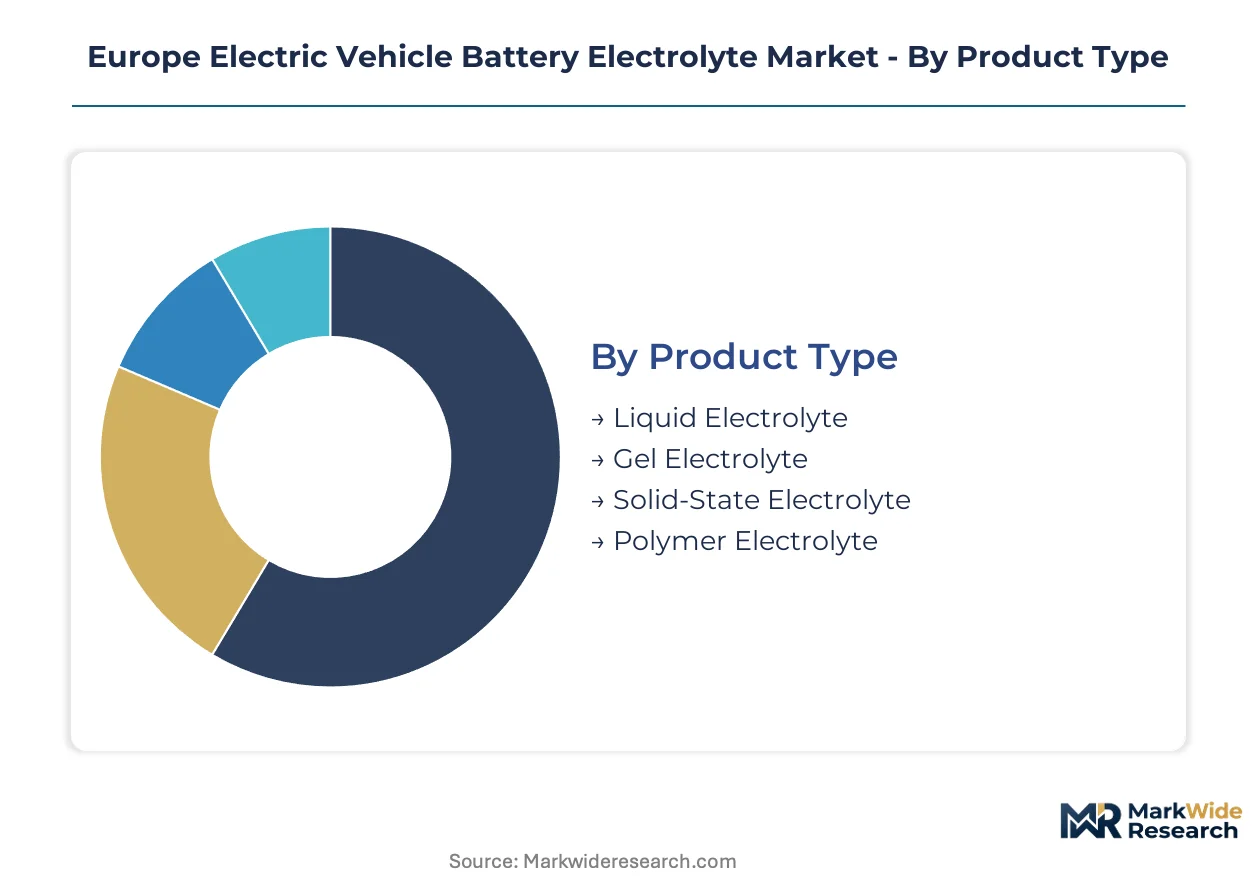
Electrolyte procurement patterns diverge sharply across cell architectures and customer types, with formulation specifications tightening as European OEMs lock in multi-year supply agreements. Segmentation reveals how technology transitions and regulatory compliance are redrawing competitive boundaries between incumbent liquid systems and emerging solid-state platforms.
Product Type:
Cost tier determines procurement scale and margin structure, with established liquid systems commanding volume contracts while novel chemistries capture premium positioning for next-generation cells.
- Liquid Electrolyte:Conventional carbonate-based formulations dissolve lithium hexafluorophosphate in ethylene carbonate and dimethyl carbonate blends, achieving ionic conductivity above 5 mS/cm at room temperature. Germany's Baden-Württemberg automotive cluster anchors procurement volumes through Northvolt and CATL European operations, though REACH Annex XVII solvent recovery mandates are elevating capital requirements for blending facilities.
- Solid-State Electrolyte:Ceramic and sulfide-based ionic conductors eliminate flammable organic solvents while enabling lithium-metal anode compatibility for energy densities targeting 400 Wh/kg. France's Hauts-de-France corridor is emerging as a qualification hub where Saft and Automotive Cells Company are piloting polymer-ceramic composite architectures.
- Gel Electrolyte:Polymer matrices immobilize liquid electrolyte in a quasi-solid matrix, bridging manufacturing compatibility and safety improvements for cylindrical cell formats.
- Polymer Electrolyte:Dry solid polymer electrolytes based on polyethylene oxide complexes operate without liquid components, constrained by room-temperature conductivity limitations.
Volume sits with Liquid Electrolyte; growth tilts toward Solid-State Electrolyte.
Application:
Vehicle class dictates thermal management requirements and formulation complexity, with commercial platforms demanding wider operating temperature ranges than passenger car specifications.
- Passenger Vehicles:C-segment and D-segment battery electric vehicles from Volkswagen, BMW, and Stellantis absorb the majority of electrolyte procurement through 800V architectures requiring high-voltage-tolerant fluorinated co-solvents.
- Commercial Vehicles:Heavy-duty trucks and urban delivery vans operate across wider temperature extremes, demanding electrolyte formulations with enhanced low-temperature conductivity and thermal stability. Germany's fleet electrification mandates for municipal logistics are concentrating demand in the Rhine-Ruhr industrial corridor.
- Two-Wheelers:Low-cost cylindrical cells for electric scooters prioritize cost-optimized carbonate formulations with simplified additive packages.
- E-Bikes:Small-format pouch cells require electrolyte wetting profiles optimized for high-speed winding processes and limited formation cycling budgets.
Procurement concentrates in Passenger Vehicles; Commercial Vehicles are expanding most quickly as fleet mandates tighten.
End User:
Customer integration depth separates formulators serving captive cell production from independent suppliers competing on specification flexibility and qualification speed.
- OEMs:Vertically integrated automotive manufacturers including Volkswagen Group and Mercedes-Benz are bringing electrolyte blending in-house at cell gigafactories to secure supply chain control and carbon footprint traceability under EU Battery Regulation requirements.
- Manufacturers:Independent cell producers such as Northvolt and Samsung SDI Europe procure electrolyte under long-term framework agreements with volume escalators indexed to lithium salt feedstock costs.
- Fleet Operators:Commercial vehicle fleet managers are emerging as specification influencers through battery-as-a-service contracts that demand extended cycle life guarantees.
- Aftermarket Providers:Service networks for battery replacement and refurbishment require small-batch electrolyte supply for cell remanufacturing operations.
Contract value sits with OEMs; specification influence is climbing fastest among Fleet Operators.
Technology:
Cell chemistry platform determines electrolyte formulation architecture, with high-nickel cathodes and silicon-anode systems driving additive complexity beyond conventional lithium-ion baselines.
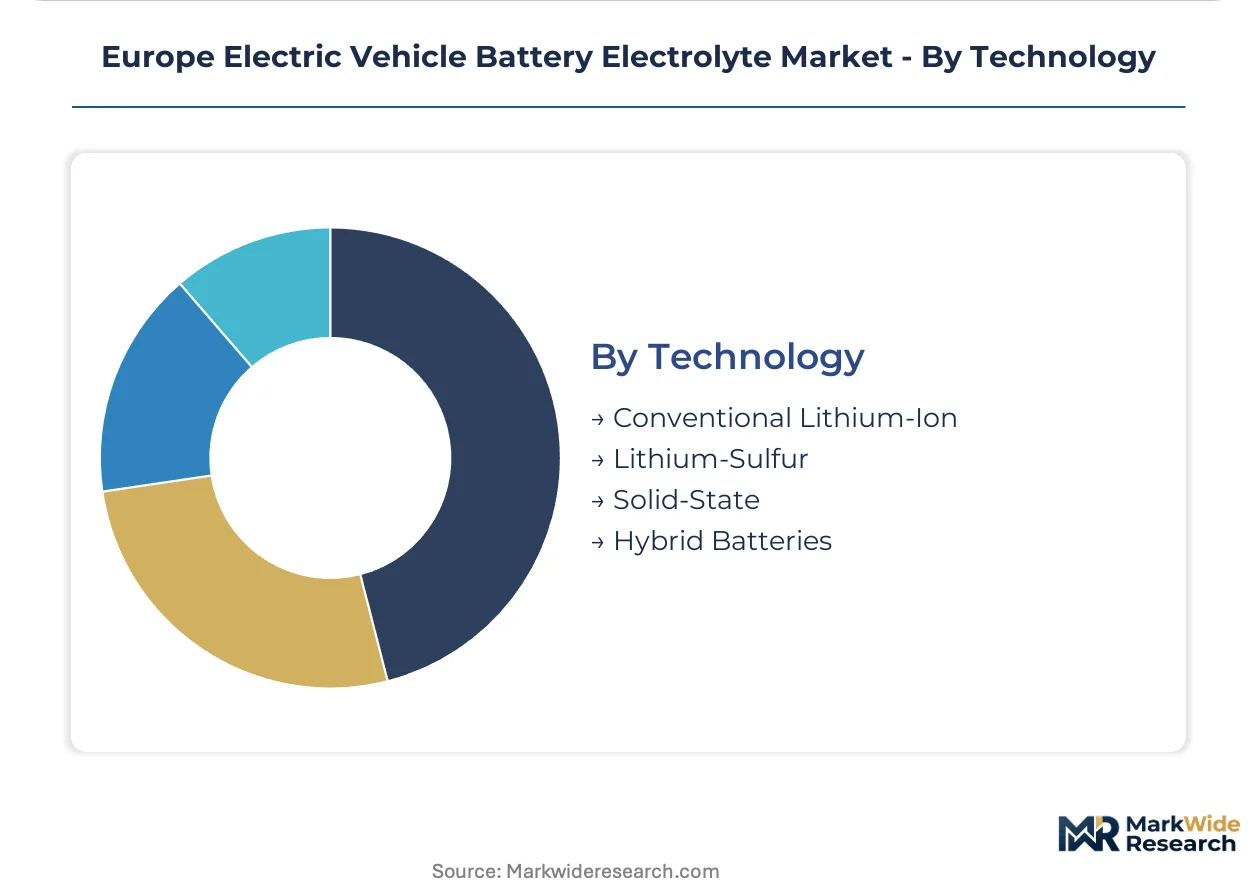
- Conventional Lithium-Ion:Graphite anode and NMC cathode cells dominate current production, utilizing established carbonate electrolyte formulations with vinylene carbonate and fluoroethylene carbonate additives for SEI stabilization.
- Solid-State:Lithium-metal anode architectures eliminate liquid components entirely, requiring sulfide or oxide ceramic electrolytes with interface engineering solutions still resolving manufacturing scalability.
- Lithium-Sulfur:High theoretical energy density systems demand polysulfide-shuttle-suppressing electrolyte additives and solvent formulations with enhanced donor number characteristics.
- Hybrid Batteries:Dual-chemistry systems combining lithium-ion power density with solid-state safety margins require electrolyte architectures bridging liquid wetting and solid interface stability.
Deployment volume sits with Conventional Lithium-Ion; technology transition is accelerating fastest in Solid-State pilot lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric vehicle battery electrolyte concentrates in Germany's automotive manufacturing corridor, where cell gigafactory investments anchor procurement volumes. France and Poland follow as secondary demand centers driven by fleet electrification mandates and battery valley developments. The EU Battery Regulation applies uniform recycled content and carbon footprint requirements across all member states, though national industrial strategies create divergent cluster formations.
Germany
North Rhine-Westphalia and Baden-Württemberg host the continent's densest concentration of cell production capacity, with Northvolt's Heidelberg facility and CATL's Erfurt operation driving electrolyte procurement volumes. The KBA enforces battery safety certifications that extend qualification timelines for new electrolyte formulations. Stuttgart's automotive engineering cluster anchors BASF Corporation's European electrolyte blending operations, serving Volkswagen Group and Mercedes-Benz captive cell production.
France
Hauts-de-France emerges as a qualification hub for solid-state electrolyte architectures, where Automotive Cells Company and Saft pilot polymer-ceramic composite systems. The national ban on internal combustion engine sales by 2035 accelerates cell gigafactory commitments in the Dunkirk corridor. ANSM guidelines on industrial chemical safety intersect with REACH protocols to govern solvent handling at blending facilities near the Belgian border.
Poland
Lower Silesia's Battery Valley attracts LG Energy Solution and SK On cell investments that outpace local electrolyte blending capacity, creating supply gaps filled by German and Belgian formulators. The country's national industrial strategy offers tax incentives for battery supply chain localization. Wrocław and Jawor host cathode and anode material plants that lack matched electrolyte production, forcing cross-border logistics dependencies.
Sweden
Northvolt's Skellefteå gigafactory operates Europe's most vertically integrated cell production, with single-source electrolyte agreements covering entire chemistry platforms. The Swedish Chemicals Agency enforces stricter occupational exposure limits than EU minimums, elevating capital requirements for solvent recovery systems. Västerbotten County's renewable electricity access supports carbon footprint scoring advantages under EU Battery Regulation frameworks.
Belgium
Antwerp's petrochemical infrastructure anchors Umicore's refining operations for battery-grade electrolyte additives, leveraging port logistics for lithium salt imports. The Flemish region's integrated solvent recycling ecosystem captures margin advantages over toll-blending competitors in neighboring markets. ECHA's proximity in Helsinki creates regulatory clarity advantages for Belgian facilities seeking rapid REACH compliance certifications.
Europe Electric Vehicle Battery Electrolyte Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding premium-tier supply agreements while independent formulators compete on qualification speed. The vendor base concentrates around three strategic archetypes: diversified chemical majors with precursor backward integration, cell manufacturer captive operations, and specialized additive refiners. Competitive dynamics center on multi-year volume contracts with fixed-price escalators and carbon footprint certification speed under CSRD disclosure timelines.
Among diversified chemical majors, BASF Corporation and Umicore exemplify the integrated archetype, combining precursor production with formulation blending to secure supply chain control. Mitsubishi Chemical Group anchors the Asian-origin specialist tier, representing legacy electrolyte technology platforms. Samsung SDI occupies a hybrid position as both cell producer and electrolyte formulator, reflecting vertical consolidation trends among tier-1 manufacturers. These players illustrate how regulatory compliance capabilities and feedstock security separate sustainable competitors from toll-dependent operators.
| Leading Market Players |
|---|
| 3M Company |
| Capchem |
| Targray Technology International Inc |
| Samsung SDI |
| LG Energy Solution |
| BASF Corporation |
| NEI Corporation |
| Umicore |
| Mitsubishi Chemical Group |
| Others |
Pricing and Supply Chain Analysis
Captive blending operations at Northvolt and Automotive Cells Company anchor supply security and pricing power by internalizing formulation costs that independent suppliers must mark up. This integration choice insulates OEM cell production from lithium salt feedstock volatility while compressing margins for toll-blending competitors across the Rhine-Ruhr corridor.
Pricing Analysis
Volume procurement through multi-year framework agreements captures economy-tier positioning, while spot-market purchases and specialized solid-state formulations command premium tiers. Price differentiation rests on carbon footprint certification speed under CSRD timelines and REACH Annex XVII compliance grade. Cost compression in standard carbonate formulations is intensifying because Chinese LiPF6 precursor supply dominates feedstock costs. Fleet operators through battery-as-a-service contracts prove least price-sensitive due to cycle-life guarantee requirements, whereas aftermarket remanufacturing operations face acute cost pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through single-source agreements covering entire chemistry platforms at Northvolt and CATL European operations. Geographic supply concentration centers on Germany, Belgium, and Poland, with Lower Silesia's Battery Valley exhibiting acute electrolyte capacity deficits relative to cathode and anode investments. Raw material dependencies draw from Chinese LiPF6 processors, Belgian additive refineries, and German solvent recovery infrastructure. Single-source vulnerability in lithium salt precursor supply creates structural exposure to tariff measures and input cost spikes. Distribution runs through integrated chemical majors with backward control over precursor production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Vehicle Battery Electrolyte Market operates as a cost-of-compliance arena where EU Battery Regulation carbon footprint scoring and due diligence documentation erect barrier-to-entry moats favoring incumbent suppliers with certified supply chains.
For Market Incumbents: Extend carbon footprint traceability investments to capture CSRD disclosure advantages before qualification timelines lengthen for non-integrated competitors. Lock in five-year volume contracts with lithium salt cost escalators to defend margin position against feedstock volatility. Prioritize solvent recovery capital deployment in Belgium and the Netherlands where REACH Annex XVII enforcement tightens fastest. For New Entrants and Emerging Players: The premium-to-economy price-point gap in solid-state electrolyte pilot production creates white-space opportunity for specialized formulators with interface engineering capabilities. Target Poland's Battery Valley where LG Energy Solution and SK On cell capacity outpaces local electrolyte blending supply. Pursue qualification partnerships with Saft and Automotive Cells Company in Hauts-de-France where polymer-ceramic composite architectures seek alternative suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified chemical majors seeking REACH-compliant European assets with integrated solvent recycling operations. Long-term viability favors suppliers with backward control over lithium salt precursor supply and certified carbon footprint data infrastructure. Watch solid-state pilot line yield improvements as the inflection signal determining which chemistry platforms achieve scalable cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Precursor Production | Secures feedstock supply independent of Chinese processor concentration under evolving trade measures. |
| Closed-Loop Solvent Recovery System Deployment | Captures margin advantages over toll-blending competitors as REACH Annex XVII enforcement tightens. |
| CSRD-Compliant Carbon Footprint Certification | Creates first-mover qualification advantages under EU Battery Regulation disclosure timelines. |
| Solid-State Electrolyte Pilot Line Scale-Up | Positions suppliers for 400 Wh/kg energy density contracts as OEMs transition from liquid systems. |
| Polish Battery Valley Blending Capacity Addition | Addresses supply gap where cathode and anode investments outpace matched electrolyte production. |
Research Methodology
Document review covered EU regulatory filings, ECHA REACH registration databases, and customs trade data, complemented by interviews with electrolyte formulation directors, cell manufacturer procurement leads, and automotive OEM platform engineers. Primary fieldwork with BASF Corporation and Umicore technical R&D teams validated secondary findings on fluorinated solvent development trajectories. Bottom-up electrolyte demand modeling triangulated against top-down cell production forecasts across Germany, France, and Poland.
Segmented volume and value outputs emerged from disaggregation by electrolyte type, vehicle application, and end-user integration depth across the projection horizon. The analytical framework modeled liquid, solid-state, gel, and polymer electrolyte platforms separately, with CAGRs derived from cell gigafactory commissioning schedules and fleet electrification mandate compliance trajectories. Forecast inputs incorporated REACH regulatory phase-in timelines and F-Gas Regulation quota restrictions on perfluorinated additives.
Inputs from ECHA registration databases and KBA safety certification records were available through the study window; gaps in solid-state pilot line yield data introduce uncertainty bands around technology transition timing assumptions. Forecasts reflect documented assumptions regarding lithium salt supply stability and carbon footprint scoring implementation pace. Periodic stress-testing of base assumptions against regulatory enforcement variance and feedstock trade policy shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Traction Battery Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market