
 EV Battery Water Cold Plates Market | 2026-2036
EV Battery Water Cold Plates Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Water Cold Plates Market Insights
China's GB/T battery safety standards is expanding the minimum performance threshold for thermal runaway containment, forcing cold plate suppliers to certify channel geometries and burst pressures that earlier designs never required. Valeo leverages its European automotive heritage to sustain premium positioning in active cooling architectures for German OEM platforms. Modine Manufacturing Company anchors North American supply through its aluminum brazing expertise and proximity to Detroit-area EV assembly lines. Dana Limited differentiates via integrated thermal-fluid systems that combine cold plates with coolant routing hardware.
EV battery water cold plates are precision-machined or stamped heat exchangers, typically fabricated from 3003 or 6061 aluminum alloy with internal turbulator geometries that maintain cell-to-cell temperature variance below 5°C during fast-charging events. Their primary purpose is to extract joule heat from lithium-ion pouch or prismatic cells at rates exceeding 500 W per module, preventing thermal propagation cascades that trigger catastrophic failure. Aluminum product types dominate unit economics due to favorable conductivity-to-weight ratios and mature roll-bond manufacturing infrastructure, while hybrid cooling technology represents the fastest-growing segment as 800V architectures demand phase-change augmentation during peak discharge. Energy storage system applications remain nascent but carry margin premiums because utility-scale battery enclosures require redundant cooling loops that double cold plate counts per megawatt-hour.
EPA tailpipe regulations and the EU Green Deal's carbon border adjustments are reshaping how cold plate suppliers document embodied emissions in aluminum sourcing and brazing furnace energy intensity. China's MIIT enforces NEV credit mandates that indirectly tighten thermal management specifications as automakers extend battery warranties beyond eight years. NHTSA's pending battery safety rulemaking in the United States will likely reference UN ECE R100 test protocols that cold plate designs must survive without coolant loss. Stakeholders should monitor which regulatory jurisdiction moves first on mandating cell-level temperature telemetry, since that specification determines whether cold plates integrate fiber-optic sensors or remain passive hardware.
Market Dynamics
Cell-to-pack battery architectures are compressing module counts per vehicle, forcing cold plate suppliers to redesign channel geometries for direct cell contact rather than module-level heat exchange. This structural shift is concentrating procurement power with platform engineering teams at BYD, Tesla, and CATL.
Growth Catalysts
- China's MIIT NEV credit mandates:Automakers extend battery warranties beyond eight years, requiring thermal management systems that maintain performance degradation curves within warranty terms. Cold plate suppliers certify burst pressures and channel geometries to GB/T thermal runaway containment standards.
- 800V platform proliferation:Fast-charging architectures above 400kW generate joule heat exceeding 500W per module, demanding water-glycol flow rates that earlier 400V designs never required. Cell-to-pack integration eliminates module housings, exposing cold plates directly to cell surfaces.
- Jiangsu-Zhejiang manufacturing corridor concentration:Cell production clusters in Changzhou, Ningbo, and Suzhou co-locate with cold plate fabricators, compressing logistics costs and enabling just-in-time thermal management procurement for new EV platforms.
Market Restraints
- Aluminum alloy price volatility:3003 and 6061 aluminum sheet inputs fluctuate with LME pricing, compressing margins for roll-bond manufacturers who cannot pass through material cost swings under fixed platform supply agreements.
- Single-source brazing furnace dependency:Vacuum brazing capacity concentrates with German and Japanese equipment suppliers, creating bottlenecks when OEMs qualify new cold plate designs requiring specialized turbulator geometries.
- Refrigerant-based cooling residual preference:Some hybrid architectures retain R-1234yf loops for cabin integration, delaying pure water-glycol adoption where dual-circuit complexity adds packaging constraints.
Strategic Opportunities
- Energy storage system cooling:Utility-scale battery enclosures require redundant cooling loops that double cold plate counts per megawatt-hour, carrying margin premiums absent in automotive volume contracts.
- EU F-Gas Regulation phase-down:Refrigerant quota reductions accelerate water-based thermal management adoption for commercial vehicle platforms, opening retrofit and new-build channels for European cold plate suppliers.
- Fiber-optic sensor integration:Pending NHTSA battery safety rulemaking referencing UN ECE R100 protocols creates demand for cell-level temperature telemetry embedded within cold plate channels.
Industry Challenges
- Multi-physics simulation talent scarcity:Computational fluid dynamics expertise for conjugate heat transfer modeling concentrates with automotive OEM engineering centers, leaving tier suppliers dependent on outsourced analysis for channel optimization.
- Platform-specific qualification timelines:Each EV architecture requires 18-24 month validation cycles for burst pressure, corrosion resistance, and vibration durability, freezing design iterations mid-program.
- Cross-material galvanic corrosion:Aluminum cold plates interface with copper busbars and nickel-plated terminals in pack assemblies, requiring dielectric coatings that add process steps and thermal resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Water Cold Plates Market |
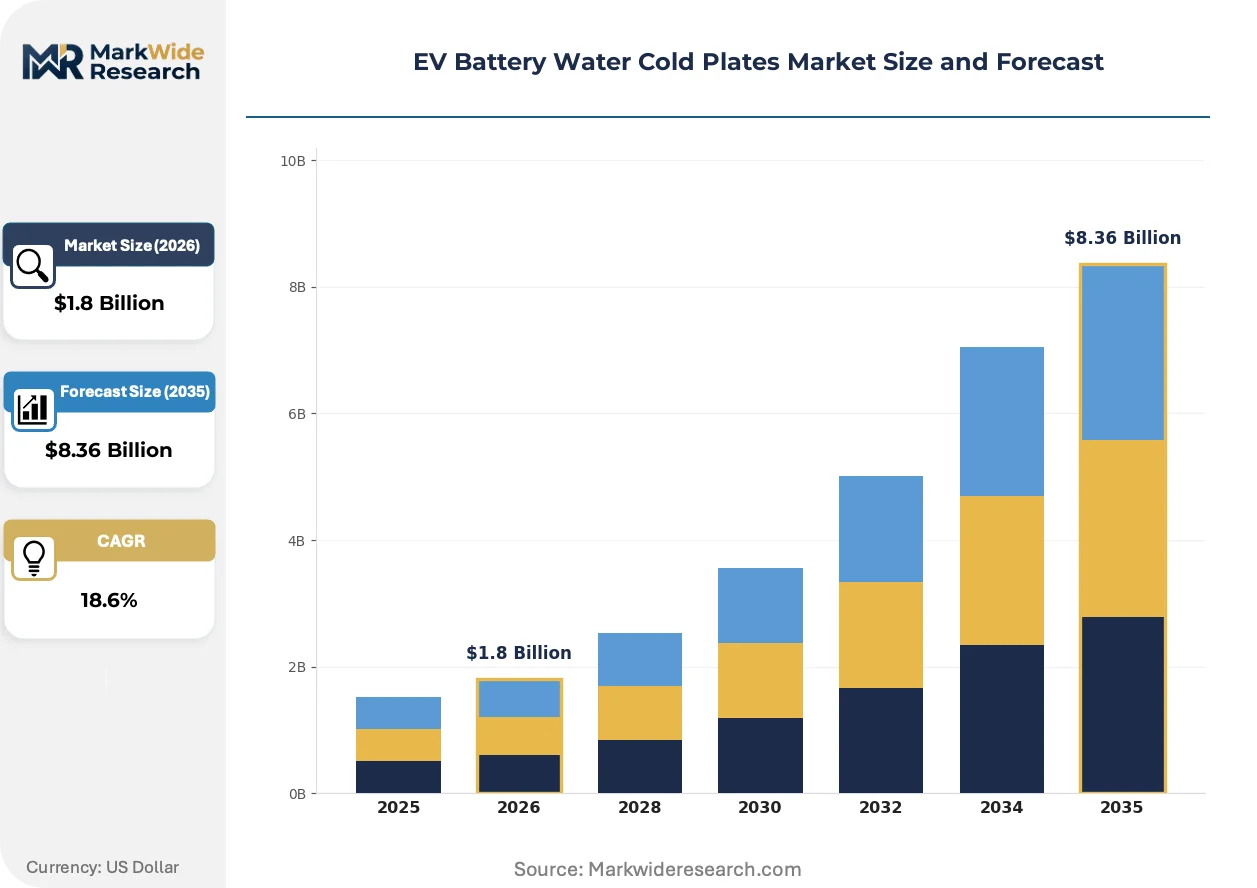
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Polycarbonate, Composite End User: Automakers, EV Manufacturers, Tier-1 Suppliers, Aftermarket Providers Technology: Passive Cooling, Active Cooling, Phase Change Material, Hybrid Systems Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Sanhua Group, Valeo, Modine Manufacturing Company, MAHLE GmbH, Boyd Corporation, Dana Limited, Nippon Light Metal, BorgWarner, Senior Flexonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Water Cold Plates Market Trends and Innovations
Water-glycol thermal management is displacing refrigerant-dependent architectures as voltage platforms rise and safety regulations tighten. Three concurrent developments are reshaping how cold plates are engineered, qualified, and procured.
Serpentine channel cold stamping with integrated turbulators is electrifying heat transfer coefficients for 800V fast-charging events. Korean and Chinese cell manufacturers specify these geometries for prismatic LFP packs. The technology is compressing cell-to-cell temperature variance below 3°C, enabling warranty terms that stamped-channel designs cannot match.
The EU F-Gas Regulation's phasedown schedule is accelerating water-based cooling adoption for commercial vehicle thermal management. Refrigerant quota restrictions force bus and truck OEMs to abandon R-134a and R-1234yf loops for battery conditioning. German commercial vehicle platforms are responding with dedicated water-glycol circuits that separate cabin HVAC from traction battery thermal control.
OEM engineering teams are consolidating thermal management procurement under platform directors rather than commodity buyers. Tier-one suppliers now negotiate system-level contracts encompassing cold plates, coolant routing hardware, and chiller integration. This concentration is most visible in China's NEV platform development, where CATL and BYD specify complete thermal-fluid systems rather than discrete heat exchanger components.
EV Battery Water Cold Plates Market Segmentation
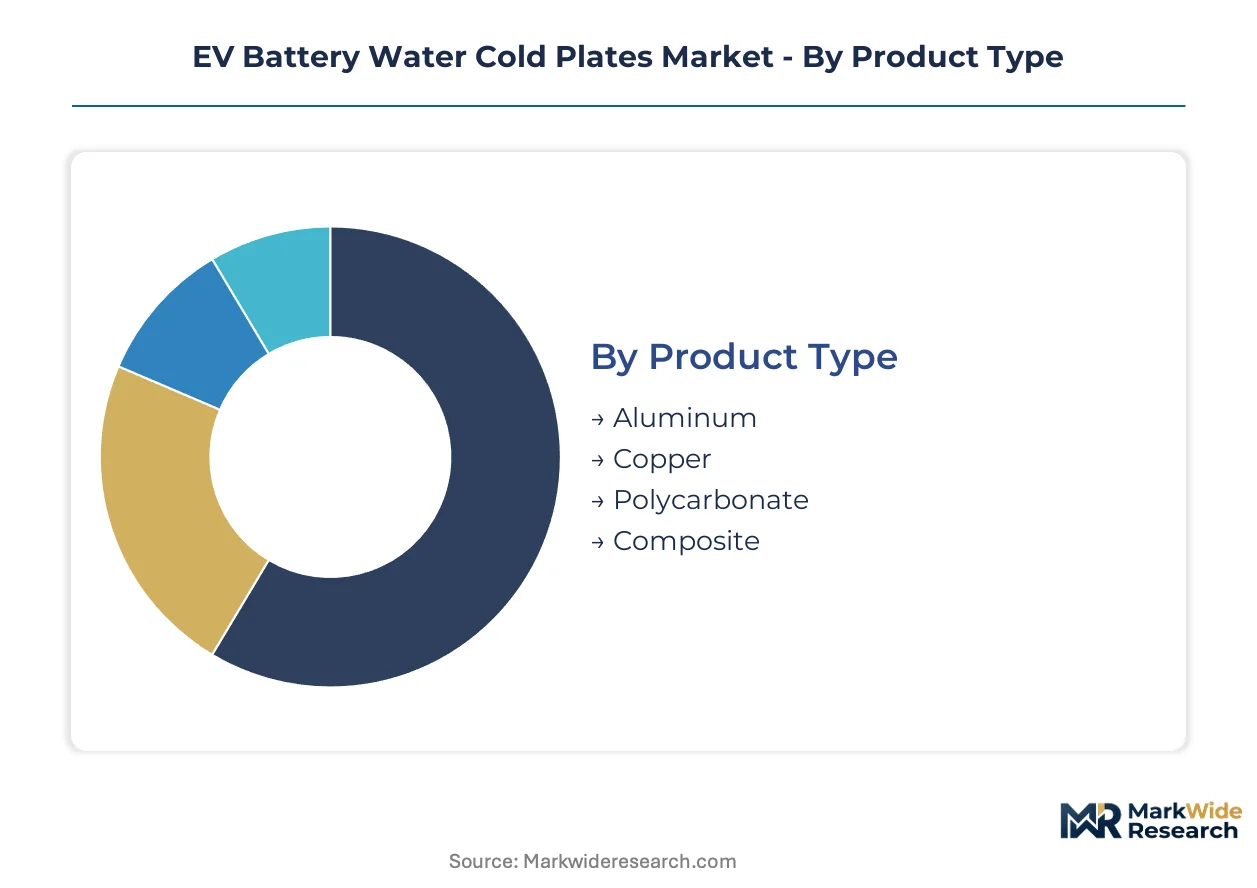
Cold plate procurement patterns diverge sharply across material grades, cooling architectures, and vehicle platforms. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier competitive position.
Product Type:
Supply concentrates with aluminum roll-bond fabricators in Changzhou and Ningbo, where 3003 and 6061 alloy sheet availability determines production scheduling.
- Aluminum:3003 and 6061 alloys dominate through favorable conductivity-to-weight ratios and mature vacuum brazing infrastructure. Changzhou and Ningbo metalworking clusters absorb the bulk of automotive procurement for cell-to-pack architectures.
- Copper:Superior thermal conductivity suits high-performance 800V platforms, yet weight penalties and material cost volatility constrain adoption to premium German and Korean OEM programs.
- Polycarbonate:Emerging in low-thermal-load auxiliary cooling loops where dielectric isolation from high-voltage busbars outweighs heat transfer efficiency.
- Composite:Carbon-fiber-reinforced polymer hybrids target motorsport and limited-production hypercar platforms seeking extreme weight reduction.
Aluminum absorbs the bulk of installed capacity; composite is expanding most quickly from a negligible base.
End User:
Procurement authority is migrating from commodity buyers to platform engineering directors who specify complete thermal-fluid systems rather than discrete components.
- Automakers:Tesla and BYD internal teams specify channel geometries directly, compressing tier-one supplier margins but capturing design control for warranty liability management.
- EV Manufacturers:Dedicated battery electric vehicle producers in China's Jiangsu corridor negotiate system-level contracts encompassing cold plates, coolant routing, and chiller integration.
- Tier-1 Suppliers:Valeo and Dana leverage thermal management heritage to bundle cold plates with coolant distribution hardware, defending margin through integration depth.
- Aftermarket Providers:Retrofit demand concentrates in EU commercial vehicle channels where F-Gas Regulation phase-down forces refrigerant-to-water conversions on existing bus fleets.
Tier-1 suppliers capture the highest contract values per platform; EV manufacturers are climbing the fastest as NEV credit mandates extend procurement timelines.
Technology:
Cost tiers separate passive hardware from sensor-embedded active architectures that command qualification premiums.
- Passive Cooling:Serpentine stamped channels with integrated turbulators serve prismatic LFP packs in Chinese passenger platforms, compressing cell-to-cell variance below 3°C during fast-charging events.
- Active Cooling:Pump-driven water-glycol loops with variable flow control dominate 800V architectures above 400kW, where joule heat extraction rates exceed 500W per module.
- Phase Change Material:Paraffin or salt hydrate integration provides thermal buffering during transient peak loads, adding cost and packaging complexity that limits adoption to luxury segments.
- Hybrid Systems:Water-glycol primary loops with PCM augmentation represent the steepest expansion trajectory as 800V platforms demand phase-change capacity during sustained discharge.
Passive cooling retains volume leadership; hybrid systems are gaining share fastest as voltage platforms rise.
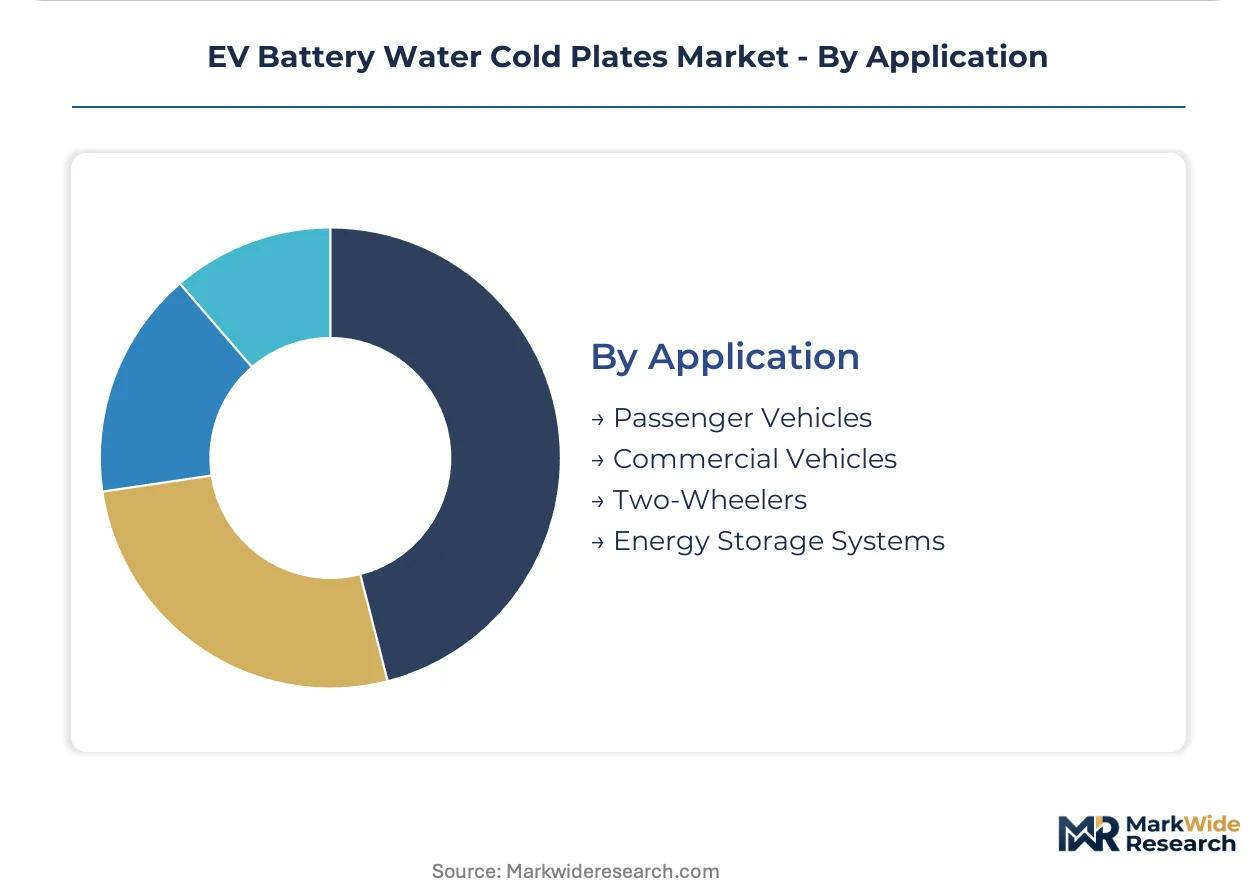
Application:
Margin profiles invert between automotive volume contracts and utility-scale energy storage redundancy requirements.
- Passenger Vehicles:Cell-to-pack architectures from CATL and BYD eliminate module housings, exposing cold plates directly to cell surfaces and demanding redesigned channel geometries.
- Commercial Vehicles:EU bus and truck OEMs respond to F-Gas quota restrictions with dedicated water-glycol circuits that separate cabin HVAC from battery thermal control.
- Two-Wheelers:Compact cold plate formats for electric scooters and motorcycles concentrate in India's Tamil Nadu and Karnataka manufacturing corridors.
- Energy Storage Systems:Utility-scale enclosures require redundant cooling loops that double cold plate counts per megawatt-hour, carrying margin premiums absent in automotive contracts.
Passenger vehicles anchor procurement volumes; energy storage systems are expanding most quickly on grid-scale deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang manufacturing corridors concentrate the bulk of cold plate procurement, with automakers in Changzhou, Ningbo, and Suzhou co-locating thermal management fabrication alongside cell production facilities.
China
MIIT NEV credit mandates force automakers to extend battery warranties beyond eight years, tightening thermal management specifications. GB/T battery safety standards mandate certified channel geometries and burst pressures for thermal runaway containment. Changzhou and Ningbo metalworking clusters absorb automotive procurement for cell-to-pack architectures from CATL and BYD platforms.
Germany
Commercial vehicle OEMs respond to EU F-Gas Regulation refrigerant quota restrictions by abandoning R-134a loops for battery conditioning. KBA type-approval processes reference UN ECE R100 test protocols that cold plate designs must survive without coolant loss. Bavaria and Baden-Württemberg engineering centers specify complete thermal-fluid systems for premium German OEM platforms.
United States
NHTSA pending battery safety rulemaking will likely mandate cell-level temperature telemetry, determining whether cold plates integrate fiber-optic sensors. EPA tailpipe regulations reshape how suppliers document embodied emissions in aluminum sourcing. Detroit-area EV assembly lines anchor North American demand through proximity to aluminum brazing expertise.
South Korea
Prismatic LFP pack manufacturers specify serpentine channel geometries with integrated turbulators for 800V fast-charging architectures. MFDS automotive safety alignment with international protocols influences thermal management qualification timelines. Busan-Ulsan manufacturing corridors concentrate fabrication capacity for export-oriented Korean OEM programs.
Japan
METI industrial policy supports domestic thermal management component production for hybrid and battery electric platforms. JIS standards govern aluminum alloy specifications for automotive heat exchangers. Nagoya-area automotive suppliers maintain vacuum brazing capacity for specialized turbulator geometries in premium vehicle segments.
EV Battery Water Cold Plates Market Competitive Landscape
Chinese producers anchor volume manufacturing through Changzhou and Ningbo metalworking clusters; European specialists hold premium positioning through system-level integration contracts. The vendor base splits between roll-bond fabricators serving cell-to-pack architectures and diversified thermal management suppliers bundling cold plates with coolant distribution hardware. Three archetypes dominate: aluminum brazing specialists, integrated thermal-fluid system providers, and diversified automotive component conglomerates. Competitive moves concentrate on geographic co-location with cell manufacturing corridors and qualification for 800V platform architectures.
Among diversified automotive suppliers, Valeo and MAHLE GmbH occupy positions emphasizing European automotive heritage and system-level contract scope. Dana Limited exemplifies the integrated thermal-fluid archetype, combining cold plate fabrication with coolant routing hardware to defend margin through bundling depth. Sanhua Group represents the China-based volume fabrication tier, anchoring supply relationships with domestic NEV platform engineering teams.
| Leading Market Players |
|---|
| Sanhua Group |
| Valeo |
| Modine Manufacturing Company |
| MAHLE GmbH |
| Boyd Corporation |
| Dana Limited |
| Nippon Light Metal |
| BorgWarner |
| Senior Flexonics |
| Others |
Pricing and Supply Chain Analysis
Platform engineering teams at CATL and BYD concentrate procurement authority for cell-to-pack architectures, compressing tier-one supplier margins and forcing contract structures that index aluminum input costs to LME benchmarks rather than fixed pricing.
Pricing Analysis
Short lead-time premiums separate qualified suppliers from spot-market fabricators in Changzhou and Ningbo. Pricing stratifies across GB/T-certified premium tiers, standard automotive-grade channels, and economy-level aftermarket conversions. Cost compression in the standard tier intensifies as roll-bond manufacturers absorb LME aluminum volatility under fixed platform agreements. Aftermarket providers serving EU commercial vehicle retrofit channels exhibit the highest price sensitivity, while German OEM system-level contracts show the least.
Supply Chain Analysis
Reverse-logistics flows for vacuum brazing furnace refurbishment and turbulator geometry requalification create secondary supply channels for legacy cold plate designs. Primary fabrication draws from China, South Korea, and Germany for aluminum sheet inputs, vacuum brazing equipment, and precision stamping dies. The supply chain rests on single-source dependencies for German and Japanese vacuum furnace technology. Distribution runs through just-in-time corridors co-located with Jiangsu-Zhejiang cell manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-direct procurement models, with aluminum price volatility and 18-24 month qualification timelines forcing sub-scale fabricators toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into aluminum rolling capacity in Changzhou or Ningbo, eliminating margin exposure to LME price swings. Secure exclusive vacuum brazing furnace partnerships with German equipment suppliers to block competitor qualification for 800V turbulator geometries. Certify channel designs to pending NHTSA battery safety rulemaking before tier-two suppliers complete UN ECE R100 testing.
For New Entrants and Emerging Players: Begin with energy storage system cooling loops, where redundant architecture requirements and utility-scale margin premiums offset lower automotive volumes. Target North American ESS deployment corridors where domestic content incentives favor non-Chinese fabrication. Pursue joint-development contracts with inverter manufacturers seeking bundled thermal-fluid system suppliers.
For Investors and Strategic Acquirers: The window for entry favors aluminum brazing specialists with existing OEM qualification relationships and idle vacuum furnace capacity. Acquisition targets should demonstrate GB/T or UN ECE R100 certification progress rather than raw fabrication scale. Monitor NHTSA final rule publication timing as the inflection signal for sensor-embedded cold plate valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Engineering Direct Contracting | Bypasses tier-one supplier margins and captures warranty liability control for BYD and CATL. |
| Aluminum Rolling Backward Integration | Secures 3003 and 6061 alloy supply at LME-indexed cost for Changzhou fabricators. |
| GB/T Certification Pre-Qualification | Locks in thermal runaway containment compliance before MIIT mandate enforcement tightens. |
| Energy Storage System Redundancy Design | Doubles cold plate counts per megawatt-hour for utility-scale battery enclosures. |
| Fiber-Optic Sensor Channel Integration | Positions for NHTSA cell-level telemetry mandates referencing UN ECE R100 protocols. |
Research Methodology
Multi-period observation of aluminum alloy pricing volatility, OEM platform launch cadence, and thermal management procurement patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement directors, vacuum brazing equipment specialists, and ESS project developers. Secondary validation drew from MIIT NEV credit filings, UN ECE R100 test protocol documentation, EU F-Gas Regulation quota schedules, and aluminum trade flow data. Bottom-up fabrication capacity estimates and top-down OEM thermal management spend projections were triangulated to constrain forecast variance.
The input-output matrix mapped cold plate unit economics against vehicle production volumes, cell-to-pack adoption curves, and 800V platform proliferation rates across the projection horizon. Segmentation dimensions modeled included material grade tier, cooling architecture type, vehicle platform class, and regional regulatory cluster. CAGRs were derived from slope-consistent growth rate analysis rather than endpoint anchoring. Forecast inputs incorporated MIIT credit mandate enforcement timelines and F-Gas Regulation phase-down schedules.
Underlying measurement precision varies by segment; automotive volume contracts carry tighter precision than nascent energy storage system deployments. Forecasts reflect assumptions regarding aluminum price stability, vacuum brazing capacity expansion, and regulatory rulemaking finalization. Practitioners should monitor NHTSA rulemaking publication, EU F-Gas quota allocation decisions, and MIIT NEV credit adjustment announcements for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Traction Battery Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Germany EV Battery Pack Market