
 Automotive Rechargeable Battery Market | 2026-2036
Automotive Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rechargeable Battery Market Insights
China's megafactory corridor is reconfiguring supply geography for automotive cells. Contemporary Amperex Technology Co Ltd leverages integrated cathode-to-pack production across Xiamen and Ningde facilities. LG Energy Solution Ltd anchors its North American position through joint ventures with Detroit Three automakers. BYD Company Ltd controls its entire battery supply chain through in-house lithium iron phosphate cell production.
An automotive rechargeable battery is an electrochemical energy storage device designed for repeated charge-discharge cycling, typically employing lithium-ion cells with nickel-cobalt-manganese or lithium iron phosphate cathodes and graphite or silicon-blend anodes, engineered to deliver sustained power density for vehicle propulsion. Lithium-ion chemistry dominates product type segmentation due to its superior gravimetric energy density and declining cell cost curves. Fast charging technology represents the fastest-growing segment as 800-volt architectures proliferate across premium electric vehicle platforms. Fleet operators command disproportionate margin pools among end users through long-term volume contracts and predictable utilization profiles.
The US EPA tailpipe standards and NHTSA CAFE rules mandate escalating electrification shares, forcing OEMs to secure multi-year cell offtake agreements. China's MIIT dual credit system and GB standards for battery safety create compliance thresholds that filter smaller pack assemblers from national supply chains. Europe's ECHA REACH restrictions on cobalt sourcing and the EU Battery Regulation's recycled content mandates are reshaping material procurement. Stakeholders must monitor cathode chemistry patent thickets and solid-state electrolyte manufacturing yields as the next competitive frontier.
Market Dynamics
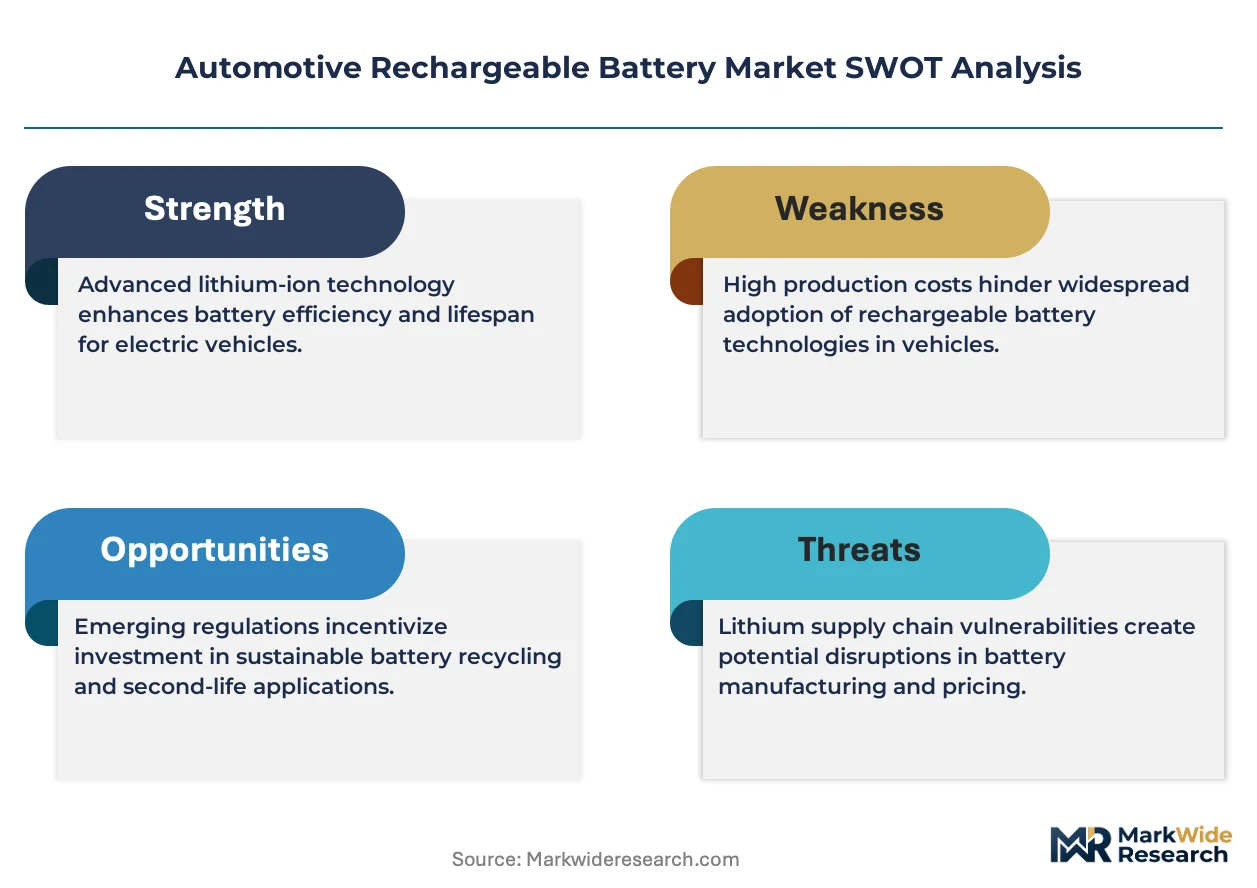
Lithium-ion cell cost curves are collapsing faster than incumbent pack architectures can absorb, forcing OEMs to renegotiate offtake terms mid-contract and triggering wholesale restructuring of cathode supply commitments.
Growth Catalysts
- China's NEV mandate:The MIIT dual credit system enforces escalating electrification quotas that lock domestic OEMs into multi-year battery procurement programs.
- Fleet electrification:Commercial vehicle operators in logistics and urban transit are consolidating demand through centralized procurement hubs that guarantee cell volume.
- Silicon-anode blending:Advanced anode formulations are extending energy density thresholds without requiring wholesale cathode chemistry changes.
Market Restraints
- Cobalt price volatility:DRC supply concentration exposes cathode producers to disruptive input cost swings that compress margin predictability.
- Graphite purification bottleneck:Battery-grade spherical graphite processing capacity concentrates in China's Shandong and Heilongjiang provinces.
- Cell dry-room capex intensity:Gigafactory construction requires humidity-controlled cleanroom investments that extend payback periods.
Strategic Opportunities
- Solid-state electrolyte convergence:Sulfide and oxide solid-state pathways are converging with silicon-anode architectures to enable next-generation pack designs.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting cathode precursor investments.
- Second-life stationary storage:Retired EV packs are repurposing into grid-scale storage through refurbished battery aggregation platforms.
Industry Challenges
- Electrolyte formulation IP thickets:Patent disputes over lithium hexafluorophosphate additives are complicating licensing negotiations.
- Pack thermal runaway certification:UN ECE R100 and GB 38031 testing timelines are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rechargeable Battery Market |
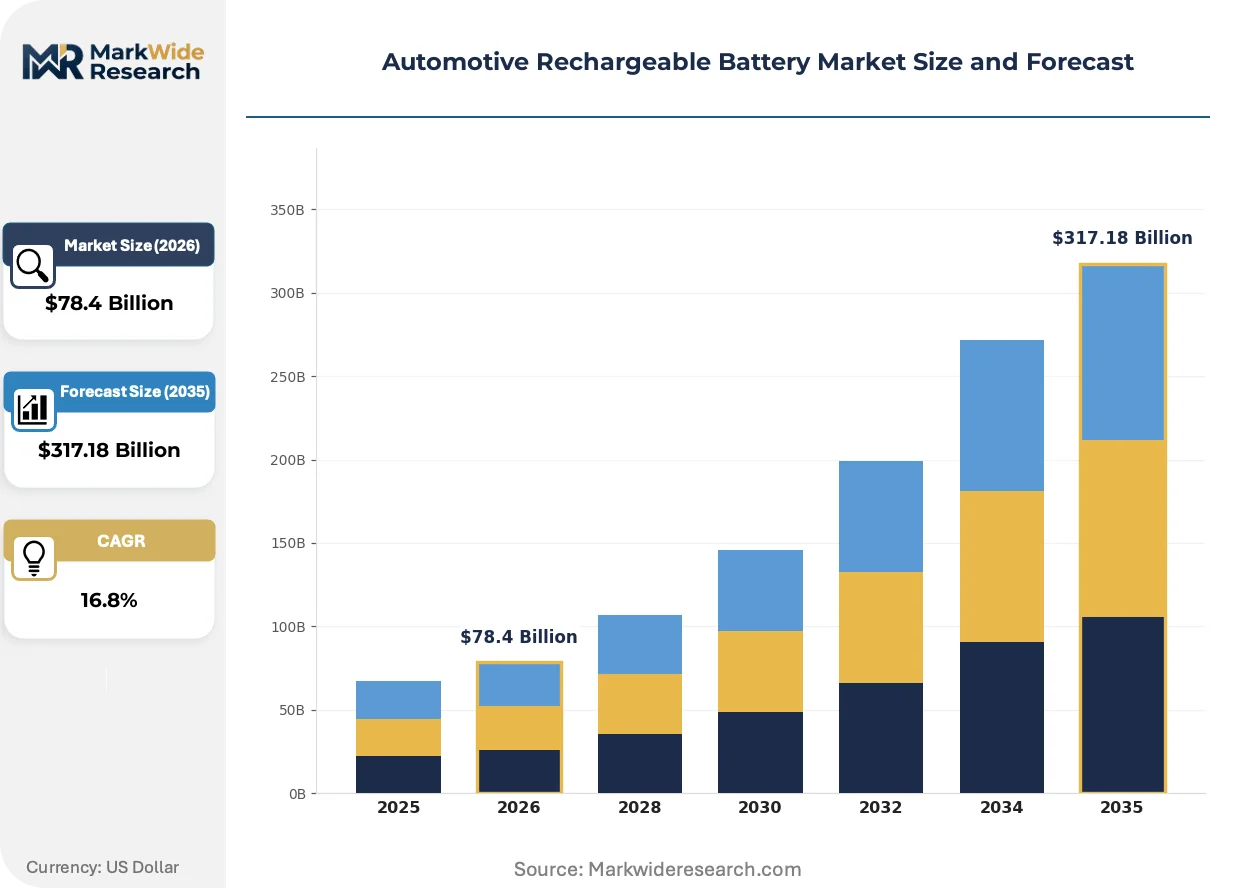
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $317.18 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Application: Electric Vehicles, Hybrid Vehicles, Plug-in Hybrids, Energy Storage Systems End User: OEMs, Aftermarket, Fleet Operators, Individual Buyers Technology: Battery Management Systems, Fast Charging, Wireless Charging, Regenerative Braking |
| Companies Covered | Contemporary Amperex Technology Co Ltd, BYD Company Ltd, LG Energy Solution Ltd, Panasonic Holdings Corp, Samsung SDI Co., Ltd, Tesla Inc, EnerSys, Johnson Controls International PLC, GS Yuasa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rechargeable Battery Market Trends and Innovations
Cell-to-pack architectures are eliminating module housings entirely, compressing bill-of-materials costs and enabling OEMs to reclaim vehicle floor space for extended range configurations.
800-volt electrical architectures are collapsing charging time thresholds for premium electric vehicle platforms. Porsche and Hyundai Motor Group have deployed these systems across performance SUV and sedan lineups. The structural consequence is collapsing the competitive relevance of 400-volt systems in segments above mass-market price points.
Europe's EU Battery Regulation mandates recycled content minimums and carbon footprint disclosures at the cell level. The industrial consequence is forcing cathode producers to secure certified recycled nickel and cobalt streams. Premium OEMs are responding fastest, embedding compliance into supplier scorecards ahead of enforcement deadlines.
Fleet operators are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle acquisition. Logistics operators in Germany and the Netherlands are piloting these models through third-party pack providers. This shift is most visible in heavy-duty commercial segments where utilization rates justify service-based economics.
Automotive Rechargeable Battery Market Segmentation
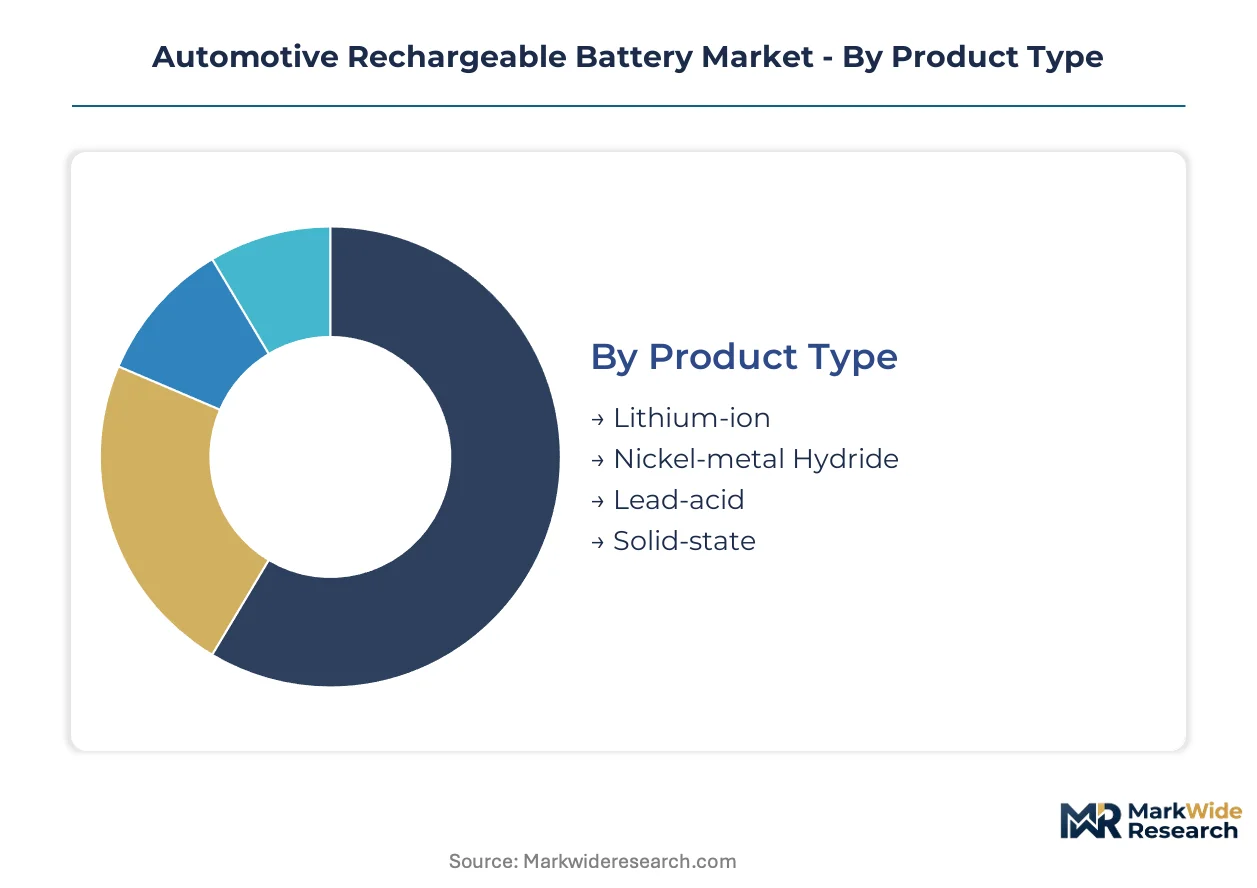
Automotive rechargeable battery segmentation reveals how chemistry choices, vehicle architectures, and procurement models fragment addressable demand. Each dimension carries distinct margin profiles and capital intensity requirements that shape supplier positioning.
Product Type:
Cost tier differentiation separates mass-market deployability from next-generation performance premiums across cathode-anode combinations.
- Lithium-ion:Nickel-cobalt-manganese and lithium iron phosphate cathodes paired with graphite or silicon-blend anodes deliver gravimetric energy density above 250 Wh/kg. Demand concentrates in China's Jiangsu and Fujian provinces where CATL and BYD operate integrated cathode-to-pack facilities, driven by MIIT dual credit compliance thresholds that filter out lower-density alternatives.
- Solid-state:Sulfide and oxide electrolyte architectures eliminate liquid organic solvents, enabling lithium-metal anodes with theoretical energy density exceeding 400 Wh/kg. Toyota Motor Corporation and Samsung SDI are piloting production lines in Japan and South Korea, constrained by dry-room manufacturing yields and ceramic electrolyte sintering bottlenecks.
- Nickel-metal Hydride:Rare-earth hydride anodes with nickel oxyhydroxide cathodes persist in hybrid electric vehicle applications requiring shallow discharge cycles. Toyota Prius production in Japan and Kentucky maintains residual demand.
- Lead-acid:Flooded and absorbed glass mat designs serve auxiliary power and starter functions in internal combustion architectures. Johnson Controls and Clarios supply aftermarket replacement channels across North America and Europe.
Lithium-ion holds installed capacity. Solid-state is rotating up the share rankings.
Application:
Vehicle electrification depth determines pack size, thermal management complexity, and cycle life specifications.
- Electric Vehicles:Pure battery-electric platforms require 60-100 kWh packs with 800-volt architectures enabling 350 kW fast charging. Demand clusters in premium SUV and sedan segments from Porsche, Hyundai, and Tesla, where extended range configurations justify cell cost premiums.
- Plug-in Hybrids:Dual-powertrain architectures deploy 15-25 kWh packs supporting 50-80 km electric-only range. European OEMs including BMW and Volvo Cars are expanding PHEV lineups to meet EU fleet CO2 standards ahead of full electrification transitions.
- Hybrid Vehicles:Smaller 1-2 kWh packs buffer internal combustion output through regenerative braking. Toyota and Honda production in Japan, Kentucky, and Indiana sustains this segment.
- Energy Storage Systems:Second-life repurposing of retired EV packs into stationary grid storage aggregates degraded cells through refurbished battery platforms. German and Dutch utilities are piloting aggregation models with logistics fleet operators.
Electric Vehicles command revenue concentration. Plug-in Hybrids are climbing the fastest as compliance bridges.
End User:
Procurement scale and contract duration separate volume-guaranteed offtake from spot-market transactions.
- Fleet Operators:Logistics and urban transit operators consolidate demand through centralized procurement hubs and battery-as-a-service contracts. DHL and DB Schenker in Germany unbundle cell ownership from vehicle acquisition, generating predictable utilization profiles.
- OEMs:Vehicle manufacturers secure multi-year cell offtake agreements with tier-one suppliers. Detroit Three automakers joint venture with LG Energy Solution for North American supply security.
- Aftermarket:Independent service channels replace degraded packs in out-of-warranty vehicles. Regional distributors in the US and Europe manage reverse logistics and refurbishment.
- Individual Buyers:Retail consumers acquire replacement batteries through dealer networks or third-party installers. Price sensitivity dominates this channel.
Fleet Operators concentrate margin pools. OEMs are rotating up the share rankings through captive sourcing.
Technology:
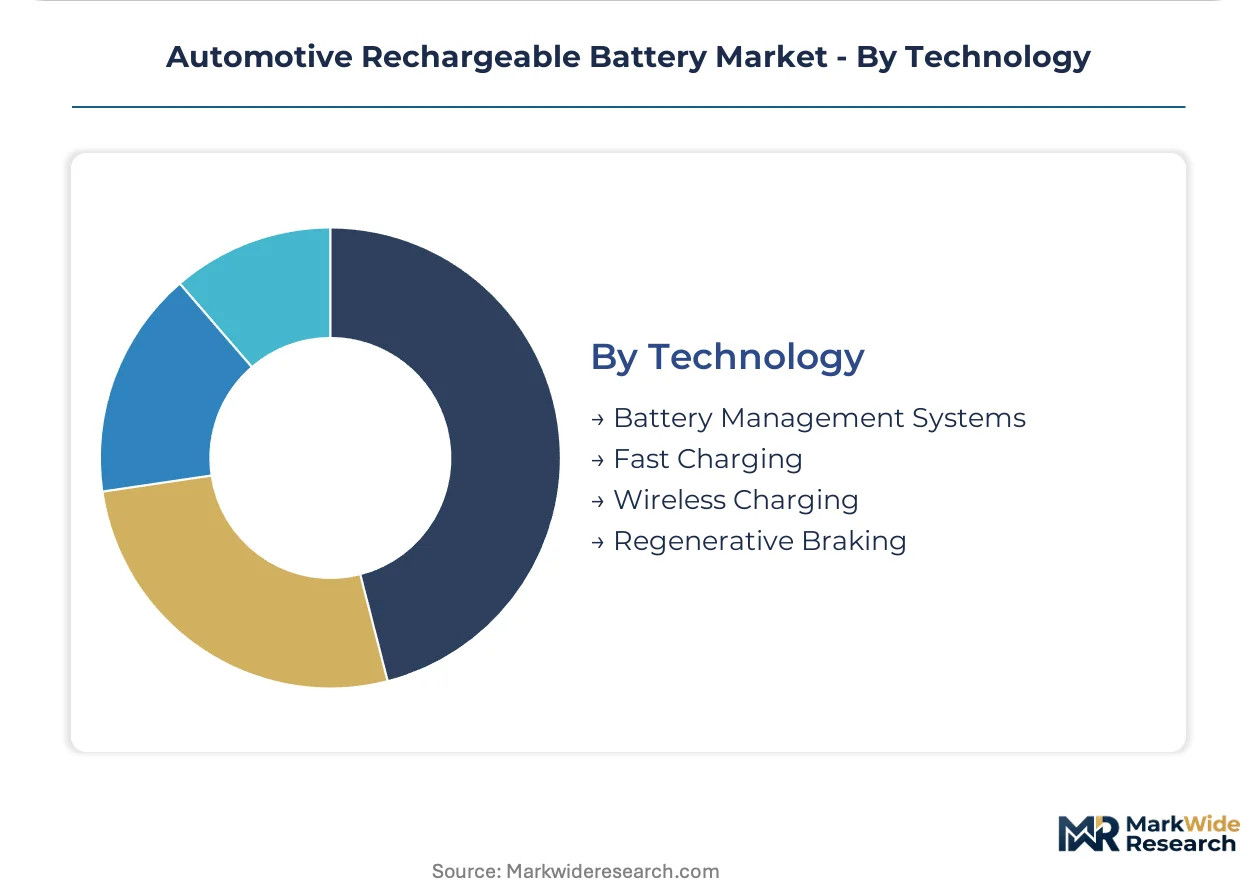
System-level integration capabilities differentiate pack performance beyond cell chemistry alone.
- Fast Charging:800-volt architectures and silicon-carbide inverters enable 10-80% state-of-charge in under 20 minutes. Hyundai Motor Group and Porsche deploy these systems across performance platforms.
- Battery Management Systems:Cell-level voltage and temperature monitoring with predictive state-of-health algorithms extends cycle life. NXP Semiconductors and Infineon Technologies supply ASIL-D compliant integrated circuits.
- Wireless Charging:Inductive power transfer eliminates connector wear in fleet depot applications. WiTricity licenses technology to commercial vehicle operators in California and Norway.
- Regenerative Braking:Kinetic energy recovery during deceleration reduces net energy consumption. All electrified platforms incorporate this function.
Fast Charging holds installed capacity. Battery Management Systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual credit enforcement anchors China's dominance in automotive cell procurement. OEM procurement programs across four additional geographies are reconfiguring supply geography through localized compliance mandates and industrial clustering.
China
Jiangsu and Fujian provinces concentrate cathode-to-pack integration as CATL and BYD scale integrated facilities. GB standards for battery safety and MIIT dual credit quotas filter smaller pack assemblers from national supply chains. Xiamen and Ningde anchor the megafactory corridor with captive precursor processing.
Germany
Premium OEM electrification roadmaps drive 800-volt architecture adoption across Porsche and BMW lineups. ECHA REACH cobalt sourcing restrictions and EU Battery Regulation recycled content mandates reshape cathode procurement. Stuttgart and Munich clusters host pilot solid-state production partnerships with Korean cell suppliers.
United States
Detroit Three automakers secure supply security through joint ventures with Korean tier-one suppliers. EPA tailpipe standards and NHTSA CAFE rules mandate escalating electrification shares forcing multi-year offtake agreements. Michigan and Ohio anchor Midwest cell assembly with Georgia and Tennessee emerging as southern production nodes.
South Korea
Samsung SDI and LG Energy Solution anchor export-oriented production for North American and European OEM contracts. MFDS battery safety certifications and METI-aligned technical standards facilitate cross-border supply integration. Gyeonggi-do and Chungcheongnam-do provinces concentrate dry-room manufacturing capacity with government-backed R&D consortia.
Japan
Toyota Motor Corporation sustains nickel-metal hydride demand for hybrid platforms while piloting sulfide solid-state lines. METI battery technology roadmaps and JIS standards create compliance thresholds for domestic OEM procurement. Aichi and Osaka prefectures maintain hybrid cell production with Kyushu hosting next-generation electrolyte research facilities.
Automotive Rechargeable Battery Market Competitive Landscape
Integrated cathode-to-pack specialists and modular cell suppliers split the market between captive supply security and flexible procurement economics. Three strategic archetypes dominate: vertically integrated conglomerates controlling upstream material refining, joint-venture platforms bridging OEM equity with supplier technology, and pure-play cell manufacturers scaling through standardized platform architectures. Competitive moves concentrate on capacity expansion through government-backed incentive zones and strategic partnerships securing precursor chemical streams.
Within the integrated conglomerate tier, Contemporary Amperex Technology Co Ltd exemplifies upstream control over cathode precursor and cell assembly. BYD Company Ltd occupies a position spanning vehicle manufacturing and in-house lithium iron phosphate production. LG Energy Solution Ltd anchors the joint-venture archetype through North American production partnerships with Detroit-based OEMs.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co Ltd |
| BYD Company Ltd |
| LG Energy Solution Ltd |
| Panasonic Holdings Corp |
| Samsung SDI Co., Ltd |
| Tesla Inc |
| EnerSys |
| Johnson Controls International PLC |
| GS Yuasa Corporation |
| Others |
Pricing and Supply Chain Analysis
Cobalt price volatility from Democratic Republic of Congo supply concentration compresses margin predictability across cathode tiers while simultaneously forcing OEMs to restructure offtake terms and diversify precursor sourcing geography. This input-cost instability widens spreads between nickel-cobalt-manganese premium formulations and lithium iron phosphate economy alternatives while reshaping where cell producers locate cathode refining capacity.
Pricing Analysis
Chinese Jiangsu and Fujian production clusters command pricing premiums over European and North American assembly nodes due to integrated cathode-to-pack economics and MIIT dual credit compliance thresholds. Pricing stratifies across premium silicon-anode configurations, standard nickel-cobalt-manganese mid-tier offerings, and economy lithium iron phosphate cells driven by certification grade and volume scale. Cost compression in standard-tier cells is intensifying because OEMs renegotiate mid-contract offtake terms as lithium carbonate spot markets soften. Fleet operators exhibit lowest price sensitivity through battery-as-a-service contracts while individual aftermarket buyers drive spot-market discounting.
Supply Chain Analysis
Spodumene concentrate from Australia, Chilean lithium brine, and Indonesian nickel laterite feed cathode precursor production across China, South Korea, and Japan. Battery-grade spherical graphite processing draws from China's Shandong and Heilongjiang provinces while synthetic anode capacity expands in Japan. Single-source vulnerability concentrates in DRC cobalt hydroxide shipments through Durban port logistics chokepoints. Distribution runs through tier-one cell suppliers joint-venturing with OEMs rather than open-market spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation through battery-as-a-service contracts shifts procurement leverage toward volume-guaranteed buyers and away from fragmented retail channels. This buyer-power concentration rewards suppliers securing long-term offtake agreements with logistics and transit operators.
For Market Incumbents: Insulate cathode supply security through backward integration into Australian and Chilean lithium feedstock offtake while expanding dry-room manufacturing capacity in Georgia and Tennessee to meet Detroit Three localization requirements. Solid-state electrolyte patent thickets from Toyota and Samsung SDI threaten chemistry-agnostic cell assemblers with licensing exclusion. Priority investment in silicon-anode blending capabilities preserves energy density leadership without full solid-state transition costs. For New Entrants and Emerging Players: India's PLI scheme production-linked incentives for advanced chemistry cell manufacturing represent the most penetrable entry point for cathode precursor specialists lacking established OEM relationships. Second-life stationary storage aggregation platforms in Germany and the Netherlands offer asset-light service models bypassing capital-intensive gigafactory construction. Go-to-market positioning through refurbished pack refurbishment partnerships with logistics fleet operators bypasses direct OEM qualification barriers. For Investors and Strategic Acquirers: EU Battery Regulation recycled content mandates and carbon footprint disclosure requirements reshape the acquisition landscape toward cathode producers with certified recycled nickel and cobalt stream access. Five-to-ten year viability favors integrated specialists controlling upstream refining rather than modular pack assemblers exposed to chemistry commoditization. Target acquisition archetype: mid-cap cathode precursor producers with European recycling partnerships. Signal to monitor: solid-state electrolyte manufacturing yield breakthroughs at Toyota and Samsung SDI pilot lines.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Cell Manufacturing | Detroit Three partnerships with LG Energy Solution anchor North American supply security against IRA localization requirements. |
| Silicon-Anode Capacity Expansion | Advanced anode formulations extend energy density thresholds without wholesale cathode chemistry transitions at premium OEMs. |
| Battery-as-a-Service Platform Launch | DHL and DB Schenker unbundle cell ownership from vehicle acquisition through third-party pack provider contracts. |
| Recycled Content Certification Program | ECHA REACH compliance and EU Battery Regulation mandates force cathode producers to secure certified secondary nickel streams. |
| 800-Volt Architecture Deployment | Hyundai Motor Group and Porsche collapse charging time thresholds and displace 400-volt relevance in premium segments. |
Research Methodology
The analysis maps lithium-ion cell chemistry tiers, solid-state pilot production lines, second-life stationary storage aggregation, and battery-as-a-service contract structures, each validated through OEM platform engineers, tier-one supplier procurement leads, fleet operator logistics directors, and aftermarket distributor operations. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, MIIT production license databases, EU Battery Regulation implementation guidance, and IHS Markit vehicle registration data. Bottom-up cell capacity buildouts triangulated against top-down OEM electrification roadmap commitments.
Assumptions held fixed include MIIT dual credit enforcement stringency, EPA tailpipe standard trajectory, and ECHA REACH cobalt sourcing restriction implementation, while lithium carbonate spot price pathways and solid-state manufacturing yield curves were stress-tested across sensitivity bands. Segmentation modeling spanned product type chemistry, vehicle electrification architecture, end-user procurement scale, and fast-charging technology integration across the projection horizon. CAGRs derived from installed capacity expansion schedules against OEM platform launch timelines, with silicon-anode adoption curves and 800-volt architecture penetration as chemistry-specific forecast inputs.
Stress conditions across DRC supply disruption duration, Chinese export license restrictions, and European carbon border adjustment phase-in were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to solid-state electrolyte sintering yield breakthroughs or cobalt hydroxide logistics chokepoint resolution. Cross-checking against IEA critical minerals supply projections and OEM announced cell offtake volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
EV Battery Heating System Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
France EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
European EV Battery Systems Market