
 Traction Battery Market | 2026-2036
Traction Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Battery Market Analysis
Project finance tied to battery-as-a-service leasing is tilting competitive dynamics toward capital-heavy incumbents. CATL leverages its vertical integration into cathode precursors to lock in long-term supply contracts. Panasonic Corporation anchors its position through dedicated production lines serving premium EV platforms. LG Chem differentiates via high-nickel chemistry R&D intensity across multiple OEM programs.
A traction battery is an electrochemical storage system engineered for propulsion duty, typically delivering continuous discharge rates above 1C and cycle life exceeding 1,000 deep cycles under variable thermal loads. Its primary purpose is to convert stored chemical energy into electrical power for motive applications ranging from passenger EVs to forklift fleets. Lithium-ion chemistry leads across all end-user categories due to unmatched gravimetric energy density, while sodium-ion variants are gaining structural relevance in material handling and stationary installations where weight tolerance permits cost-driven substitution. The above 200 Ah capacity tier commands the deepest margin pools as rail transport and heavy marine applications consolidate procurement around single large-format packs.
The EU's F-Gas Regulation and CE marking requirements under the EU Green Deal are mandating lower-carbon cell production pathways, directly shaping factory siting decisions and supplier qualification criteria. China's MIIT enforces GB standards for traction battery safety and recycling traceability, creating compliance barriers for non-domestic entrants. India's BIS certification and PLI scheme for advanced chemistry cell manufacturing are redirecting investment toward localized gigafactory development. Stakeholders must monitor how evolving carbon border adjustment mechanisms redefine cost competitiveness between regional supply bases.
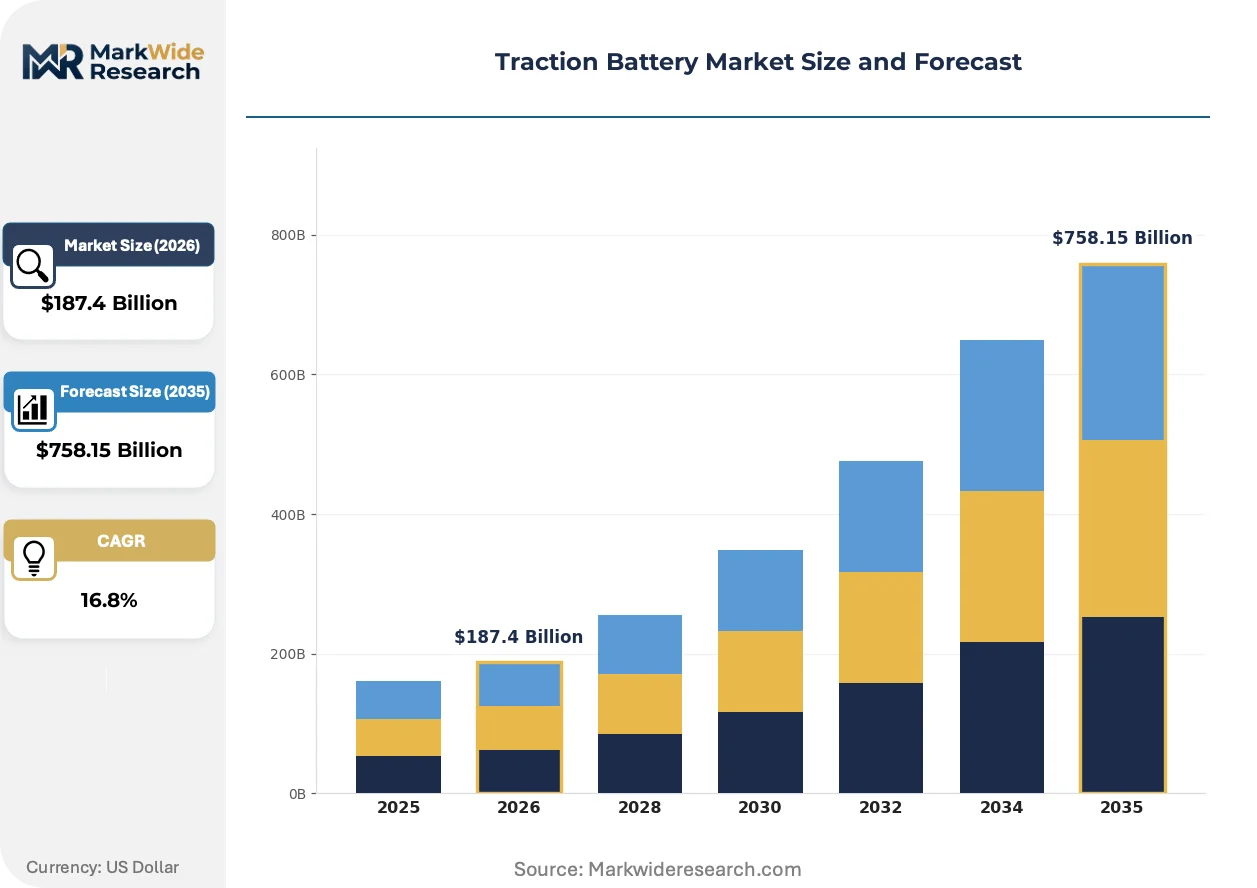
Market Dynamics
Capital intensity in cathode precursor production is concentrating competitive advantage among suppliers with captive mining offtake and integrated refining capacity, locking out capital-constrained entrants from the highest-margin supply tiers.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-carbon cell manufacturing are redirecting factory investment toward renewable-powered production sites, qualifying European-sourced cells for premium automotive contracts.
- Heavy marine electrification:Above 200 Ah large-format packs are capturing procurement volumes from ferry operators and short-sea shipping lines seeking zero-emission harbor compliance.
- China's dual carbon goals:MIIT enforcement of GB standards for battery traceability is accelerating domestic recycling infrastructure buildout, reducing virgin material dependency for qualified suppliers.
Market Restraints
- Lithium carbonate volatility:Price swings in spodumene concentrate feedstock are compressing margin predictability for cathode material producers without long-term offtake hedging.
- Supply concentration risk:Cathode precursor refining capacity clusters in China's Hunan and Fujian provinces, exposing non-Chinese cell makers to single-geography disruption scenarios.
- Sodium-ion energy density ceiling:Gravimetric performance gaps versus lithium-ion chemistry constrain sodium-ion traction batteries to material handling and stationary applications where weight tolerance exists.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Production-linked incentives are attracting gigafactory investment toward Tamil Nadu and Gujarat, creating localized supply for two-wheeler and three-wheeler electrification.
- Battery-as-a-service leasing models:Fleet operators in Germany's automotive corridor are adopting pay-per-kilometer contracts, decoupling vehicle purchase from energy storage capital expenditure.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator technologies are approaching pilot-scale validation, promising step-change improvements in fast-charge capability for premium EV platforms.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise concentrates at established research centers, constraining expansion timelines for new market entrants.
- CE marking certification timelines:EU battery passport requirements and carbon footprint verification protocols are extending product qualification cycles by twelve to eighteen months for non-European suppliers.
- Legacy BMS integration complexity:Retrofitting second-life traction batteries into stationary storage applications requires proprietary communication protocol adaptation, fragmenting aftermarket value recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Battery Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Sodium-ion End User: Electric Vehicles, Material Handling, Marine, Rail Transport Installation: Onboard, Stationary, Portable, Backup Capacity: Below 50 Ah, 51-100 Ah, 101-200 Ah, Above 200 Ah |
| Companies Covered | CATL, Panasonic Corporation, LG Chem, Samsung SDI, BYD Company, GS Yuasa International, EnerSys, Amara Raja Batteries, Exide Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Battery Market Emerging Trajectories
Electrode architecture innovations and manufacturing process intensification are compressing cost curves while regulatory pressure on embodied carbon reshapes siting and sourcing decisions across the value chain.
Sodium-ion chemistry is hybridizing with hard carbon anode formulations to serve forklift fleets and grid storage installations where energy density requirements relax and cost minimization dominates procurement criteria. Warehouse operators in Germany and the Netherlands are piloting sodium-ion traction packs for material handling equipment, validating cycle life performance under intensive shift-duty conditions. This chemistry hybridization is creating a mid-market tier between lead-acid displacement and premium lithium-ion applications, expanding addressable volume in industrial electrification.
The EU's F-Gas Regulation and battery passport requirements under the EU Green Deal are mandating granular carbon accounting across cell production stages, disqualifying coal-intensive supply chains from qualified supplier lists. OEM procurement teams are now requiring Scope 3 emissions disclosures from cathode active material suppliers, shifting contract awards toward European and North American production bases. Premium EV platforms in Germany and Sweden are prioritizing cells produced with renewable electricity, compressing market access for unverified Asian supply.
Fleet operators are consolidating procurement around battery-as-a-service contracts that transfer residual value risk and performance liability to cell suppliers or third-party lessors. Logistics companies operating regional distribution networks are abandoning capital purchase models in favor of usage-based agreements with guaranteed capacity retention clauses. This financing model rotation is most visible in Germany's Ruhr industrial corridor and the Netherlands' port logistics clusters, where electrified heavy-duty vehicle deployment is accelerating under emissions zone pressure.
Traction Battery Market Segmentation
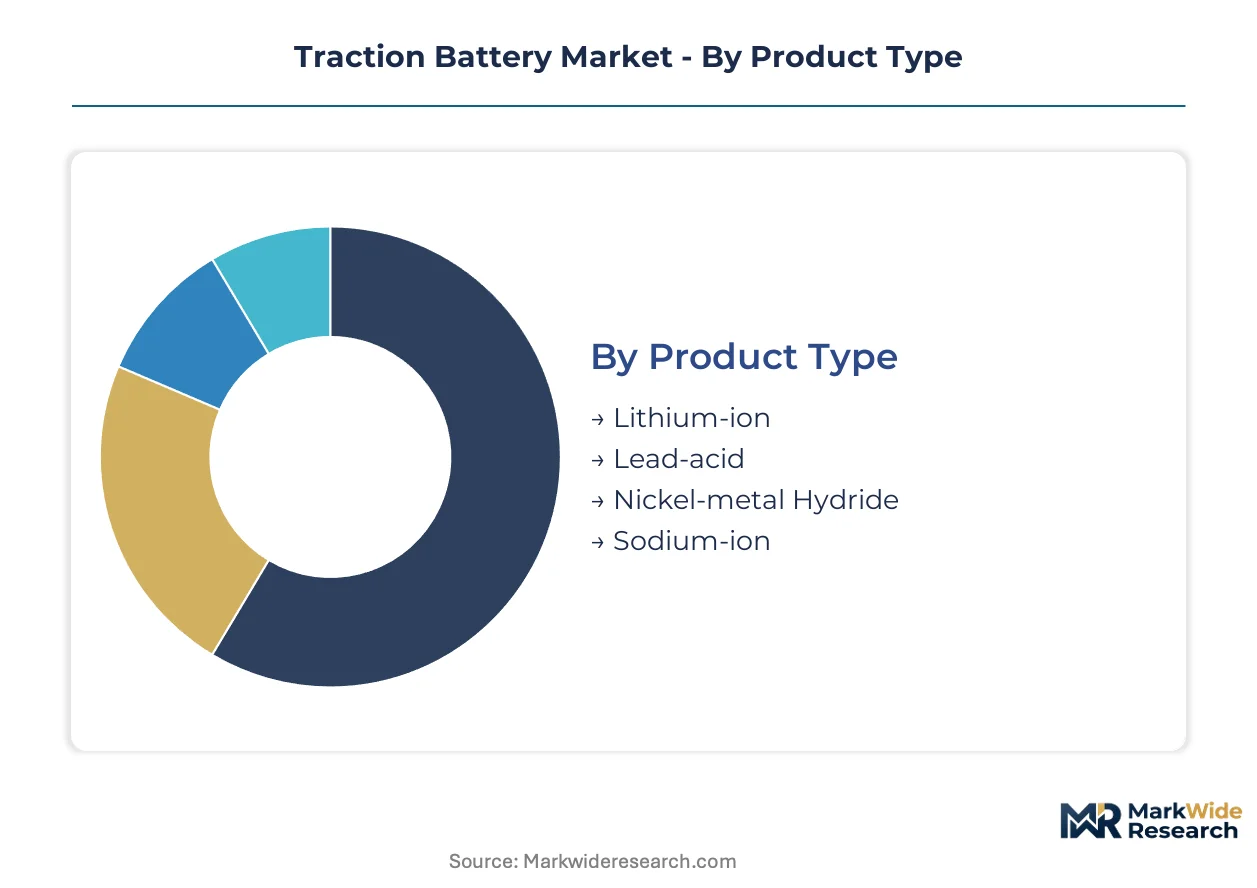
Traction battery procurement patterns diverge sharply across chemistry families and duty cycles. Fleet operators select cell platforms based on discharge rate requirements, thermal envelope constraints, and second-life recovery potential.
Product Type:
Cycle-time economics separate chemistries with 3,000+ cycle endurance from those requiring mid-life replacement in intensive duty applications.
- Lithium-ion:NMC and LFP cathode formulations deliver gravimetric energy density above 250 Wh/kg for passenger EV platforms. CATL and LG Chem supply chains dominate procurement for German and Swedish OEM premium platforms seeking fast-charge capability under EU Green Deal carbon accounting rules.
- Lead-acid:Flooded and AGM variants retain installed base in forklift fleets and golf cart applications where capital constraints override energy density requirements. Warehouse operators in India's industrial corridors specify lead-acid for single-shift equipment with predictable replacement schedules.
- Nickel-metal Hydride:Toyota's hybrid electric vehicle programs remain the primary offtake channel for this chemistry. NiMH traction packs serve mild-hybrid architectures where deep discharge avoidance extends service life beyond 15 years.
- Sodium-ion:Hard carbon anode formulations achieve 160 Wh/kg cell-level density for grid storage and material handling substitution. China's CATL and BYD are scaling pilot lines for stationary installations where weight tolerance permits cost-driven chemistry switching.
Lithium-ion anchors the volume base while sodium-ion gains share at the steepest rate.
End User:
Application-specific duty profiles create margin tiering from continuous deep-cycle marine to shallow-cycle automotive stop-start systems.
- Electric Vehicles:Passenger cars, buses, and two-wheelers absorb the deepest cell production volumes with 1C continuous discharge requirements. China's MIIT GB standards and India's PLI scheme are redirecting gigafactory investment toward localized EV supply chains.
- Material Handling:Forklift fleets and automated guided vehicles operate multi-shift cycles demanding 8-hour endurance under 25°C ambient thermal management. Germany's Ruhr logistics corridor and Netherlands port clusters are electrifying under emissions zone compliance pressure.
- Marine:Ferry operators and short-sea shipping lines specify large-format packs above 200 Ah for harbor zero-emission mandates. EU F-Gas Regulation carbon accounting is qualifying Scandinavian-produced cells for premium marine contracts.
- Rail Transport:Locomotive and multiple-unit traction systems require 1,500V DC compatibility with crashworthiness certification. India's Dedicated Freight Corridor and Germany's regional rail networks are consolidating procurement around single-supplier maintenance agreements.
Electric vehicles anchor the volume base while marine applications expand most quickly under regulatory compliance deadlines.
Installation:
Mounting configuration determines thermal management complexity and crash safety engineering requirements across vehicle platforms.
- Onboard:Chassis-integrated packs with liquid cooling circuits serve motive duty in passenger EVs and commercial trucks. German OEMs specify onboard architectures with cell-to-pack designs eliminating module housings.
- Stationary:Containerized systems for rail yard charging and port electrification operate at fixed locations with grid-tied power conversion. China's dual carbon goals are accelerating stationary installations at domestic logistics hubs.
- Portable:Swappable battery systems for two-wheelers and three-wheelers enable rapid energy replenishment without charging infrastructure. India's BIS certification requirements are standardizing portable pack interfaces for last-mile delivery fleets.
- Backup:Traction-derived cells repurposed for uninterruptible power supply duty in data centers and medical facilities. Second-life sourcing from automotive retirement streams is creating supply uncertainty for backup system integrators.
Onboard installations anchor the volume base while portable configurations climb the fastest in emerging market two-wheeler electrification.
Capacity:
Pack sizing stratifies procurement between high-volume standardized modules and low-volume engineered systems for heavy transport.
- Below 50 Ah:Cell formats for electric two-wheelers and power tools with 18650 and 21700 cylindrical geometries. India's PLI scheme is attracting capacity investment toward sub-50 Ah production for domestic mobility markets.
- 51-100 Ah:Prismatic and pouch cells serving passenger EV platforms with 60-80 kWh pack targets. German automotive corridor OEMs are consolidating 100 Ah-class procurement around European-sourced cells with renewable electricity verification.
- 101-200 Ah:Large prismatic formats for electric buses and light commercial vehicles requiring 200-300 km range. China's MIIT traceability standards are mandating cell-level serialization for this capacity tier in domestic commercial vehicle applications.
- Above 200 Ah:Single large-format packs for rail locomotives, marine vessels, and mining trucks with megawatt-hour scale energy storage. EU F-Gas Regulation embodied carbon limits are restricting market access for unverified Asian supply in this premium tier.
51-100 Ah capacity anchors the volume base while above 200 Ah configurations show the steepest expansion trajectory in heavy transport electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and carbon border mechanisms are redirecting gigafactory investment toward jurisdictions with renewable electricity verification and domestic content requirements. National regulators are tightening traceability mandates while fleet electrification deadlines accelerate procurement concentration in automotive corridors.
China
MIIT enforcement of GB standards for battery safety and recycling traceability is compressing market access for non-compliant imports. The dual carbon goals are accelerating domestic cathode precursor refining capacity in Hunan and Fujian provinces. CATL and BYD anchor cell production in the Yangtze River Delta and Pearl River Delta clusters serving both domestic EV absorption and export qualification.
Germany
OEM procurement teams in the automotive corridor are mandating renewable electricity verification for cell suppliers under EU Green Deal carbon accounting rules. The F-Gas Regulation embodied carbon limits are disqualifying coal-intensive supply chains from qualified supplier lists. The Ruhr industrial corridor and Stuttgart region are consolidating battery-as-a-service leasing adoption for electrified heavy-duty vehicle deployment.
United States
IRA domestic content bonuses are redirecting cathode active material investment toward North American production bases. EPA emissions standards for commercial vehicle fleets are accelerating port electrification procurement in California and the Pacific Northwest. The Southeast automotive belt is attracting gigafactory development to serve regional OEM final assembly plants.
India
The PLI scheme for advanced chemistry cell manufacturing is attracting investment toward Tamil Nadu and Gujarat for localized two-wheeler and three-wheeler supply. BIS certification requirements are standardizing portable pack interfaces for last-mile delivery fleets. The Dedicated Freight Corridor is consolidating rail traction battery procurement around single-supplier maintenance agreements with domestic qualification.
South Korea
METI-aligned technology licensing frameworks are supporting high-nickel chemistry R&D intensity across multiple OEM programs. The Seoul Capital Area and Busan-Ulsan industrial belt host concentrated cell design and thermal management expertise. Domestic suppliers are anchoring dedicated production lines serving premium EV platforms with fast-charge capability requirements.
Traction Battery Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base organizes around three archetypes: vertically integrated miners-refiners with captive precursor supply, technology licensors with chemistry-specific R&D depth, and regional assemblers serving price-sensitive fleet replacement cycles. Consolidation pressure is concentrating advantage among suppliers with backward integration into cathode materials and renewable-powered production verification. Strategic moves center on long-term offtake hedging and M&A targeting recycling infrastructure.
Within the integrated-tier archetype, CATL exemplifies upstream control over cathode precursor supply chains. Panasonic Corporation occupies a position representing dedicated production line arrangements for premium automotive platforms. LG Chem sits within the technology-licensor tier, anchoring high-nickel chemistry development intensity. These three entities collectively illustrate how competitive positioning stratifies between captive supply security, manufacturing fidelity, and electrochemical innovation vectors.
| Leading Market Players |
|---|
| CATL |
| Panasonic Corporation |
| LG Chem |
| Samsung SDI |
| BYD Company |
| GS Yuasa International |
| EnerSys |
| Amara Raja Batteries |
| Exide Industries |
| Others |
Supply Flow & Price Mechanics
Germany's Ruhr logistics corridor freight cost dynamics expose how cathode precursor concentration in China's Hunan and Fujian provinces feeds downstream price differentiation across certification tiers. OEM procurement teams leverage EU F-Gas Regulation carbon accounting to extract premium pricing for renewable-verified cells while squeezing margin pools for unverified Asian supply.
Pricing Analysis
Certification level under EU battery passport and CE marking protocols creates the primary spread between premium and standard supply tiers. Three-tier pricing structure across premium, standard, and economy levels reflects embodied carbon verification, with renewable-electricity cells commanding placement in German and Swedish OEM platforms. Cost compression in the economy tier is intensifying because of lithium carbonate volatility and spodumene concentrate feedstock uncertainty. Fleet operators in material handling and two-wheeler segments exhibit highest price sensitivity, while marine and rail procurement teams prioritize performance retention clauses over unit economics.
Supply Chain Analysis
CATL, LG Chem, and Samsung SDI contract manufacturing arrangements concentrate high-nickel and LFP cell capacity in China, South Korea, and Japan. The traction battery supply chain draws from lithium spodumene concentrate, nickel sulfate, and cobalt hydroxide feedstocks with refining clusters concentrated in East Asian industrial belts. Single-geography disruption scenarios expose non-Chinese cell makers to cathode precursor supply interruption. Distribution runs through dedicated production line arrangements serving premium EV platforms and modular pack suppliers for industrial electrification fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical engineering talent scarcity constrains expansion timelines for new market entrants, with cell design and thermal management expertise anchored at established Yangtze River Delta and Seoul Capital Area research centers. The capability gap favors incumbents with captive R&D infrastructure.
For Market Incumbents: Entrench position through backward integration into cathode active material refining and renewable electricity verification for European qualification. Lock in long-term offtake hedging with Australian and Chilean lithium miners to defend margin pools against carbonate volatility. Prioritize recycling infrastructure M&A to secure domestic traceability compliance under China's MIIT GB standards. For New Entrants and Emerging Players: Pursue white-space opportunity in India's Tamil Nadu and Gujarat gigafactory zones where PLI scheme incentives offset capital intensity barriers. Target sodium-ion chemistry for material handling and stationary storage applications where energy density tolerance permits cost-driven substitution. Deploy battery-as-a-service leasing models to decouple vehicle purchase from energy storage capital expenditure in Germany's automotive corridor. For Investors and Strategic Acquirers: Cathode precursor refiners with captive mining offtake and integrated renewable power represent the most defensible acquisition archetype in a five-to-ten-year window. Monitor EU carbon border adjustment mechanism implementation as the critical inflection signal for cost competitiveness between regional supply bases. Prioritize targets with established CE marking certification and cell-to-pack thermal management IP.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive nickel sulfate and lithium hydroxide refining locks in margin pools for CATL and LG Chem supply chains. |
| Renewable Electricity Verification Program | EU F-Gas Regulation compliance qualifies European-sourced cells for premium automotive contracts in Germany. |
| Battery-as-a-Service Platform Launch | Pay-per-kilometer contracts transfer residual value risk to cell suppliers in Netherlands port logistics clusters. |
| Solid-State Electrolyte Pilot Scale-Up | Sulfide ceramic separator validation promises fast-charge capability for premium EV platforms in South Korea. |
| Recycling Infrastructure Joint Venture | Dominated recycling traceability under China's MIIT GB standards reduces virgin material dependency for qualified suppliers. |
Methodological Framework
Cross-validation between primary interviews with cell design engineers, OEM platform procurement leads, and cathode material plant managers anchors the qualitative findings against secondary validation from MIIT GB standard filings, EU battery passport regulatory disclosures, and customs trade data for lithium carbonate and nickel sulfate flows. Bottom-up segmentation modeling triangulates with top-down industry absorption estimates across chemistry families and end-use categories.
Calibration against historical capacity deployment patterns and announced gigafactory investment timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include chemistry family, capacity tier, installation configuration, and end-use duty cycle intensity. CAGRs derive from installed base replacement schedules and electrification deadline compliance trajectories in Germany's automotive corridor and India's Dedicated Freight Corridor.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot pricing, renewable electricity cost curves, or EU carbon border adjustment implementation schedules would shift the trajectory. Quarterly review of cathode precursor refining capacity utilization and CE marking certification timeline extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Germany EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
US EV Battery Pack Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Japan EV Battery Pack Market