
 Middle-East Electric Vehicle Battery Market | 2026-2036
Middle-East Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Electric Vehicle Battery Market Foresight
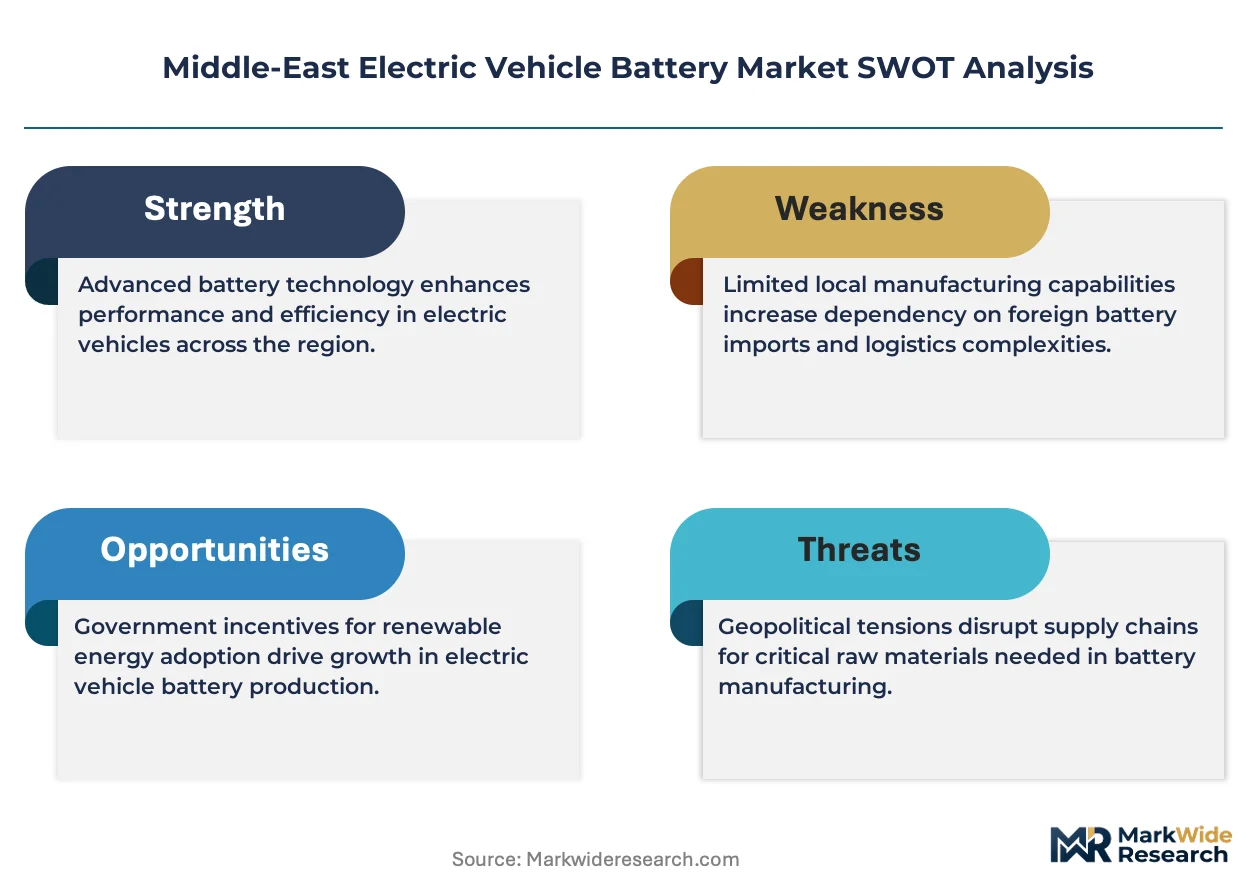
Aftermarket battery refurbishment and second-life energy storage revenue is rewriting margin allocation across the Middle-East value chain. LG Energy Solution leverages its cylindrical cell expertise to anchor supply relationships with emerging Gulf automakers. Samsung SDI sustains technology leadership through its prismatic NCM platform optimized for desert thermal conditions. CATL dominates regional procurement conversations with its LFP cost structure and scale advantages in utility-scale storage tie-ins.
Middle-East electric vehicle batteries are electrochemical energy storage systems engineered with nickel-manganese-cobalt or lithium-iron-phosphate cathode chemistries, operating within 400-800V architectures and thermal management thresholds exceeding 55°C ambient design points, purpose-built to power traction motors in passenger and commercial vehicles across high-temperature desert climates. Lithium-ion chemistry leads absolute volume while solid-state prototypes attract R&D capital from Gulf sovereign wealth funds seeking technology differentiation. Passenger vehicles anchor current offtake, though commercial vehicle electrification for last-mile logistics and intercity freight is expanding fastest among application categories.
Saudi Arabia's dual carbon goals and the UAE's net-zero transport mandates shape product standards, with both frameworks requiring localized content thresholds and recycling accountability that filter market access for foreign suppliers. SFDA and SASO technical regulations in Saudi Arabia, alongside Emirates Authority for Standardization and Metrology specifications in the UAE, establish cell-grade certification and thermal safety testing protocols that suppliers must satisfy before commercial deployment. Stakeholders must monitor how Gulf standardization bodies harmonize battery passport requirements with EU regulatory trajectories to avoid compliance fragmentation across export and domestic channels.
Market Dynamics
Sovereign capital deployment into domestic battery manufacturing zones is restructuring competitive access across Gulf Cooperation Council states, with localized content mandates from Saudi Arabia and the UAE now filtering supplier qualification.
Growth Catalysts
- SFDA and SASO technical regulations:Saudi Arabia's cell-grade certification requirements are accelerating compliance investments from qualified suppliers, creating preferential market access for pre-certified producers.
- Last-mile logistics electrification:Fleet operators across Dubai and Riyadh are scaling battery-electric van procurement, generating concentrated offtake corridors for lithium-ion cell suppliers.
- Desert thermal management engineering:NCM and LFP architectures optimized for 55°C ambient operating thresholds are unlocking commercial vehicle deployment in high-temperature climates previously inaccessible to standard battery packs.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings are compressing cell producer margins and delaying project financing for Gulf manufacturing investments.
- Supply concentration in Northeast Asian cell production:Procurement dependency on cylindrical and prismatic cell imports from concentrated production bases creates logistics vulnerability and currency exposure.
- Recycling infrastructure deficit:Absence of regional battery dismantling and black mass processing capacity is imposing end-of-life compliance costs on importers under emerging UAE and Saudi recycling accountability frameworks.
Strategic Opportunities
- Kingdom of Saudi Arabia gigafactory zones:Greenfield battery manufacturing sites within NEOM and King Abdullah Economic City offer tariff-advantaged production for regional export.
- Second-life stationary storage:Retired EV battery packs are finding utility-scale demand from Gulf grid operators seeking 4-6 hour duration storage for solar pairing.
- Emirates Authority for Standardization and Metrology specifications:Thermal safety testing protocols aligned with EU battery passport trajectories are creating regulatory harmonization premiums for early-compliant suppliers.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell chemistry specialists and thermal management engineers remain concentrated in Northeast Asian and European labor markets, constraining Gulf manufacturing ramp timelines.
- Certification timeline compression:SFDA and SASO approval cycles for new cell formats are extending commercial deployment schedules, particularly for solid-state prototypes seeking sovereign wealth fund backing.
- Charging-battery integration complexity:800V architecture deployment requires coordinated validation between cell suppliers, power electronics providers, and Gulf utility grid operators, fragmenting procurement accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Electric Vehicle Battery Market |
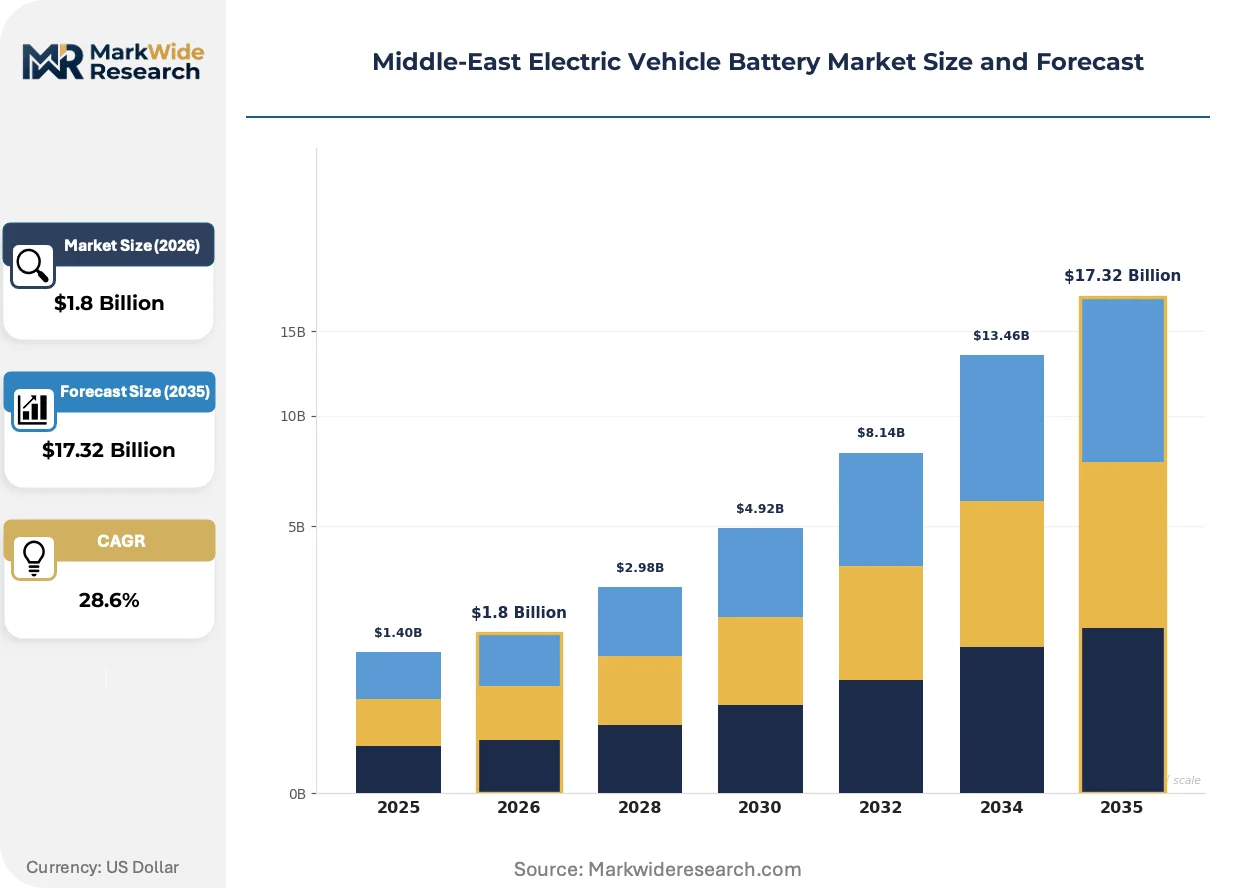
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Energy Storage Systems End User: Automotive Manufacturers, Fleet Operators, Charging Station Providers, Consumers Technology: Fast Charging, Battery Management Systems, Recycling Solutions, Thermal Management |
| Companies Covered | Samsung SDI, Panasonic Corporation, LG Energy Solution, Exide Industries Ltd, Middle East Battery Company (MEBCO), BYD Co. Ltd., Tesla Inc., Saft Groupe SA, CATL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Electric Vehicle Battery Market Shifts & Advancements
Thermal engineering breakthroughs and regulatory harmonization efforts are compressing technology adoption cycles across Middle-East electric vehicle battery procurement.
Lithium-iron-phosphate chemistry is collapsing cost barriers for commercial vehicle electrification in Saudi Arabia and the UAE. Fleet procurement managers at logistics operators are specifying LFP packs for last-mile delivery vans at accelerating volume. This chemistry shift is collapsing the historical premium that nickel-manganese-cobalt cells commanded in high-temperature desert applications.
SFDA technical regulations governing cell-grade certification and thermal runaway propagation testing are mandating design modifications from all suppliers seeking Saudi commercial deployment. The industrial consequence is accelerated R&D allocation toward flame-retardant electrolyte formulations and ceramic-coated separators. Commercial vehicle segments operating in Riyadh and Jeddah corridors are responding with extended validation timelines and pre-qualification partnerships.
Direct procurement relationships between Gulf fleet operators and cell manufacturers are displacing traditional tiered distribution through automotive OEMs. Large logistics providers in Dubai and Abu Dhabi are negotiating volume offtake agreements directly with cylindrical and prismatic cell producers, bypassing integrated vehicle suppliers. This channel compression is most visible in the UAE, where Emirates Authority for Standardization and Metrology certification allows parallel import pathways for non-OEM battery configurations.
Middle-East Electric Vehicle Battery Market Segmentation
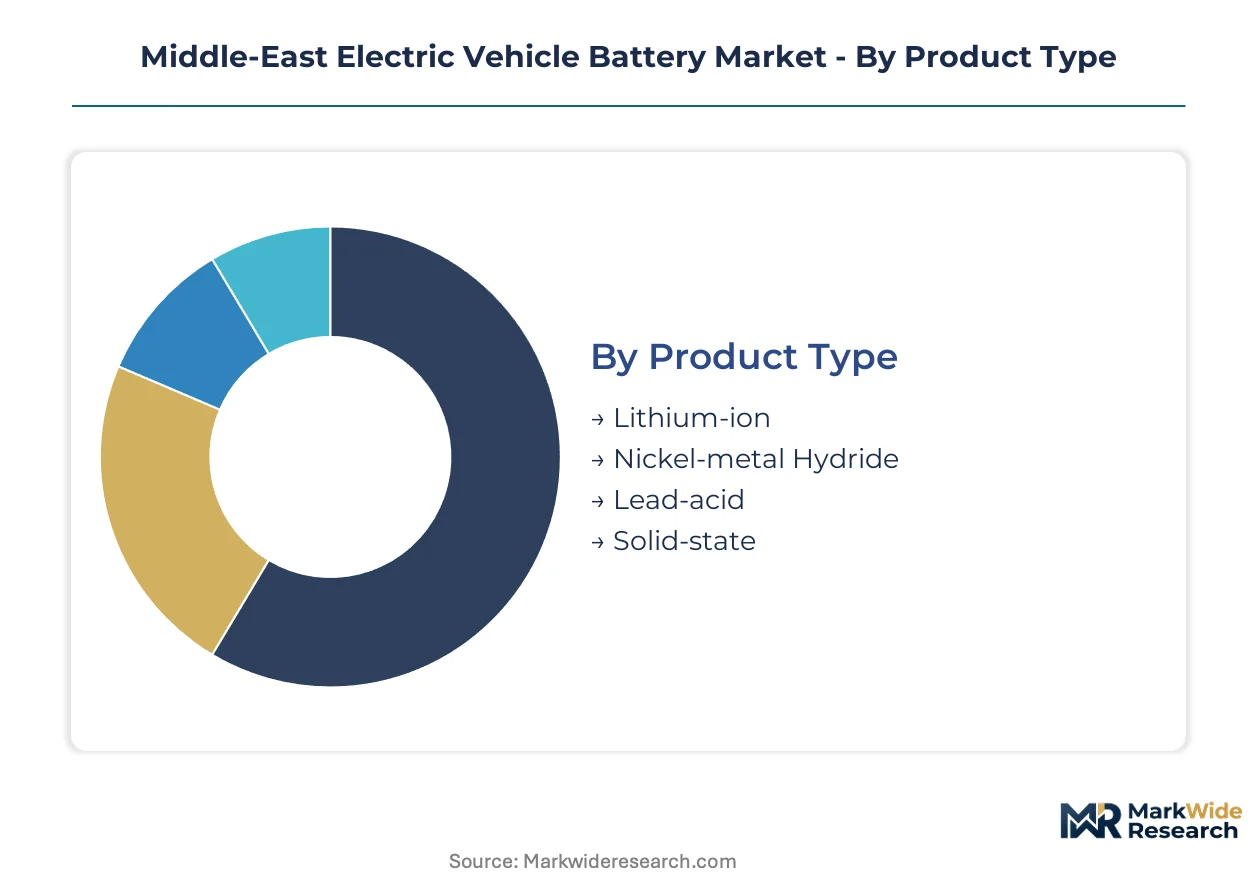
Segmentation across the Middle-East electric vehicle battery market reveals how Gulf procurement patterns diverge from global norms. Desert thermal engineering requirements and sovereign capital deployment priorities reshape which technologies and customer categories command commercial attention.
Product Type:
Cell chemistry selection in the Gulf balances cost efficiency against 55°C ambient operating thresholds that degrade standard pack performance.
- Lithium-ion:NCM and LFP architectures dominate procurement conversations across Saudi Arabia and the UAE. Fleet operators in Dubai and Riyadh specify these cells for passenger and commercial vehicle programs where thermal management systems add necessary engineering overhead.
- Solid-state:Prototype development attracts sovereign wealth fund capital seeking technology differentiation beyond incumbent chemistries. SFDA certification timelines for solid-state formats remain extended, compressing near-term deployment schedules despite performance advantages.
- Nickel-metal Hydride:Legacy hybrid vehicle applications in established Gulf fleets sustain limited procurement volume.
- Lead-acid:Auxiliary power applications and low-speed electric vehicles in price-sensitive segments retain residual demand.
Established volume favors lithium-ion; emerging adoption favors solid-state.
Application:
Deployment patterns track infrastructure buildout sequencing and regulatory mandate intensity across Gulf Cooperation Council states.
- Commercial Vehicles:Last-mile logistics electrification in Dubai and Riyadh corridors is climbing the fastest among application categories. Battery-electric van procurement from fleet operators generates concentrated offtake corridors with direct cell manufacturer negotiations bypassing traditional OEM channels.
- Passenger Vehicles:Current absolute volume anchors in the UAE and Saudi Arabia where charging infrastructure buildouts and government-backed EV manufacturing zones create concentrated battery demand. Consumer procurement responds to Emirates Authority for Standardization and Metrology certification pathways.
- E-Bikes:Micro-mobility solutions in dense urban centers like Abu Dhabi and Jeddah attract municipal procurement programs.
- Energy Storage Systems:Retired EV battery packs find second-life utility-scale demand from Gulf grid operators seeking solar pairing duration.
Passenger vehicles anchor present procurement; commercial vehicles dominate forward investment.
End User:
Customer structure reflects channel compression as direct procurement displaces traditional tiered distribution models.
- Fleet Operators:Large logistics providers negotiate volume offtake agreements directly with cylindrical and prismatic cell producers. Emirates Authority for Standardization and Metrology certification allows parallel import pathways that fragment traditional OEM control over battery supply.
- Automotive Manufacturers:Emerging Gulf automakers anchor supply relationships with established cell producers for localized assembly operations within Saudi gigafactory zones.
- Charging Station Providers:Grid operators coordinate 800V architecture validation with cell suppliers and power electronics providers.
- Consumers:Retail procurement concentrates in premium segments where thermal engineering specifications justify price premiums.
Fleet operators capture procurement scale; automotive manufacturers anchor manufacturing investment.
Technology:
Technical capability differentiation separates qualified suppliers from commodity competitors in Gulf certification frameworks.
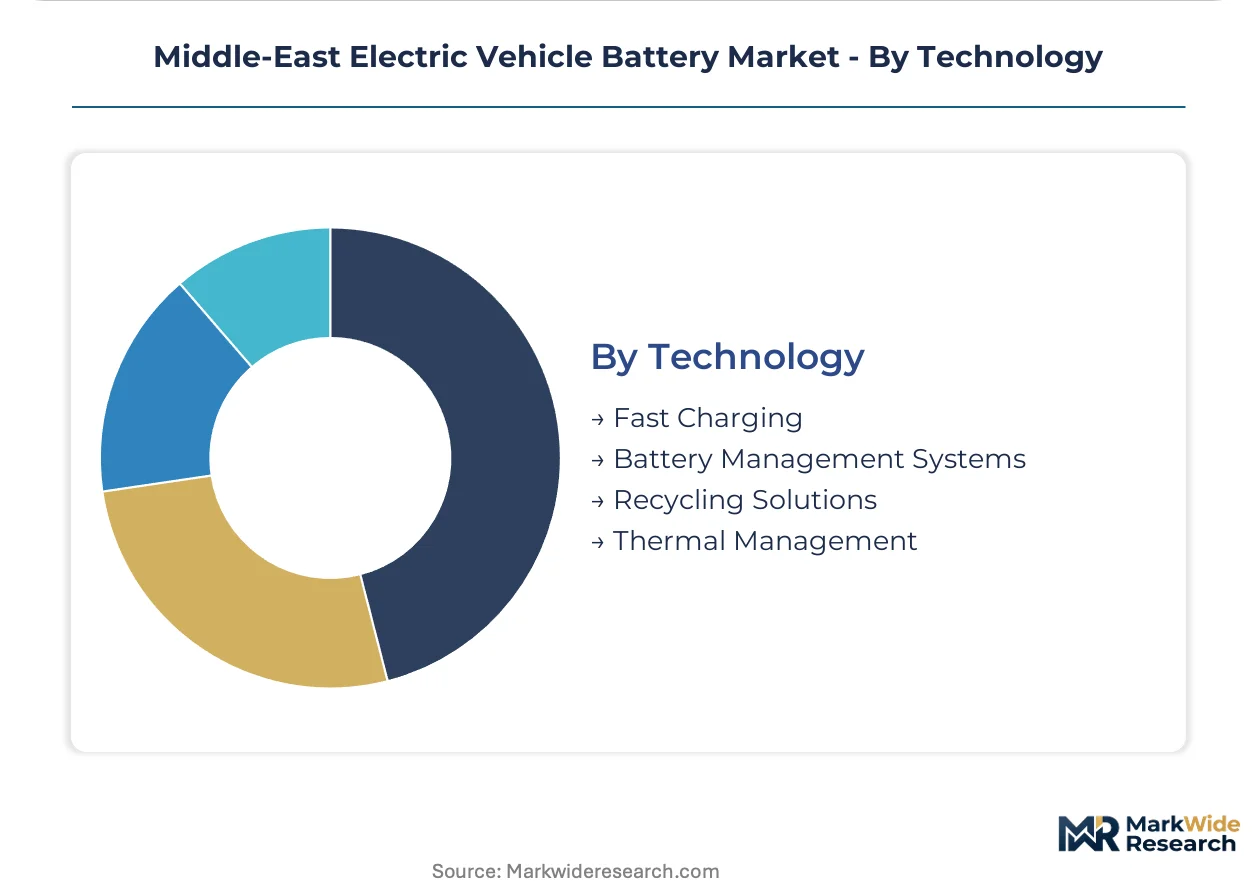
- Thermal Management:Engineering optimized for 55°C ambient thresholds unlocks commercial vehicle deployment in climates previously inaccessible to standard battery packs. SFDA technical regulations mandate flame-retardant electrolyte formulations and ceramic-coated separators.
- Battery Management Systems:Cell-grade certification requirements from SASO accelerate compliance investments toward intelligent monitoring architectures.
- Fast Charging:800V deployment requires coordinated validation between cell suppliers, power electronics providers, and Gulf utility grid operators.
- Recycling Solutions:Absence of regional dismantling capacity imposes end-of-life compliance costs under emerging UAE and Saudi recycling accountability frameworks.
Thermal management commands engineering premium; recycling solutions face infrastructure deficit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery procurement patterns diverge sharply across Gulf Cooperation Council states, with fleet operators in the UAE and Saudi Arabia driving commercial vehicle electrification while other markets remain anchored in passenger vehicle pilots and early infrastructure deployment.
United Arab Emirates
Dubai-based logistics fleets are negotiating direct offtake agreements with cylindrical cell producers, bypassing traditional automotive OEM channels. Emirates Authority for Standardization and Metrology specifications for thermal safety testing create regulatory harmonization premiums for pre-certified suppliers. Abu Dhabi's industrial zones concentrate battery assembly operations serving both domestic demand and re-export corridors into Africa and South Asia.
Saudi Arabia
SFDA and SASO technical regulations governing cell-grade certification and thermal runaway propagation testing mandate design modifications from all suppliers seeking commercial deployment. The Kingdom's dual carbon goals accelerate lithium-ion procurement for government-backed EV manufacturing zones. NEOM and King Abdullah Economic City host greenfield gigafactory sites offering tariff-advantaged production for regional battery export.
Qatar
Public transit electrification programs generate concentrated demand for high-temperature optimized battery packs in Doha metropolitan corridors. The country's national standardization body aligns certification pathways with emerging Gulf harmonization frameworks. Industrial clusters around Ras Laffan integrate battery storage with utility-scale solar deployment for grid stabilization.
Kuwait
Municipal fleet procurement for last-mile delivery applications sustains modest battery offtake despite limited charging infrastructure buildout. The country's technical regulations for automotive components impose import testing requirements that filter supplier market access. Urban centers concentrate early pilot programs for commercial vehicle electrification in logistics and parcel delivery segments.
Oman
Port and logistics hub electrification at Sohar and Salalah drives niche demand for heavy-duty battery systems in material handling and short-haul freight. The sultanate's renewable energy integration targets create secondary demand for retired EV batteries in stationary storage applications. Industrial free zones offer tariff advantages for battery assembly and pack integration serving regional re-export markets.
Middle-East Electric Vehicle Battery Market Competitive Landscape
Capability concentration sits with established Northeast Asian cell producers; scale advantage sits with integrated automotive-battery conglomerates seeking Gulf manufacturing footholds. The vendor base structures around three tiers: global cell specialists with certified thermal management platforms, regional pack integrators serving fleet direct procurement, and emerging Gulf-based assemblers leveraging sovereign capital deployment. Dominant competitive moves include strategic partnerships with Saudi and Emirati industrial zones and technology licensing arrangements that satisfy localized content mandates.
Among Northeast Asian specialists, Samsung SDI, LG Energy Solution, and CATL occupy positions that exemplify divergent strategic archetypes. Samsung SDI represents the premium-tier thermal engineering specialist segment. LG Energy Solution anchors the cylindrical cell expertise tier serving emerging Gulf automaker relationships. CATL sits within the cost-optimized LFP scale tier dominating regional procurement conversations through utility-scale storage tie-ins.
| Leading Market Players |
|---|
| Samsung SDI |
| Panasonic Corporation |
| LG Energy Solution |
| Exide Industries Ltd |
| Middle East Battery Company (MEBCO) |
| BYD Co. Ltd. |
| Tesla Inc. |
| Saft Groupe SA |
| CATL |
| Others |
Supply & Pricing Matrix
Northeast Asian cell production clusters in Incheon, Osaka, and Ningbo concentrate cathode active material capacity that feeds directly into Gulf procurement negotiations. This geographic concentration grants incumbent suppliers substantial leverage over contract terms, while lithium carbonate price volatility transmits downstream into compressed margins for pack integrators serving Saudi and Emirati fleet operators.
Pricing Analysis
Long-term offtake contracts dominate procurement between Gulf fleet operators and cylindrical cell producers, locking in volume commitments across multi-year horizons. Pricing stratifies across premium thermal-engineering tiers, with SFDA-certified packs commanding substantial premiums over standard configurations. Cost compression in the LFP segment is intensifying as CATL scales regional utility-storage tie-ins, eroding historical NCM premiums. Fleet operators in Dubai and Riyadh exhibit acute price sensitivity, while emerging Gulf automakers prioritize certification-grade reliability over unit economics.
Supply Chain Analysis
Contract manufacturing capacity concentrates with LG Energy Solution, Samsung SDI, and CATL, which control cylindrical and prismatic cell output feeding Middle-East demand. Cathode precursors and lithium carbonate draw from concentrated South Korean and Chinese refining operations. Single-source vulnerability around electrolyte formulations and ceramic-coated separators creates exposure to logistics chokepoints through Red Sea corridors. Distribution runs through direct manufacturer-fleet relationships that displace traditional OEM intermediaries, compressing channel margins while accelerating deployment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East electric vehicle battery market represents an early-cycle expansion story where sovereign capital deployment and regulatory mandate intensity are outpacing infrastructure readiness, creating asymmetric opportunity for positioned suppliers.
For Market Incumbents: Insulate market position by accelerating backward integration into cathode active material production within Saudi gigafactory zones, reducing exposure to lithium carbonate price swings. Deepen thermal engineering certification investments ahead of SFDA timeline compressions to create regulatory moats against emerging LFP competitors. Prioritize direct fleet operator relationships in Dubai and Riyadh corridors to defend channel control against parallel import pathways.
For New Entrants and Emerging Players: Pursue white-space opportunities in second-life stationary storage applications, where retired EV battery packs face limited regional competition for solar pairing contracts. Target Oman's port electrification segment at Sohar and Salalah, where heavy-duty material handling systems require specialized thermal management that incumbent suppliers have underdeveloped. Anchor go-to-market strategy through Emirates Authority for Standardization and Metrology certification partnerships that unlock UAE commercial deployment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pack integrators with demonstrated SFDA compliance and established fleet operator relationships over pure cell manufacturers facing margin compression. Long-term viability across the five-to-ten-year window rests on recycling infrastructure capture as Saudi and Emirati end-of-life accountability frameworks mature. Monitor sovereign wealth fund capital deployment velocity into NEOM and King Abdullah Economic City manufacturing zones as the primary inflection signal for regional production scale.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Pre-Investment | Early compliance with Saudi thermal runaway protocols secures preferential market access before mandate enforcement tightens. |
| Direct Fleet Operator Partnerships | Bypassing OEM channels in Dubai and Riyadh captures volume offtake agreements with logistics providers scaling electrification. |
| Cathode Material Backward Integration | In-house precursor production within Saudi gigafactory zones reduces lithium carbonate price exposure and satisfies localization thresholds. |
| Second-Life Storage Channel Development | Retired EV battery repurposing for Gulf grid operators creates revenue streams independent of new vehicle sales cycles. |
| Desert Thermal Engineering R&D | Flame-retardant electrolyte and ceramic separator development addresses 55°C ambient thresholds that standard packs fail. |
Research Methodology
A spread of perspectives from cell chemistry specialists, fleet procurement managers at Dubai-based logistics operators, thermal management engineers, and Saudi regulatory affairs consultants converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, IHS Markit vehicle production databases, and Emirates Authority for Standardization and Metrology technical specifications. Bottom-up cell procurement estimates triangulated against top-down sovereign capital deployment disclosures.
Demand-supply-balance modeling across the projection horizon integrated passenger vehicle, commercial vehicle, and stationary storage segmentation with thermal engineering capability tiers and certification status. CAGRs derived from volume trajectory analysis incorporating fleet operator electrification timelines, charging infrastructure buildout sequencing, and localized content mandate phase-ins. Industry-specific forecast inputs included lithium carbonate price scenario curves and SFDA approval cycle duration assumptions.
Macroeconomic conditions sit as an overlay; deviation in Gulf sovereign liquidity deployment, Red Sea logistics costs, or Chinese export policy would shift the trajectory materially. Forecasts reflect documented assumptions around regulatory harmonization pace and cell chemistry transition timelines. Quarterly review of Saudi gigafactory construction milestones, SFDA certification queue depth, and fleet operator order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
EV Batteries Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Cells Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Auto Storage Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market