
 Europe Electric Vehicle Battery Market | 2026-2036
Europe Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Market Foresight
Commercial vehicle electrification is restructuring how European fleet operators contract for battery capacity. SK On leverages its cylindrical cell expertise to anchor supply agreements with premium truck manufacturers. Samsung SDI competes through solid-state R&D intensity, while CATL dominates volume positioning via its Hungarian manufacturing base.
Europe electric vehicle batteries are electrochemical storage systems with nominal voltages typically ranging from 400V to 800V, engineered to deliver sustained discharge rates for traction applications across varying thermal conditions. Their primary purpose is to convert stored chemical energy into electrical power for propulsion while maintaining cycle stability over vehicle lifespans. Lithium-ion chemistry leads installed capacity due to energy density advantages, though lithium polymer formats are gaining share in performance-oriented passenger cars where packaging flexibility commands premium positioning. Nickel-metal hydride retains niche presence in hybrid architectures where cost sensitivity outweighs pure-electric range requirements.
The EU Green Deal, REACH, and the F-Gas Regulation collectively mandate carbon footprint declarations for imported cells and restrict fluorinated greenhouse gas use in manufacturing processes. EMA and national regulators are aligning clinical-grade quality frameworks with automotive battery safety protocols, tightening market access for non-compliant suppliers. Stakeholders must monitor how the EU AI Act and emerging battery passport requirements reshape traceability obligations and supplier qualification timelines.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing cathode chemistry transitions across European cell manufacturing, compressing supplier qualification timelines while redirecting capital toward lower-carbon production pathways. This regulatory pressure is restructuring how gigafactory operators contract for precursor materials and energy inputs.
Growth Catalysts
- EU Green Deal carbon footprint mandates:The regulation requires imported cells to carry verified carbon declarations, accelerating domestic manufacturing investments in Poland and Germany.
- Commercial fleet electrification:Logistics operators across the Netherlands and Belgium are restructuring long-term battery service agreements to secure capacity for electric trucks.
- Solid-state chemistry advancement:Higher energy density architectures are penetrating premium passenger segments where range anxiety previously constrained adoption.
Market Restraints
- Lithium carbonate price volatility:Input cost swings from South American brine operations are compressing cell producer margins and destabilizing contract pricing.
- Cathode active material concentration:Supply from Chinese precursor refiners creates geopolitical exposure for European battery assemblers dependent on nickel-manganese-cobalt formulations.
- Fluorinated solvent restrictions:The F-Gas Regulation limits electrolyte manufacturing processes, constraining local production scale-up timelines.
Strategic Opportunities
- Eastern European manufacturing expansion:Hungary and Poland offer cost-competitive greenfield sites with proximity to German OEM assembly plants.
- Battery passport traceability systems:The EU's digital product tracking mandate creates service revenue streams for compliance software providers and testing laboratories.
- Sodium-ion chemistry convergence:Emerging alternative formulations paired with stationary storage applications open cost-sensitive market segments.
Industry Challenges
- Electrochemical engineer scarcity:European universities produce insufficient talent to staff gigafactory process engineering roles.
- EMA-aligned safety certification timelines:Automotive battery protocols adapted from pharmaceutical quality frameworks extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Market |
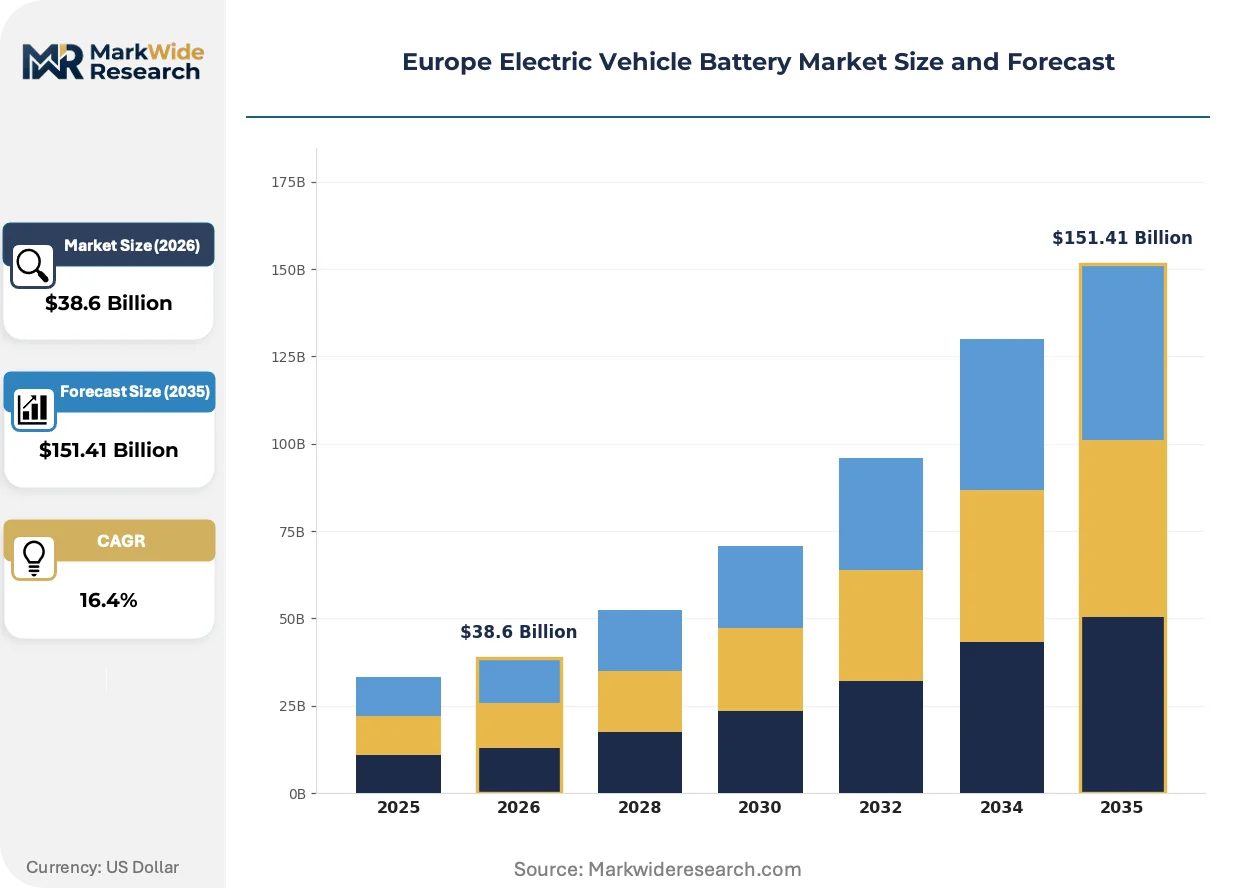
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lithium Polymer, Lead Acid Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, E-Bikes End User: Automakers, Fleet Operators, Charging Station Providers, Consumers Installation Type: Stationary, Mobile, Integrated, Modular |
| Companies Covered | SK On, Samsung SDI, CATL, Gotion High-Tech, EVE Energy, BYD, Panasonic, Automotive Cells Company (ACC), LG Energy Solution, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Market Shifts & Advancements
Cell chemistry diversification and digital traceability mandates are compressing traditional supply relationships while opening new service layers around battery lifecycle management. These forces are reshaping how European manufacturers compete on sustainability credentials.
Cell-to-pack architectures are eliminating module housings and reducing structural mass in passenger vehicle applications. Premium German OEMs are adopting these designs for their next-generation electric platforms launching through 2027. This consolidation is decentralizing tiered supplier hierarchies as cell producers assume direct integration responsibilities previously held by module assemblers.
The EU AI Act imposes algorithmic transparency requirements on battery management systems that use machine learning for state-of-charge estimation. Cell producers must now document training data provenance and decision logic for regulatory review. Automotive OEMs in France and Italy are most exposed given their early deployment of predictive maintenance software.
Fleet operators are contracting for battery capacity through energy-as-a-service models rather than capital purchase. Logistics providers in the Nordic region are leading this transition, substituting upfront cell acquisition with per-kilometer usage fees. This restructures risk allocation toward manufacturers while compressing financing margins for traditional equipment lessors.
Europe Electric Vehicle Battery Market Segmentation
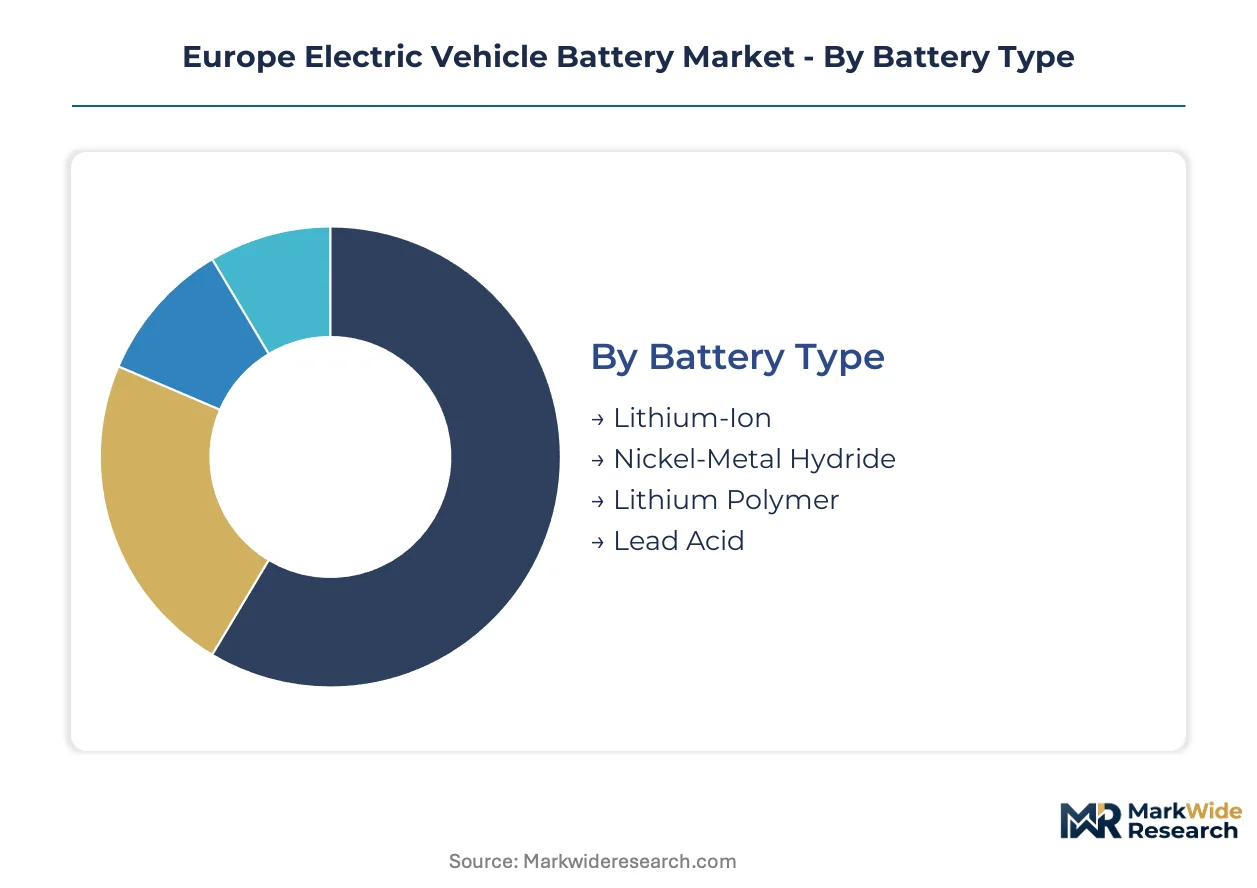
Cell chemistry selection and installation architecture determine how European manufacturers align with EU Green Deal carbon mandates and F-Gas Regulation compliance timelines. Segmentation reveals which battery configurations command premium positioning versus volume scale.
Battery Type:
Integration depth varies sharply: standalone cell formats serve aftermarket replacement demand while embedded chemistries lock into OEM platform designs for vehicle lifecycles.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate architectures dominate European gigafactory output, with NMC formulations preferred by German premium OEMs for energy density. Polish and Hungarian cell plants are scaling LFP production for commercial vehicle contracts where cycle life outweighs gravimetric efficiency.
- Lithium Polymer:Pouch cell configurations enable packaging flexibility in performance-oriented passenger cars from Italian and French manufacturers. These cells integrate directly into skateboard chassis designs, eliminating module housings and reducing thermal management complexity.
- Nickel-Metal Hydride:Hybrid electric vehicle architectures in cost-sensitive segments retain this chemistry for power-assist applications where pure-electric range is secondary to regenerative braking capture.
- Lead Acid:Auxiliary power units and low-speed electric vehicles in Eastern European markets continue using this mature technology for 12V subsystem support and starter battery replacement.
Lithium-ion leads volumes today; lithium polymer is gaining share fastest in premium passenger segments.
Application:
Cost tier stratification separates capital-intensive commercial deployments from consumer-driven passenger adoption curves.
- Passenger Cars:Cell-to-pack architectures are compressing bill-of-materials costs for German and French OEM platform launches. Range requirements above 500km are pushing nickel-rich cathode adoption despite raw material price volatility.
- Commercial Vehicles:Fleet operators across Belgium and the Netherlands are restructuring procurement around battery-as-a-service contracts. Electric truck demand is concentrating in urban delivery routes where overnight depot charging eliminates fast-charging infrastructure dependency.
- Two-Wheelers:Last-mile delivery fleets in Southern European cities are electrifying scooter and moped segments with swappable battery systems.
- E-Bikes:German and Dutch cycling infrastructure investments are driving mid-drive motor battery integration with frame-locked designs to reduce theft exposure.
Passenger cars anchor current installed capacity; commercial vehicles are climbing the fastest as logistics operators electrify.
End User:
Customer type determines contract structure complexity and service layer attachment rates.
- Automakers:Direct cell supply agreements with CATL, Samsung SDI, and SK On are restructuring tiered supplier hierarchies as cell producers assume module integration responsibilities previously held by intermediaries.
- Fleet Operators:Energy-as-a-service models are displacing capital purchase in Nordic logistics markets, transferring residual value risk to manufacturers.
- Charging Station Providers:Stationary storage buffer batteries are creating secondary demand streams for retired automotive cells under circular economy mandates.
- Consumers:Aftermarket replacement demand concentrates in aging hybrid vehicle populations where dealer network access constrains supplier choice.
Automakers dominate procurement volumes today; fleet operators are expanding most quickly through service-based contracting.
Installation Type:
Supply concentration in module assembly versus pack integration is reshaping margin capture across the value chain.
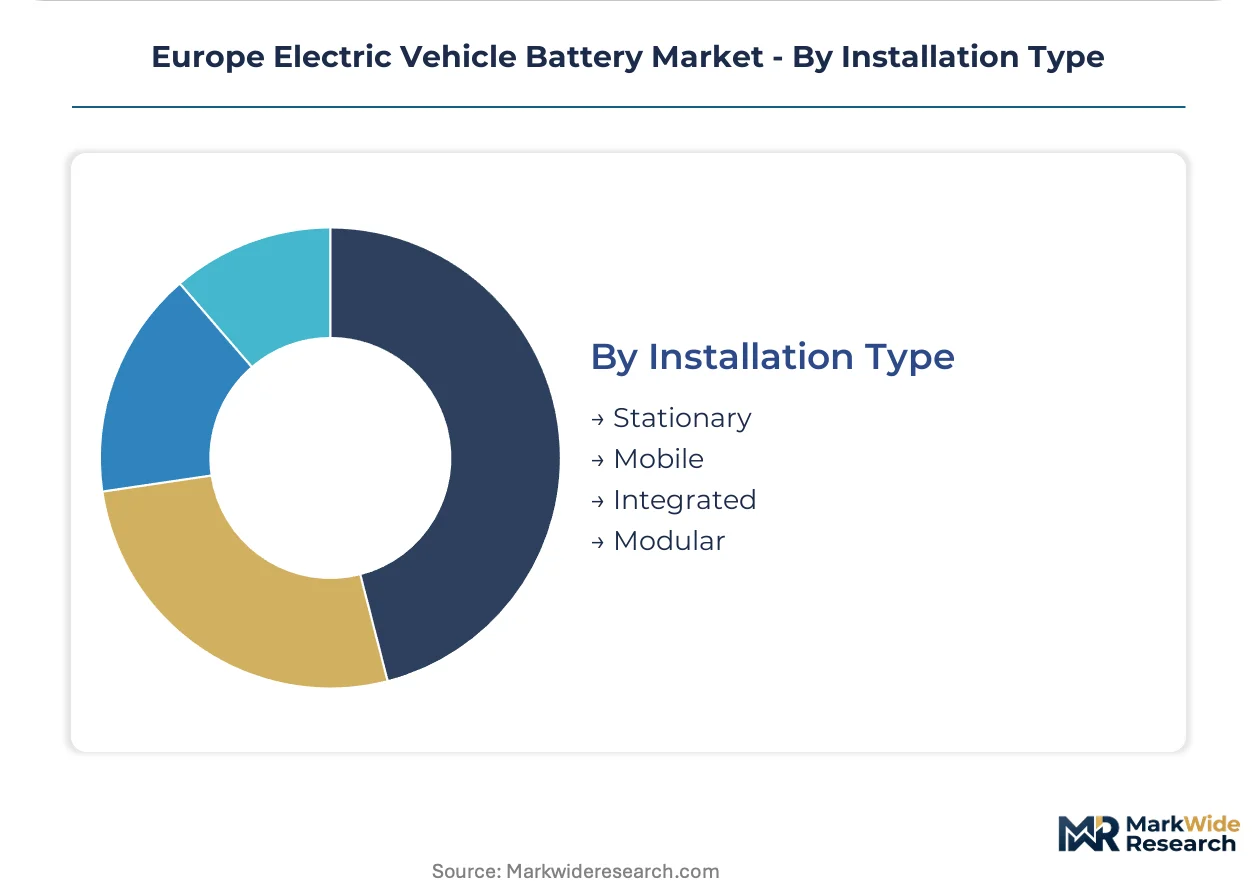
- Stationary:Grid-connected storage systems at charging hubs are absorbing second-life automotive batteries, with EMA-aligned safety protocols extending validation timelines for these repurposed installations.
- Mobile:Swappable battery stations for two-wheeler fleets are concentrating in Paris and Barcelona urban cores, requiring standardized form factors across competing vehicle brands.
- Integrated:Structural battery packs welded directly into vehicle chassis are eliminating separate enclosure mass, with German OEMs leading this architectural transition.
- Modular:Serviceable cell modules with standardized interfaces are retaining presence in commercial vehicle segments where field replacement minimizes downtime costs.
Integrated installations lead new vehicle platforms today; modular designs are gaining share fastest in commercial segments prioritizing serviceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting gigafactory investments toward jurisdictions with streamlined permitting and renewable energy access. Poland and Hungary attract capital through faster environmental approvals than Germany or France, compressing project timelines by 12-18 months despite weaker domestic demand bases.
Germany
CATL's Erfurt plant and Tesla's Berlin-Brandenburg complex anchor European cell capacity. The KBA enforces EMA-aligned safety protocols that extend validation cycles for new chemistries. North Rhine-Westphalia hosts precursor material refiners supplying cathode active material to domestic assemblers.
Poland
LG Energy Solution's Wrocław facility and SK On's planned investment leverage EU cohesion funds for greenfield development. The national climate ministry accelerates permitting for renewable-powered industrial zones. Lower Silesia concentrates cathode precursor production serving German OEM supply chains.
Hungary
CATL's Debrecen megafactory represents the largest Chinese battery investment in Europe. The government offers tax holidays for strategic manufacturing projects under its investment promotion framework. Eastern Hungary is emerging as a cell-to-pack integration hub for premium German electric platforms.
France
Automotive Cells Company anchors domestic production through its Douai and Billy-Berclau plants. The national industrial strategy channels state aid toward gigafactory construction under EU Green Deal alignment. Hauts-de-France hosts cathode material joint ventures with Korean precursor suppliers.
Sweden
Northvolt's Skellefteå facility pioneers fossil-free cell production using hydropower. The Swedish Energy Agency funds pilot lines for sodium-ion chemistry development. Västerbotten County concentrates recycling infrastructure for second-life battery applications.
Europe Electric Vehicle Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cell producers assuming integration roles previously held by tier-two module assemblers. The vendor base concentrates around cylindrical and prismatic format expertise, with pouch configurations retaining niche presence in French and Italian OEM portfolios. Three archetypes dominate: Korean specialists with cylindrical IP, Chinese scale players with integrated precursor supply, and European joint ventures with state-backed offtake guarantees. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure renewable energy contracts and cathode material offtake.
Within the Korean specialist tier, SK On and Samsung SDI exemplify technology-led positioning through cylindrical cell architectures and solid-state R&D pipelines. CATL anchors the Chinese scale archetype with Hungarian manufacturing presence and integrated upstream control over precursor refining. LG Energy Solution occupies a hybrid position, combining Korean technology origins with Polish manufacturing scale and European customer proximity.
| Leading Market Players |
|---|
| SK On |
| Samsung SDI |
| CATL |
| Gotion High-Tech |
| EVE Energy |
| BYD |
| Panasonic |
| Automotive Cells Company (ACC) |
| LG Energy Solution |
| Others |
Supply & Pricing Matrix
Cathode chemistry certification tiers split European cell procurement into parallel tracks, with EU Green Deal carbon declarations commanding premium positioning while uncertified Asian imports face margin compression at logistics-dependent pricing. This bifurcation concentrates procurement power among German and French OEMs with verified supply chains while forcing price-sensitive fleet operators toward longer-dated contracts with emerging Polish and Hungarian producers.
Pricing Analysis
Distributor margins for cathode active materials absorb 8-12 percentage points before cell assembly, compressing further for direct-to-OEM volume agreements. Three-tier pricing structure across premium, standard, and economy levels separates nickel-rich NMC cells with full EU carbon certification from LFP alternatives with partial traceability and uncertified imports. Pricing pressure stems from lithium carbonate spot volatility originating in Chilean and Argentine brine operations. Commercial vehicle fleet operators exhibit highest price sensitivity, while German premium OEMs prioritize energy density over unit economics.
Supply Chain Analysis
EMA-aligned safety certification gates access to German and French OEM supply chains, extending qualification timelines for non-compliant precursor suppliers. Cathode active material refining concentrates in China, South Korea, and Indonesia, with European gigafactories drawing from these hubs for nickel-manganese-cobalt formulations. Raw material dependencies span lithium carbonate from South American brine, cobalt from DRC artisanal and industrial mines, and nickel from Indonesian laterite operations. Single-source vulnerability runs through Chinese precursor refiners controlling 70%+ of global NMC output. Distribution runs through Rotterdam and Hamburg port clusters for bulk chemical intake, with just-in-time delivery to Polish and German cell plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture adoption and cathode chemistry standardization are compressing manufacturing costs while enabling premium-tier positioning through carbon-certified supply chains. This margin-expansion dynamic favors producers with captive precursor access and renewable-powered production footprints.
For Market Incumbents: Acquire stranded precursor refining assets in Eastern Europe to secure EU Green Deal-compliant supply chains before competitor lock-in. CATL and LG Energy Solution must defend module integration revenues against cell producers assuming direct pack assembly responsibilities previously held by tier-two suppliers. Capacity addition in Poland and Hungary offers geographic hedge against German permitting delays.
For New Entrants and Emerging Players: Capture battery-as-a-service contract structures in Nordic commercial fleet markets where capital purchase is already displacing toward per-kilometer models. Sodium-ion chemistry for stationary storage applications represents the most penetrable white-space segment, with lower performance requirements easing qualification barriers. Partner with charging station providers for second-life cell offtake agreements under circular economy mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where EMA-aligned safety certification timelines exceed 18 months and capital intensity deters standalone entrants. Five-to-ten year viability hinges on securing renewable energy contracts and cathode material offtake at prices below spot market volatility. Target acquisition archetype: mid-scale Polish or Hungarian cell producers with existing OEM qualification and expansion-ready greenfield permits. Signal to watch: F-Gas Regulation enforcement actions against electrolyte solvent imports disrupting local production scale-up.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Secures EU Green Deal carbon certification timelines for German OEM supply agreements. |
| Cell-to-Pack Manufacturing Transition | Eliminates module assembler margins while capturing structural pack integration revenues. |
| Battery-as-a-Service Platform Launch | Restructures Nordic fleet procurement from capital purchase toward usage-based contracting. |
| Solid-State Chemistry R&D Partnership | Positions Samsung SDI and SK On for premium passenger segment energy density leadership. |
| Second-Life Circular Economy Infrastructure | Creates revenue streams from retired automotive cells under EU battery passport mandates. |
Research Methodology
Direct dialogue with gigafactory process engineers, cathode material procurement leads at German OEMs, EMA regulatory affairs specialists, and Nordic fleet operations managers grounded qualitative findings in operational reality. Secondary validation drew from EU Green Deal implementation reports, F-Gas Regulation enforcement databases, ECHA substance registration filings, and national climate ministry permitting records. Bottom-up cell capacity buildouts across Poland, Germany, Hungary, and France were triangulated against top-down OEM platform production schedules.
Segment-level projections across battery type, application, and end user were generated through integrated modeling of cathode chemistry adoption curves, commercial fleet electrification timelines, and regulatory compliance cost burdens over the projection horizon. CAGRs reflect compounding effects of lithium carbonate price normalization, cell-to-pack cost reduction, and battery-as-a-service penetration in logistics markets. Key inputs included OEM platform launch schedules, EU cohesion fund disbursement timelines for gigafactory construction, and EMA-aligned safety protocol implementation rates.
Underlying measurement precision varies by segment; passenger car and commercial vehicle applications carry tighter precision than two-wheeler and e-bike categories due to more consolidated OEM reporting. Forecasts reflect assumptions around F-Gas Regulation enforcement intensity, EU Green Deal carbon border adjustment implementation, and South American lithium supply expansion. A model refresh is warranted upon material change in cathode active material trade policy or solid-state chemistry commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
EV Battery Cells Market
EV Batteries
European EV Battery Systems Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Auto Storage Battery Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market