
 Europe Electric Vehicle VRLA Batteries Market | 2026-2036
Europe Electric Vehicle VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle VRLA Batteries Market Insights
The transition from flooded to absorbed glass mat architectures is fragmenting established supply relationships across the European VRLA value chain. EnerSys leverages its pan-European distribution footprint to sustain service-level agreements with commercial vehicle OEMs. Exide Technologies anchors its competitive stance through backward integration into lead smelting and recycling operations. HOPPECKE Batterien GmbH & Co. KG differentiates via specialized traction battery configurations for material-handling electric vehicles.
Europe electric vehicle VRLA batteries are rechargeable lead-acid cells employing valve-regulated gas recombination, typically manufactured with calcium-tin alloy grids and sulfuric acid electrolyte immobilized in fiberglass separators or silica gel matrices, designed to deliver cyclic durability for auxiliary power, starter lighting ignition backup, and regenerative energy absorption in electrified vehicle platforms. AGM configurations dominate current procurement volumes due to superior vibration resistance and faster charge acceptance relative to gel or flooded alternatives. The electric drive application segment captures concentrated engineering investment as OEMs seek VRLA solutions for 48-volt mild-hybrid architectures, while energy storage deployments for electric bus depot charging represent the fastest-expanding end-use trajectory.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that ECHA monitors through REACH substance restrictions on lead compounds, compelling manufacturers to requalify supply chains or forfeit CE-marked market access. Germany's KBA enforces UN ECE R100 type approval for battery systems installed in electric vehicles, adding compliance layers distinct from stationary industrial applications. Stakeholders must track how delegated acts under the EU Battery Regulation define performance and durability criteria before committing capital to next-generation VRLA platform development.
Market Dynamics
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are forcing VRLA manufacturers to requalify supply chains or lose CE-marked market access, compressing lead-acid battery economics across Germany, France, and Italy's electrified vehicle corridors.
Growth Catalysts
- EU Battery Regulation mandates:Recycled lead content thresholds and carbon footprint declarations are compelling fleet operators to source compliant VRLA systems for auxiliary power in electric commercial vehicles.
- Material-handling electrification:Warehouse automation across Germany's industrial corridor is driving procurement of specialized traction battery configurations for electric forklifts and AGVs.
- 48-volt mild-hybrid architectures:Automakers in France and Italy are engineering VRLA solutions for regenerative energy absorption and starter lighting ignition backup systems.
Market Restraints
- Lead price volatility:ECHA REACH restrictions on lead compound processing are elevating smelting compliance costs and compressing cell manufacturer margins.
- Lithium-ion substitution threat:Declining lithium iron phosphate pack costs are displacing VRLA in energy-intensive electric bus depot charging applications.
- Technical energy density ceiling:Absorbed glass mat chemistry cannot match lithium-ion gravimetric performance for extended-range electric drive applications.
Strategic Opportunities
- Italian aftermarket channel consolidation:Independent service networks for commercial vehicle battery replacement remain fragmented, creating white space for certified distributor partnerships.
- F-Gas Regulation retrofit demand:Cold-chain logistics operators across France must upgrade auxiliary power systems to meet refrigerant phase-down timelines.
- AGM-gel hybrid architectures:Convergence of fiberglass separator and silica gel immobilization technologies is enabling next-generation cyclic durability for stop-start systems.
Industry Challenges
- UN ECE R100 certification timelines:Germany's KBA type approval process for electric vehicle battery systems adds 8-14 months to product launch schedules versus stationary industrial applications.
- Lead smelter workforce scarcity:Qualified metallurgical engineers and environmental compliance specialists are concentrating at legacy recycling facilities, constraining plant modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle VRLA Batteries Market |
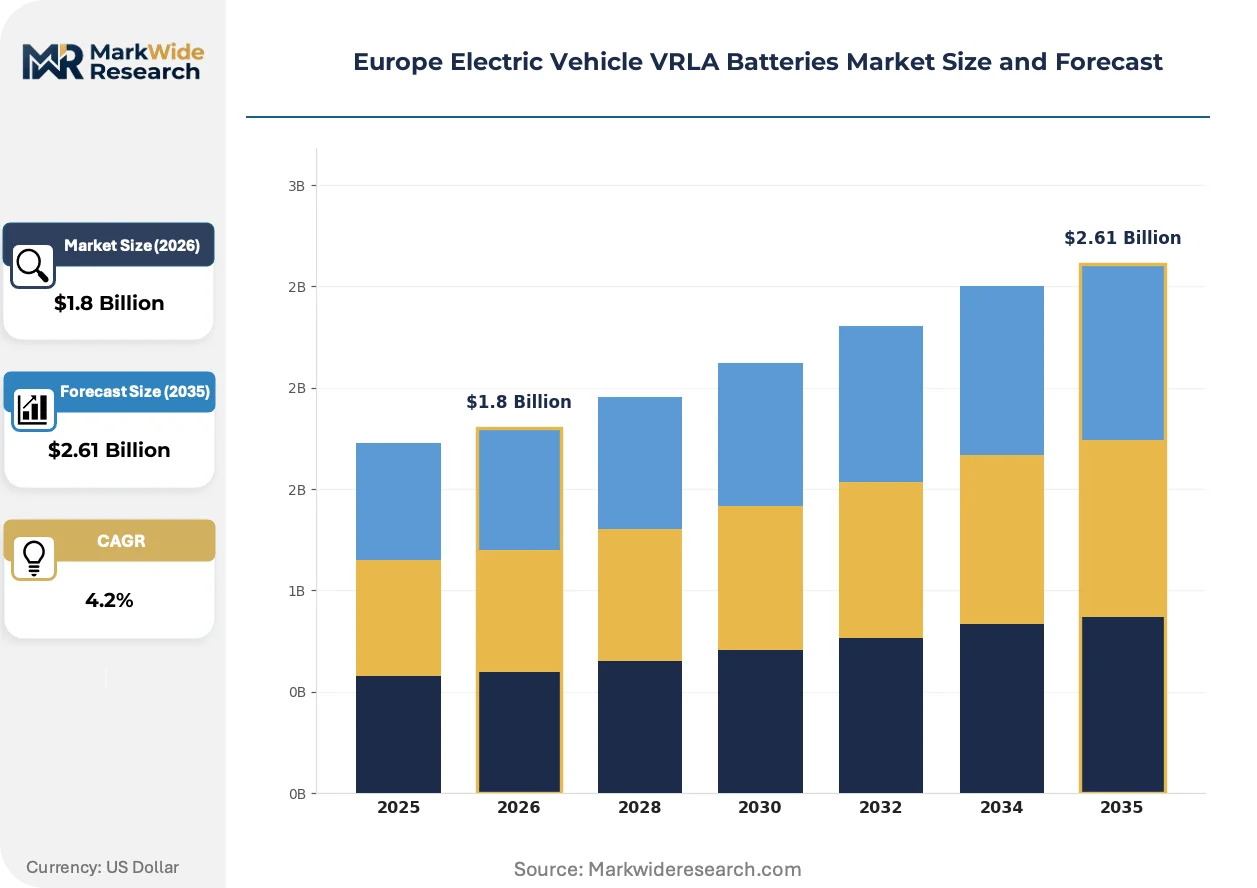
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AGM, Gel, Flooded, Sealed End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: Lead-Acid, Lithium-Ion, Nickel-Hydride, Carbon-Based Application: Energy Storage, Backup Power, Electric Drive, Regenerative Braking |
| Companies Covered | FIAMM Energy Technology S.p.A., EnerSys, Exide Technologies, Saft Groupe S.A., HOPPECKE Batterien GmbH & Co. KG, Clarios, GS Yuasa International, C&D Technologies, East Penn Manufacturing Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle VRLA Batteries Market Trends and Innovations
Valve-regulated lead-acid architectures are undergoing material and process reinvention as EU environmental mandates tighten and electrified vehicle platforms demand higher cyclic durability from auxiliary power systems.
Battery management system integration is digitizing VRLA performance monitoring across commercial vehicle fleets. Telematics providers are embedding cell voltage and temperature sensors into AGM packs for predictive maintenance contracts. This capability is digitizing aftermarket service models and compressing warranty claim cycles for fleet operators.
REACH substance restrictions on lead compounds are forcing manufacturers to requalify calcium-tin alloy grid suppliers. ECHA monitoring of smelter emissions is accelerating closed-loop recycling investments. The F-Gas Regulation's refrigerant phase-down is most affecting cold-chain logistics auxiliary power procurement in France and Germany.
Fleet procurement departments are consolidating VRLA sourcing through long-term service agreements rather than spot purchasing. Tier-one suppliers are displacing fragmented distributor networks with direct OEM partnerships. This concentration is most visible in Germany's automotive industrial corridor where automakers coordinate localized cell sourcing with certified recyclers.
Europe Electric Vehicle VRLA Batteries Market Segmentation
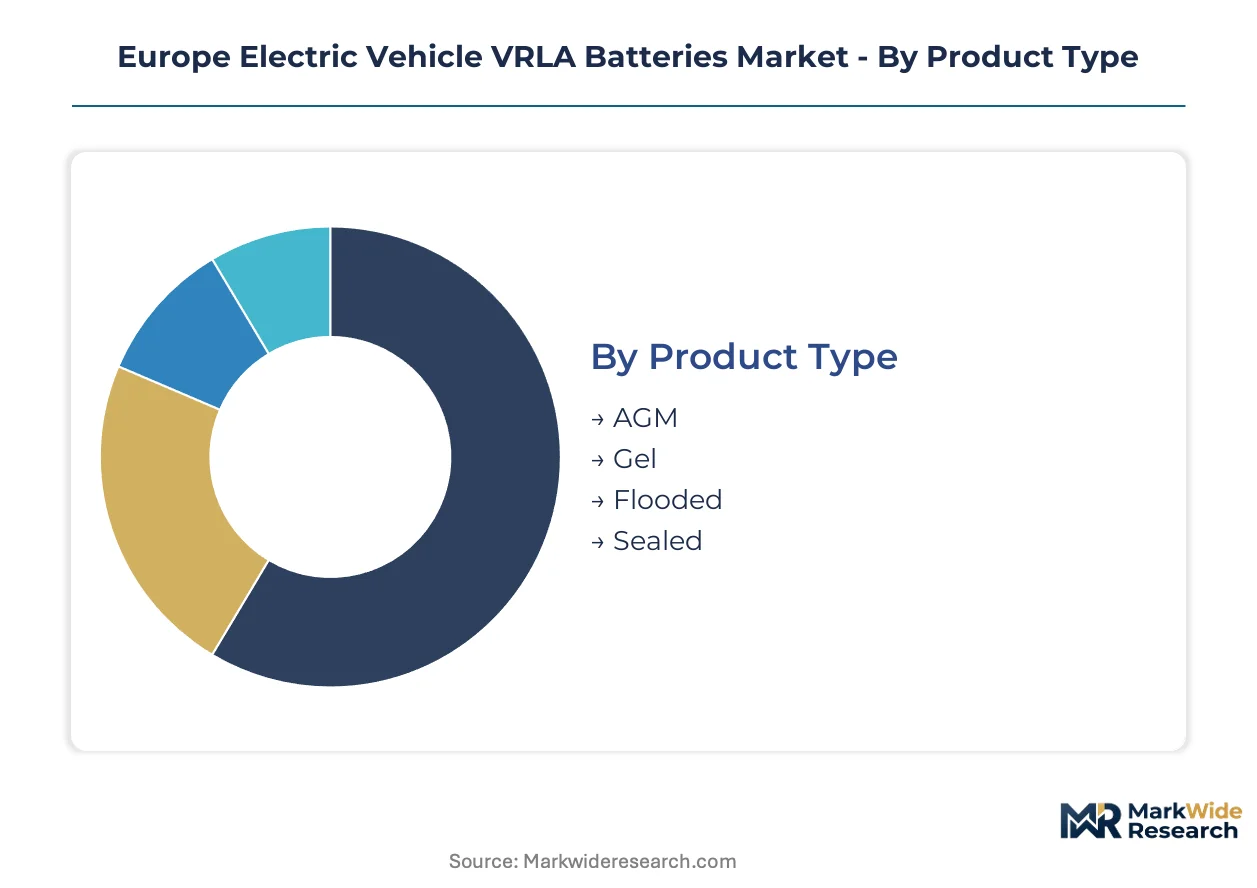
Segmentation in the Europe Electric Vehicle VRLA Batteries Market reveals how regulatory pressure and electrification patterns concentrate procurement across distinct technical configurations. Understanding these divisions exposes where EU Battery Regulation compliance costs and 48-volt mild-hybrid engineering investments reshape supplier economics.
Product Type:
Cost tier positioning determines which VRLA architectures capture fleet procurement volumes versus aftermarket replacement cycles.
- AGM:Absorbed glass mat configurations employ fiberglass separators to immobilize sulfuric acid electrolyte, delivering superior vibration resistance for commercial vehicle auxiliary power systems. Demand concentrates across Germany's automotive industrial corridor where OEMs specify AGM for starter lighting ignition backup in electrified platforms.
- Gel:Silica gel matrices immobilize electrolyte for deep-cycle durability, suiting material-handling electric vehicles in warehouse automation deployments. Italian logistics operators favor gel configurations for forklift traction batteries where charge acceptance speed matters less than cycle life.
- Flooded:Conventional liquid electrolyte designs persist in price-sensitive aftermarket channels across Eastern Europe.
- Sealed:Maintenance-free constructions serve two-wheeler electrification in France's urban mobility schemes.
AGM commands the established base. The steepest expansion runs through gel configurations for material-handling electrification.
End User:
Application intensity separates high-cyclic auxiliary power demand from intermittent backup requirements across vehicle electrification tiers.
- Commercial Vehicles:Fleet operators across Germany, France, and Italy procure VRLA systems for auxiliary power in electric vans and trucks, driven by EU Battery Regulation recycled content mandates and carbon footprint declaration requirements. Cold-chain logistics in France particularly drive procurement for refrigerant phase-down compliance under the F-Gas Regulation.
- Buses:Electric bus depot charging infrastructure represents the most energy-intensive VRLA deployment, with energy storage configurations absorbing regenerative braking energy and supporting overnight fleet charging. German municipal operators anchor this segment through coordinated procurement with certified lead recyclers.
- Passenger Vehicles:48-volt mild-hybrid architectures specify VRLA for regenerative energy absorption and SLI backup.
- Two-Wheelers:Urban mobility electrification in Italian and French cities drives compact VRLA procurement for e-scooters and e-mopeds.
Commercial vehicles anchor procurement volumes. Bus depot energy storage is gaining share fastest as electrification accelerates municipal fleet transitions.
Technology:
Material chemistry choices reflect the tension between established lead-acid economics and lithium-ion substitution pressure across electrified vehicle platforms.
- Lead-Acid:Valve-regulated lead-acid chemistry with calcium-tin alloy grids dominates current VRLA procurement for auxiliary power and backup applications, constrained by ECHA REACH restrictions on lead compound processing that elevate smelter compliance costs. Germany's KBA enforces UN ECE R100 type approval specifically for these systems in electric vehicles.
- Lithium-Ion:Lithium iron phosphate packs are displacing VRLA in energy-intensive electric bus depot charging where gravimetric energy density determines system feasibility.
- Nickel-Hydride:Legacy hybrid architectures in French and Italian passenger vehicles retain limited nickel-metal hydride presence.
- Carbon-Based:Experimental lead-carbon hybrid configurations target enhanced cyclic durability for stop-start systems.
Lead-acid retains the installed base. Lithium-ion is climbing fastest in bus depot applications where energy density requirements exceed VRLA technical ceilings.
Application:
Functional role within electrified vehicle architectures determines whether VRLA serves primary propulsion support or peripheral power management.
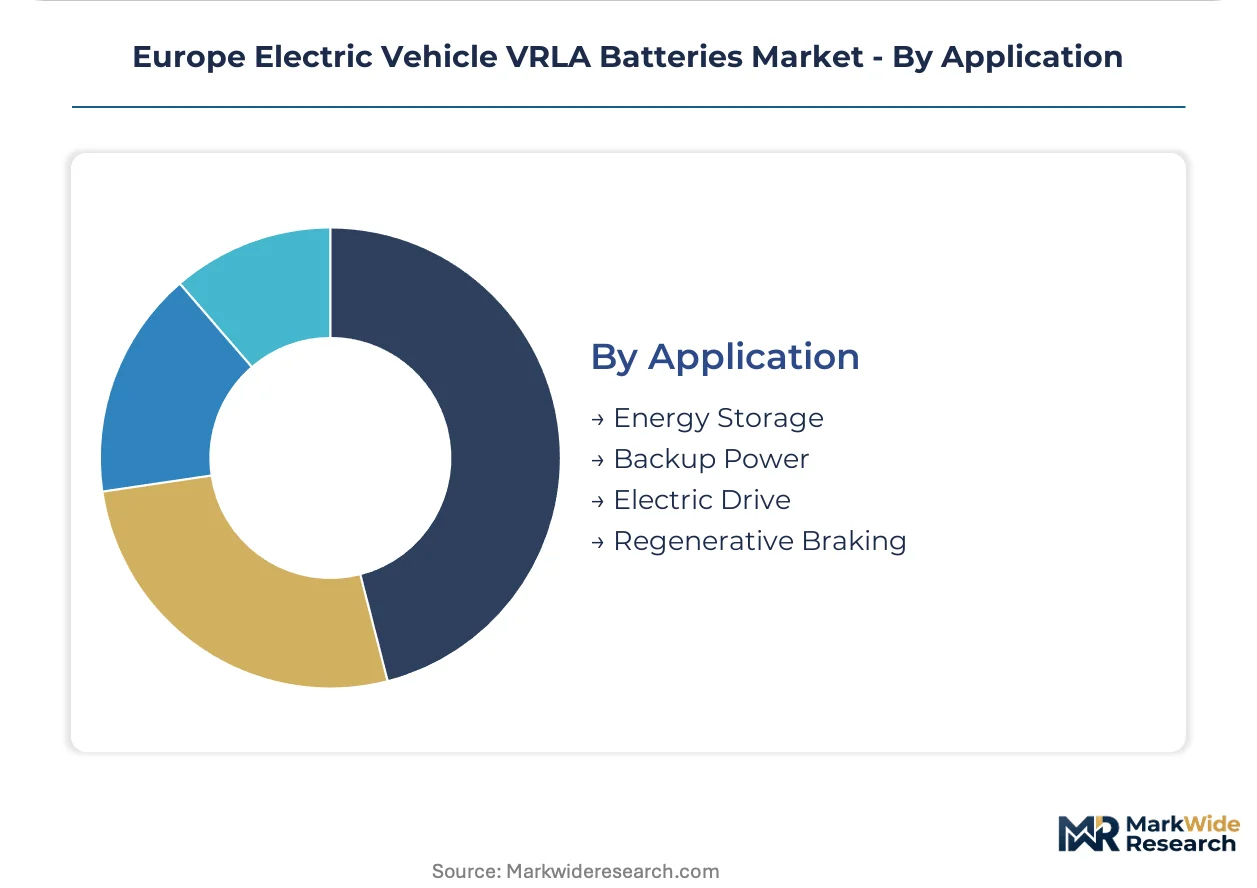
- Electric Drive:48-volt mild-hybrid systems employ VRLA for torque assist and regenerative energy absorption, with German automakers engineering specialized AGM configurations for this emerging duty cycle. The EU Battery Regulation's performance and durability criteria, once defined in delegated acts, will requalify which designs maintain CE-marked access.
- Energy Storage:Depot charging infrastructure for electric bus fleets requires high-capacity VRLA banks to buffer grid demand and store regenerative braking energy, representing the most technically demanding application as lithium-ion costs decline.
- Backup Power:Starter lighting ignition backup systems in commercial vehicles specify VRLA for reliability in auxiliary electrical architectures.
- Regenerative Braking:Energy absorption during deceleration subjects VRLA to high-rate partial state-of-charge cycling.
Backup power retains the largest installed presence. Energy storage for bus depot charging is expanding most quickly as municipal electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments concentrate VRLA sourcing decisions across Germany's automotive corridor, France's cold-chain logistics networks, and Italy's material-handling zones. Each geography exhibits distinct regulatory exposure and buyer archetype composition.
Germany
Commercial vehicle OEMs and tier-one suppliers coordinate localized cell sourcing for 48-volt mild-hybrid architectures. KBA enforces UN ECE R100 type approval for electric vehicle battery systems, adding 8-14 months to product launch schedules. Stuttgart and Wolfsburg anchor engineering investment in AGM configurations for regenerative energy absorption.
France
Cold-chain logistics operators upgrade auxiliary power systems to meet F-Gas Regulation refrigerant phase-down timelines. ECHA REACH restrictions on lead compound processing elevate smelter compliance costs for manufacturers serving this segment. Lyon and Paris metropolitan zones drive procurement of sealed VRLA for urban delivery electrification.
Italy
Warehouse automation across Lombardy and Emilia-Romagna drives procurement of specialized traction battery configurations for electric forklifts. Independent service networks for commercial vehicle battery replacement remain fragmented, creating white space for certified distributor partnerships. Gel configurations dominate material-handling applications where cycle life outweighs charge speed.
United Kingdom
Bus depot charging infrastructure for municipal fleet electrification requires high-capacity VRLA banks to buffer grid demand. CSRD reporting requirements extend carbon footprint declaration obligations to public transport operators. Midlands industrial zones concentrate lead-acid recycling investments to secure compliant material supply.
Poland
Price-sensitive aftermarket channels retain flooded VRLA configurations for Eastern European commercial vehicle replacement cycles. EU Battery Regulation recycled content thresholds apply equally, forcing requalification of supply chains serving this value tier. Silesian manufacturing clusters absorb modernization investments from Western European battery producers seeking cost-advantaged production.
Europe Electric Vehicle VRLA Batteries Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure consolidating around pan-European distribution footprints and backward integration into lead smelting. The vendor base separates into three strategic archetypes: integrated manufacturers with captive recycling, regional specialists in traction configurations, and distributors with fleet service-level agreements. Dominant competitive moves include M&A to secure certified recycling capacity and strategic partnerships with commercial vehicle OEMs for 48-volt platform co-development.
Among Germany-based fabricators, HOPPECKE Batterien GmbH & Co. KG occupies a position exemplifying specialized traction battery expertise for material-handling applications. EnerSys represents the channel-controlling archetype through its pan-European distribution infrastructure. Exide Technologies anchors the integrated manufacturer tier through its backward integration into lead smelting and recycling operations.
| Leading Market Players |
|---|
| FIAMM Energy Technology S.p.A. |
| EnerSys |
| Exide Technologies |
| Saft Groupe S.A. |
| HOPPECKE Batterien GmbH & Co. KG |
| Clarios |
| GS Yuasa International |
| C&D Technologies |
| East Penn Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH restrictions on lead compound processing constitute the dominant risk vector compressing VRLA battery economics across Europe, simultaneously widening price spreads between certified premium tiers and uncertified economy alternatives while forcing supply chain reconfiguration toward backward-integrated recyclers. Fleet procurement departments now weight total cost of ownership calculations heavily toward carbon footprint declaration compliance, effectively decoupling pricing power from raw material cost advantages alone.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lead prices dominate procurement agreements between commercial vehicle OEMs and cell manufacturers, with quarterly adjustment clauses protecting margin structures against ECHA-mandated smelter compliance cost escalation. Three-tier pricing structure across premium, standard, and economy levels separates AGM configurations certified for UN ECE R100 type approval from uncertified gel alternatives serving aftermarket channels. Cost compression in economy tiers is intensifying because Polish and Eastern European flooded battery producers face identical EU Battery Regulation recycled content thresholds without scale advantages. Fleet operators in Germany's automotive corridor exhibit least price sensitivity due to co-development partnerships with tier-one suppliers, while independent Italian service networks remain most exposed to spot purchasing volatility.
Supply Chain Analysis
Secondary lead feedstock from Germany, France, and Poland's recycling infrastructure anchors European VRLA cell production, with calcium-tin alloy grid manufacturing concentrated in German industrial clusters and separator materials sourced from specialized fiberglass producers. Raw material dependencies center on refined lead ingots, sulfuric acid electrolyte, and silica gel matrices for deep-cycle configurations. Single-source vulnerability runs through certified lead smelters qualified under ECHA emissions monitoring, where qualified metallurgical engineers and environmental compliance specialists concentrate at legacy facilities constraining plant modernization timelines. Distribution runs through pan-European logistics networks coordinated from Stuttgart and Wolfsburg, with direct OEM partnerships displacing fragmented distributor networks across Germany's electrified vehicle corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across Germany, France, and Italy has shifted negotiating power toward buyer coalitions, compressing supplier margins and favoring manufacturers with captive recycling capacity and long-term service agreement structures.
For Market Incumbents: Pre-empt lithium-ion substitution in bus depot energy storage by accelerating AGM-gel hybrid architecture R&D for enhanced cyclic durability in stop-start systems. Secure KBA UN ECE R100 type approval pipelines ahead of delegated acts defining EU Battery Regulation performance criteria, locking in 8-14 month certification advantages over competitors forced into requalification cycles.
For New Entrants and Emerging Players: Italy's fragmented independent service networks for commercial vehicle battery replacement offer the most penetrable geographic entry point, with certified distributor partnerships representing the fastest channel to fleet procurement visibility. Target gel configuration specialization for Lombardy warehouse automation deployments where cycle life requirements exceed charge speed priorities, bypassing established AGM supply relationships.
For Investors and Strategic Acquirers: Mid-cap recyclers with ECHA-compliant smelter infrastructure and KBA certification relationships present the highest-conviction acquisition target archetype for exposure to EU Battery Regulation compliance premiums. Monitor delegated act publication timelines for EU Battery Regulation performance and durability criteria as the critical inflection signal determining which VRLA architectures maintain CE-marked market access versus forced obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Recycling | Captures ECHA compliance premiums and secures recycled content thresholds under EU Battery Regulation mandates. |
| AGM-Gel Hybrid Architecture Development | Addresses 48-volt mild-hybrid cyclic durability requirements exceeding conventional separator capabilities. |
| KBA Certification Pipeline Expansion | Compresses UN ECE R100 type approval timelines relative to competitors facing 8-14 month delays. |
| Direct OEM Partnership Structuring | Displaces fragmented distributor networks across Germany's automotive industrial corridor. |
| Telematics-Enabled Battery Management Integration | Digitizes aftermarket service models through predictive maintenance contracts with fleet operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, commercial vehicle OEM platform engineers, tier-one supplier battery specialists, and certified lead recycler operations managers. Secondary validation drew from KBA type approval registries, ECHA REACH substance restriction filings, EU Battery Regulation delegated act progress tracking, and commercial vehicle production databases. Bottom-up cell shipment estimates by country and application were triangulated against top-down market value reconstructions from pan-European distributor revenue disclosures.
Calibration against historical price realization data and documented procurement contract structures anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed product type architecture, end-use vehicle class, technology chemistry, and application functional role within electrified platforms. CAGRs were derived from regression analysis of fleet electrification penetration curves and regulatory compliance cost trajectories, incorporating lead price volatility scenarios and lithium-ion substitution elasticity parameters specific to auxiliary power versus energy storage use cases.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese lithium iron phosphate producers or accelerated F-Gas Regulation refrigerant phase-down timelines would shift outcomes materially from projected VRLA demand trajectories. Cross-checking against IEA electric bus deployment forecasts and ACEA commercial vehicle registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market