
 South America Electric Vehicle VRLA Batteries Market | 2026-2036
South America Electric Vehicle VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle VRLA Batteries Market Insights
Software-defined battery management is broadening what suppliers monetize beyond hardware sales. Clarios leverages its service network across Brazilian industrial corridors to capture recurring maintenance contracts. EnerSys anchors its position through deep integration with regional fleet charging infrastructure. Moura Accumulators dominates local assembly operations, exploiting Brazil's Rota 2030 local content thresholds to control domestic sourcing channels.
South America Electric Vehicle VRLA Batteries are rechargeable lead-acid cells using immobilized electrolyte—either absorbed in fiberglass mats (AGM) or gelled with silica additives—delivering 12-48V nominal outputs with 200-800 cold cranking amperes for auxiliary power and low-speed traction applications. Their primary purpose is supplying cost-effective, recyclable energy storage for electric vehicles operating on short-range urban duty cycles where lithium-ion cost premiums prove prohibitive. Absorbent Glass Mat variants lead volume shipments due to superior vibration resistance on deteriorating regional road infrastructure, while Gel configurations capture margin pools in tropical climates where elevated temperatures accelerate standard flooded cell degradation. The Aftermarket Providers channel is expanding fastest as aging first-generation electric bus fleets in São Paulo and Santiago enter replacement cycles.
Brazil's INMETRO certification mandates and Argentina's IRAM safety standards govern cell construction, charge acceptance, and recycling chain accountability across the regional value chain. ANVISA's overlapping chemical substance controls and Chile's Ministry of Environment extended producer responsibility frameworks add compliance layers that favor suppliers with established reverse-logistics networks. Stakeholders must weigh local assembly commitments against import tariff exposure as Mercosur trade negotiations evolve and national industrial policies diverge on battery value chain localization requirements.
Market Dynamics
Brazil's PROCONVE emission standards and Rota 2030 local content mandates are forcing battery suppliers to reconfigure assembly footprints across the southeastern manufacturing corridor, compressing procurement timelines for fleet electrification contracts.
Growth Catalysts
- Urban Bus Electrification Mandates:São Paulo's municipal fleet decarbonization targets are generating replacement demand for auxiliary power systems in electric bus platforms, favoring VRLA configurations for cost-sensitive operators.
- PROCONVE P-8 Standards:Brazil's tightening commercial vehicle emission thresholds are accelerating diesel-to-electric conversions in light commercial vehicle segments where VRLA batteries serve as bridge storage solutions.
- Reverse-Logistics Infrastructure:Established lead-acid recycling networks across Minas Gerais and São Paulo states are lowering total lifecycle costs versus lithium-ion alternatives for short-range duty cycles.
Market Restraints
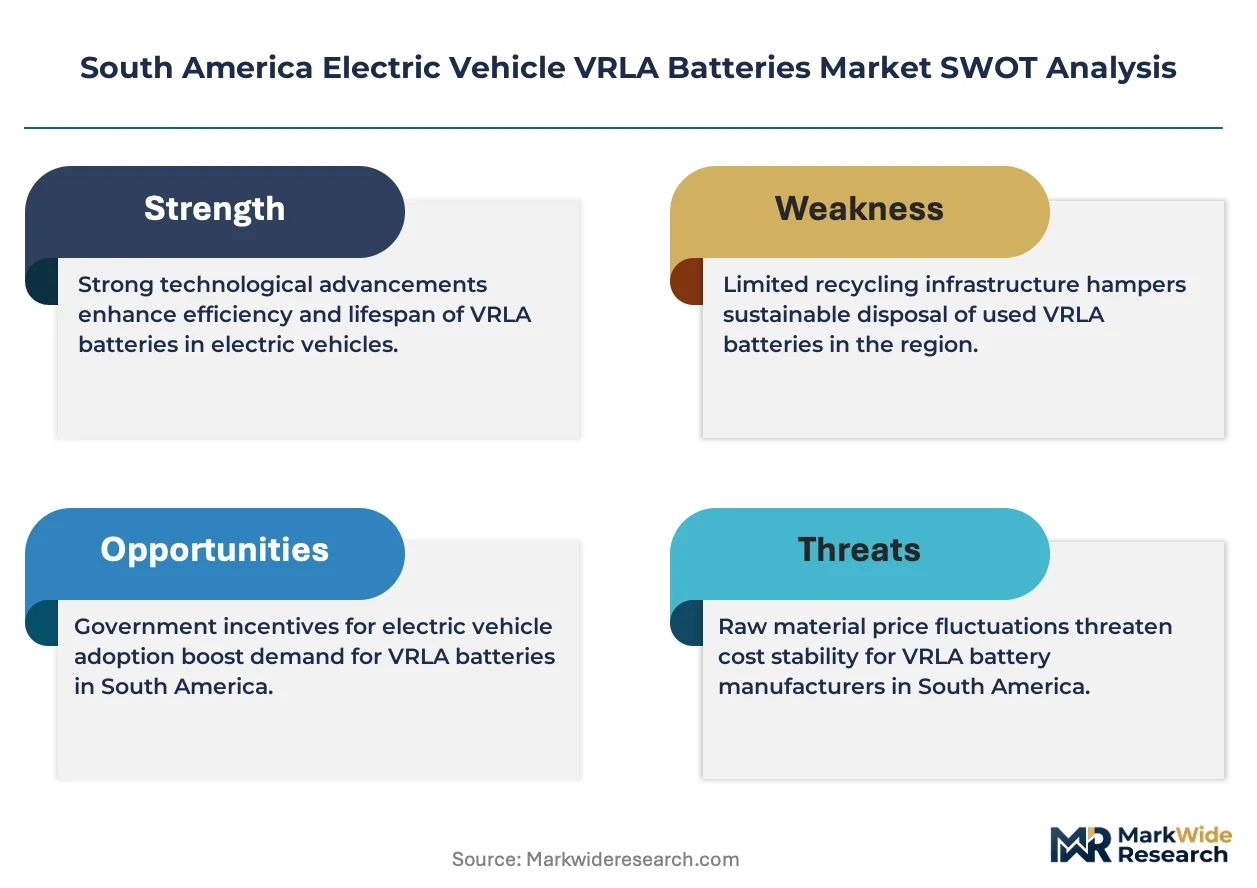
- Lead Price Volatility:Fluctuations in global lead ingot markets directly compress margin pools for VRLA cell assemblers operating on fixed-price municipal contracts.
- Import Tariff Exposure:Mercosur trade negotiation uncertainties create procurement risk for Brazilian manufacturers dependent on separator materials and silica gel inputs from Argentine suppliers.
- Lithium-Ion Cost Compression:Declining lithium iron phosphate pack pricing in Chinese export markets is narrowing the total-cost-of-ownership gap for urban fleet operators evaluating chemistry options.
Strategic Opportunities
- Argentine Fleet Retrofit Programs:Buenos Aires provincial transport authorities are launching second-wave electric bus tenders with localized assembly requirements favoring regional VRLA suppliers.
- Chilean Mining Electrification:Underground light vehicle mandates in Chilean copper operations are creating demand for explosion-proof gel cell configurations in hazardous environment applications.
- Aftermarket Service Unbundling:Aging first-generation electric bus fleets in Santiago and São Paulo are entering replacement cycles, opening recurring revenue streams for cell replacement and capacity testing services.
Industry Challenges
- INMETRO Certification Timelines:Extended approval windows for new cell form factors are delaying product launches and compressing commercialization windows for platform-specific designs.
- Technical Workforce Scarcity:Shortages of technicians trained in valve-regulated lead-acid diagnostics and electrolyte immobilization processes are constraining service network expansion in secondary Brazilian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle VRLA Batteries Market |
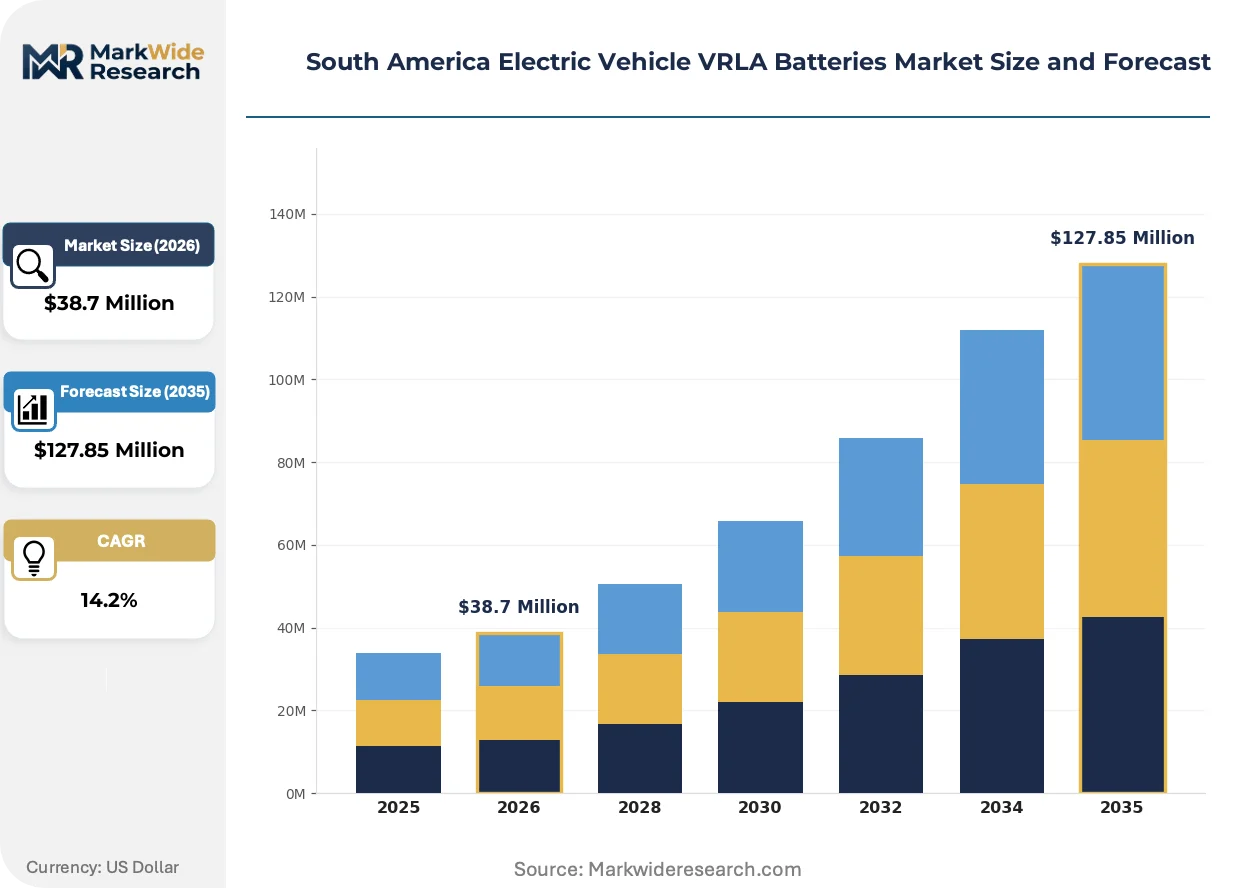
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
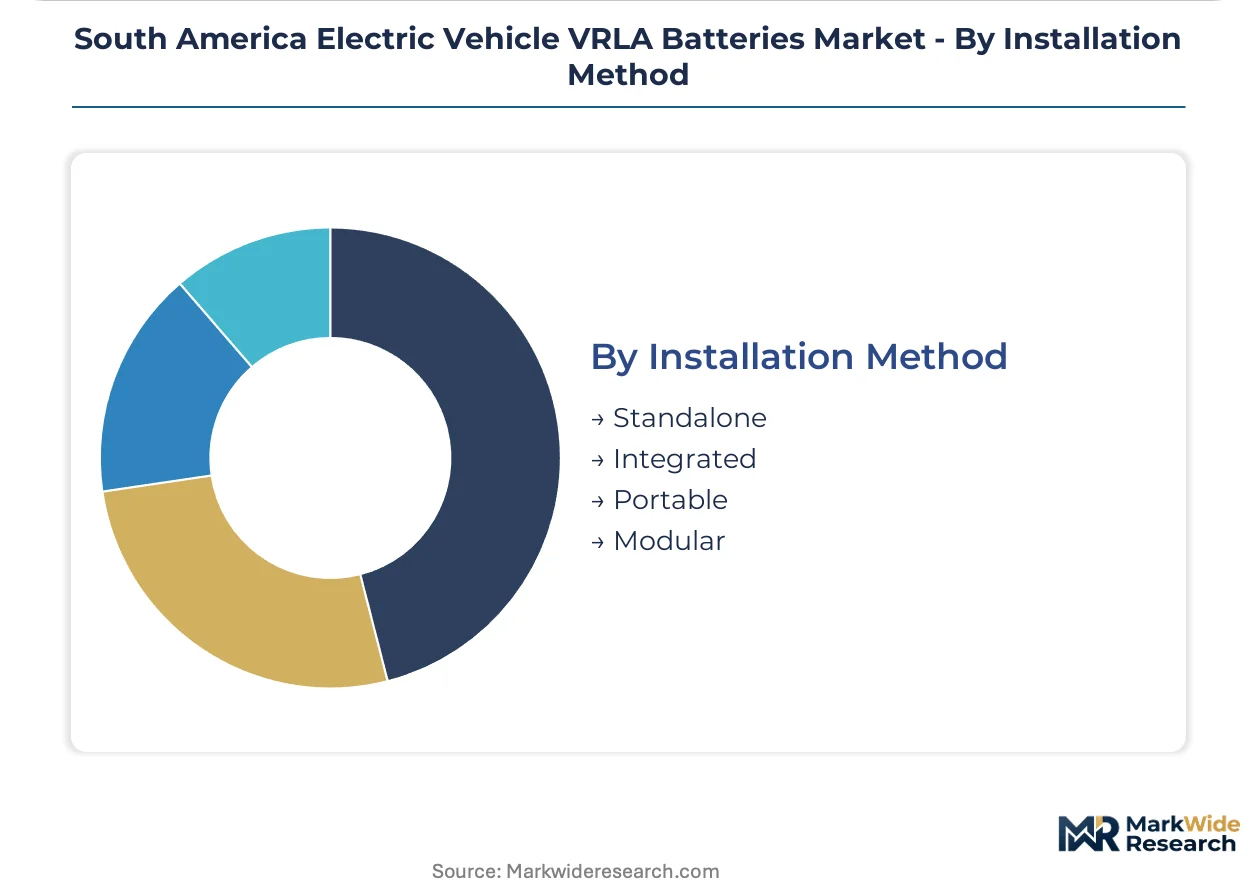
| Segmentation | Battery Type: Flooded, Absorbent Glass Mat, Gel, Sealed Lead Acid End User: OEMs, Fleet Operators, Government, Aftermarket Providers Application: Passenger Vehicles, Commercial Vehicles, Public Transport, Two-Wheelers Installation Method: Standalone, Integrated, Portable, Modular |
| Companies Covered | Clarios, EnerSys, Exide Technologies, GS Yuasa Corporation, East Penn Manufacturing, Moura Accumulators, C&D Technologies, Johnson Controls International, Exide Industries, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle VRLA Batteries Market Trends and Innovations
Software-defined battery architectures are redefining value capture models across South American electric vehicle supply chains, shifting supplier revenue from hardware transactions toward performance-based service agreements.
Carbon-enhanced negative active mass formulations are unifying cycle life and cold-cranking performance in single cell designs. Brazilian electric bus operators in Curitiba and Porto Alegre are specifying these hybrid chemistries for routes spanning both tropical lowlands and elevated southern plateaus. This convergence is unifying previously separate product lines into unified platform offerings, reducing inventory complexity for regional distributors.
Argentina's IRAM safety standards are mandating enhanced flame-arrestor venting systems and thermal runaway containment protocols for cells deployed in passenger-carrying applications. These requirements are accelerating design standardization across Mercosur trade zones, forcing Brazilian suppliers to harmonize production lines with Argentine certification benchmarks. Light commercial vehicle segments in both countries are absorbing compliance costs through platform consolidation.
Fleet procurement teams are consolidating vendor relationships around suppliers offering integrated battery-charger-service bundles. Municipal operators in São Paulo's metropolitan region are displacing spot-purchase models with multi-year total-cost contracts that internalize capacity fade risk. This restructuring is most visible in electric bus deployments where battery replacement timing uncertainty previously complicated operating budget forecasting.
South America Electric Vehicle VRLA Batteries Market Segmentation
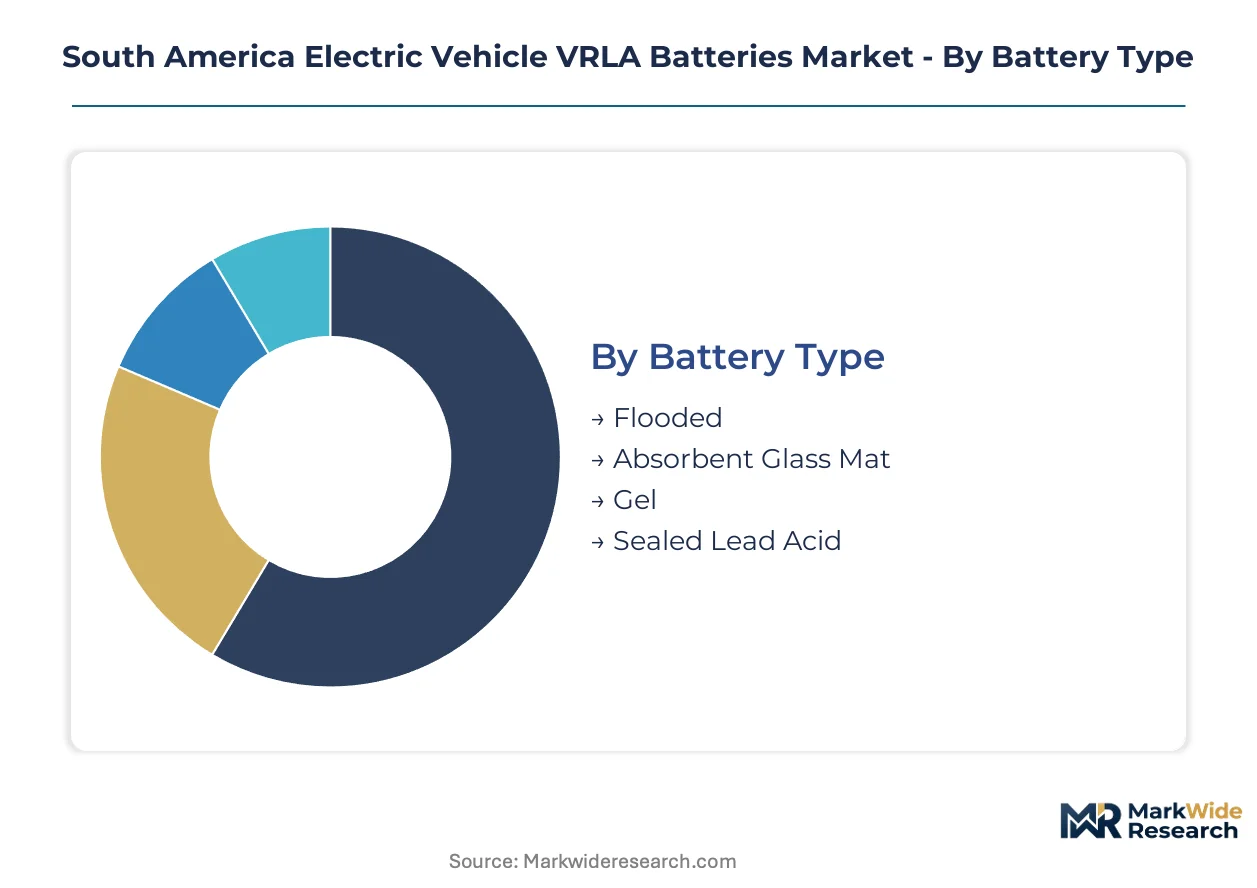
Segmentation reveals how certification burdens and procurement frameworks split the South America Electric Vehicle VRLA Batteries Market into distinct competitive arenas. Each dimension carries unique compliance obligations under INMETRO, IRAM, and ANVISA oversight that reshape supplier economics and customer switching costs.
Battery Type:
INMETRO certification timelines vary sharply across chemistries, with gel formulations requiring extended thermal stability testing that delays commercialization by months versus flooded alternatives.
- Absorbent Glass Mat:Fiberglass mat separators immobilize electrolyte for superior vibration resistance on deteriorating Brazilian and Argentine road infrastructure. São Paulo's electric bus fleet operators specify AGM configurations for auxiliary power systems, accepting premium pricing to reduce cell replacement frequency on high-vibration urban routes.
- Gel:Silica-thickened electrolyte delivers enhanced thermal tolerance for tropical climates where ambient temperatures accelerate standard cell degradation. Chilean mining operators in Atacama and Antofagasta regions favor gel configurations for underground light vehicles, where explosion-proof ratings and extended float life justify procurement complexity.
- Flooded:Conventional liquid electrolyte designs serve cost-sensitive applications in secondary Brazilian markets where maintenance access remains practical.
- Sealed Lead Acid:Maintenance-free construction targets remote installations across Argentine provincial fleets with limited technical service infrastructure.
Leading the category by volume: Absorbent Glass Mat. Growing fastest: Gel.
End User:
Procurement patterns diverge sharply between long-term contract holders and spot-market purchasers, with fleet operators consolidating around multi-year service agreements that internalize capacity fade risk.
- Fleet Operators:Municipal and private fleet managers across Brazil's southeastern corridor negotiate total-cost-of-ownership contracts bundling cells, chargers, and predictive maintenance. São Paulo's metropolitan bus operators displace spot purchasing with performance-based agreements that transfer technical risk to suppliers.
- Aftermarket Providers:Independent distributors and service networks capture replacement demand as first-generation electric bus fleets in Santiago and Porto Alegre age into cell refresh cycles. These channels expand fastest as warranty expirations concentrate replacement timing across 2018-2020 vintage deployments.
- OEMs:Original equipment manufacturers integrate VRLA systems into low-speed electric vehicle platforms for Brazilian light commercial segments.
- Government:Federal and provincial procurement offices manage electrification mandates through centralized tenders with localized assembly requirements.
Highest contract values concentrate with Fleet Operators. Aftermarket Providers gain share fastest as replacement cycles synchronize.
Application:
Duty cycle characteristics and range requirements determine chemistry selection, with auxiliary power applications tolerating VRLA weight penalties that traction-primary platforms reject.
- Public Transport:Electric bus auxiliary systems across Curitiba, Porto Alegre, and Buenos Aires municipal fleets represent the core demand concentration. These applications prioritize cost predictability over energy density, with VRLA configurations serving HVAC, lighting, and door systems where lithium-ion premiums prove unjustified.
- Commercial Vehicles:Light commercial electrification in Brazil's PROCONVE P-8 transition uses VRLA as bridge storage for short-range urban delivery routes. Minas Gerais-based logistics operators specify these configurations for predictable replacement budgeting on fixed municipal contracts.
- Passenger Vehicles:Low-speed neighborhood electric vehicles in Argentine tourist zones absorb surplus VRLA production.
- Two-Wheelers:Electric motorcycle and scooter segments in secondary Brazilian cities favor lowest-cost flooded configurations.
Public Transport commands the largest procurement volumes. Commercial Vehicles climb fastest as emission standards tighten.
Installation Method:
Physical integration depth shapes supplier technical support obligations and customer switching costs across the value chain.
- Integrated:Factory-installed battery systems within electric bus chassis require platform-specific form factors and thermal management coordination. Brazilian manufacturers in São Paulo state specify integrated designs to optimize pack placement and weight distribution for regulatory compliance.
- Modular:Swappable rack-mounted configurations enable rapid replacement in Chilean mining operations where vehicle uptime directly correlates with production economics. Antofagasta-based copper operators specify modular architectures to minimize technician exposure time in hazardous environments.
- Standalone:Conventional tray-mounted installations persist in retrofit applications across aging Argentine municipal fleets.
- Portable:Detachable auxiliary power units serve temporary charging infrastructure and emergency backup roles.
Integrated designs dominate new platform procurement. Modular formats expand most quickly in mining and heavy-duty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates regional production capacity while consumption spreads across Mercosur trade zones. Argentine and Chilean fleet operators import assembled cells through Brazilian distribution corridors. Local content mandates under Rota 2030 are forcing suppliers to relocate final assembly to Minas Gerais and São Paulo states.
Brazil
São Paulo's metropolitan bus operators drive procurement volumes for auxiliary power systems in electric fleet deployments. INMETRO certification mandates govern cell construction standards and charge acceptance protocols across the national value chain. The southeastern manufacturing corridor spanning São Paulo and Minas Gerais states hosts localized assembly operations exploiting Rota 2030 local content thresholds.
Argentina
Buenos Aires provincial transport authorities are launching second-wave electric bus tenders with localized assembly requirements. IRAM safety standards mandate enhanced flame-arrestor venting systems and thermal runaway containment protocols for passenger-carrying applications. Córdoba and Rosario industrial zones are absorbing compliance costs through platform consolidation with Brazilian suppliers.
Chile
Underground light vehicle mandates in Atacama and Antofagasta copper operations create demand for explosion-proof gel cell configurations. The Ministry of Environment extended producer responsibility frameworks add compliance layers favoring suppliers with established reverse-logistics networks. Santiago's aging first-generation electric bus fleets are entering replacement cycles for cell refresh services.
Colombia
Bogotá's TransMilenio bus rapid transit electrification pilots are testing VRLA auxiliary configurations for cost-sensitive municipal operators. National mining regulations are tightening emissions standards for underground equipment in coal and gold operations. Medellín's manufacturing clusters are evaluating regional sourcing partnerships with Brazilian separator material suppliers.
South America Electric Vehicle VRLA Batteries Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for positioning across South American electric vehicle battery supply chains. The vendor base splits between integrated manufacturers owning separator production and assemblers sourcing materials through Mercosur trade channels. Three archetypes dominate: multinational industrial battery specialists with regional service networks, domestic assemblers exploiting local content mandates, and mining-focused suppliers certifying for hazardous environment applications. Competitive moves concentrate on backward integration into lead smelting capacity and multi-year service contract bundling with municipal fleet operators.
Within the multinational tier, Clarios and EnerSys anchor positions through established distribution infrastructure across Brazilian industrial corridors. Moura Accumulators exemplifies the domestic assembler archetype, leveraging Rota 2030 compliance to control procurement channels for southeastern manufacturing clusters. These three entities represent the competitive spectrum from global scale to localized regulatory adaptation.
| Leading Market Players |
|---|
| Clarios |
| EnerSys |
| Exide Technologies |
| GS Yuasa Corporation |
| East Penn Manufacturing |
| Moura Accumulators |
| C&D Technologies |
| Johnson Controls International |
| Exide Industries |
| Others |
Pricing and Supply Chain Analysis
Municipal fleet procurement offices across São Paulo and Buenos Aires concentrate purchasing power through multi-year total-cost contracts, anchoring pricing models around performance guarantees rather than per-unit transactions. This buyer concentration forces suppliers to internalize capacity fade risk and bundle predictive maintenance services, compressing spot-market premiums and rewarding integrated service providers with recurring revenue stability.
Pricing Analysis
Margin tightening in standard-grade AGM configurations traces to lithium iron phosphate cost compression from Chinese export markets narrowing the total-cost-of-ownership gap. Three-tier pricing structure across INMETRO-certified premium, standard commercial, and economy flooded tiers separates buyers by certification burden and vibration resistance requirements. Pricing pressure intensifies in gel segments as Chilean mining operators consolidate vendor relationships around explosion-proof bundled offerings. Aftermarket providers exhibit highest price sensitivity, while integrated fleet operators absorbing multi-year contracts demonstrate lowest sensitivity to unit price fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Argentine silica gel suppliers feeding Brazilian cell assemblers, exposing manufacturers to Mercosur trade negotiation uncertainties. Lead ingot sourcing draws from domestic Minas Gerais smelters and Peruvian imports, while fiberglass mat separators hinge on São Paulo-based production clusters. Tariff exposure on separator materials creates procurement risk for manufacturers dependent on cross-border inputs. Distribution runs through Brazilian southeastern manufacturing corridors into Argentine and Chilean fleet operator channels, with aftermarket service networks capturing replacement cycles in Santiago and Porto Alegre.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified assembly capacity scarcity under Rota 2030 local content mandates props pricing power for incumbents with established Minas Gerais footprints, constraining supply elasticity against fleet electrification timelines.
For Market Incumbents: Anticipate lithium-ion substitution acceleration in light commercial segments by deepening backward integration into lead smelting capacity and locking multi-year service contracts with São Paulo metropolitan bus operators before PROCONVE P-8 compliance windows compress procurement flexibility. For New Entrants and Emerging Players: Capture Argentine second-wave electric bus tenders through Buenos Aires provincial retrofit programs, where localized assembly requirements favor regional suppliers without established Brazilian footprints. Target gel cell certification for Chilean mining electrification as the most penetrable white-space segment, leveraging explosion-proof ratings as differentiation against standard AGM incumbents. For Investors and Strategic Acquirers: The window for entry favors domestic assemblers with Rota 2030 compliance infrastructure and established reverse-logistics networks. Long-term viability centers on suppliers controlling southeastern Brazilian manufacturing corridors as electrification mandates synchronize replacement cycles across Mercosur fleets. Monitor lithium iron phosphate import pricing from Chinese markets as the critical inflection signal for VRLA demand elasticity in cost-sensitive urban fleet segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captures margin pools from volatile ingot markets while satisfying Rota 2030 localization thresholds. |
| INMETRO Certification Fast-Tracking | Compresses product launch timelines against competitors stuck in extended thermal stability testing windows. |
| Multi-Year Service Contract Bundling | Transfers capacity fade risk to suppliers while securing recurring revenue from São Paulo fleet operators. |
| Argentine Assembly Footprint Establishment | Exploits Buenos Aires provincial tender requirements favoring localized production over Brazilian imports. |
| Explosion-Proof Gel Cell Development | Opens Chilean mining electrification demand where standard AGM configurations fail hazardous environment ratings. |
Research Methodology
Document review covered INMETRO certification databases, PROCONVE regulatory filings, and Mercosur trade statistics, complemented by interviews with fleet procurement managers at São Paulo municipal operators, technical directors at Argentine bus manufacturers, and aftermarket service heads across Chilean mining corridors. Secondary validation drew from Brazilian automotive production registries, Argentine IRAM safety standard documentation, and Chilean Ministry of Environment extended producer responsibility frameworks. Bottom-up cell shipment estimates triangulated against top-down fleet electrification mandate targets.
Historical deployment patterns cross-referenced against expert panel assessments of Rota 2030 compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry type, end-user procurement channel, vehicle application duty cycle, and installation integration depth. CAGRs derived from elasticity-adjusted fleet conversion rates and replacement cycle synchronization. Industry-specific inputs incorporated PROCONVE P-8 phase-in schedules and lithium-ion import price trajectory assumptions.
The model holds under stable Mercosur trade arrangements and continued Rota 2030 localization enforcement; deviation in tariff regimes or lithium iron phosphate cost compression velocity would shift fleet operator chemistry preferences and replacement timing. Forecasts reflect documented assumptions on certification timeline durations and mining electrification mandate implementation pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Traction Battery Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
US EV Battery Pack Market