
 South America Electric Vehicle Battery Anode Market | 2026-2036
South America Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Anode Market Insights
Performance-based battery leasing is recalibrating what anode suppliers must deliver across South America. CBMM leverages its niobium expertise to anchor differentiated anode formulations for regional OEM programs. Albemarle Corporation sustains upstream lithium supply integration that competes with imported graphite feedstock. Umicore SA specializes in closed-loop recycling services that extend material security for Brazilian cell manufacturers.
The South America electric vehicle battery anode comprises the negative electrode material—typically graphite, silicon, or lithium-ion compounds—engineered to intercalate lithium ions during charge cycles with specific capacities ranging from 372 mAh/g for standard graphite to over 4,000 mAh/g for silicon-doped variants. Its primary commercial purpose is to determine energy density, cycle life, and fast-charge capability in battery packs deployed across passenger and commercial vehicle platforms. Graphite formulations currently dominate installed capacity due to mature supply chains, while silicon-blend architectures represent the fastest-expanding technology segment as regional cell makers pursue range extension. OEM direct procurement occupies the deepest margin pool within end-user channels, though aftermarket providers are gaining traction through refurbished pack programs.
Brazil's ANFAVEA emission protocols and Argentina's national industrial promotion frameworks shape anode chemistry selection and local content thresholds. Chile's environmental ministry enforces carbon footprint disclosure on lithium extraction that cascades into anode material certification requirements. Stakeholders must monitor how MERCOSUR harmonization of battery standards alters cross-border component qualification before committing to fixed manufacturing footprints.
Market Dynamics
Battery leasing contracts are forcing anode suppliers to guarantee cycle-life performance rather than sell materials outright, compressing margins while extending commercial relationships across Brazil's fleet electrification programs.
Growth Catalysts
- ANFAVEA Emission Protocols:Brazil's automotive industry association mandates tightening CO2 thresholds that push OEMs toward higher-capacity anode chemistries. Passenger vehicle manufacturers in São Paulo accelerate silicon-blend adoption to meet fleet-average requirements.
- Lithium Triangle Feedstock Proximity:Argentina's expanding brine extraction operations reduce transportation costs for regional cell manufacturers. Minas Gerais-based pack assemblers source precursor materials through shortened supply loops.
- Silicon-Doped Architectures:Next-generation anode formulations achieving 800+ mAh/g practical capacity enable range extension without pack volume expansion. Chilean cell pilot lines validate these materials for Andean altitude performance.
Market Restraints
- Spherical Graphite Import Dependency:Battery-grade graphite processing concentrates in East Asian facilities, exposing Brazilian manufacturers to shipping cost volatility and currency fluctuation risks.
- Chilean Carbon Footprint Disclosure Mandates:Environmental ministry certification requirements add 12-18 month qualification timelines for anode material imports, delaying commercial deployment.
- Lithium-Ion Intercalation Limits:Standard graphite anodes face theoretical capacity ceilings that constrain fast-charge capability in commercial vehicle applications requiring sub-30 minute replenishment.
Strategic Opportunities
- Colombia's Underpenetrated Commercial Fleet:Bogotá's bus rapid transit electrification program lacks established anode suppliers, creating first-mover positioning for qualified regional vendors.
- Closed-Loop Recycling Infrastructure:Brazilian federal industrial policy incentives support domestic black mass processing capacity. Spent anode recovery operations in southeastern industrial corridors reduce virgin material requirements.
- MERCOSUR Harmonization Trajectory:Pending battery standard alignment across member states would enable single-qualification access to Argentina, Brazil, Paraguay, and Uruguay markets.
Industry Challenges
- Electrochemical Engineer Scarcity:Brazilian universities produce fewer than 200 specialized battery researchers annually, constraining R&D velocity for domestic anode formulation development.
- Cell-to-Pack Integration Complexity:OEM direct procurement models demand anode suppliers assume liability for full pack performance, requiring capital investment in systems engineering capabilities beyond material production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Anode Market |
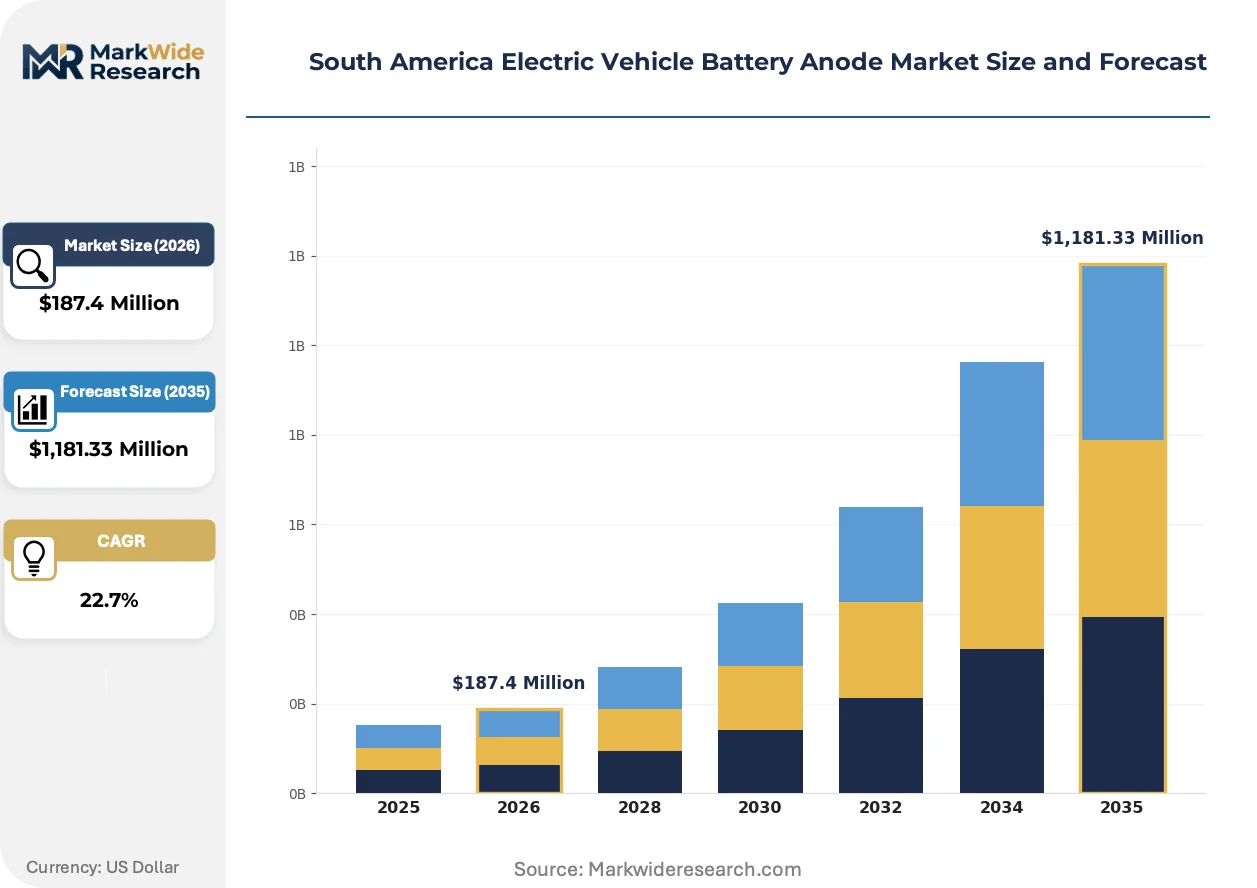
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Graphite, Silicon, Lithium-ion, Conductive Additives End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Traditional, Advanced, Solid-State, Hybrid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Redwood Materials Inc., Mitsubishi Chemical Group Corporation, CBMM, LG Chem Ltd, Targray Industries Inc., BASF SE, UBE Corporation, Albemarle Corporation, Umicore SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Anode Market Trends and Innovations
Silicon-blend anode architectures are consolidating technical roadmaps across South American cell manufacturers, displacing pure graphite formulations in premium vehicle programs while forcing supply chain reconfiguration around novel precursor sourcing.
Silicon-doped composite anodes intercalate lithium ions through alloy mechanisms that achieve 3x theoretical capacity versus standard graphite. Brazilian OEMs in the São Paulo-Minas Gerais corridor adopt these materials for 2026-2028 vehicle platforms. This technology is consolidating supplier relationships around performance-guarantee contracts rather than commodity spot purchases.
Chile's environmental ministry enforces carbon footprint disclosure on lithium extraction operations that cascades into anode material certification requirements. Cell manufacturers must document Scope 3 emissions across graphite mining, spheroidization, and surface coating processes. Brazilian pack assemblers are responding by qualifying regional synthetic graphite alternatives with shorter transport distances.
Fleet operators are abandoning capital purchase models for battery assets in favor of per-kilometer service contracts. This restructures anode supplier relationships toward outcome-based pricing tied to cycle-life guarantees. The transformation is most visible in Brazil's southeastern logistics corridor, where refrigerated truck electrification programs demand 10-year performance warranties.
South America Electric Vehicle Battery Anode Market Segmentation
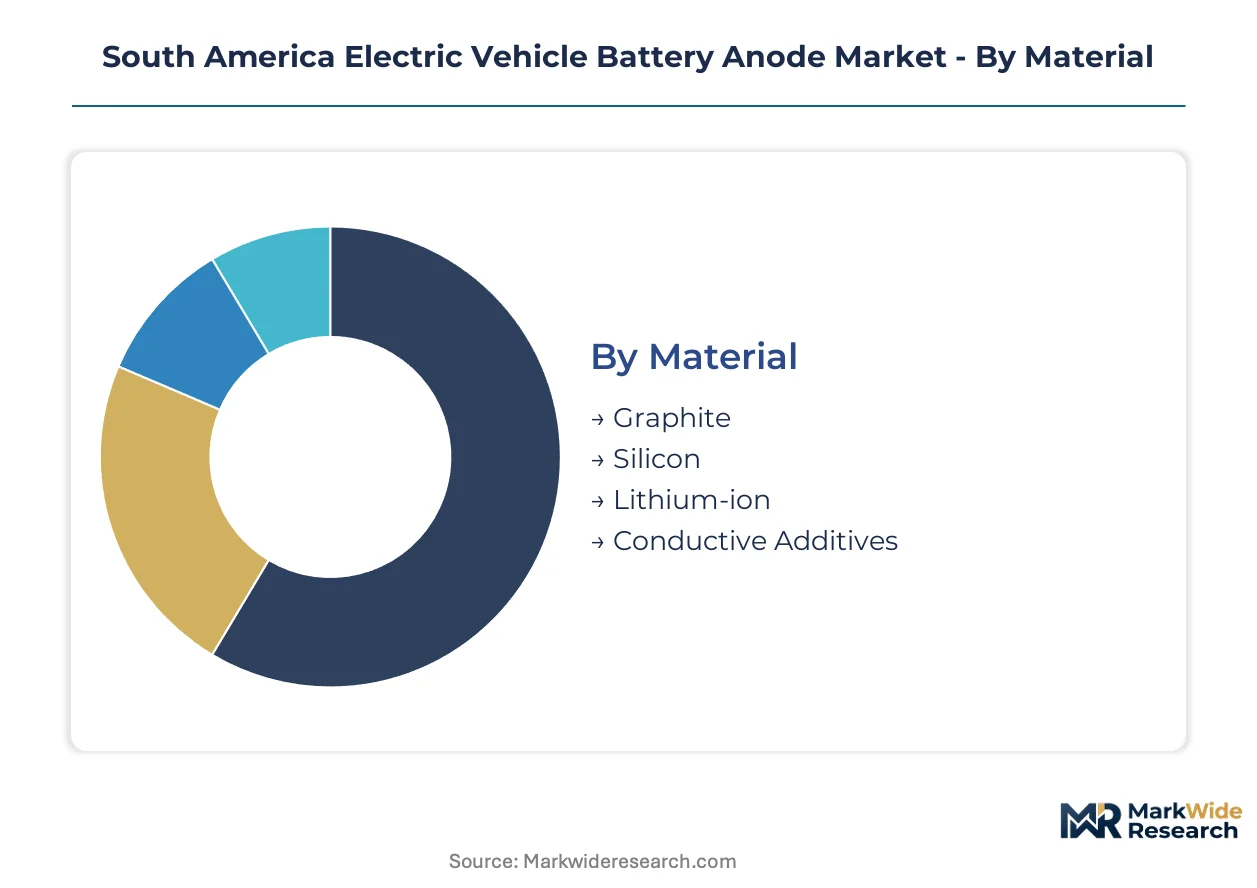
Anode procurement patterns across South America diverge sharply by material chemistry and customer type. Fleet operators in Brazil's southeastern corridor negotiate performance guarantees that reshape supplier priorities, while Chilean carbon disclosure mandates filter through every segment.
Material:
Volume deployment concentrates in mature graphite formulations, while premium positioning shifts toward silicon-enhanced architectures with superior energy density.
- Graphite:Spherical and flake variants dominate installed capacity across Brazilian pack assembly lines. São Paulo-based cell manufacturers source primarily through East Asian processing facilities, exposing operations to shipping cost volatility and currency fluctuation risks.
- Silicon:Alloy-intercalation mechanisms achieve practical capacities exceeding 800 mAh/g in pilot validation. Chilean cell lines at Andean altitude test these formulations for thermal stability, with Brazilian OEMs targeting 2026-2028 platform integration.
- Lithium-ion:Pre-lithiated compounds address first-cycle efficiency losses in high-nickel cathode pairings. Regional adoption remains constrained by precursor availability from Argentina's expanding brine operations.
- Conductive Additives:Carbon black and CNT dispersions optimize electron pathways in high-loading silicon blends. Minas Gerais-based formulators qualify these materials for fast-charge architectures.
Mature deployment sits with graphite. Newer deployment is concentrated in silicon.
End User:
Direct procurement authority determines margin capture and liability exposure across the value chain.
- OEMs:Brazilian automotive manufacturers in the São Paulo-Minas Gerais corridor negotiate cycle-life guarantees that transfer pack performance risk upstream to anode suppliers. ANFAVEA emission protocols tighten fleet-average requirements that favor higher-capacity material selection.
- Aftermarket Providers:Refurbished pack programs gain traction through performance-based leasing contracts. These operators source anode materials for remanufacturing operations with shorter qualification timelines than OEM direct procurement.
- Tier-1 Suppliers:Cell-to-pack integration specialists assume systems engineering liability beyond material production. Brazilian federal industrial policy incentives support domestic capability buildout in southeastern industrial corridors.
- Vehicle Assemblers:Commercial fleet operators in Bogotá's bus rapid transit electrification program procure through outcome-based pricing tied to kilometer-driven performance metrics.
Margin concentration follows OEM direct relationships. Fastest volume expansion is occurring in aftermarket channels.
Technology:
Manufacturing maturity separates near-term deployable solutions from architectures requiring extended qualification.
- Traditional:Slurry-coated graphite anodes with established formation protocols. Brazilian universities produce fewer than 200 specialized battery researchers annually, constraining R&D velocity for domestic formulation development beyond these proven architectures.
- Advanced:Silicon-blend composites with engineered porosity for volume expansion management. Chilean environmental ministry carbon footprint disclosure requirements add 12-18 month qualification timelines for these material imports.
- Solid-State:Sulfide and oxide electrolyte interfaces with lithium-metal compatibility. Regional cell pilot lines evaluate these architectures for Andean altitude performance where reduced air pressure affects conventional liquid electrolyte behavior.
- Hybrid:Mixed-ion systems combining lithium intercalation with alternative charge carriers. Argentine lithium triangle feedstock proximity supports precursor sourcing for experimental formulations.
Production scale sits with traditional coating methods. Steepest expansion trajectory is occurring in advanced silicon-blend processing.
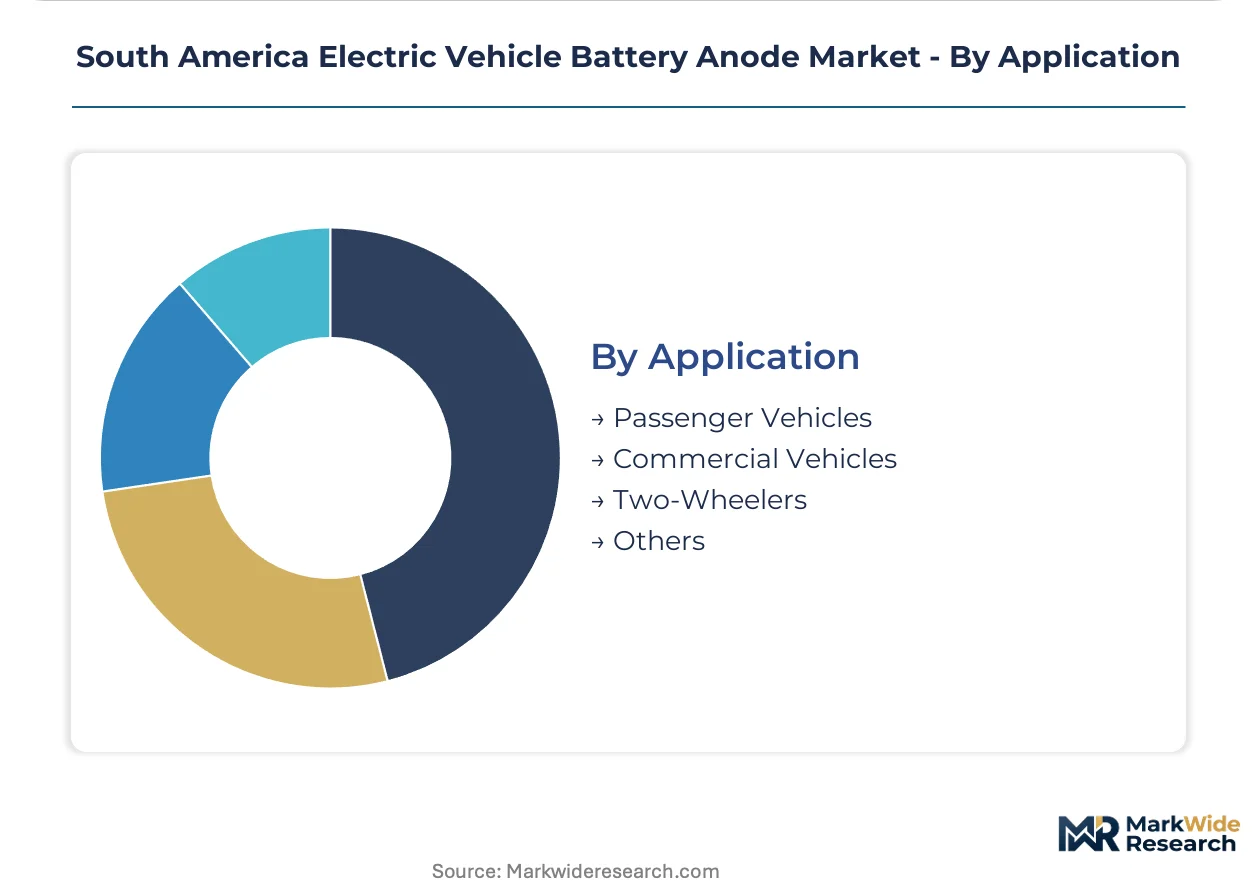
Application:
Vehicle duty cycles dictate anode durability requirements and fast-charge capability thresholds.
- Passenger Vehicles:Brazilian OEMs accelerate silicon-blend adoption to meet ANFAVEA fleet-average CO2 thresholds. Range extension targets drive energy density priorities without pack volume expansion.
- Commercial Vehicles:Refrigerated truck electrification programs in Brazil's southeastern logistics corridor demand 10-year performance warranties and sub-30 minute replenishment capability. Standard graphite anodes face theoretical capacity ceilings that constrain these fast-charge requirements.
- Two-Wheelers:Cost-optimized graphite formulations serve price-sensitive urban mobility markets. Colombian commercial fleet electrification lacks established anode suppliers, creating positioning opportunities for qualified regional vendors.
- Others:Off-highway and specialty vehicle applications with customized duty cycles. Closed-loop recycling infrastructure in Brazilian southeastern corridors reduces virgin material requirements for these lower-volume segments.
Technology validation sits with passenger vehicle platforms. Emerging deployment is concentrating in commercial vehicle electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes the majority of anode materials while Argentina and Chile supply upstream lithium feedstock, creating a regional production-consumption asymmetry that shapes cross-border trade flows and qualification requirements.
Brazil
Fleet electrification programs and ANFAVEA emission protocols drive anode demand across passenger and commercial vehicle platforms. The national automotive industry association mandates tightening CO2 thresholds that push OEMs toward higher-capacity silicon-blend chemistries. São Paulo and Minas Gerais anchor the southeastern automotive corridor where cell manufacturers and pack assemblers concentrate manufacturing operations.
Argentina
Lithium triangle brine extraction operations reduce precursor transportation costs for regional battery supply chains. National industrial promotion frameworks establish local content thresholds that influence anode chemistry selection for domestically assembled packs. Jujuy and Salta provinces host expanding extraction facilities that feed Minas Gerais-based cell manufacturers through shortened supply loops.
Chile
Carbon neutrality mandates and environmental ministry certification requirements cascade into anode material traceability obligations. The ministry enforces carbon footprint disclosure on lithium extraction that adds qualification timelines for imported graphite and silicon precursors. Atacama Desert extraction operations and Santiago-based pilot lines validate advanced anode formulations for Andean altitude performance.
Colombia
Bogotá's bus rapid transit electrification program lacks established anode suppliers, creating positioning opportunities for qualified regional vendors. National urban mobility initiatives prioritize commercial fleet decarbonization without domestic cell manufacturing infrastructure. Antioquia and Valle del Cauca industrial zones present aftermarket refurbishment prospects for imported battery assets.
South America Electric Vehicle Battery Anode Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South America electric vehicle battery anode market, with integrated mining-chemical conglomerates facing specialized materials technology firms. The supplier base organizes around three strategic archetypes: diversified mining-chemical conglomerates with upstream lithium control, dedicated battery materials specialists with formulation expertise, and diversified industrial conglomerates with cross-sector process capabilities. Capacity expansion and strategic partnerships dominate competitive moves as participants secure qualification status with Brazilian OEMs.
Among diversified mining-chemical conglomerates, Albemarle Corporation and CBMM occupy positions that exemplify upstream integration strategies, while Umicore SA represents the specialized battery materials technology archetype with closed-loop recycling capabilities. These participants anchor distinct competitive vectors—feedstock security versus materials engineering versus circular economy infrastructure—without overlapping positioning.
| Leading Market Players |
|---|
| Redwood Materials Inc. |
| Mitsubishi Chemical Group Corporation |
| CBMM |
| LG Chem Ltd |
| Targray Industries Inc. |
| BASF SE |
| UBE Corporation |
| Albemarle Corporation |
| Umicore SA |
| Others |
Pricing and Supply Chain Analysis
Brazilian fleet operators' shift toward performance-guaranteed battery leasing contracts is forcing anode suppliers to absorb cycle-life risk and recalibrate pricing models around outcome-based service fees rather than commodity material sales.
Pricing Analysis
Margin tightening in OEM direct procurement reflects ANFAVEA emission protocols that mandate higher-capacity silicon-blend chemistries with cost premiums over standard graphite. Three-tier pricing structure across premium silicon-doped, certified high-purity graphite, and economy flake grades separates performance-guaranteed contracts from spot material purchases. Cost-down pressure on aftermarket channels accelerates because refurbished pack programs compete on per-kilometer service rates. Tier-1 suppliers demonstrate lowest price sensitivity due to cell-to-pack integration liability transfer, while two-wheeler assemblers in Colombia exhibit highest sensitivity to base material costs.
Supply Chain Analysis
Electrochemical engineer scarcity across Minas Gerais and São Paulo industrial corridors constrains domestic formulation development velocity and extends reliance on imported technical expertise. Manufacturing concentration centers on China, South Korea, and Japan for spherical graphite spheroidization and surface coating operations. Raw material dependencies draw from Argentine lithium triangle brine operations, East Asian synthetic graphite facilities, and Chilean carbon black precursors. Single-source vulnerability in battery-grade graphite processing exposes Brazilian pack assemblers to shipping cost volatility and currency fluctuation risks. Distribution runs through regional cell manufacturers in the southeastern automotive corridor before reaching OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream lithium feedstock control and downstream cell-to-pack engineering capabilities determine supplier survival against margin-compressing performance guarantees.
For Market Incumbents: Deepen captive supply relationships with Argentine lithium triangle operators to secure precursor cost advantages against graphite import volatility. Expand in-house silicon-doped formulation R&D in Minas Gerais to reduce qualification dependency on East Asian technical partnerships. ANFAVEA protocol tightening threatens commodity graphite suppliers with displacement from premium OEM programs. For New Entrants and Emerging Players: Launch via refurbished pack aftermarket channels in Bogotá's bus rapid transit electrification program where incumbent qualification status remains unestablished. Colombia's commercial fleet segment offers lowest competitive density among South American geographies. Target performance-based leasing contracts with refrigerated truck operators in Brazil's southeastern logistics corridor seeking 10-year cycle-life warranties. For Investors and Strategic Acquirers: The window for entry favors closed-loop recycling specialists with black mass processing capabilities ahead of Brazilian federal industrial policy incentive maturation. Long-term viability hinges on material security positioning through spent anode recovery infrastructure rather than virgin feedstock trading. Watch for MERCOSUR battery standard harmonization as the signal to accelerate cross-border manufacturing footprint commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstock | Argentine brine extraction proximity reduces transportation costs for Minas Gerais cell manufacturers. |
| Silicon-Blend Formulation Partnership | Chilean pilot line validation accelerates Andean altitude performance certification for Brazilian OEMs. |
| Closed-Loop Recycling Infrastructure | Brazilian federal incentives support domestic black mass processing capacity in southeastern industrial corridors. |
| Performance-Guarantee Contract Structuring | Fleet operator per-kilometer service contracts extend supplier relationships beyond commodity spot sales. |
| MERCOSUR Harmonization Alignment | Single-qualification access across Argentina, Brazil, Paraguay, and Uruguay reduces regulatory fragmentation costs. |
Research Methodology
Independent corroboration across primary interviews with anode material procurement managers, cell manufacturing engineers, and OEM platform electrification directors, combined with secondary validation through ANFAVEA emission protocol filings, Chilean environmental ministry carbon disclosure records, and Argentine national industrial promotion framework documents, underwrites the qualitative findings. Bottom-up triangulation across battery pack assembly capacity announcements and top-down reconciliation with vehicle electrification program targets ensures segmentation integrity.
Rate-of-change decomposition across material chemistry transitions, end-user procurement model shifts, and technology qualification timelines structures the analytical framework. Segmentation dimensions modeled include anode material type, customer procurement authority, manufacturing technology maturity, and vehicle application duty cycle. CAGRs derive from installed capacity buildout trajectories, fleet electrification program commitments, and precursor supply expansion schedules across the analysis window.
Chilean carbon footprint disclosure mandate delays, Argentine lithium extraction expansion velocity, and MERCOSUR regulatory harmonization trajectory are the dominant revision risks to forecast assumptions. Material deviation in these triggers warrants pause and re-evaluation of fixed manufacturing footprint commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Anode Market