
 North America Electric Vehicle Battery Materials Market | 2026-2036
North America Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Materials Market Insights
Electrochemical engineering talent is collapsing across the Great Lakes and Southeast battery corridors, constraining plant commissioning timelines and process optimization. BASF SE leverages its cathode active material pilot lines in Ohio to anchor regional precursor supply. Umicore competes through its closed-loop recycling technology, recovering nickel and cobalt from spent cells in Ontario. ENTEK dominates separator film manufacturing in Kentucky, sustaining North American capacity for dry-process polypropylene membranes.
Electric vehicle battery materials encompass refined metals, engineered ceramics, polymer membranes, and electrolyte formulations that enable reversible lithium-ion intercalation at cell voltages typically spanning 3.2 to 4.3 volts. These materials determine energy density, cycle life, thermal stability, and ultimately vehicle range and safety. Lithium Iron Phosphate chemistry leads in commercial vehicle and entry-level passenger applications where cycle durability outweighs gravimetric energy targets. Nickel Cobalt Manganese materials occupy the premium long-range segment where cathode energy density directly translates to pack-level range extension. Solid State electrolytes represent the fastest-growing development trajectory, though manufacturing scale and interfacial impedance remain unresolved before structural margin pools shift.
The US Inflation Reduction Act, administered through Treasury and IRS guidance, mandates escalating domestic content thresholds for battery components to qualify consumer tax credits, forcing supply chain relocalization. EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates compound this demand by accelerating OEM electrification timelines. NHTSA battery safety protocols and UL 9540A thermal runaway testing requirements shape cell architecture and material selection decisions. Stakeholders must monitor how mid-decade mineral processing capacity in Quebec and the US Midwest resolves against cathode plant buildout schedules to avoid feedstock bottlenecks.
Market Dynamics
The US Inflation Reduction Act's domestic content thresholds are forcing a complete rewiring of battery material sourcing, concentrating investment around Michigan and Tennessee gigafactory clusters while straining midstream processing capacity.
Growth Catalysts
- IRA Tax Credit Thresholds:Treasury guidance mandates escalating North American content percentages for consumer EV credits, pulling cathode and precursor production onshore.
- Zero-Emission Vehicle Mandates:California Air Resources Board regulations and EPA tailpipe standards compress OEM electrification timelines, tightening material offtake contracts.
- Pickup and SUV Electrification:Long-range electric truck programs from Detroit automakers concentrate demand for high-nickel cathode formulations.
Market Restraints
- Midstream Processing Gap:Lithium hydroxide and nickel sulfate conversion capacity in Quebec and the US Midwest lags cathode plant commissioning schedules.
- Cobalt Supply Concentration:DRC-origin cobalt faces reputational and logistics constraints as OEMs scrub supply chains for IRA compliance.
- Solid-State Manufacturing Immaturity:Interfacial impedance and dry electrode processing yield rates block structural margin shifts away from liquid electrolyte cells.
Strategic Opportunities
- Closed-Loop Recycling Infrastructure:Ontario and Ohio facilities can recover nickel and cobalt from manufacturing scrap and end-of-life packs, reducing virgin material dependence.
- Lithium Iron Phosphate Expansion:Entry-level passenger and commercial vehicle segments in Mexico offer untapped demand for lower-cost, high-cycle-life chemistry.
- Southeast Battery Corridor:Tennessee and Kentucky separator and electrolyte plants anchor regional supply networks for Southeast OEM assembly.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Commissioning timelines for Ohio and Michigan gigafactories slip as qualified process engineers migrate between competing projects.
- UL 9540A Certification Bottlenecks:Thermal runaway propagation testing queues extend cell qualification cycles, delaying pack integration programs.
- Legacy Tier-One Supplier Reconfiguration:Traditional powertrain material suppliers face stranded asset risk as cathode and electrolyte procurement bypasses established automotive supply hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Materials Market |
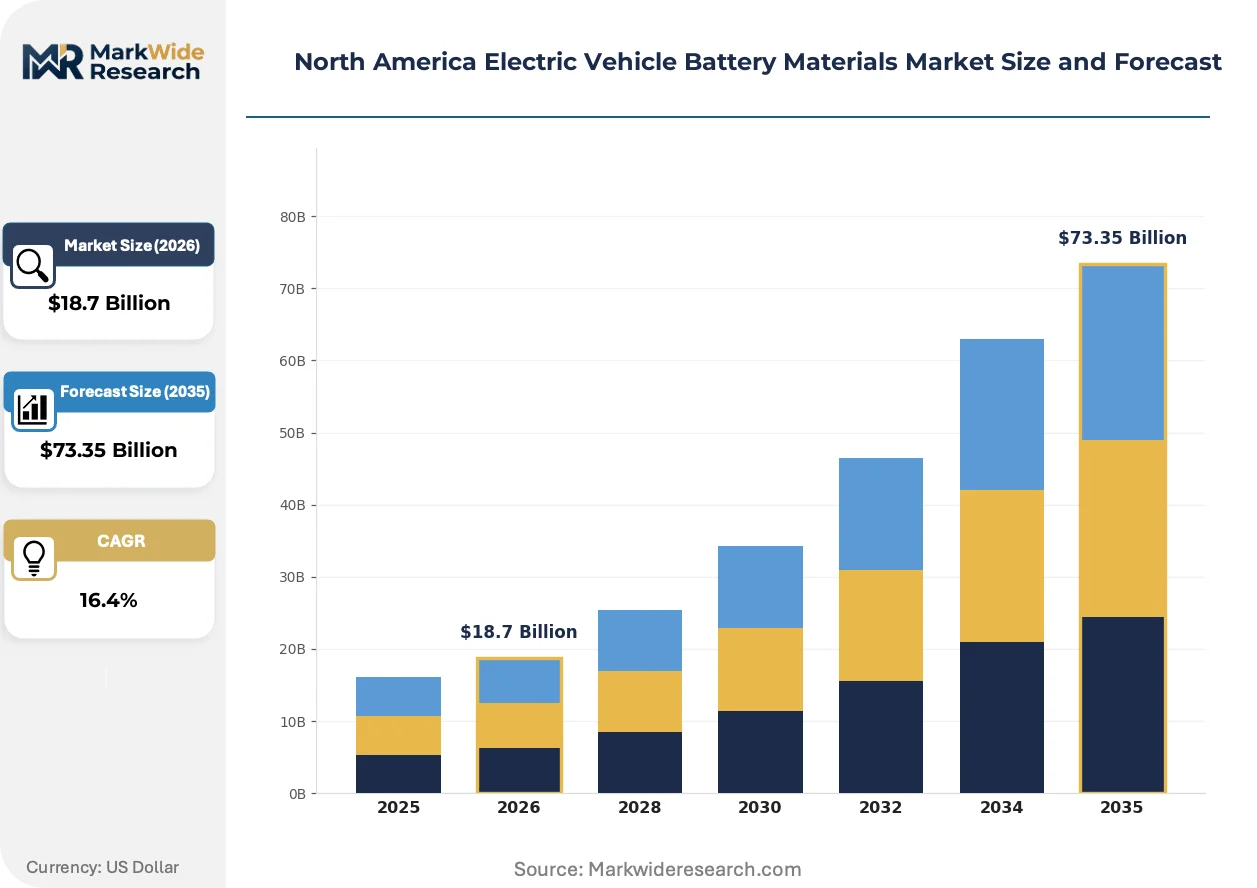
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium Ion, Nickel Cobalt Manganese, Solid State, Lithium Iron Phosphate Battery Chemistry: LFP, NCA, NMC, Li-S End User: OEMs, Aftermarket Providers, Fleet Operators, Retailers Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Targray Technology International Inc., BASF SE, Mitsubishi Chemical Group Corporation, UBE Corporation, Umicore, ENTEK, Asahi Kasei Corporation, Celgard LLC, Nichia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Materials Market Trends and Innovations
Material innovation trajectories are diverging across chemistry, form factor, and manufacturing process, with regulatory compliance and range targets pulling development in conflicting directions.
Dry-process electrode coating is fragmenting cathode manufacturing economics by eliminating solvent recovery infrastructure and reducing energy intensity. Korean and Japanese equipment suppliers are shipping coating lines to Kentucky and Ohio plants. The technology is compressing capital requirements for new entrants while fragmenting incumbent wet-process equipment installed bases.
IRA domestic content rules administered through Treasury and IRS guidance are reshaping mineral sourcing decisions, forcing OEMs to trace lithium from Nevada brine and Quebec spodumene through to finished cells. The regulation most acutely affects cathode active material suppliers, who must document North American conversion steps to preserve customer tax credit eligibility.
Fleet procurement departments are consolidating battery material specifications across light-, medium-, and heavy-duty vehicle programs, pressuring suppliers to qualify single chemistry platforms for multiple duty cycles. Direct contracting between logistics operators and cell manufacturers is displacing tiered automotive supply chain intermediaries in California and Texas commercial vehicle markets.
North America Electric Vehicle Battery Materials Market Segmentation
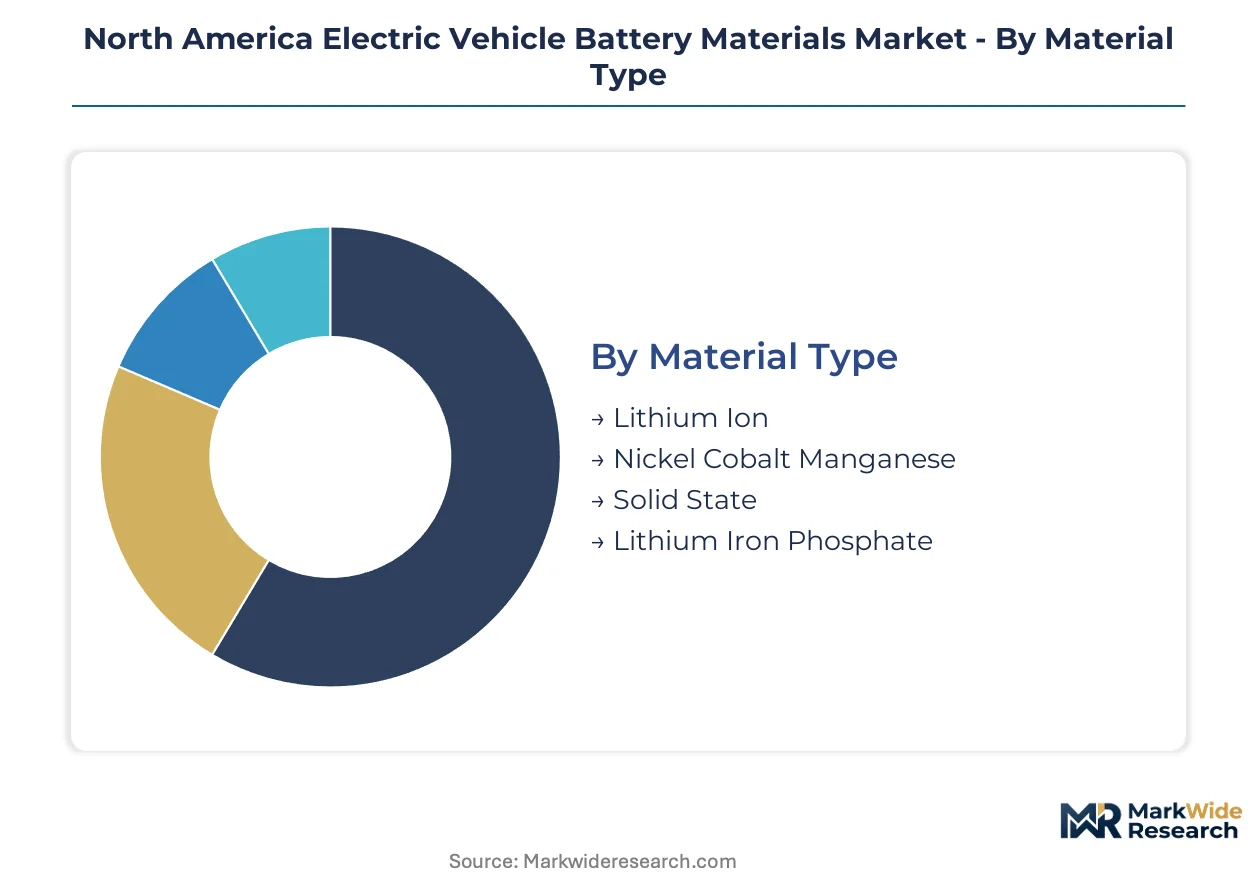
Material specification cascades through chemistry selection, procurement channel, and end-use application, with IRA domestic content rules forcing traceability at every tier. Segment boundaries are blurring as OEMs consolidate specifications across light- and heavy-duty platforms.
Material Type:
Channel flow varies sharply by material maturity—established cathode precursors move through distributor networks while novel solid-state electrolytes ship direct from pilot plants to cell engineering teams.
- Lithium Ion:Encompasses carbonate and hydroxide salts refined from Nevada brine and Quebec spodumene, with hydroxide dominating high-nickel cathode formulations. Cell producers in Michigan and Tennessee offtake through long-term contracts tied to IRA credit eligibility.
- Nickel Cobalt Manganese:Delivers highest gravimetric energy density among commercial cathode families, enabling 300+ mile range in electric pickups. NCM 811 and 9½½ formulations concentrate demand around Detroit OEM long-range programs, though cobalt sourcing constraints complicate compliance documentation.
- Solid State:Sulfide and oxide electrolyte chemistries promise energy density gains and thermal stability, but dry electrode processing yield gaps block volume ramp. Pilot shipments flow direct to cell R&D centers, bypassing conventional material distributors.
- Lithium Iron Phosphate:Iron and phosphate precursors cost less than nickel and cobalt, supporting entry-level passenger and commercial vehicle price points. Mexican assembly plants are expanding LFP pack sourcing for regional fleet deployment.
Lithium Ion dominates installed base. Solid State is where expansion concentrates.
Battery Chemistry:
Cost tier stratification separates premium range applications from cycle-life-focused commercial deployment, with chemistry selection locking in downstream material procurement for a decade.
- LFP:Lithium iron phosphate cells cycle 3,000+ times with minimal capacity fade, suiting delivery vans and school buses with predictable daily routes. Kentucky separator plants supply dry-process polypropylene membranes optimized for LFP voltage windows.
- NCA:Nickel cobalt aluminum cathodes maximize energy density in luxury sedans, though aluminum doping adds processing complexity. Tesla's Nevada cell production anchors North American NCA demand.
- NMC:Nickel manganese cobalt formulations balance energy density and thermal stability across 523, 622, and 811 ratios. Michigan gigafactories qualify multiple NMC variants to hedge nickel price volatility.
- Li-S:Lithium-sulfur chemistry offers theoretical energy density multiples above insertion oxides, but polysulfide shuttle and cycle life barriers confine deployment to defense and aerospace prototypes.
NMC commands revenue concentration. LFP is climbing the fastest.
End User:
Procurement authority is shifting from tiered automotive supply chains toward direct OEM and fleet operator contracting, fragmenting traditional distributor relationships.
- OEMs:Detroit automakers and Tesla negotiate cathode active material supply directly with BASF and Umicore, bypassing legacy tier-one powertrain suppliers. IRA credit documentation requirements force granular supply chain visibility.
- Aftermarket Providers:Independent repair networks and remanufacturers source replacement cells through distributors, though battery pack sealing and thermal management complexity limits addressable scope.
- Fleet Operators:Logistics companies in California and Texas contract directly with cell manufacturers for commercial vehicle programs, consolidating specifications across light-, medium-, and heavy-duty platforms.
- Retailers:Auto parts chains and e-commerce platforms move consumer-grade battery accessories and diagnostic tools, with minimal penetration into high-voltage cell commerce.
OEMs dominate installed base. Fleet Operators is where expansion concentrates.
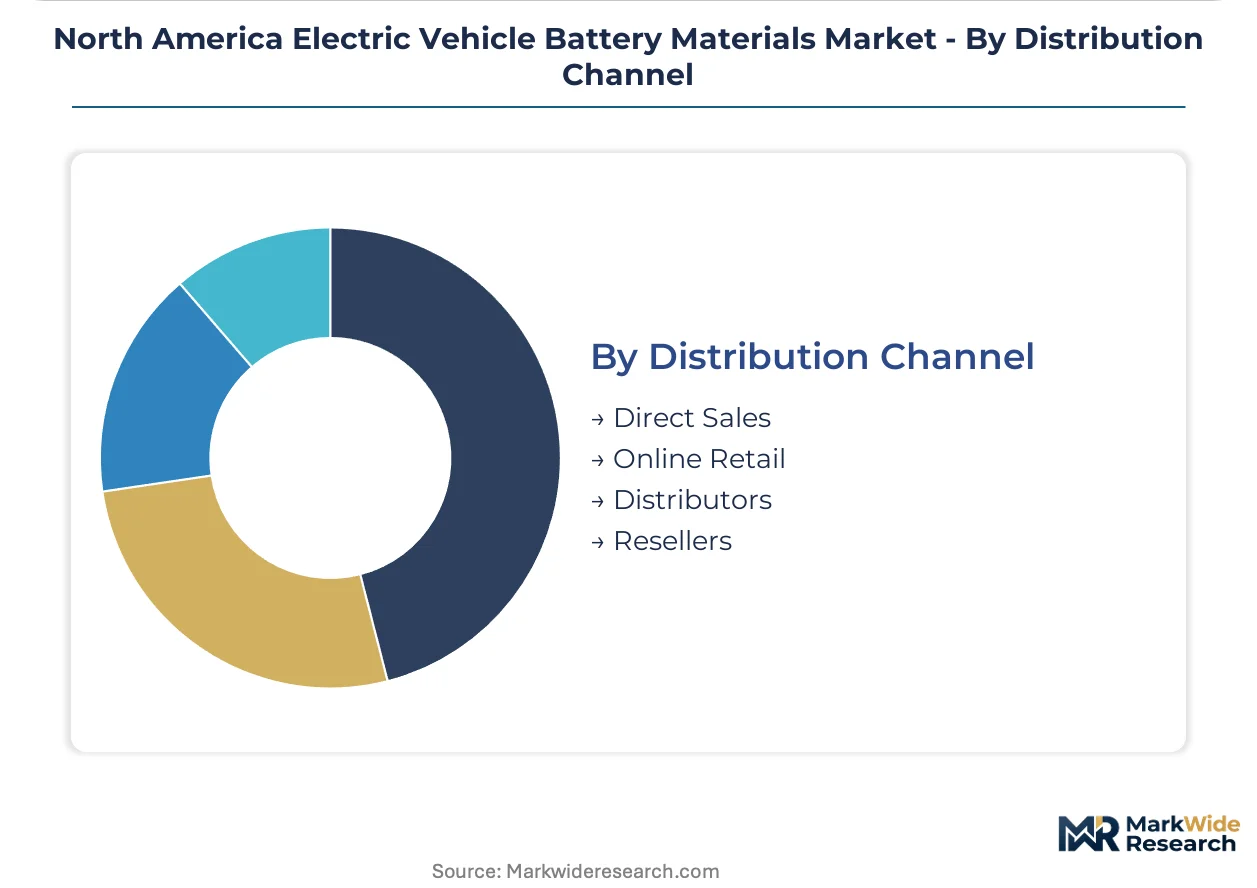
Distribution Channel:
Supply concentration dictates channel structure—bulk precursor chemicals flow through integrated producer networks while specialty electrolyte additives reach formulators via chemical distributors.
- Direct Sales:Cathode active material producers ship railcar quantities to gigafactory receiving facilities, with quality agreements specifying particle size distribution and trace metal limits.
- Online Retail:Laboratory-grade battery materials and research quantities move through specialized chemical marketplaces, serving university and startup cell development programs.
- Distributors:Univar and Brenntag manage electrolyte salt and solvent logistics, blending formulations to customer specifications in regional facilities.
- Resellers:Secondary market participants broker surplus manufacturing scrap and end-of-life pack materials into Ontario and Ohio recycling facilities.
Direct Sales dominates installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act anchors North American battery material demand through escalating domestic content thresholds. Treasury and IRS guidance pulls cathode and precursor production toward Michigan and Tennessee gigafactory clusters. Canada and Mexico complete the regional supply chain through mineral processing and assembly integration.
United States
Michigan and Tennessee battery gigafactories concentrate cathode active material demand for Detroit OEM long-range electric pickup programs. NHTSA battery safety protocols and UL 9540A thermal runaway testing shape cell architecture decisions. Kentucky separator plants supply dry-process polypropylene membranes to regional cell producers.
Canada
Quebec spodumene and Ontario recycling facilities anchor North American lithium and secondary nickel-cobalt supply. Federal critical minerals strategy accelerates midstream conversion capacity buildout. Ontario closed-loop recovery plants process manufacturing scrap and end-of-life packs for regional cathode producers.
Mexico
Northern border states integrate lithium iron phosphate pack assembly for commercial vehicle fleet deployment. Mexican assembly plants expand LFP sourcing to serve entry-level passenger and delivery van markets. Nearshoring trends pull electrolyte and separator logistics toward Baja California and Nuevo León distribution nodes.
North America Electric Vehicle Battery Materials Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Cathode active material specialists compete against diversified chemical conglomerates with integrated precursor networks. Strategic moves concentrate on capacity expansion near gigafactory clusters and backward integration into mineral conversion. Partnership structures with OEMs lock in offtake volumes and IRA credit eligibility documentation.
Within the diversified chemical tier, BASF SE and Umicore occupy positions defined by regional pilot line investments and closed-loop recovery capabilities. ENTEK anchors the separator film segment through Kentucky manufacturing presence. These three exemplify how European-headquartered specialists have captured North American battery corridor positioning through targeted facility deployment rather than broad portfolio expansion.
| Leading Market Players |
|---|
| Targray Technology International Inc. |
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| UBE Corporation |
| Umicore |
| ENTEK |
| Asahi Kasei Corporation |
| Celgard LLC |
| Nichia Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode active material lead times from pilot line qualification to gigafactory receiving dock concentrate pricing power with integrated producers possessing captive precursor networks, while spot-market lithium hydroxide buyers absorb volatility from Quebec and Nevada conversion bottlenecks.
Pricing Analysis
Contract spreads between Michigan NCM cathode deliveries and Mexican LFP pack assemblies widen as IRA domestic content documentation commands premium qualification overhead. Pricing stratifies across premium, standard, and economy tiers based on trace metal certification thresholds and volume scale commitments. Cost compression in entry-level LFP chemistries intensifies because Chinese precursor imports undercut regional conversion economics. Fleet operators exhibit highest price sensitivity, while Detroit OEMs prioritize supply security over unit economics.
Supply Chain Analysis
Nevada-Toronto rail corridor chokepoints constrain lithium hydroxide flow to Michigan cathode plants, amplifying inventory carrying costs for non-integrated cell producers. North American battery material supply draws from Quebec spodumene, Ontario recycling recovery, and Kentucky separator manufacturing. Raw material dependencies center on lithium brine conversion, nickel sulfate refining, and dry-process polypropylene membrane supply. Single-source vulnerability concentrates in DRC-origin cobalt routing through European refiners. Distribution runs through direct railcar contracts from cathode producers to gigafactory receiving facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where IRA domestic content thresholds create switching costs that lock OEMs into qualified supplier relationships for decade-long platform cycles.
For Market Incumbents: Fortify backward integration into Quebec lithium conversion and Ontario recycling recovery to defend against Korean cathode producers establishing US tolling arrangements. Secure captive nickel sulfate supply from Midwest processing investments before midstream capacity gaps force spot-market exposure. Prioritize UL 9540A thermal runaway certification depth as a barrier to European separator film entrants. For New Entrants and Emerging Players: Anchor in Mexican LFP pack assembly for commercial vehicle fleet deployment, the most penetrable segment given minimal incumbent qualification overhead. Exploit underdeveloped electrolyte additive formulation capacity in the Southeast battery corridor. Pursue direct qualification with California logistics operators bypassing tiered automotive supply hierarchies. For Investors and Strategic Acquirers: Long-term, this sits as a stranded-asset-avoidance play because legacy powertrain material suppliers face disintermediation as cathode procurement bypasses established automotive tiers. Target midstream conversion specialists with Quebec or Nevada lithium hydroxide offtake agreements. Monitor EPA tailpipe standard stringency acceleration as the inflection signal for NCM demand compression versus LFP expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Quebec Lithium Conversion Capacity Buildout | Resolves midstream processing gaps threatening Michigan cathode plant feedstock security. |
| Kentucky Dry-Process Separator Expansion | Captures Southeast battery corridor demand from Tennessee and Georgia gigafactory clusters. |
| Ontario Closed-Loop Recycling Joint Venture | Recovers nickel and cobalt from end-of-life packs for regional cathode active material supply. |
| IRA Compliance Documentation Platform | Preserves customer tax credit eligibility through granular supply chain traceability systems. |
| Solid-State Electrolyte Pilot Line Investment | Positions for technology transition when dry electrode processing yields achieve commercial viability. |
Research Methodology
Desk research of SEC 10-K filings, customs trade records, and EPA regulatory dockets preceded structured interviews with cathode plant engineering directors, OEM platform procurement managers, and lithium conversion facility operators. Primary fieldwork with Kentucky separator manufacturers and Quebec mining executives validated secondary production capacity estimates. Bottom-up cell chemistry demand modeling triangulated against top-down EV sales forecasts from vehicle registration databases.
Variance decomposition across material type, battery chemistry, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions encompass cathode formulation ratios, pack integration duty cycles, and regional production cluster proximity. CAGRs derived from segment-level volume buildups incorporating IRA credit phase-in schedules and OEM electrification program announcements. Forecast inputs included NHTSA battery safety protocol evolution and Quebec hydroelectric power availability for conversion energy intensity.
Underlying assumptions cover sustained IRA domestic content threshold enforcement, with deviation risk concentrated in Treasury guidance relaxation or midstream processing capacity acceleration. Forecasts reflect modeled conditions without guarantee of realization. Practitioners should keep alternative scenarios live as EPA tailpipe standard stringency and solid-state manufacturing yield trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Auto Storage Battery Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market