
 Italy Electric Vehicle Battery Electrolyte Market | 2026-2036
Italy Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Battery Electrolyte Market Insights
Aftermarket service revenue for electrolyte analysis and cell refurbishment is reshaping margin distribution across Italy's battery value chain. BASF SE leverages its Ludwigshafen R&D footprint to sustain formulation leadership for high-voltage lithium-ion systems. Solvay SA anchors specialty polymer electrolyte production through its Italian manufacturing network. Umicore SA competes on precursor-to-electrolyte integration, controlling critical material flows into domestic cell plants.
Electric vehicle battery electrolyte comprises the ion-conducting medium—typically lithium salts dissolved in organic carbonate solvents such as ethylene carbonate and dimethyl carbonate—that enables lithium-ion transport between cathode and anode during charge and discharge cycles. Solid-state formulations employ sulfide or oxide ceramic conductors to eliminate flammability risks while enabling higher energy densities. Lithium-ion liquid electrolytes currently occupy the dominant share of Italian procurement volumes, though solid-state categories are attracting disproportionate R&D investment from domestic OEMs seeking next-generation performance. Gel polymer variants serve niche applications in portable devices and specialized energy storage installations where form-factor flexibility outweighs cost premiums.
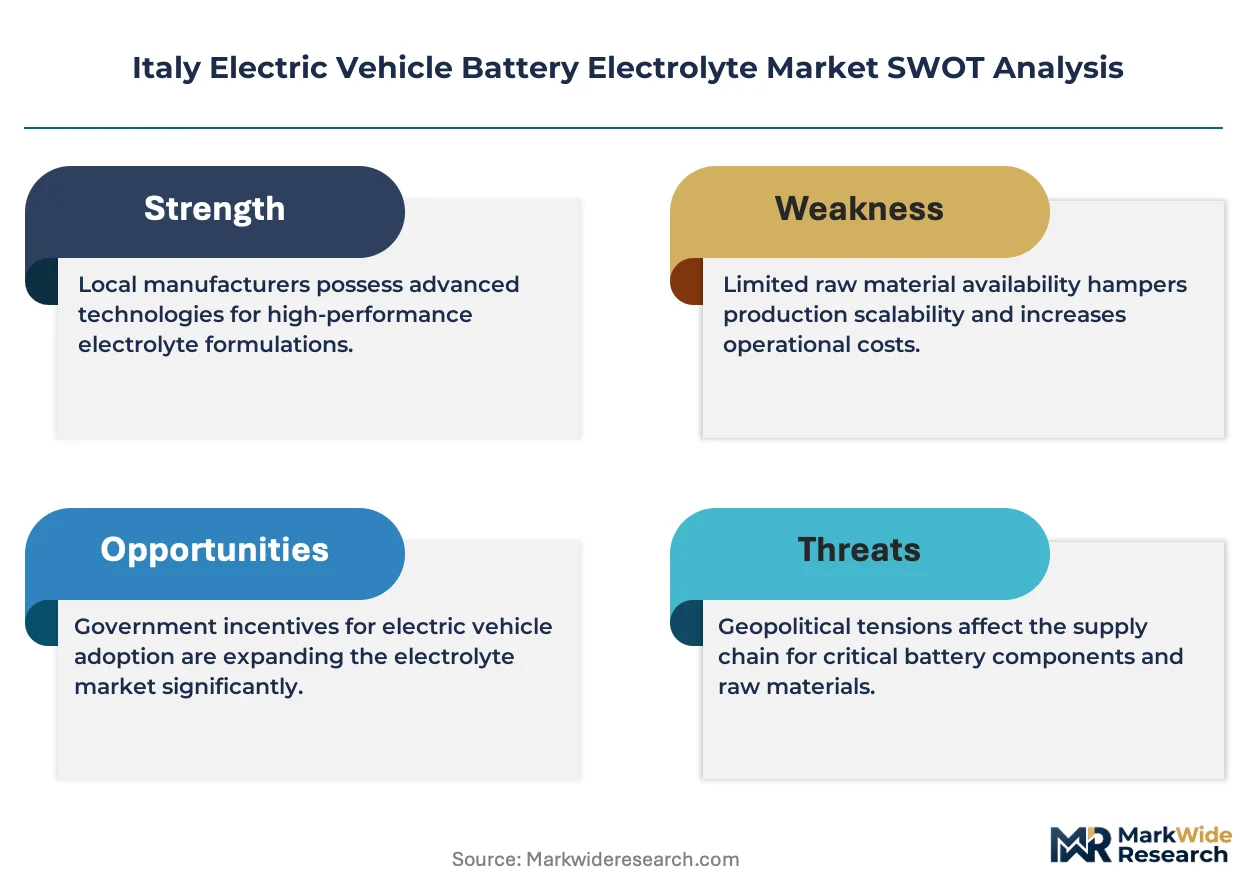
Italy's Ministry of Enterprise and Made in Italy, alongside the European Commission's REACH framework and EU Green Deal battery sustainability mandates, enforce chemical disclosure, carbon footprint labeling, and recycled content thresholds that directly shape electrolyte formulation decisions. The National Recovery and Resilience Plan allocates public capital to domestic battery gigafactory development, conditioning supplier access on compliance with these evolving standards. Stakeholders must monitor how forthcoming EU Battery Regulation secondary legislation affects electrolyte import qualifications and domestic blending requirements.
Market Dynamics
Italy's National Recovery and Resilience Plan is accelerating electrolyte localization by conditioning gigafactory subsidies on domestic blending capabilities, compressing supplier qualification timelines from 24 months to under 12 months for qualified formulators.
Growth Catalysts
- EU Green Deal battery sustainability mandates:Carbon footprint labeling requirements are forcing OEMs to source electrolytes from European blending facilities rather than Asian imports, redirecting procurement toward Italian producers.
- Solid-state ceramic conductors:Sulfide and oxide electrolyte formulations are attracting disproportionate R&D investment from Turin-based OEMs seeking next-generation energy density targets.
- Automotive electrification programs:Tier-one suppliers in Milan are coordinating directly with electrolyte producers for high-voltage cell designs, creating captive demand pipelines.
Market Restraints
- Lithium salt cost volatility:LiPF6 and LiFSI precursor prices fluctuate with Chinese export quotas, compressing margins for Italian blenders dependent on Asian chemical imports.
- REACH chemical disclosure requirements:ECHA's evolving substance registration thresholds force continuous reformulation, extending product development cycles by 8-14 months.
- Organic carbonate solvent supply concentration:Ethylene carbonate and dimethyl carbonate production clusters in Germany and Belgium create single-source vulnerability for Italian electrolyte manufacturers.
Strategic Opportunities
- Southern Italy gigafactory zones:Sicily and Puglia development corridors offer underutilized industrial land with preferential grid pricing for energy-intensive electrolyte blending operations.
- Stationary energy storage applications:Grid-scale battery deployments are creating demand for gel polymer electrolyte variants where form-factor flexibility outweighs automotive cost benchmarks.
- NRRP localization incentives:Public capital allocation for battery value-chain development covers 40-50% of capital equipment costs for domestic electrolyte production facilities.
Industry Challenges
- Electrochemist talent scarcity:Italian universities produce insufficient PhD-level specialists in solid-state ionic conductivity, forcing producers to recruit from German and Swiss research institutes.
- EU Battery Regulation certification timelines:Secondary legislation on recycled content thresholds remains unresolved, freezing long-term formulation investments until compliance pathways clarify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Battery Electrolyte Market |
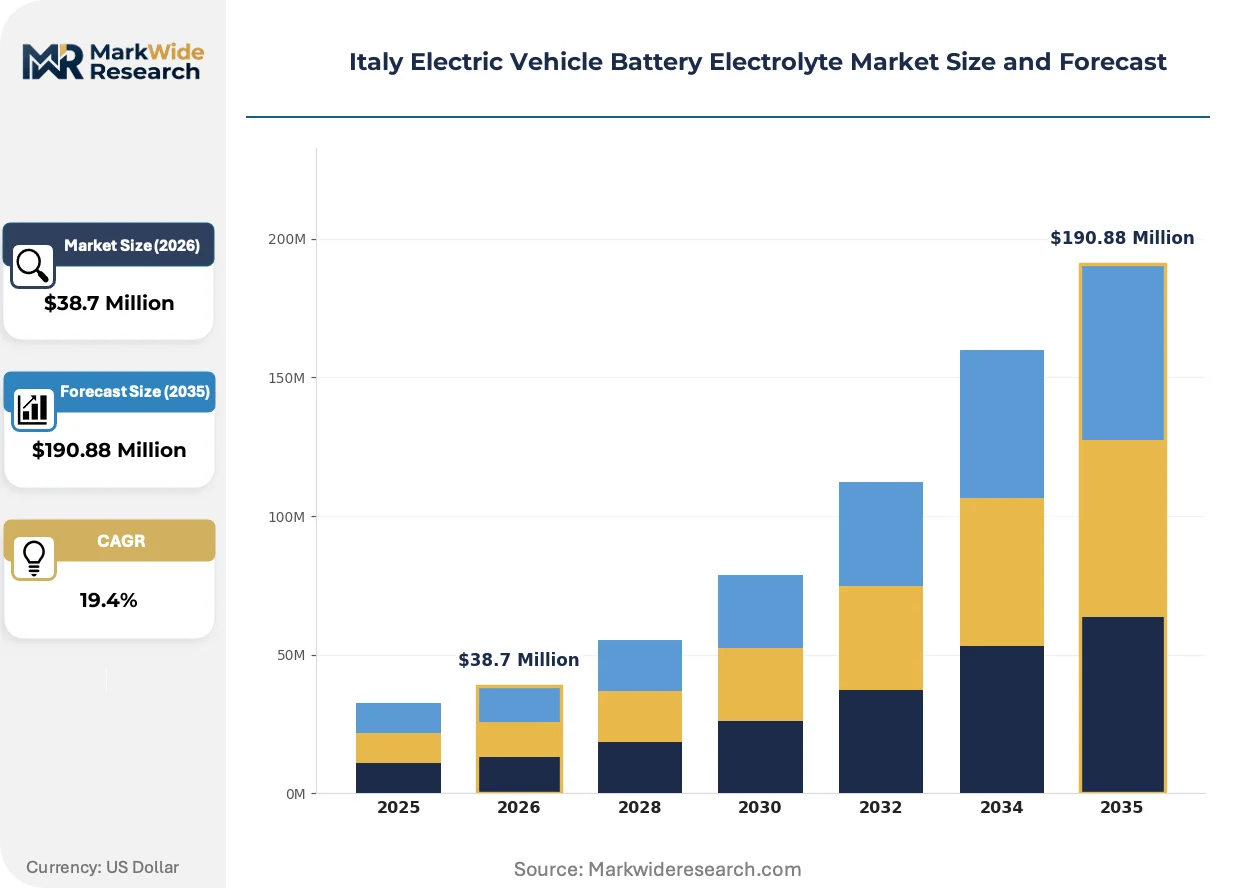
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid-state, Gel polymer, Hybrid End User: OEMs, Aftermarket Providers, Battery Manufacturers, Fleet Operators Form: Liquid, Gel, Powder, Solid Application: Automotive, Energy Storage, Portable Devices, Others |
| Companies Covered | Mitsubishi Chemical Group, 3M, Hitachi Ltd., BASF SE, Solvay SA, Umicore SA, Arkema SA, Sumitomo Chemical Co., Ltd, UBE Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte chemistry is fragmenting across three parallel development tracks as Italian producers balance immediate automotive qualification requirements against longer-term solid-state transition timelines.
Solid-state sulfide electrolytes are collapsing the traditional liquid electrolyte supply chain by eliminating separator and casing materials from cell architecture. Stellantis and Ferrari R&D programs in Modena are fast-tracking ceramic conductor validation for 800V platforms. This compression is forcing incumbent liquid electrolyte suppliers to diversify into polymer-gel intermediates or risk exclusion from premium vehicle programs.
REACH framework amendments on per- and polyfluoroalkyl substances are restricting fluorinated electrolyte additives previously standard in high-voltage formulations. Italian blenders must reformulate with phosphate-based flame retardants that degrade cycle life performance. Automotive OEMs are responding by relaxing fast-charge specifications to accommodate safer but less conductive electrolyte chemistries.
Direct supplier-OEM contracting is displacing distributor-mediated procurement for electrolyte volumes exceeding 500 tonnes annually. Tier-one cell manufacturers in Turin are establishing dedicated technical service agreements with formulators, embedding quality engineers at blending facilities. This channel consolidation is most advanced in the premium electric vehicle segment, where traceability requirements exceed standard industrial battery specifications.
Italy Electric Vehicle Battery Electrolyte Market Segmentation
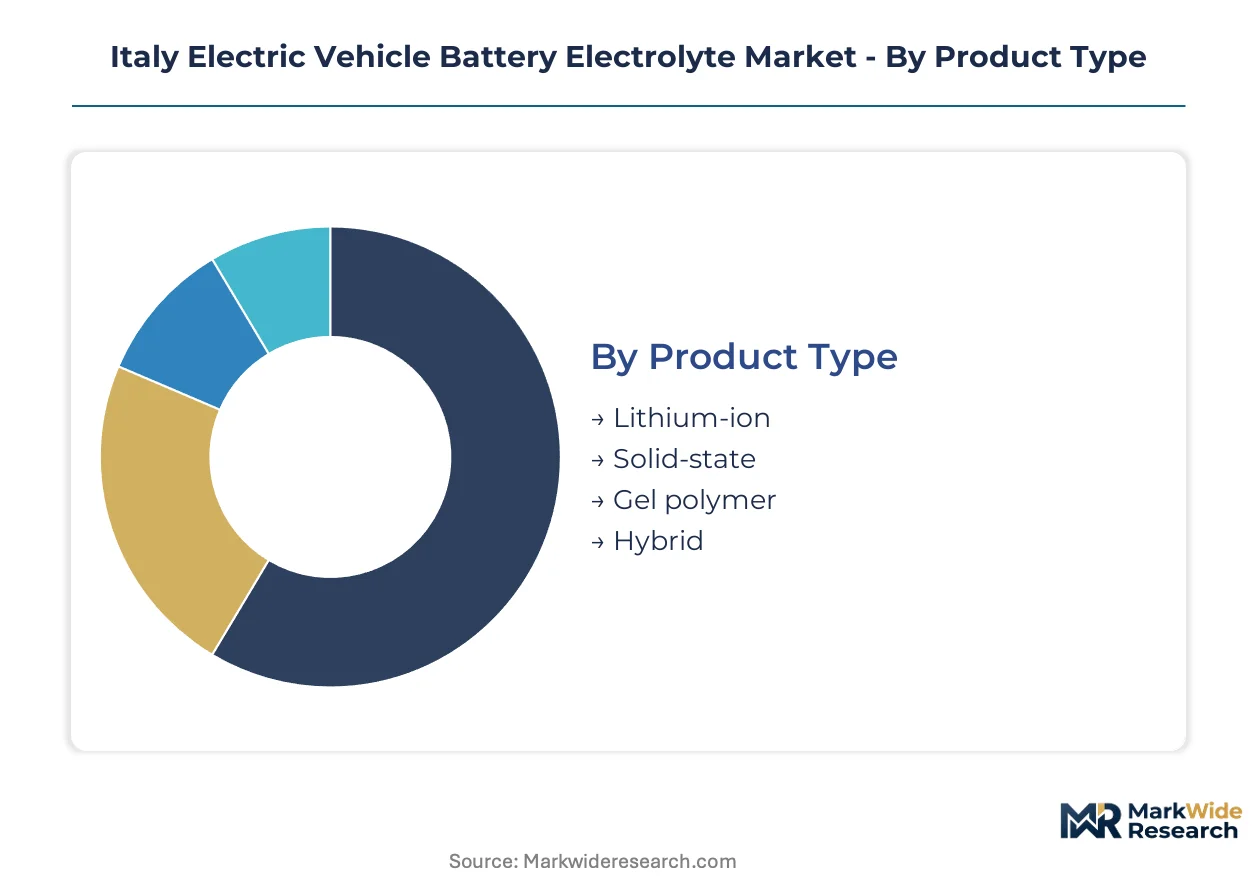
Electrolyte procurement cycles vary dramatically across Italy's battery value chain, with automotive qualification timelines stretching to 18 months while portable device formulations turn over quarterly. Understanding these velocity differentials helps suppliers align inventory and R&D investments with actual demand rhythms.
Product Type:
Lithium-ion formulations refresh annually as OEMs push for higher voltage tolerances, whereas solid-state categories operate on 5-7 year development horizons before commercial validation.
- Lithium-ion:Organic carbonate solvents dissolved with LiPF6 or LiFSI salts dominate Turin-Milan procurement corridors. Stellantis and Ferrari cell programs in Piedmont specify these formulations for 400-800V platforms, though REACH chemical disclosure requirements force continuous reformulation cycles.
- Solid-state:Sulfide and oxide ceramic conductors eliminate flammability risks while enabling energy density targets that liquid electrolytes cannot achieve. Modena-based R&D centers are fast-tracking these formulations for next-generation premium electric vehicles, compressing traditional supply chain architectures by removing separator materials.
- Gel polymer:Semi-solid matrices serve niche applications where form-factor flexibility outweighs cost premiums.
- Hybrid:Composite formulations blend liquid conductivity with polymer mechanical stability for transitional cell designs.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
End User:
Procurement scale and technical sophistication diverge sharply, with OEMs demanding embedded quality engineers at blending facilities while fleet operators prioritize unit economics over formulation customization.
- OEMs:Stellantis, Ferrari, and Lamborghini coordinate directly with electrolyte producers through dedicated technical service agreements, embedding traceability requirements that exceed standard industrial specifications. These partnerships cover volumes exceeding 500 tonnes annually.
- Battery Manufacturers:Tier-one cell producers in Milan and Turin serve as the critical intermediaries between formulators and vehicle programs, controlling qualification timelines and specification lock-ins.
- Aftermarket Providers:Service networks for electrolyte analysis and cell refurbishment concentrate in Northern Italy's industrial corridors.
- Fleet Operators:Commercial vehicle electrification programs in Lombardy and Veneto drive bulk procurement of standardized formulations.
Battery manufacturers intermediate the largest capital flows while OEMs capture the steepest margin expansion.
Form:
Manufacturing complexity and equipment amortization schedules separate high-volume liquid production from capital-intensive solid-phase operations.
- Liquid:Standard organic carbonate solutions flow through continuous blending equipment at Sicily and Puglia gigafactory zones, leveraging preferential grid pricing for energy-intensive operations.
- Gel:Semi-solid matrices require batch processing with precise viscosity control, limiting production scale.
- Solid:Ceramic conductor pressing and sintering demand cleanroom environments that concentrate production in specialized facilities.
- Powder:Precursor materials for solid-state cell assembly ship under controlled atmosphere protocols.
Liquid forms dominate production volumes while solid forms expand most quickly in R&D allocation.
Application:
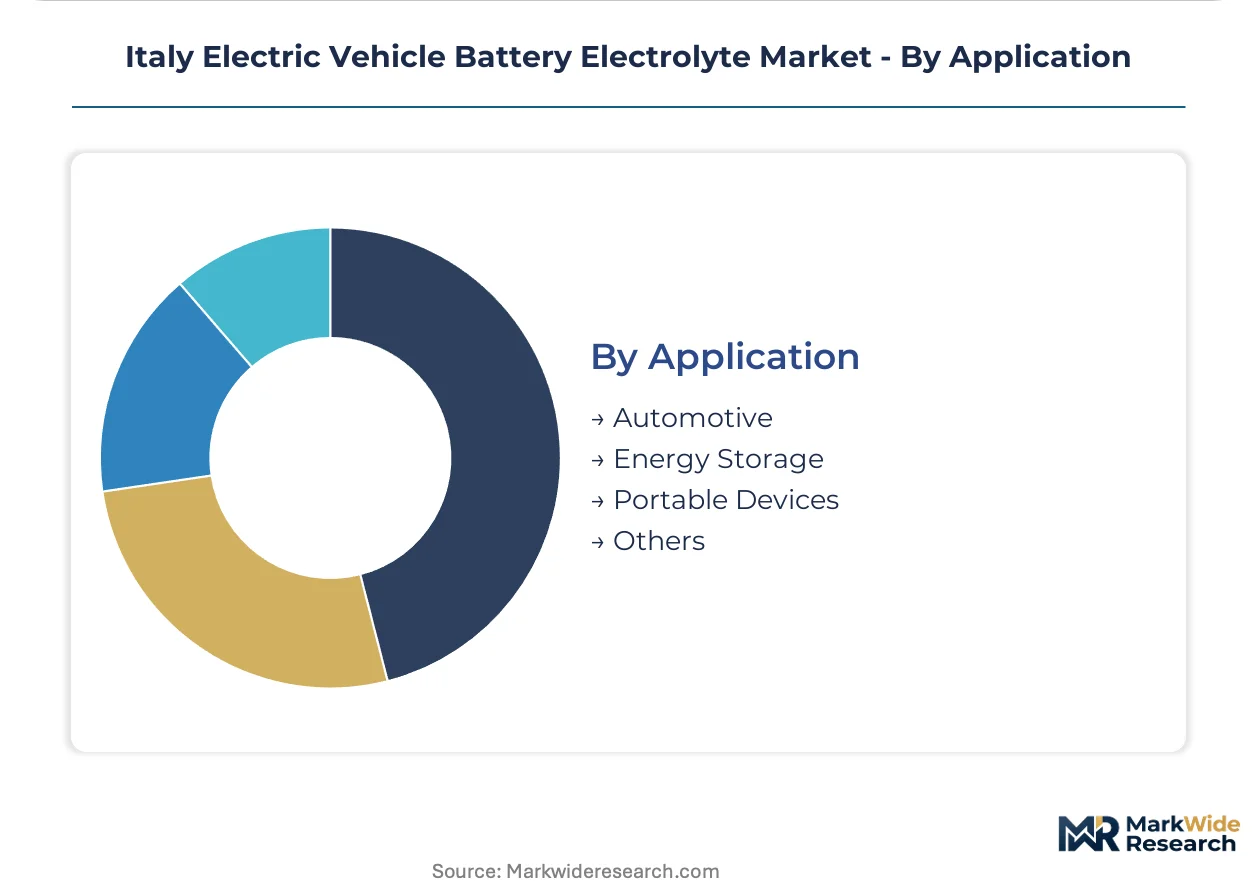
Performance specifications and certification burdens stratify the addressable market, with automotive applications demanding 10-year cycle life guarantees versus 3-5 year horizons for portable devices.
- Automotive:High-voltage cell designs for 800V platforms require electrolytes with oxidative stability above 4.5V, driving qualification investments that lock suppliers into multi-year supply agreements with Turin-based tier-one manufacturers.
- Energy Storage:Grid-scale battery deployments in Southern Italy create demand for gel polymer variants where form-factor flexibility and fire safety outweigh automotive cost benchmarks.
- Portable Devices:Consumer electronics specifications concentrate procurement in Lombardy's chemical processing clusters.
- Others:Specialized industrial and medical applications represent fragmented demand pockets.
Automotive anchors the revenue base while energy storage climbs the fastest in capacity deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyte consumption patterns diverge sharply across Italian sub-regions, with Northern industrial corridors driving automotive-grade volumes while Southern development zones attract energy-intensive blending operations through preferential infrastructure pricing.
Piedmont
Stellantis and Ferrari electrification programs in Turin generate concentrated demand for high-voltage lithium-ion formulations. Italy's Ministry of Enterprise and Made in Italy channels NRRP subsidies toward local cell manufacturing, accelerating supplier qualification timelines. The Torino-based battery cluster coordinates directly with electrolyte producers for 800V platform specifications.
Lombardy
Milan's tier-one cell manufacturers intermediate between formulators and OEMs, controlling procurement flows exceeding 500 tonnes annually. REACH chemical disclosure requirements from ECHA force continuous reformulation cycles for industrial chemical processors. The Lombard chemical corridor specializes in organic carbonate solvent blending for consumer electronics and automotive applications.
Veneto
Commercial fleet electrification programs in Verona and Padua drive bulk procurement of standardized electrolyte formulations. EU Green Deal carbon footprint labeling mandates redirect sourcing toward European blending facilities. The Veneto industrial zone concentrates aftermarket service networks for electrolyte analysis and cell refurbishment.
Sicily
Grid-scale energy storage deployments create demand for gel polymer variants where fire safety outweighs automotive cost benchmarks. NRRP localization incentives cover 40-50% of capital equipment costs for energy-intensive blending operations. The Sicily gigafactory development corridor leverages underutilized industrial land with preferential grid pricing.
Emilia-Romagna
Modena-based R&D centers fast-track solid-state ceramic conductor validation for premium electric vehicle programs. ECHA's evolving substance registration thresholds extend product development cycles for specialty chemical producers. The Emilia-Romagna automotive research cluster attracts disproportionate R&D investment from domestic OEMs seeking next-generation energy density targets.
Italy Electric Vehicle Battery Electrolyte Market Competitive Landscape
Capability concentration sits with specialty chemical multinationals possessing integrated precursor-to-electrolyte control; scale advantage sits with diversified materials conglomerates with cross-sector manufacturing footprints. The market structures around three archetypes: integrated chemical majors with lithium salt supply control, polymer specialists with proprietary formulation IP, and regional blenders serving captive automotive demand. Competitive moves center on backward integration into lithium salt production and strategic partnerships with tier-one cell manufacturers for qualification lock-ins.
Among European-headquartered chemical majors, BASF SE and Solvay SA exemplify divergent strategic positions—BASF anchoring integrated materials science capabilities across the value chain, Solvay occupying specialty polymer electrolyte production through Italian manufacturing infrastructure. Umicore SA represents the precursor-to-electrolyte integration archetype, controlling critical material flows into domestic cell plants. These three entities collectively illustrate how geographic proximity to automotive OEMs combines with regulatory compliance capabilities to shape competitive positioning under REACH and EU Battery Regulation frameworks.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| 3M |
| Hitachi Ltd. |
| BASF SE |
| Solvay SA |
| Umicore SA |
| Arkema SA |
| Sumitomo Chemical Co., Ltd |
| UBE Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
The Genoa-Rotterdam maritime corridor carries ethylene carbonate and dimethyl carbonate feedstocks from German and Belgian production clusters, with freight cost volatility translating directly into margin compression for Italian blenders and tiered pricing separation between automotive OEM contracts and industrial battery procurement.
Pricing Analysis
Long-term offtake agreements exceeding 500 tonnes annually lock in 18-month price stability for Stellantis and Ferrari cell programs, while spot procurement for sub-scale industrial buyers absorbs lithium salt cost volatility from Chinese export quota fluctuations. Price differentiation separates REACH-certified formulations for premium electric vehicles from uncertified industrial grades. Margins are tightening due to LiPF6 precursor price swings. Fleet operators in Veneto exhibit highest price sensitivity; OEMs in Piedmont prioritize qualification security over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as Italian blenders finance working capital gaps created by Asian lithium salt procurement. Supply concentrates in China for LiPF6 and LiFSI precursors, Germany for ethylene carbonate, and Belgium for dimethyl carbonate. Feedstock dependencies include lithium hexafluorophosphate, organic carbonate solvents, and ceramic oxide powders. Single-source vulnerability in German ethylene carbonate production creates exposure to Rhine logistics disruptions. Distribution runs through tier-one cell manufacturers in Milan and Turin who control qualification access to OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent electrolyte formulators face substitution pressure from solid-state ceramic conductor architectures that eliminate liquid electrolyte demand entirely, requiring defensive repositioning before sulfide and oxide technologies achieve automotive qualification.
For Market Incumbents: Pre-empt qualification lock-outs by embedding technical service teams at Stellantis and Ferrari R&D facilities in Modena, securing multi-year supply agreements before solid-state technologies reach commercial validation. Accelerate backward integration into lithium salt precursor production to reduce exposure to Chinese export quota volatility. Prioritize gel polymer formulation capabilities for grid-scale energy storage applications where liquid electrolyte substitution is less advanced.
For New Entrants and Emerging Players: Southern Italy gigafactory zones in Sicily and Puglia represent the most penetrable entry point, leveraging NRRP capital equipment subsidies covering 40-50 percent of blending facility costs and preferential grid pricing for energy-intensive operations. Stationary energy storage applications for gel polymer variants offer lower qualification barriers than automotive programs. Establish direct contracting relationships with tier-one cell manufacturers rather than distributor-mediated channels.
For Investors and Strategic Acquirers: Specialty polymer electrolyte producers with Italian manufacturing infrastructure and REACH compliance capabilities present the most defensible acquisition targets, capturing value from regulatory barriers that exclude Asian competitors. Long-term viability hinges on successful navigation of the 5-10 year transition window between liquid electrolyte dominance and solid-state ceramic conductor adoption. Monitor ECHA substance registration threshold amendments as the critical inflection signal for formulation investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Production | Captive LiPF6 supply from Ludwigshafen or Antwerp insulates BASF and Solvay from Chinese export quota volatility. |
| Solid-State Electrolyte Joint Venture | Modena-based R&D partnerships with Stellantis accelerate ceramic conductor validation for 800V platforms. |
| REACH Compliance Certification Program | ECHA-aligned disclosure capabilities unlock premium automotive contracts exceeding 500 tonnes annually. |
| Southern Italy Gigafactory Zone Expansion | Sicily and Puglia facilities leverage NRRP subsidies and preferential grid pricing for blending operations. |
| Aftermarket Service Network Development | Northern Italy electrolyte analysis and cell refurbishment capabilities capture recurring revenue from fleet operators. |
Research Methodology
Initial hypotheses were tested against primary input from electrolyte formulator technical directors, tier-one cell manufacturer procurement leads, OEM platform engineers, and ECHA regulatory affairs specialists, and refined through secondary validation against SEC filings from BASF and Umicore, Italian customs trade data, EU Battery Regulation draft texts, and IHS Markit vehicle production databases. Bottom-up electrolyte volume estimates from individual gigafactory announcements were triangulated against top-down automotive electrification program targets.
Demand-supply balance modeling across the projection horizon segmented procurement by electrolyte form, end-user archetype, and regional production cluster, with automotive application content per vehicle serving as the core volume driver. CAGRs were derived from fitted growth curves calibrated to NRRP subsidy disbursement timelines and OEM platform launch schedules. Solid-state technology readiness levels and REACH amendment implementation timelines provided scenario-boundary inputs.
Macroeconomic conditions sit as an overlay; deviation in euro-yuan exchange rates, Rhine water levels affecting German chemical logistics, or lithium carbonate spot prices would shift the trajectory. Forecasts reflect documented assumptions on subsidy continuity, regulatory implementation pacing, and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market