
 Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market Insights
The capital-intensity divergence between integrated European equipment suppliers and regional assembly specialists is unwinding competitive dynamics across the Middle East and Africa. Manz AG leverages its precision coating and cell assembly expertise to anchor premium positioning in Gulf state gigafactory projects. Buhler AG sustains technology leadership through its dry-electrode processing platforms, while Sovema Group S.p.A specializes in formation and testing equipment tailored to emerging African battery assembly hubs.
Middle East and Africa electric vehicle battery manufacturing equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and end-of-line validation, typically operating at precision tolerances below 10 micrometers to ensure cell energy density and safety performance. Assembly machines dominate current procurement volumes as greenfield factories in Morocco and the UAE prioritize full-line integration, while solid-state technology segments attract accelerated R&D investment from research institutions seeking next-generation cell architectures. Testing systems capture concentrated margin pools due to stringent certification requirements imposed by automotive OEMs sourcing locally manufactured battery packs.
Saudi Arabia's SFDA and the UAE's MOHAP coordinate industrial safety standards for chemical handling in battery plants, while South Africa's central energy regulator enforces grid-interconnection protocols for formation and charging equipment. The EU Green Deal's extraterritorial carbon-border adjustments increasingly shape export-oriented facility design decisions across North African manufacturing zones. Stakeholders must monitor how Gulf sovereign wealth fund commitments to domestic EV value chains redirect equipment procurement from turnkey European imports toward joint-venture localization models.
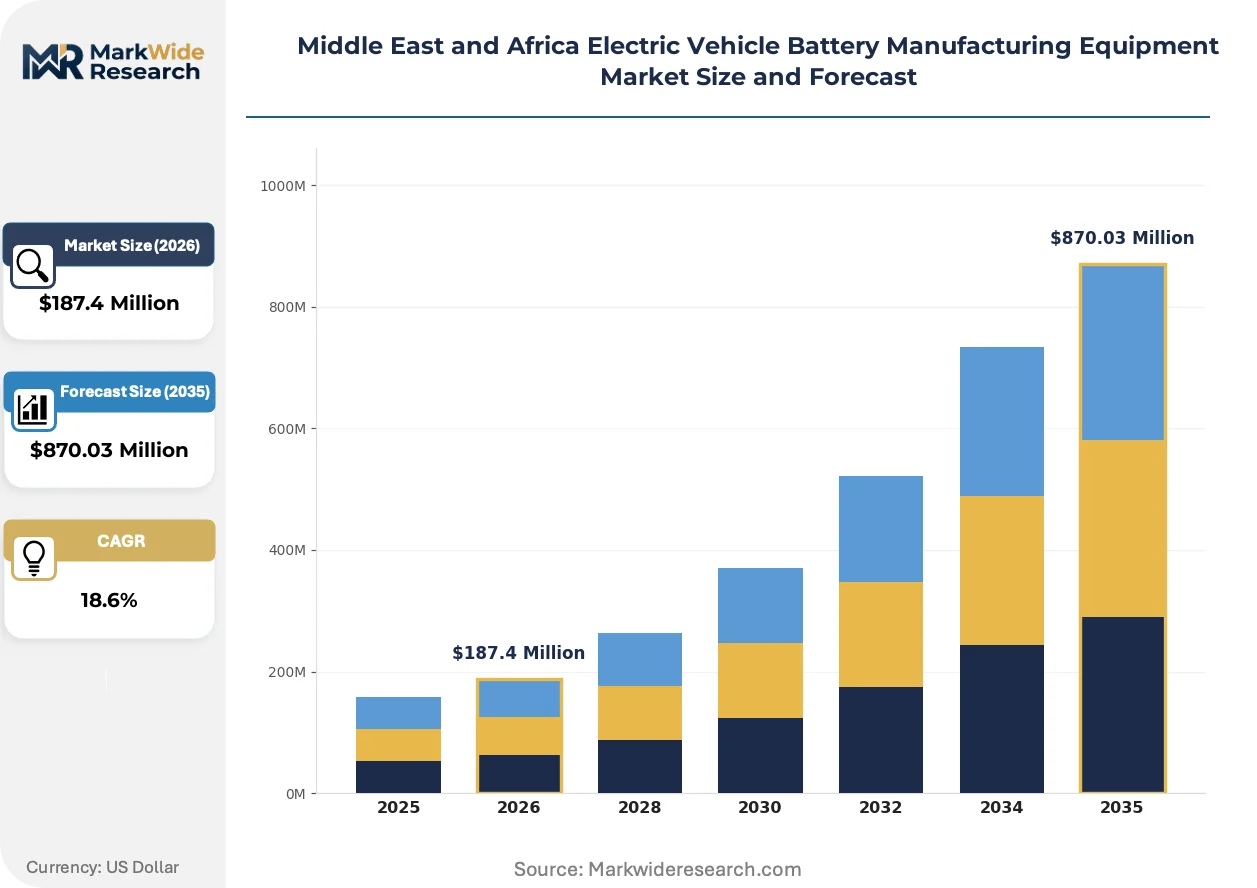
Market Dynamics
Gulf sovereign wealth funds are redirecting capital from hydrocarbon portfolios into domestic EV value chains, compressing equipment procurement timelines and favoring joint-venture localization models over turnkey European imports.
Growth Catalysts
- Saudi Vision 2030 industrial localization mandates:Domestic content requirements for gigafactory projects are accelerating demand for electrode coating and cell assembly machinery within the Kingdom.
- Morocco's phosphate-based cathode precursor ecosystem:Concentrated phosphate mining and processing infrastructure is pulling formation and testing equipment toward North African assembly hubs.
- Dry-electrode processing platforms:Elimination of toxic solvent handling is reducing plant permitting complexity and accelerating greenfield project approvals across water-scarce Gulf states.
Market Restraints
- Specialized technician scarcity:Precision calibration expertise for sub-10-micrometer tolerance equipment remains concentrated in European and East Asian labor pools.
- Grid-interconnection bottlenecks:South Africa's central energy regulator enforces formation equipment protocols that extend commissioning timelines for high-capacity cycling systems.
- Lithium hydroxide import dependency:Precursor chemical supply chains route through Asian processing hubs, exposing equipment utilization rates to maritime logistics volatility.
Strategic Opportunities
- Second-life battery refurbishment:Aging automotive packs from early GCC fleet deployments are creating demand for disassembly and diagnostic machinery in UAE service hubs.
- Solid-state R&D convergence:Research institutions in Saudi Arabia and the UAE are co-investing in sulfide electrolyte deposition equipment for next-generation cell architectures.
- EU Green Deal carbon-border alignment:North African export-oriented facilities are retrofitting formation systems to capture embodied carbon data for European OEM compliance.
Industry Challenges
- Multi-standard certification complexity:Equipment must simultaneously satisfy SFDA chemical handling protocols, MOHAP industrial safety frameworks, and automotive OEM validation requirements.
- Legacy system integration friction:Brownfield industrial sites in South Africa's mining belt face structural incompatibility between existing power infrastructure and high-precision formation cycling loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Assembly Machines, Testing Systems, Charging Equipment, Handling Tools Application: Battery Production, Quality Control, Research & Development, Maintenance End User: Automotive Manufacturers, Battery Producers, Research Institutions, Suppliers Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Others |
| Companies Covered | Manz AG, Hitachi Ltd., Sovema Group S.p.A, Wirtz Manufacturing, Buhler AG, SunPower Corporation, Panasonic Holdings Corporation, C&D Technologies Inc., Exide Industries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment architecture is pivoting from standardized European turnkey lines toward modular, regionally configurable systems that accommodate divergent feedstock chemistries and localized regulatory overlays.
Dry-electrode coating technology is fragmenting the incumbent solvent-based equipment installed base. Saudi Aramco-funded gigafactories are piloting binder-free calendaring systems that eliminate N-methylpyrrolidone recovery infrastructure. This compression of plant footprint and permitting scope is enabling faster commissioning cycles in greenfield desert locations where water access constrains traditional wet-process economics.
EU Green Deal carbon-border adjustment mechanisms are reshaping North African facility design. Moroccan phosphate-to-cathode plants are retrofitting formation equipment with embedded emissions tracking to satisfy European OEM Scope 3 documentation requirements. Battery pack exports from Tangier-Med industrial zones now require granular carbon intensity data that legacy testing systems cannot capture, forcing equipment refresh cycles ahead of typical depreciation schedules.
Buyer concentration among Gulf sovereign-backed OEMs is consolidating procurement leverage. Abu Dhabi and Riyadh-based vehicle manufacturers are negotiating multi-site equipment frameworks that bundle electrode coating, cell stacking, and end-of-line validation under single-source agreements. This aggregation is marginalizing smaller European specialists unable to guarantee cross-border service coverage across dispersed desert plant locations.
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market Segmentation
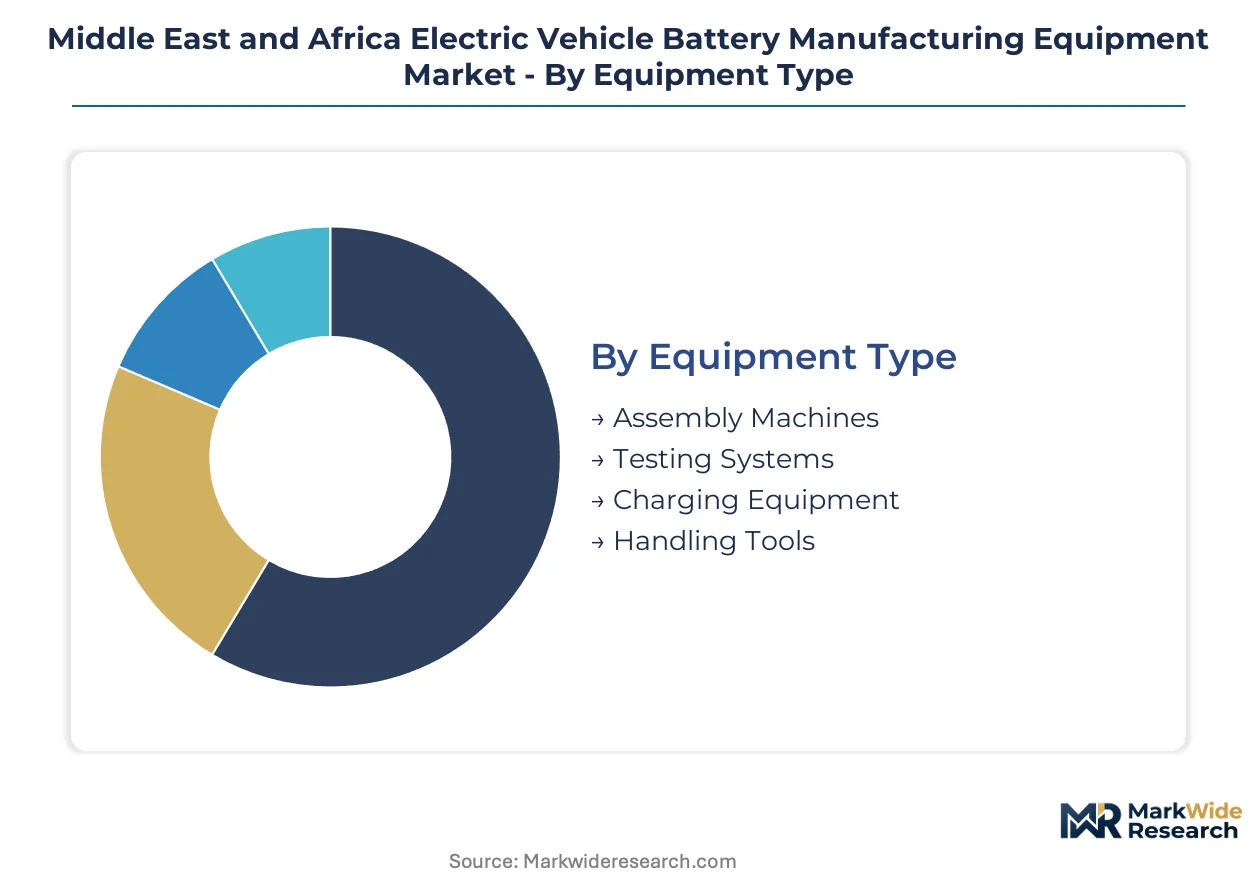
Equipment procurement patterns across the Middle East and Africa diverge sharply between Gulf sovereign-backed gigafactories and African mining-linked assembly hubs. Segmentation reveals how channel structures concentrate demand for precision machinery in specific geographies and end-use configurations.
Equipment Type:
Assembly machines flow primarily through turnkey European suppliers serving Gulf greenfield projects, while testing systems concentrate via specialized distributors into Moroccan and South African facilities.
- Assembly Machines:Electrode coating, cell stacking, and electrolyte filling systems operate at sub-10-micrometer tolerances. Procurement concentrates in Saudi Arabia and UAE gigafactories where domestic content mandates accelerate localized integration timelines.
- Testing Systems:Formation cycling and end-of-line validation equipment capture concentrated margin pools. Demand clusters in Morocco's phosphate-to-cathode corridor where European OEM certification requirements enforce stringent validation protocols.
- Charging Equipment:Grid-interconnection systems for formation cycling face commissioning bottlenecks in South Africa under central energy regulator protocols.
- Handling Tools:Automated material transport and chemical containment systems serve water-scarce Gulf states where solvent-free dry-electrode processing reduces infrastructure requirements.
Assembly machines dominate installed base. Testing systems are where expansion concentrates.
Application:
Cost tier differentiation separates high-precision battery production lines from lower-margin maintenance retrofit segments across regional procurement portfolios.
- Battery Production:Full-line integration of coating, stacking, and formation equipment. Procurement clusters in Morocco and UAE greenfield facilities where sovereign wealth capital compresses commissioning schedules.
- Quality Control:In-process inspection and end-of-line validation systems. Demand concentrates among automotive OEMs sourcing from Tangier-Med industrial zones requiring EU Green Deal carbon intensity documentation.
- Research & Development:Solid-state electrolyte deposition and sulfide chemistry pilot equipment. Investment flows to Saudi Aramco-funded research institutions and UAE technical universities.
- Maintenance:Diagnostic and refurbishment machinery for second-life battery processing. Emerging demand in UAE service hubs managing early GCC fleet retirements.
Battery production commands capital allocation. Quality control is climbing the fastest.
End User:
Customer type determines procurement leverage, with automotive manufacturers consolidating multi-site frameworks while research institutions negotiate discrete pilot-scale purchases.
- Automotive Manufacturers:Abu Dhabi and Riyadh-based OEMs bundle electrode coating, cell stacking, and validation under single-source agreements. Buyer concentration marginalizes smaller European specialists lacking cross-border service coverage.
- Battery Producers:Dedicated cell manufacturers serving regional supply chains. Procurement focuses on formation equipment compatible with Moroccan phosphate-derived cathode chemistries.
- Research Institutions:Saudi and UAE technical universities co-investing in solid-state R&D equipment. Purchases concentrate on sulfide electrolyte deposition platforms for next-generation architectures.
- Suppliers:Precursor chemical and component vendors requiring handling and testing machinery. Demand links to lithium hydroxide import logistics through Asian processing hubs.
Automotive manufacturers dominate procurement volume. Battery producers represent the steepest expansion trajectory.
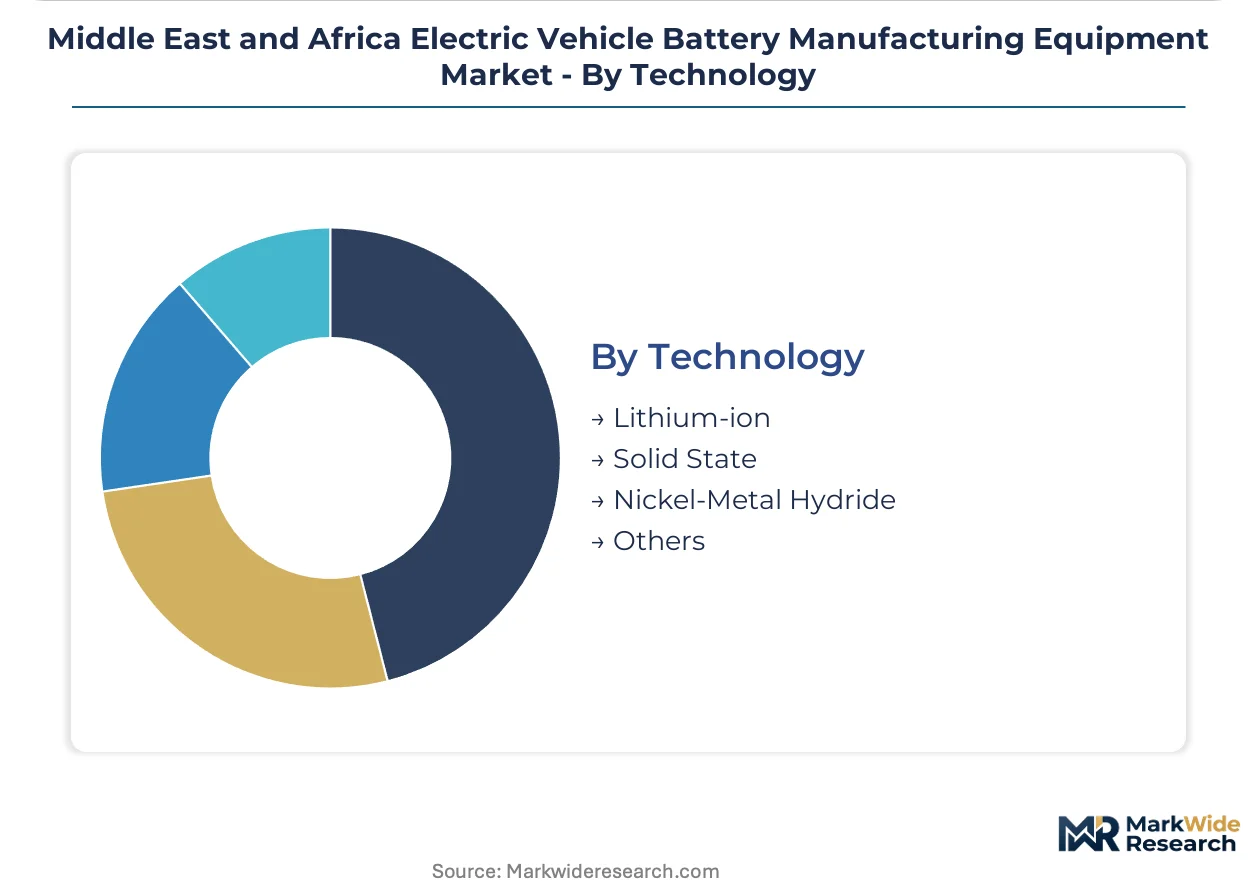
Technology:
Technology maturity segments the installed base between incumbent lithium-ion platforms and emerging solid-state architectures requiring specialized deposition equipment.
- Lithium-ion:Dominant chemistry for current gigafactory deployments. Equipment specifications accommodate NMC and LFP variants across Moroccan and Gulf assembly lines.
- Solid State:Sulfide and oxide electrolyte systems requiring novel deposition and sealing machinery. R&D investment concentrates in Saudi Aramco-funded facilities and UAE research clusters.
- Nickel-Metal Hydride:Legacy chemistry for hybrid vehicle applications. Limited equipment demand restricted to South African mining belt retrofit projects.
- Others:Sodium-ion and emerging chemistries. Pilot-scale equipment purchases by research institutions evaluating feedstock diversification.
Lithium-ion anchors current installed base. Solid state is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market balances import dependency against nascent domestic assembly capacity, with equipment flows concentrated through Gulf port infrastructure while African mining corridors develop localized precursor processing capabilities.
Saudi Arabia
SFDA chemical handling protocols and domestic content mandates under Vision 2030 are accelerating electrode coating and cell assembly machinery procurement. The Kingdom's sovereign wealth capital is compressing gigafactory commissioning timelines in Riyadh and the Eastern Province. NEOM's northwest industrial zone is piloting dry-electrode processing platforms that eliminate solvent recovery infrastructure.
United Arab Emirates
MOHAP industrial safety frameworks and Abu Dhabi-based OEM consolidation are driving multi-site equipment frameworks bundling full-line integration. Dubai's Jebel Ali port corridor serves as the primary entry point for European turnkey assembly systems. Sharjah's emerging technical universities are co-investing in solid-state R&D equipment alongside Saudi Aramco-funded research clusters.
Morocco
EU Green Deal carbon-border adjustments are forcing formation equipment retrofits to capture embodied carbon data for European OEM compliance. Tangier-Med industrial zones concentrate phosphate-to-cathode precursor processing that pulls testing and validation machinery toward North African assembly hubs. The country's mining-linked supply chain is localizing electrode material production for export-oriented battery pack manufacturing.
South Africa
The central energy regulator's grid-interconnection protocols are extending commissioning timelines for high-capacity formation cycling systems in the mining belt. Gauteng and Western Cape industrial zones face structural incompatibility between legacy power infrastructure and precision battery manufacturing loads. Lithium hydroxide import dependency through Asian processing hubs is exposing equipment utilization rates to maritime logistics volatility.
Israel
Research institution investment in next-generation cell architectures is creating demand for sulfide electrolyte deposition pilot equipment. Tel Aviv's technology corridor is converging with Gulf sovereign-funded R&D programs on solid-state chemistry development. The country's precision manufacturing heritage is transferring toward battery testing and diagnostic machinery for regional service hub deployment.
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Concentration sits with integrated European equipment suppliers holding turnkey integration capabilities, while regional assembly specialists occupy fragmented niches around testing and formation systems. German and Swiss precision engineering groups anchor premium positioning through sub-10-micrometer tolerance machinery. Japanese industrial conglomerates represent a second archetype leveraging dry-electrode processing platforms. Italian specialists exemplify the third tier focused on modular formation and diagnostic equipment. Dominant competitive moves include joint-venture localization partnerships with Gulf sovereign wealth vehicles and technology licensing agreements to circumvent turnkey import dependency.
Within the European integrated tier, Manz AG and Buhler AG exemplify precision coating and dry-electrode processing leadership respectively. Sovema Group S.p.A occupies a position among modular testing specialists serving emerging African assembly hubs. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive archetypes without requiring specific product or strategic claims.
| Leading Market Players |
|---|
| Manz AG |
| Hitachi Ltd. |
| Sovema Group S.p.A |
| Wirtz Manufacturing |
| Buhler AG |
| SunPower Corporation |
| Panasonic Holdings Corporation |
| C&D Technologies Inc. |
| Exide Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Equipment lead times stretching 14-18 months for precision coating systems from European suppliers concentrate pricing power with turnkey integrators serving Gulf sovereign-backed gigafactories, while modular testing equipment from Italian specialists commands shorter-cycle premiums in African assembly hubs.
Pricing Analysis
The customization-premium spread between configured-to-order electrode coating lines and standard formation equipment runs 35-45 percent, with project-based contracting dominating procurement for full-line integration. Price differentiation hinges on sub-10-micrometer tolerance certification tiers and after-sales service bundling across dispersed desert plant locations. Pricing pressure stems from buyer consolidation among Abu Dhabi and Riyadh-based OEMs negotiating multi-site frameworks. Automotive manufacturers show lowest price sensitivity given domestic content mandates, while research institutions exhibit highest sensitivity due to discrete pilot-scale purchasing.
Supply Chain Analysis
Germany, Switzerland, and Japan anchor precision machinery production for electrode coating and dry-electrode processing platforms serving Middle East and African markets. The regional supply chain draws from lithium hydroxide processed through Asian hubs, precision bearings from German industrial clusters, and automation controls from Japanese conglomerates. Single-source vulnerability concentrates in sub-10-micrometer calibration expertise held by European technician pools. Distribution runs through Jebel Ali and Tangier-Med port corridors with localized service partnerships for commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery equipment market is approaching a platform-economics inflection as modular, regionally configurable systems displace standardized European turnkey lines, with interoperability between dry-electrode and wet-process platforms reshaping competitive boundaries.
For Market Incumbents: Compound technology leadership in sub-10-micrometer precision coating through captive training academies addressing technician scarcity in Gulf states, while securing joint-venture localization partnerships with Saudi sovereign wealth vehicles to defend against Japanese dry-electrode platform encroachment.
For New Entrants and Emerging Players: Anchor in second-life battery refurbishment machinery for UAE service hubs managing early GCC fleet retirements, targeting diagnostic and disassembly equipment as the most penetrable segment with lowest incumbent concentration.
For Investors and Strategic Acquirers: Carve-out targets emerge from European industrial conglomerates spinning off battery-specific equipment divisions amid automotive electrification portfolio rebalancing. Long-term viability centers on sulfide electrolyte deposition capabilities for solid-state transitions. Watch Saudi Aramco-funded research institution procurement as the inflection signal for next-generation architecture adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | Gulf sovereign wealth partnerships compress commissioning timelines under Vision 2030 domestic content mandates. |
| Dry-Electrode Platform Migration | Solvent-free processing eliminates N-methylpyrrolidone recovery infrastructure in water-scarce Saudi locations. |
| Carbon-Border Data Integration | EU Green Deal alignment forces formation equipment retrofits for Scope 3 documentation in Moroccan export zones. |
| Technician Training Academy Buildout | Localized calibration expertise reduces dependency on European labor pools for precision maintenance. |
| Solid-State R&D Equipment Investment | Sulfide electrolyte deposition platforms capture early-mover positioning in Saudi and UAE research clusters. |
Research Methodology
Cross-validation between equipment procurement databases and regulatory filing repositories anchors the qualitative findings, combining primary interviews with gigafactory project directors, precision machinery procurement leads, and SFDA compliance officers with secondary validation through customs trade records, SEC filings of listed equipment suppliers, and EU Green Deal implementation documents. Bottom-up demand aggregation from individual facility announcements triangulates against top-down market sizing from regional automotive production forecasts.
Sensitivity analysis across lithium-ion chemistry variants, solid-state technology readiness levels, and sovereign wealth fund commitment timelines shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include equipment type, application tier, end-user category, and technology maturity. CAGRs derive from installed base growth rates adjusted for replacement cycles and greenfield capacity absorption patterns, with specific inputs from grid-interconnection protocol timelines and phosphate-to-cathode supply chain localization trajectories.
Material uncertainties — lithium hydroxide import logistics volatility, Gulf domestic content mandate enforcement variability, and EU carbon-border adjustment implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions about equipment utilization rates and commissioning schedule achievability. Recalibration cycles align with material shifts in sovereign wealth fund capital allocation and solid-state technology pilot-scale validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
EV Battery Cells Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
EV Battery Heating System Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Auto Storage Battery Market
EV Batteries
EV Batteries Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market