
 United States Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
United States Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Manufacturing Equipment Market Insights
Energy density specifications above 300 Wh/kg are reorganizing procurement priorities across US battery manufacturing lines. Tesla Inc. leverages its integrated cell-to-vehicle architecture to sustain captive demand for dry electrode equipment. Applied Materials Inc. anchors its position through vacuum deposition systems tailored to solid-state pilot lines. Dürr Group competes on automated coating and drying systems that occupy critical stages in cylindrical cell production.
United States Electric Vehicle Battery Manufacturing Equipment encompasses machinery for electrode preparation, cell assembly, formation cycling, and module-pack integration, with coating uniformity tolerances typically held within ±2% to ensure electrochemical consistency. The primary purpose is to automate precision manufacturing of battery cells at throughput rates exceeding 300 ppm for cylindrical formats. Coating Systems command the largest capital allocation due to their direct impact on cell energy density and yield rates. Solid State technology represents the fastest-growing segment as OEMs and Tier-1 Suppliers redirect R&D budgets toward next-generation chemistries requiring novel deposition and sintering equipment. Cell Testing Equipment maintains mature margin pools because formation and aging protocols remain standardized across lithium-ion architectures.
The Inflation Reduction Act, administered through Treasury Department guidance, mandates escalating domestic content thresholds for clean vehicle tax credits, directly conditioning OEM equipment sourcing decisions on US manufacturing location. OSHA and EPA standards govern particulate exposure limits and solvent emissions from coating operations, compelling equipment vendors to integrate enclosed drying and solvent recovery systems. Stakeholders must monitor how NHTSA battery safety rulemakings and state-level zero-emission vehicle mandates reshape the required mix of formation testing and thermal management equipment across new production facilities.
Market Dynamics
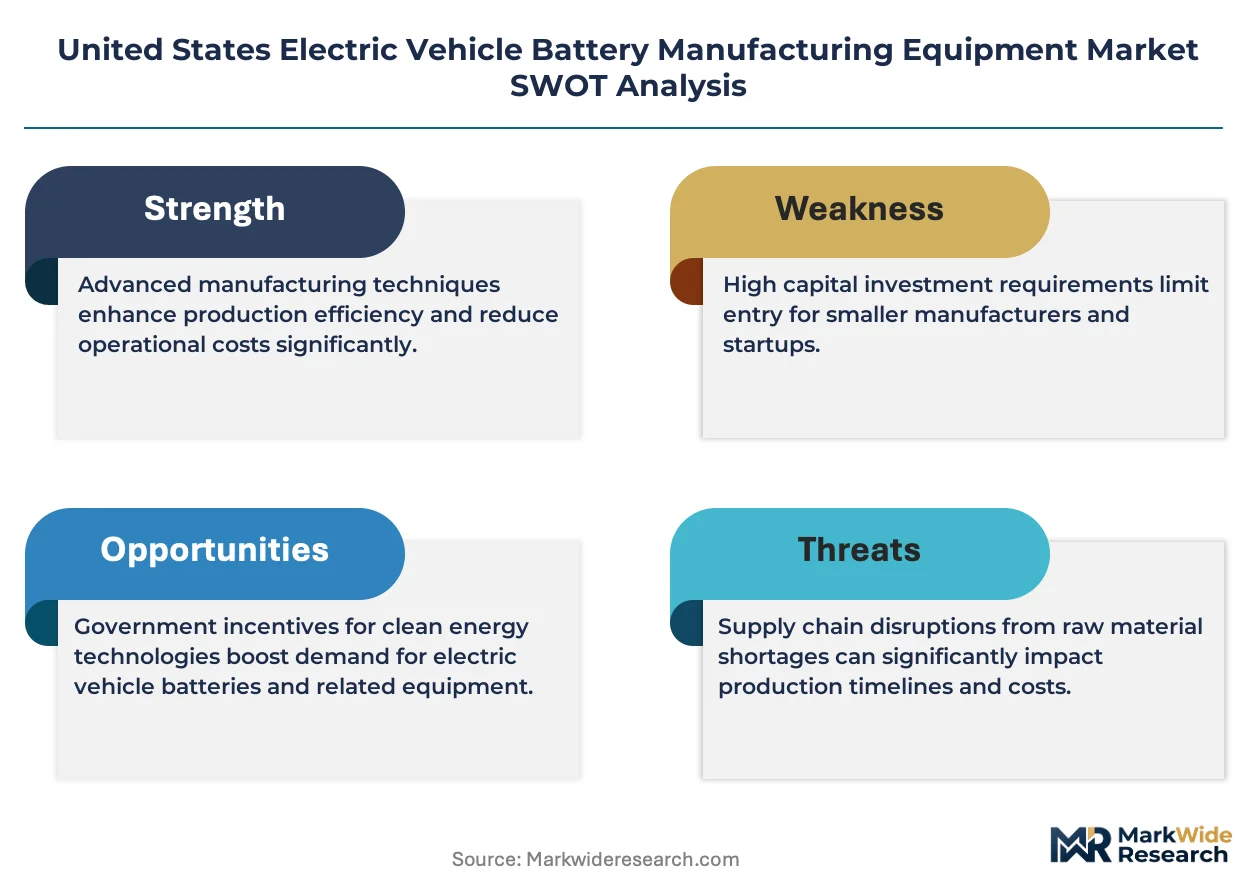
The Inflation Reduction Act's domestic content thresholds are restructuring capital allocation across US battery manufacturing, compelling OEMs to source electrode coating and cell assembly equipment from domestic vendors or forfeit clean vehicle tax credits.
Growth Catalysts
- IRA Domestic Content Requirements:Treasury Department guidance mandates escalating US-manufactured equipment shares for clean vehicle credits, redirecting gigafactory procurement toward domestic coating and formation system vendors.
- Solid-State Pilot Line Expansion:Next-generation battery chemistries require novel vacuum deposition and sintering equipment, opening demand for specialized machinery beyond incumbent lithium-ion architectures.
- Michigan-Tennessee-Texas Plant Clustering:Concentrated battery facility construction across these three states is generating localized demand surges for automated cell assembly and module-pack integration lines.
Market Restraints
- Specialized Equipment Lead Times:Custom electrode coating systems from German and Japanese suppliers extend delivery cycles to 18-24 months, constraining US production ramp schedules.
- Copper Foil and Lithium Carbonate Volatility:Input material price swings compress margin pools for equipment vendors locked into fixed-price contracts with gigafactory operators.
- Technical Limitation in Dry Electrode Scalability:Binder dispersion uniformity challenges at throughput rates above 300 ppm restrict commercial deployment of solvent-free coating systems.
Strategic Opportunities
- Second-Life Battery Disassembly Equipment:Emerging recycling mandates in California and New York are creating demand for automated module dismantling and black mass recovery systems.
- Solid-State and Silicon-Anode Convergence:Equipment vendors combining thin-film deposition expertise with high-precision slitting capabilities can capture pilot-to-production scaling contracts.
- Department of Energy Loan Programs:Title 17 clean energy financing is lowering capital barriers for domestic equipment manufacturers expanding electrode coating capacity.
Industry Challenges
- Electrochemical Engineer Shortage:US universities produce insufficient talent versed in both battery chemistry and high-speed manufacturing automation, forcing vendors to poach from automotive and semiconductor sectors.
- OSHA Particulate Exposure Compliance:Enclosed drying and solvent recovery systems add 15-20% to equipment capital costs while extending commissioning timelines for coating line installations.
- Legacy PLC Integration Complexity:New equipment must interface with existing SCADA architectures from disparate OEMs, requiring costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Manufacturing Equipment Market |
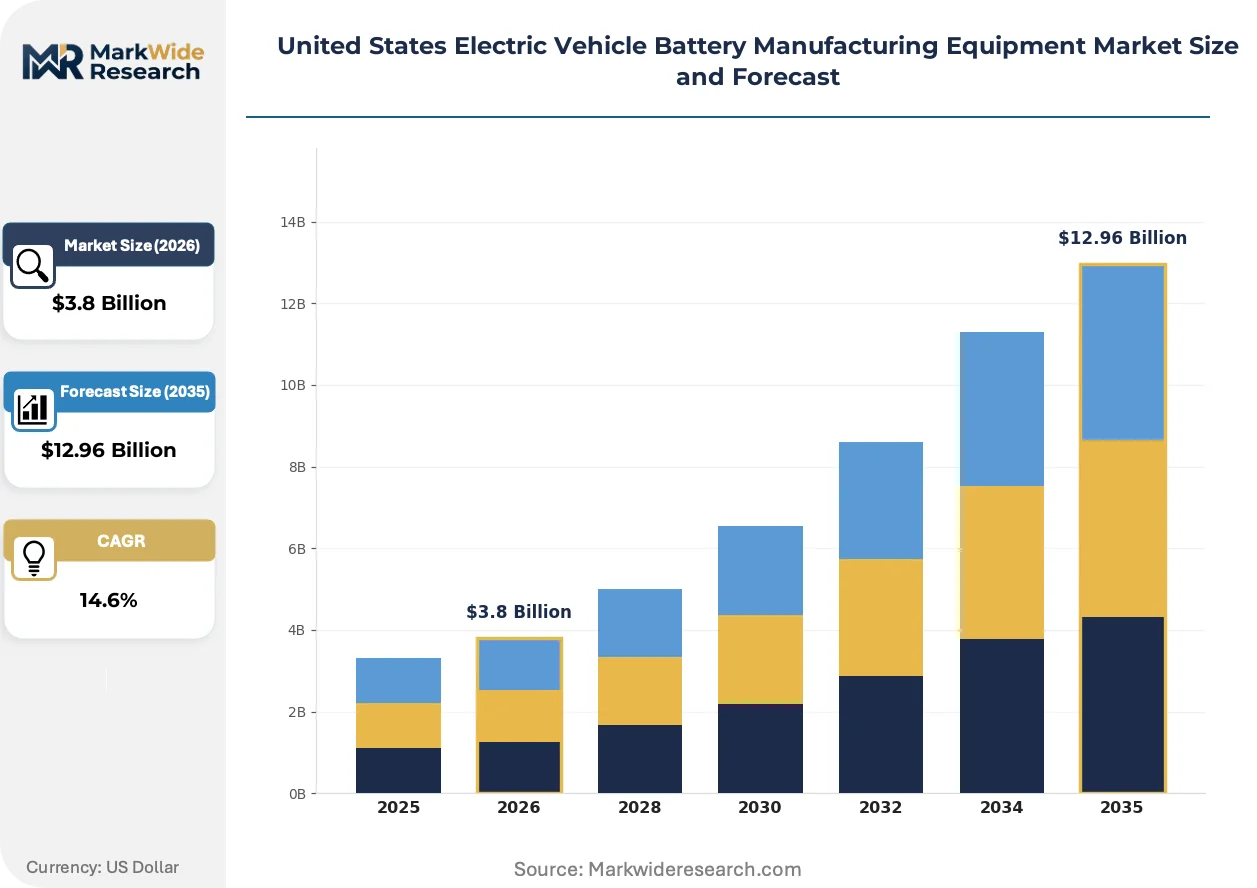
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Assembly Machines, Cell Testing Equipment, Coating Systems, Handling Tools Technology: Lithium-ion, Solid State, Nickel-metal Hydride, Lithium-polymer End User: OEMs, Tier-1 Suppliers, Modular Manufacturers, Aftermarket Providers Application: Passenger Vehicles, Commercial Vehicles, E-scooters, Industrial Equipment |
| Companies Covered | Tesla Inc., Hitachi High-Tech Corporation, Manz AG, Dürr Group, Wuxi Lead Intelligent Equipment, Applied Materials Inc., Nordson Corporation, ULVAC Inc., Bühler AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry electrode manufacturing is compressing the competitive landscape for coating equipment, while regulatory pressure on domestic content and safety standards accelerates vendor specialization.
Electrode binder technologies utilizing polytetrafluoroethylene fibrillation are supplanting conventional PVDF-NMP solvent systems in pilot production environments. Tesla and established cell manufacturers are adopting these methods to eliminate toxic solvent handling and reduce drying energy intensity. This transition is compressing demand for traditional slot-die coating lines while expanding orders for calendering and fibrillation-specific machinery.
NHTSA battery safety rulemakings are mandating thermal runaway propagation testing for all domestic cell production, compelling equipment vendors to integrate formation cycling protocols with abuse testing capabilities. The industrial consequence is a convergence of cell testing and safety validation equipment into unified production lines. Formation cycling equipment manufacturers are responding by acquiring thermal imaging and nail penetration testing technologies to maintain vendor status with OEM qualification programs.
Cell-to-pack architectural adoption by Detroit automakers is collapsing the traditional module assembly stage, altering procurement patterns for welding and inspection equipment. Tier-1 suppliers are displacing standalone module-pack integrators with direct equipment sales to OEM gigafactories. This channel compression is most visible in Michigan, where Ford and General Motors are consolidating equipment vendor relationships to reduce commissioning complexity and spare parts fragmentation.
United States Electric Vehicle Battery Manufacturing Equipment Market Segmentation
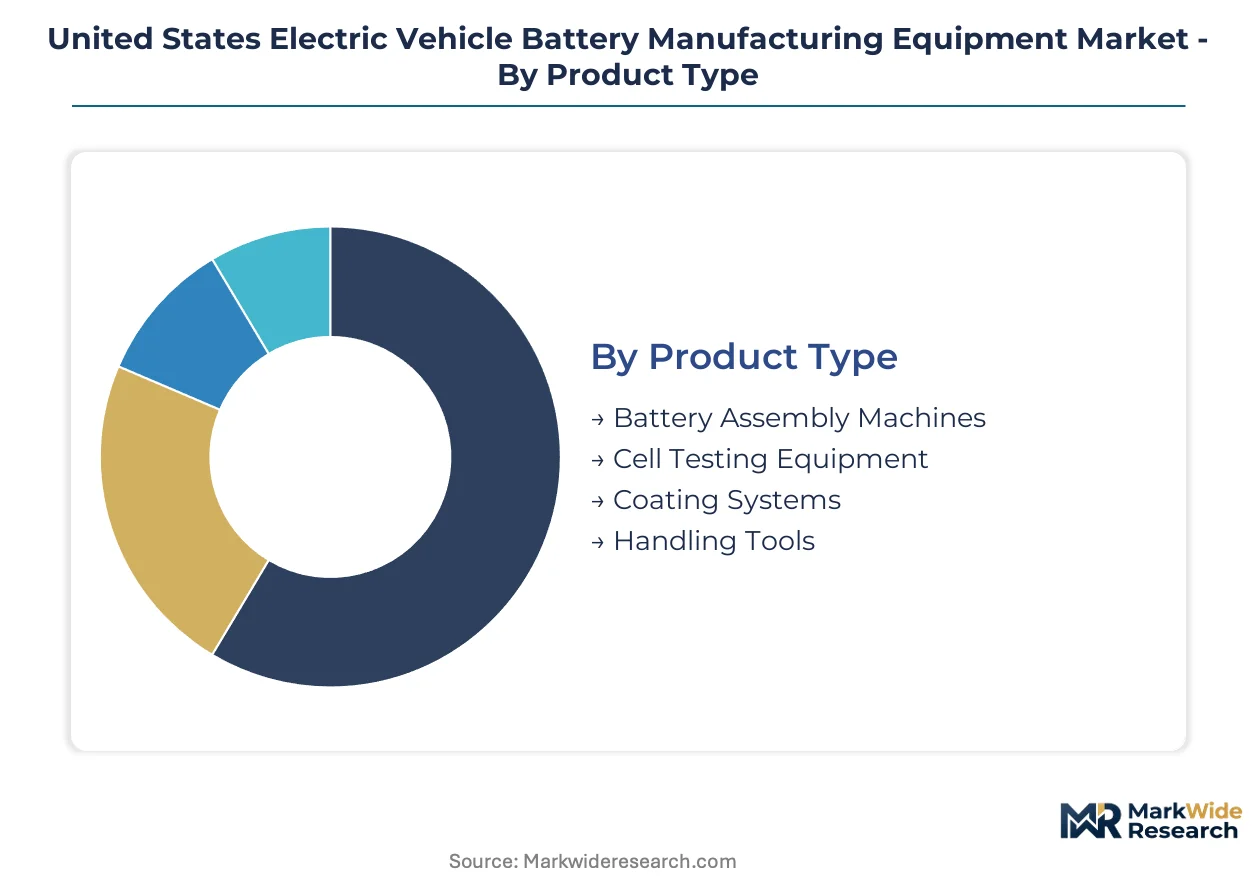
Equipment procurement patterns across US battery manufacturing diverge sharply by production stage and chemistry platform. Segmentation reveals where capital concentrates and which technology transitions are redirecting vendor order books.
Product Type:
Margin pools concentrate in coating and formation stages where precision tolerances create vendor stickiness and recurring service revenue.
- Coating Systems:Slot-die and comma-bar coaters apply active material slurries to copper and aluminum foils with thickness uniformity held within ±2%. Michigan and Tennessee gigafactories are expanding electrode line capacity to support cylindrical and prismatic cell ramps, with IRA domestic content rules favoring US-based coating equipment vendors.
- Cell Testing Equipment:Formation cycling systems condition cells through initial charge-discharge protocols while capturing electrochemical performance data. Demand clusters in Texas where OEMs are commissioning high-throughput aging chambers capable of processing 10,000+ cells simultaneously for quality validation.
- Battery Assembly Machines:Stacking, winding, and tab welding equipment automates cell construction at rates exceeding 300 ppm for cylindrical formats.
- Handling Tools:Vacuum grippers and automated guided vehicles transport electrodes and cells between process stations in dry room environments.
Coating Systems hold installed capacity. Cell Testing Equipment is rotating up the share rankings.
Technology:
Volume throughput still flows through incumbent chemistries while pilot line investments concentrate on next-generation architectures.
- Lithium-ion:NMC and LFP cathode configurations dominate current US manufacturing with established supply chains for precursor materials and electrolyte formulations. Texas and Michigan facilities are scaling 4680 and blade cell formats requiring specialized winding and laser welding equipment adapted to larger form factors.
- Solid State:Sulfide and oxide electrolyte chemistries demand vacuum deposition, sintering presses, and dry room infrastructure beyond conventional lithium-ion tooling. Pilot lines in California and Massachusetts are qualifying thin-film deposition systems for sulfide electrolyte layers, with equipment vendors developing scalable solutions for oxide ceramic processing.
- Nickel-metal Hydride:Legacy chemistry retains niche demand for hybrid vehicle applications with established Toyota supply relationships.
- Lithium-polymer:Pouch cell formats serve specialty applications requiring flexible packaging and high discharge rates.
Lithium-ion maintains production dominance. Solid State is climbing the fastest as R&D budgets pivot toward next-generation qualification.
End User:
Customer type determines equipment specification complexity and vendor relationship intensity.
- OEMs:Tesla, Ford, and General Motors operate captive gigafactories with vertically integrated equipment procurement teams specifying custom line configurations. These buyers demand direct vendor relationships for electrode coating and cell assembly systems, with IRA compliance teams auditing domestic content thresholds at equipment qualification stage.
- Tier-1 Suppliers:LG Energy Solution, SK On, and Panasonic Energy supply cells to multiple OEMs from US-based plants, requiring flexible equipment platforms capable of format switching between cylindrical, prismatic, and pouch configurations.
- Modular Manufacturers:Pack integrators source standardized module assembly lines for secondary battery applications.
- Aftermarket Providers:Service and refurbishment operations purchase diagnostic and disassembly equipment for warranty claim processing.
OEMs command specification authority. Tier-1 Suppliers are rotating up the share rankings as cell outsourcing contracts expand.
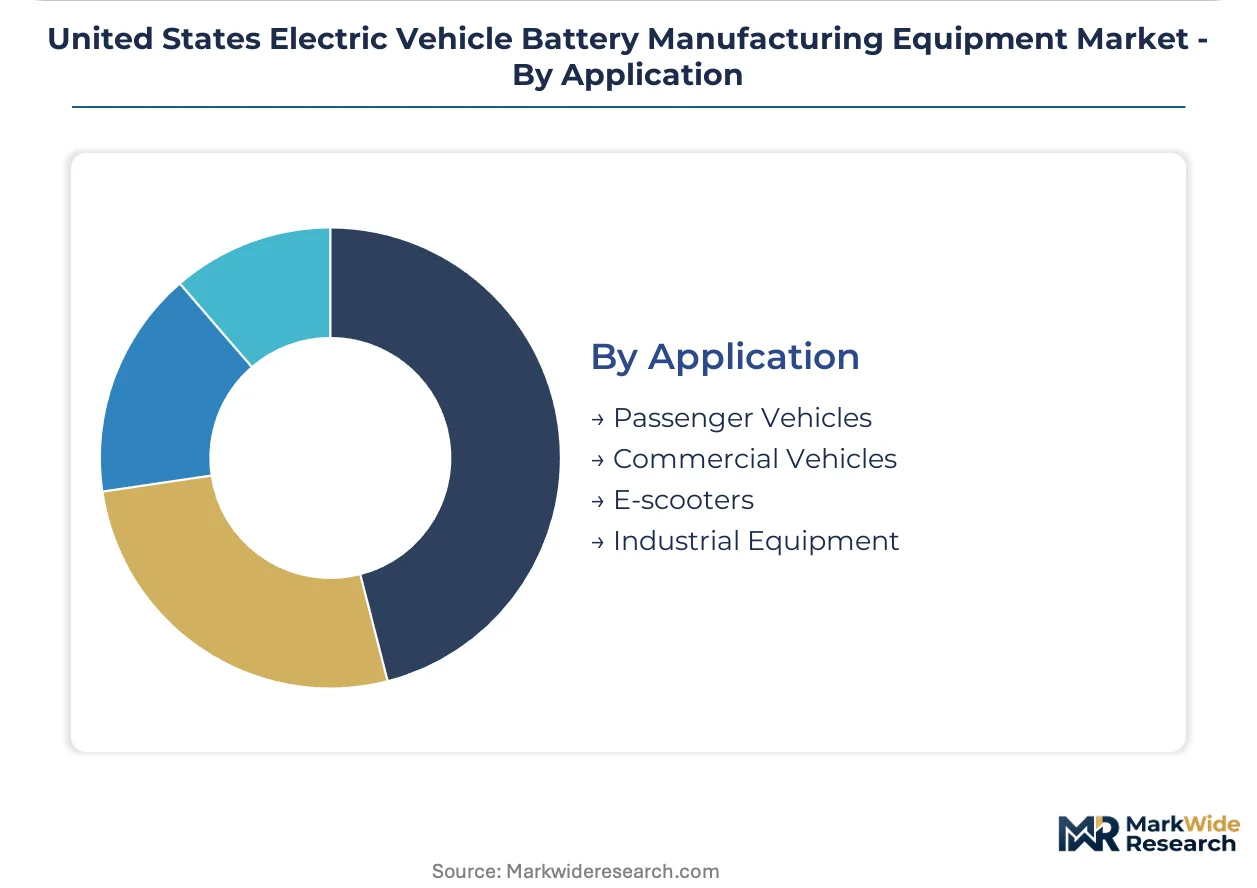
Application:
Vehicle class dictates energy density requirements and thermal management complexity.
- Passenger Vehicles:Light-duty EVs require high-volume cell production with stringent safety validation for NHTSA thermal runaway compliance. Michigan and Tennessee facilities are scaling lines for 300+ mile range packs, with formation cycling equipment integrating abuse testing protocols mandated by pending federal rulemaking.
- Commercial Vehicles:Heavy-duty trucks and delivery vans demand larger format cells with enhanced cycle life for high-utilization duty cycles. Texas-based manufacturing is expanding for Class 8 electric truck programs, with module-pack integration lines sized for megawatt-hour scale battery systems.
- E-scooters:Micromobility applications utilize standardized cylindrical cell formats with simplified assembly requirements.
- Industrial Equipment:Forklifts and stationary storage systems employ robust cell configurations optimized for cycle durability over energy density.
Passenger Vehicles hold installed capacity. Commercial Vehicles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment import dependence persists for precision coating and vacuum deposition systems, while domestic assembly line vendors capture share in electrode handling and module-pack integration. Michigan, Tennessee, and Texas anchor production capacity expansion through 2035.
Michigan
Ford and General Motors gigafactory construction drives electrode coating line procurement. OSHA particulate exposure standards govern enclosed drying system specifications for Detroit-area facilities. The Detroit-Hamtramck corridor concentrates cell assembly equipment commissioning for 4680 cylindrical formats.
Tennessee
SK On and LG Energy Solution plants generate demand for high-throughput winding and tab welding machinery. IRA domestic content thresholds condition equipment qualification on US manufacturing location. The Clarksville-Jackson industrial corridor hosts formation cycling facility construction for regional cell supply.
Texas
Tesla's Austin gigafactory sustains captive demand for dry electrode calendering and cell-to-pack integration lines. NHTSA thermal runaway propagation testing mandates reshape formation equipment specifications. The Greater Austin metro anchors pilot-to-production scaling for next-generation cell architectures.
California
Solid-state battery startups drive vacuum deposition and sintering equipment procurement for sulfide electrolyte pilot lines. California Air Resources Board zero-emission vehicle mandates accelerate equipment investment timelines. The San Francisco Bay Area concentrates thin-film deposition system development for oxide ceramic processing.
Massachusetts
Research institutions and solid-state ventures generate demand for laboratory-scale deposition and electrochemical testing equipment. Department of Energy ARPA-E funding supports next-generation battery manufacturing technology development. The Greater Boston corridor anchors pilot line equipment qualification for emerging chemistries.
United States Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized automation vendors rather than pure-play battery equipment firms. German and Japanese precision engineering specialists retain dominance in coating uniformity and vacuum deposition segments. Three archetypes define competitive positioning: captive automotive integrators, diversified process equipment conglomerates, and specialized Asian automation vendors. Capacity expansion and technology licensing represent the dominant competitive moves as vendors establish US service infrastructure and transfer deposition know-how to domestic partners.
Within the diversified industrial tier, Dürr Group and Manz AG exemplify European precision engineering capabilities adapted to cylindrical cell production requirements. Among Asian automation specialists, Wuxi Lead Intelligent Equipment occupies a position representing Chinese equipment scale economics. Tesla Inc. anchors the captive integrator archetype through vertical control over cell-to-vehicle manufacturing architecture. These three patterns illustrate how vendor selection criteria diverge between OEMs prioritizing specification control and Tier-1 suppliers seeking flexible platform economics.
| Leading Market Players |
|---|
| Tesla Inc. |
| Hitachi High-Tech Corporation |
| Manz AG |
| Dürr Group |
| Wuxi Lead Intelligent Equipment |
| Applied Materials Inc. |
| Nordson Corporation |
| ULVAC Inc. |
| Bühler AG |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month lead times for precision coating systems from German and Japanese suppliers concentrate pricing power with incumbent equipment vendors while compressing margin pools for gigafactory operators locked into fixed-price contracts. This supply bottleneck feeds directly into procurement cost structures, as domestic buyers absorb premium pricing for expedited delivery slots or forfeit IRA tax credit eligibility through non-compliant sourcing.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for electrode coating and cell assembly lines, with contract values scaling against throughput specifications and customization depth. Price differentiation separates high-precision vacuum deposition systems from standardized winding equipment, while certification tier—UL versus CE marking—commands additional engineering premiums. Cost compression in mid-tier coating equipment is intensifying because Chinese automation vendors are expanding US service infrastructure. Tier-1 suppliers exhibit highest price sensitivity due to multi-OEM contract pricing pressures, whereas captive OEM gigafactories prioritize specification control over unit economics.
Supply Chain Analysis
Strategic stockpiling of copper foil and lithium carbonate inventories is displacing just-in-time preferences as raw material volatility forces equipment vendors into forward commodity hedging. Equipment manufacturing draws from precision engineering clusters in Germany, Japan, and South Korea for coating uniformity systems, while domestic assembly line vendors source from Mexico and Canada for electrode handling robotics. Single-source vulnerability concentrates in vacuum deposition chamber fabrication, where two Japanese suppliers control thin-film expertise. Distribution runs through direct OEM procurement teams for gigafactory-scale orders, with regional equipment integrators serving secondary module-pack lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment vendors face substitution pressure from solid-state battery architectures requiring entirely different deposition and sintering toolsets, forcing defensive repositioning around next-generation chemistry qualification.
For Market Incumbents: Secure captive relationships with Detroit automakers by co-developing dry electrode calendering systems tailored to 4680 cylindrical formats. Deepen upstream control over precision component machining through acquisition of Midwest-based tooling specialists, insulating against German supplier lead time volatility while satisfying IRA domestic content audits. For New Entrants and Emerging Players: UL certification fast-tracks for formation cycling equipment offer entry into Texas-based OEM facilities where thermal runaway testing mandates are reshaping procurement specifications. Target second-life battery disassembly equipment in California and New York, where emerging recycling mandates outpace incumbent vendor adaptation. Lead with automated black mass recovery systems priced below European competitor offerings. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core battery equipment divisions amid portfolio restructuring. Long-term viability centers on vendors with pilot-to-production scaling capabilities across both lithium-ion and solid-state architectures. Watch NHTSA thermal runaway rulemaking finalization as inflection indicator for formation equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Process Qualification | Tesla's captive demand for solvent-free coating compresses incumbent slot-die equipment margins. |
| Solid-State Pilot Line Partnership | Applied Materials' vacuum deposition expertise captures sulfide electrolyte equipment contracts in California. |
| IRA Domestic Content Compliance | Dürr Group's US assembly expansion satisfies Treasury Department audits for clean vehicle tax credits. |
| Formation Cycling Integration | Hitachi High-Tech's thermal imaging acquisition addresses NHTSA abuse testing mandate convergence. |
| Second-Life Disassembly Automation | California recycling mandates generate demand for module dismantling systems beyond primary cell manufacturing. |
Research Methodology
Cross-validation between primary interviews with gigafactory procurement directors and secondary validation through SEC equipment vendor filings anchors the qualitative findings. The research incorporated discussions with electrode line engineers, OSHA compliance officers, Tier-1 supplier technical directors, and Department of Energy loan program administrators. Secondary sources included NHTSA rulemaking dockets, Treasury Department IRA guidance documents, state zero-emission vehicle mandate registries, and customs import records for precision coating machinery. Bottom-up equipment order book analysis and top-down gigafactory capex projections were triangulated against disclosed vendor backlog figures.
Sensitivity analysis around IRA domestic content threshold timing and solid-state pilot line conversion rates frames the forecast uncertainty. The analytical framework segments by equipment type, battery chemistry platform, end-user archetype, and regional production cluster across the projection horizon. CAGRs were derived from equipment capacity installation schedules and announced gigafactory construction timelines. Forecast inputs incorporated electrode coating throughput specifications, formation cycling chamber utilization rates, and dry room infrastructure cost curves.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive continuity and NHTSA rulemaking finalization would require recalibration. Forecasts reflect assumptions regarding equipment vendor US manufacturing expansion and lithium-ion format standardization persistence. Revision becomes warranted when solid-state chemistry qualification timelines accelerate or raw material price volatility exceeds hedging capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market