
 Asia Pacific Electric Vehicle Battery Electrolyte Market | 2026-2036
Asia Pacific Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle Battery Electrolyte Market Insights
China's Jiangsu and Fujian province electrolyte capacity build-out is fragmenting as provincial governments compete for cathode-active material investment. CATL anchors its position through backward integration into lithium salt purification. Mitsubishi Chemical Group competes on high-purity additive formulations for silicon-anode cells. Tinci Materials dominates carbonate solvent supply through captive chlor-alkali feedstock control.
Electric vehicle battery electrolyte comprises conductive ionic media—typically lithium hexafluorophosphate dissolved in ethylene carbonate and dimethyl carbonate blends—enabling lithium-ion transport between anode and cathode during charge and discharge cycles. Liquid electrolytes sustain the largest revenue pool due to established manufacturing infrastructure and compatibility with current gigafactory designs, while solid electrolytes represent the fastest-growing technology segment as OEMs pursue cobalt-free cell architectures. Battery Manufacturers constitute the most concentrated end-user channel, with procurement patterns tightening around electrolyte suppliers offering integrated additive packages.
China's MIIT enforces GB standards for thermal runaway propagation resistance, forcing reformulation of carbonate solvent ratios. Japan's METI and South Korea's MFDS coordinate lithium supply chain certification protocols that restrict non-compliant electrolyte imports. India's BIS is developing localized testing frameworks for imported electrolyte batches under its automotive mission plan. Stakeholders must monitor solid-state pilot line yield rates and sulfide electrolyte moisture sensitivity thresholds to calibrate R&D allocation between liquid and next-generation platforms.
Market Dynamics
China's MIIT thermal runaway propagation standards are forcing electrolyte reformulation across the Asia Pacific supply base, compressing carbonate solvent ratios and accelerating additive package integration by battery manufacturers seeking GB compliance certification.
Growth Catalysts
- High-voltage battery pack procurement:Electric bus fleets in China are scaling orders for next-generation cell architectures. This pulls specialized electrolyte volumes through cathode material corridors.
- Supply chain localization mandates:Japan's METI battery supply chain directives redirect electrolyte sourcing toward domestic purification capacity. MFDS certification alignment with Japanese protocols extends this restructuring to South Korean procurement.
- Solid-state pilot line investment:Sulfide electrolyte moisture control breakthroughs are unlocking cobalt-free cell designs. OEMs in the region are reallocating R&D toward solid platforms.
Market Restraints
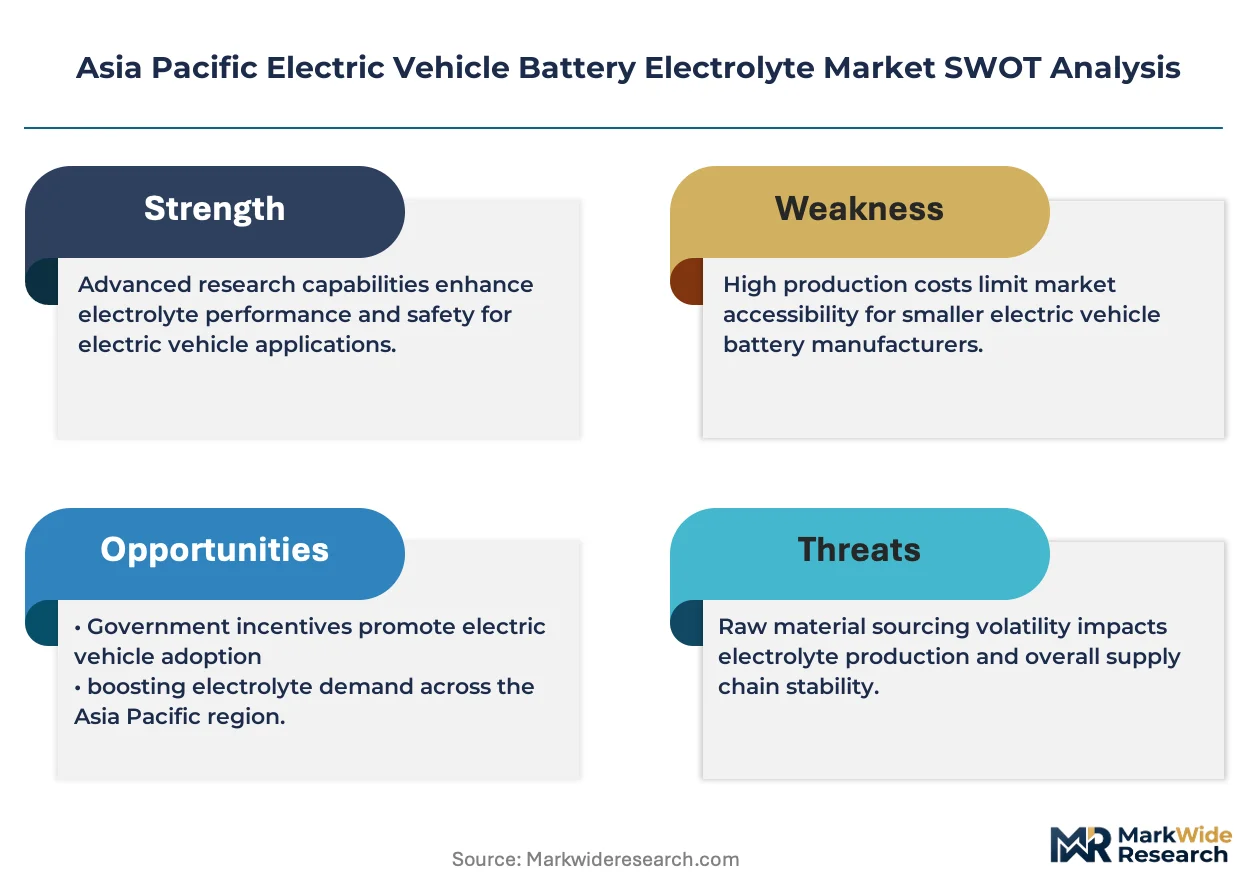
- Lithium salt price volatility:Hexafluorophosphate precursor costs fluctuate with fluorspar concentrate availability. This squeezes margin structures for non-integrated electrolyte blenders.
- Chlor-alkali feedstock concentration:Captive ethylene carbonate supply concentrates in Jiangsu and Fujian province clusters. Provincial competition for cathode investment fragments capacity planning.
- Solid electrolyte moisture sensitivity:Sulfide-based solid platforms require sub-ppm moisture handling. This technical limitation constrains pilot line yield rates and defers commercial scale-up.
Strategic Opportunities
- India BIS localization frameworks:India's automotive mission plan is developing domestic testing protocols for imported electrolyte batches. Early compliance positioning opens procurement relationships with emerging cell manufacturers.
- Silicon-anode additive specialization:High-purity additive formulations for silicon-anode cells represent a white space. Suppliers with fluorinated compound expertise can capture premium positioning.
- Integrated additive package channels:Battery manufacturers are consolidating procurement around electrolyte suppliers offering complete additive suites. This channel evolution rewards formulation breadth over commodity carbonate supply.
Industry Challenges
- Moisture control engineering talent:Sulfide solid-state production requires specialized dry-room engineering skills. Regional universities have not scaled training programs to match pilot line demand.
- Dual certification timeline compression:Simultaneous MIIT GB standard compliance and METI/MFDS supply chain certification extends validation cycles. This delays volume qualification for cross-border suppliers.
- Legacy liquid electrolyte asset stranding:Gigafactory designs optimized for carbonate blending face reconfiguration costs. Solid-state transition timelines remain uncertain, freezing incremental capacity decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle Battery Electrolyte Market |
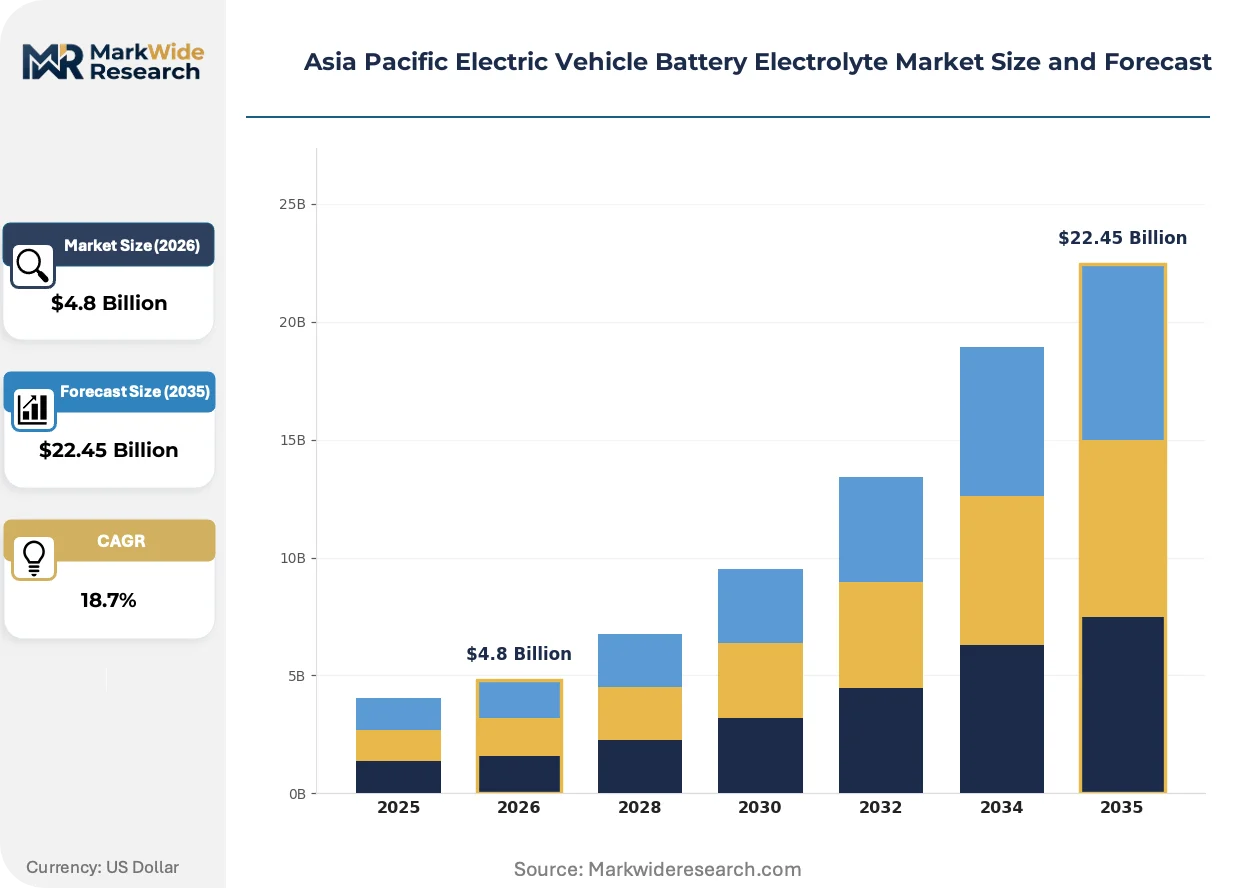
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolytes, Solid Electrolytes, Gel Electrolytes, Polymer Electrolytes End User: OEMs, Aftermarket Suppliers, Battery Manufactures, Research Institutions Technology: Li-ion, NiMH, Solid-State, Flow Battery Form: Liquid, Powder, Film, Gel |
| Companies Covered | Mitsubishi Chemical Group, CATL (Contemporary Amperex Technology), 3M Company, BASF, Soulbrain, UBE Corporation, Central Glass, CAPCHEM, Tinci Materials, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte formulation intelligence is digitizing quality control and supply chain traceability, compressing the gap between laboratory development and gigafactory deployment across Asia Pacific cell manufacturing corridors.
Artificial vision systems are digitizing electrolyte impurity detection during lithium salt dissolution. South Korean cathode material producers are deploying these platforms at Ulsan and Gwangyang corridor facilities. This technology is digitizing batch release decisions, collapsing certification timelines from weeks to hours while tightening specification windows for high-nickel cathode compatibility.
China's MIIT GB standards for thermal runaway propagation resistance mandate reformulated carbonate solvent ratios in liquid electrolyte products. Battery manufacturers must requalify cell designs under accelerated abuse testing protocols. High-voltage bus fleet procurement in Jiangsu and Fujian provinces faces the tightest compliance deadlines, forcing backward integration into additive synthesis.
Buyer concentration around integrated electrolyte-additive suppliers is displacing discrete component procurement. Battery manufacturers now specify complete ionic media packages rather than sourcing lithium salts and carbonate solvents separately. This pattern is most visible in South Korea's cathode material corridor, where Ulsan-based cell producers have consolidated vendor lists to three qualified formulation houses.
Asia Pacific Electric Vehicle Battery Electrolyte Market Segmentation
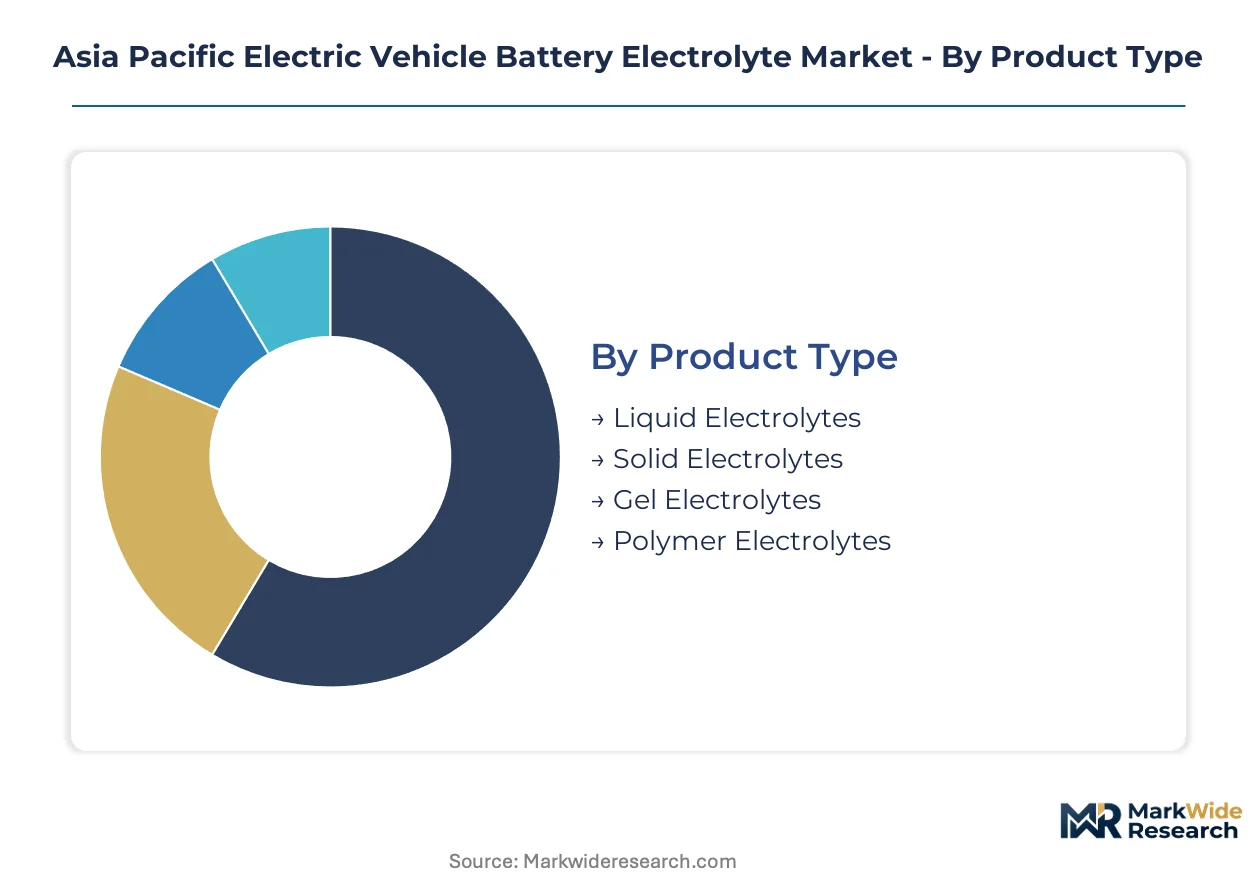
Electrolyte segmentation in the Asia Pacific region tracks divergent technology maturities and procurement consolidation patterns. Battery manufacturers are tightening specifications around integrated ionic media packages rather than discrete component sourcing.
Product Type:
The use-case spectrum spans established liquid formulations through emerging solid-state platforms, with each chemistry commanding distinct manufacturing infrastructure and qualification timelines.
- Liquid Electrolytes:Lithium hexafluorophosphate dissolved in ethylene carbonate and dimethyl carbonate blends dominates current gigafactory procurement. Jiangsu and Fujian province capacity build-outs in China concentrate supply, though MIIT thermal runaway standards are forcing reformulation of carbonate solvent ratios.
- Solid Electrolytes:Sulfide and oxide ceramic ionic conductors enable cobalt-free cell architectures. Moisture sensitivity constraints at sub-ppm thresholds currently limit pilot line yields in Japan and South Korea, though OEMs are reallocating R&D toward these platforms for next-generation high-voltage packs.
- Gel Electrolytes:Polymer-swollen liquid matrices occupy niche applications requiring mechanical flexibility.
- Polymer Electrolytes:Dry solid polymer electrolytes serve specialized low-power applications with limited regional penetration.
The dominant share belongs to liquid electrolytes, while solid electrolytes are climbing the fastest as solid-state pilot lines advance.
End User:
Procurement consolidation varies sharply across customer types, with volume concentration favoring integrated cell producers over fragmented aftermarket channels.
- Battery Manufacturers:Gigafactory operators in South Korea's Ulsan-Gwangyang cathode corridor specify complete additive packages rather than discrete salts and solvents. This channel commands the tightest qualification protocols and longest vendor lists, with three qualified formulation houses currently serving Ulsan-based producers.
- OEMs:Electric bus fleet operators in China are scaling direct procurement of high-voltage battery packs, pulling specialized electrolyte volumes through backward-integrated supply chains. CATL anchors this segment through in-house lithium salt purification.
- Aftermarket Suppliers:Replacement cell servicing and refurbishment operations source electrolyte through distributors with less stringent certification requirements.
- Research Institutions:National laboratories and university programs drive pre-competitive formulation development, particularly for sulfide solid-state chemistries.
Battery manufacturers capture the largest procurement volumes, while OEM direct sourcing is expanding most quickly as fleet electrification accelerates.
Technology:
Cell chemistry roadmaps determine electrolyte specification windows, with lithium-ion maintaining near-term dominance while solid-state architectures reshape R&D allocation.
- Li-ion:NMC and LFP cathode pairings with graphite or silicon-anode configurations constitute the installed base. High-purity additive formulations for silicon-anode cells represent a premium white space, with Mitsubishi Chemical Group competing on fluorinated compound expertise.
- Solid-State:Sulfide electrolyte platforms promise energy density breakthroughs but require specialized dry-room engineering skills that regional universities have not scaled to match demand.
- NiMH:Nickel-metal hydride chemistry persists in hybrid vehicle applications with modest electrolyte requirements.
- Flow Battery:Vanadium and zinc-bromine redox systems utilize aqueous electrolytes with limited overlap in automotive battery supply chains.
Li-ion technology holds the dominant position, while solid-state is gaining share fastest as METI and MFDS coordination on certification protocols accelerates pilot line investment.
Form:
Physical state dictates handling infrastructure and moisture control requirements, with liquid and powder forms commanding distinct supply chain configurations.
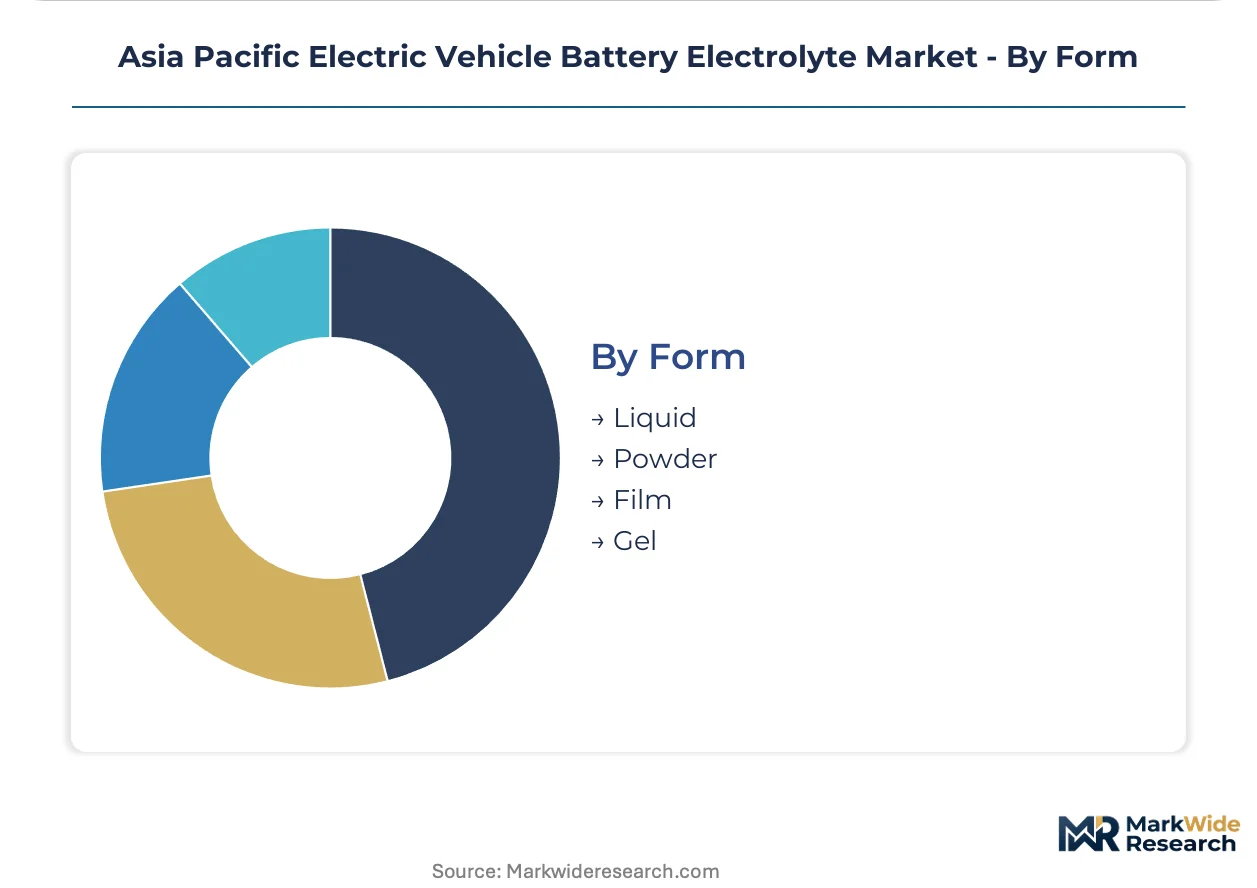
- Liquid:Blended carbonate solutions with dissolved lithium salts flow through established gigafactory dosing equipment. Tinci Materials dominates regional supply through captive chlor-alkali feedstock control in Jiangsu province.
- Powder:Ceramic sulfide and oxide solid electrolytes require inert atmosphere processing throughout the value chain, from synthesis through cell assembly.
- Film:Cast polymer electrolyte membranes serve thin-form-factor applications with limited current adoption.
- Gel:Semi-solid matrices occupy intermediate territory between liquid convenience and solid safety profiles.
Liquid form maintains the dominant share, while powder form is expanding most quickly as solid-state production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia Pacific region. China absorbs electrolyte volumes through backward-integrated gigafactory networks. Japan and South Korea source through specialized formulation houses with premium additive capabilities.
China
Electric bus fleets in Jiangsu and Fujian provinces are scaling procurement of high-voltage battery packs. MIIT enforces GB standards for thermal runaway propagation resistance, forcing reformulation of carbonate solvent ratios. The Jiangsu-Fujian cathode-active material corridor anchors regional electrolyte capacity build-out as provincial governments compete for investment.
Japan
Silicon-anode cell development pulls high-purity additive formulations from domestic suppliers. METI battery supply chain localization mandates redirect electrolyte sourcing toward in-country purification capacity. Nagoya-area chemical producers are retrofitting chlor-alkali infrastructure to serve solid-state pilot line demand.
South Korea
Ulsan-based cell producers in the cathode material corridor specify complete additive packages rather than discrete salts and solvents. MFDS certification alignment with Japanese protocols restricts non-compliant electrolyte imports. Gwangyang industrial complexes are consolidating vendor lists to three qualified formulation houses.
India
Emerging cell manufacturers are qualifying imported electrolyte batches under developing domestic frameworks. BIS is constructing localized testing protocols under the automotive mission plan. Tamil Nadu and Gujarat industrial corridors are attracting electrolyte distributors seeking early procurement relationships.
Australia
Lithium concentrate exports feed into regional electrolyte supply chains with limited downstream blending presence. The national critical minerals strategy prioritizes cathode precursor investment over electrolyte formulation. Western Australian mining hubs are exploring offtake partnerships with Asian purification facilities.
Asia Pacific Electric Vehicle Battery Electrolyte Market Competitive Landscape
Capability concentration sits with additive specialists; scale advantage sits with integrated chemical conglomerates. The vendor base separates into three tiers: captive producers serving single OEMs, independent blenders supplying formulation houses, and diversified material science groups with fluorinated compound expertise. Strategic moves center on backward integration into lithium salt purification and consolidation around integrated additive packages.
Within the diversified chemical tier, Mitsubishi Chemical Group and UBE Corporation exemplify formulation breadth. CATL anchors the captive producer archetype through in-house supply chain control. Tinci Materials occupies a position reflecting feedstock-integrated scale in carbonate solvent supply.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| CATL (Contemporary Amperex Technology) |
| 3M Company |
| BASF |
| Soulbrain |
| UBE Corporation |
| Central Glass |
| CAPCHEM |
| Tinci Materials |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Fujian province capacity build-outs anchor regional electrolyte supply, with provincial competition for cathode-active material investment fragmenting capacity planning and compressing margin structures for non-integrated blenders. Tinci Materials leverages captive chlor-alkali feedstock control to dominate carbonate solvent supply, while Mitsubishi Chemical Group competes on high-purity additive formulations for silicon-anode cells.
Pricing Analysis
Long-term offtake contracts dominate procurement between battery manufacturers and qualified formulation houses, with spot market exposure limited to carbonate solvent spot markets and lithium salt spot positions. Price differentiation separates integrated additive package suppliers from discrete component vendors, with certification alignment to MIIT GB standards and METI/MFDS protocols commanding premium positioning. Pricing pressure stems from lithium salt price volatility tied to fluorspar concentrate availability, squeezing margin structures for non-integrated electrolyte blenders. Aftermarket suppliers exhibit the highest price sensitivity due to less stringent certification requirements, while battery manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard practice as formulation houses compete for qualification slots with Ulsan-based cell producers. Geographic supply concentration centers on China, South Korea, and Japan, with raw material dependencies spanning lithium carbonate, fluorspar concentrate, and ethylene carbonate feedstocks. Single-source vulnerability concentrates in chlor-alkali infrastructure for carbonate solvent production, particularly in Jiangsu province clusters. Distribution runs through direct qualification channels to battery manufacturers, with consolidated vendor lists reducing intermediary layers in South Korea's cathode material corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as battery manufacturers consolidate procurement around three qualified formulation houses in the Ulsan-Gwangyang corridor, shifting leverage toward integrated additive package suppliers and away from discrete component vendors.
For Market Incumbents: Entrench qualification relationships with Ulsan-based cell producers by accelerating backward integration into lithium salt purification and expanding high-purity additive synthesis capacity for silicon-anode formulations. Defend against solid-state substitution threats by securing dry-room engineering talent pools ahead of pilot line scale-up demands. Prioritize dual certification investment spanning MIIT GB standards and METI/MFDS protocols to compress validation cycles for cross-border volume qualification. For New Entrants and Emerging Players: Pursue silicon-anode additive specialization as the most penetrable white space, where fluorinated compound expertise commands premium positioning absent from commodity carbonate supply. Target India's emerging cell manufacturers through early BIS compliance positioning under developing automotive mission plan frameworks. Establish go-to-market presence via technical partnership structures with Tamil Nadu and Gujarat industrial corridor distributors seeking qualified electrolyte batch suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive specialists with formulation breadth over scale-commoditized carbonate blenders, as procurement consolidation rewards integrated package capabilities. Long-term viability hinges on optionality across liquid and solid-state platforms, with sulfide electrolyte moisture control breakthroughs representing the critical inflection signal for R&D allocation shifts. Acquisition target archetypes include fluorinated compound specialists and dry-room engineering service providers with solid-state pilot line exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Purification | CATL anchors competitive position through in-house supply chain control over hexafluorophosphate precursors. |
| High-Purity Additive Formulation Investment | Mitsubishi Chemical Group captures premium positioning in silicon-anode cell development pipelines. |
| Solid-State Pilot Line Partnership | Nagoya-area chemical producers retrofit chlor-alkali infrastructure to serve sulfide electrolyte moisture control demand. |
| Dual Certification Compliance Program | Simultaneous MIIT GB and METI/MFDS alignment compresses cross-border validation timelines for formulation houses. |
| India BIS Localization Framework Positioning | Early compliance with developing automotive mission plan protocols opens procurement relationships with emerging cell manufacturers. |
Research Methodology
A spread of perspectives from electrolyte plant managers, battery manufacturer procurement leads, cathode material R&D directors, and distribution channel partners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, MIIT regulatory filings, METI supply chain directives, and SEC disclosures from diversified chemical conglomerates. Bottom-up electrolyte volume modeling triangulated against top-down gigafactory capacity announcements across the Asia Pacific region.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type (liquid, solid, gel, polymer), end user (battery manufacturers, OEMs, aftermarket, research institutions), technology (Li-ion, solid-state, NiMH, flow battery), and form (liquid, powder, film, gel). CAGRs were derived from electrolyte intensity per gigawatt-hour of cell capacity, calibrated against cathode material corridor expansion timelines and solid-state pilot line yield progression. Industry-specific forecast inputs included high-voltage bus fleet procurement schedules and chlor-alkali capacity build-out announcements in Jiangsu and Fujian provinces.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing trajectories, fluorspar concentrate availability, or electric vehicle subsidy policy would shift the trajectory of electrolyte demand growth. Forecasts reflect documented assumptions regarding solid-state commercialization timelines, regulatory certification harmonization progress, and provincial investment competition patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Rechargeable Battery Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Disposable Batteries Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Portable Battery Pack Market
Batteries
Battery Cases Market
Batteries
Seawater Battery Market
Batteries
Yacht Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
East Africa Battery Market
Batteries
Military Battery Packs Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Mobile Battery Market
Batteries
Portable Battery Station Market