
 UK EV Battery Pack Market | 2026-2036
UK EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
UK EV Battery Pack Market Insights
Solid-state cell architecture is rewriting pack design priorities for UK manufacturers. Envision AESC UK Ltd anchors large-format cylindrical production at its Sunderland facility. Agratas Energy Storage Solutions leverages Tata Group capital to build scale in Somerset. AMTE Power plc specializes in lithium-ion cells for high-performance automotive applications.
An EV battery pack integrates cells, modules, thermal management hardware, and battery management electronics into a sealed enclosure rated for IP67 protection and cycle lives exceeding 1,000 full-depth discharges. Its primary purpose is to store and deliver direct-current energy to electric drivetrains while maintaining thermal stability across operating temperatures. Lithium-ion chemistry dominates current UK production lines due to established supply chains and manufacturing equipment availability. Solid-state technology attracts the fastest development investment as developers target energy density improvements and reduced thermal runaway risk. Battery Management Systems command concentrated margin pools because software-defined safety and state-of-charge accuracy differentiate pack performance.
The UK's Department for Transport ZEV mandate shapes OEM procurement timelines by requiring escalating zero-emission sales shares. BIS standards for cell safety and recycling compliance filter market access for imported packs. The Environment Agency's battery waste regulations force end-of-life collection infrastructure investment. Stakeholders must monitor how post-Brexit alignment with EU Battery Regulation evolves to avoid dual certification costs.
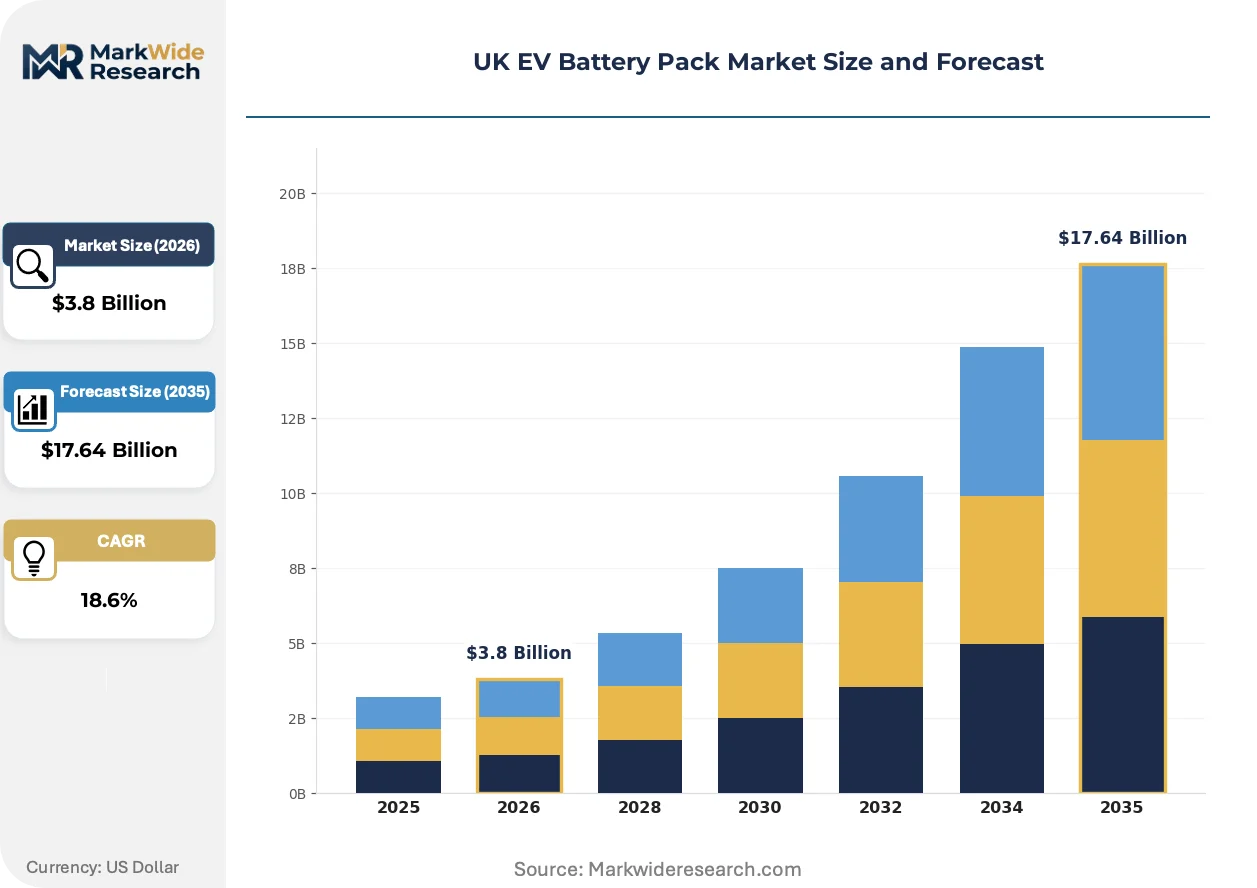
Market Dynamics
Domestic cell manufacturing mandates under the UK's ZEV mandate are forcing pack integrators to reconfigure supply chains around Midlands-based gigafactory clusters rather than Asian import dependencies.
Growth Catalysts
- Zero-Emission Vehicle Mandate:The Department for Transport's escalating sales share requirements compel OEMs to localize battery procurement, creating captive demand for UK-assembled packs.
- Solid-state chemistry advancement:Developers are redirecting R&D capital toward ceramic electrolyte architectures that eliminate thermal runaway risks and enable thinner pack enclosures.
- Midlands battery belt concentration:Gigafactory investments across Coventry, Warwickshire, and Derbyshire are generating supplier ecosystems that reduce logistics costs for pack integrators.
Market Restraints
- Cathode material cost volatility:Lithium carbonate and nickel sulfate price swings compress pack assembler margins, forcing long-term offtake contracts with Australian and Chilean miners.
- Cell supply concentration:UK pack producers remain dependent on a narrow supplier base for high-nickel cylindrical cells, creating vulnerability to allocation restrictions.
- Recycling infrastructure gaps:The Environment Agency's battery waste regulations outpace domestic black mass processing capacity, elevating end-of-life compliance costs.
Strategic Opportunities
- Scottish Highlands grid storage:Remote wind farm operators seek containerized second-life EV packs for frequency regulation, creating demand outside automotive channels.
- Cell-to-pack architecture adoption:Eliminating modular housings reduces pack weight and assembly labor, offering differentiation for UK integrators serving premium OEMs.
- Post-Brexit regulatory arbitrage:Divergence between UK BIS standards and EU Battery Regulation creates certification complexity that domestic players can monetize as compliance services.
Industry Challenges
- Electrolyte formulation expertise scarcity:UK universities produce insufficient solid-state chemists, forcing pack developers to recruit from German and Japanese battery programs.
- Thermal interface material qualification timelines:New TIM formulations require 18-24 month OEM validation cycles, delaying pack design refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK EV Battery Pack Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Energy Storage Technology: Fast Charging, Wireless Charging, Battery Management Systems, Thermal Management End User: OEMs, Fleet Operators, Individual Consumers, Second-Life Applications |
| Companies Covered | Envision AESC UK Ltd, Agratas Energy Storage Solutions, AMTE Power plc, Nyobolt Ltd, LEAPENERGY, Ricardo, Zenobē, Nexeon, Denchi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK EV Battery Pack Market Trends and Innovations
Pack architecture is compressing from modular hierarchies toward integrated cell-to-chassis designs that embed thermal management directly into vehicle structures.
Solid-state cell chemistry is migrating from laboratory validation to pilot production lines at UK research facilities. Premium OEMs are sampling large-format pouch prototypes for 2028 platform launches. This transition is compressing incumbent lithium-ion equipment depreciation schedules and redirecting capital toward dry-electrode coating infrastructure.
The UK's ZEV mandate is tightening fleet-average CO2 enforcement thresholds faster than original timelines. OEM procurement teams are advancing supplier qualification deadlines by 12-18 months to secure pack capacity. Midlands-based assemblers are responding by expanding cleanroom square footage ahead of cell supply agreements.
Fleet operators are consolidating battery procurement through power purchase agreements rather than capital purchases. Logistics providers across England's motorway corridors are leasing pack capacity bundled with charging infrastructure. This shift is most visible among Birmingham-based distribution firms electrifying last-mile delivery routes.
UK EV Battery Pack Market Segmentation
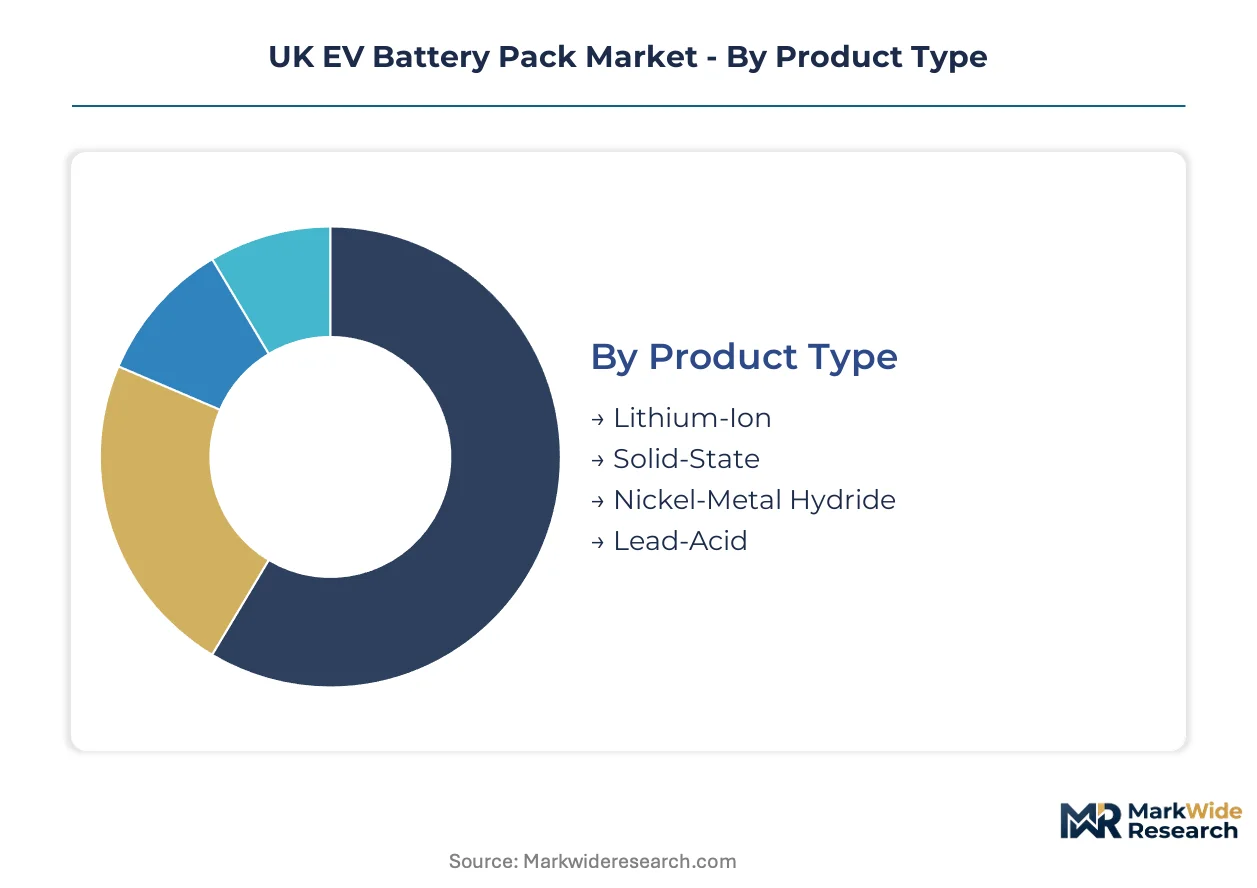
Pack configuration choices in the UK market directly determine thermal performance envelopes and vehicle platform compatibility. Procurement patterns across chemistry types and end-use channels reveal divergent margin structures and qualification timelines.
Product Type:
Chemistry selection governs energy density targets, thermal runaway profiles, and recycling pathway economics for UK assemblers.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate formulations dominate current UK production lines. Midlands gigafactory clusters source cylindrical cells from established supply chains for passenger vehicle platforms.
- Solid-State:Ceramic electrolyte architectures eliminate liquid electrolyte fire risks while enabling thinner pack geometries. Somerset and Oxfordshire pilot facilities are scaling sulfide-based prototypes for premium OEM qualification programs.
- Nickel-Metal Hydride:Legacy chemistry persists in hybrid vehicle retrofit applications where thermal stability outweighs energy density requirements.
- Lead-Acid:Auxiliary power units and low-speed electric vehicle segments retain demand for mature, cost-optimized 12V systems.
Lithium-ion commands the established base. The steepest expansion runs through solid-state as OEMs advance platform refresh timelines.
Application:
Vehicle duty cycles and power requirements fragment pack specifications across mobility and stationary energy segments.
- Passenger Vehicles:C-segment and D-segment platforms drive demand for 60-100 kWh pack capacities with cell-to-pack architectures. England's motorway corridor charging networks are shaping range requirements.
- Commercial Vehicles:Last-mile delivery vans and regional haulage trucks require modular pack designs enabling rapid swap configurations. Birmingham and Manchester fleet operators are consolidating procurement through leasing structures.
- E-Bikes:Compact 500-800 Wh packs with IP54 enclosures serve urban micromobility segments.
- Energy Storage:Containerized second-life packs from retired automotive units address Scottish Highlands wind farm frequency regulation demand.
Passenger vehicles anchor volume concentration. The steepest demand trajectory climbs through commercial vehicle electrification mandates.
Technology:
Subsystem integration depth separates commodity pack assemblers from margin-capturing technology providers.
- Fast Charging:800V architectures and silicon-carbide inverters enable 10-80% charge cycles under 20 minutes. Thermal management complexity increases with C-rate demands.
- Wireless Charging:Inductive pad systems for fleet depot automation reduce connector wear. Coventry manufacturing clusters are prototyping standardized ground assemblies.
- Battery Management Systems:Software-defined state-of-charge accuracy and predictive thermal algorithms command premium pricing. UK engineering centers specialize in ASIL-D functional safety certification.
- Thermal Management:Liquid cooling plates and phase-change materials maintain cell temperature uniformity across operating envelopes.
Battery Management Systems concentrate margin pools. Fast charging infrastructure deployment is expanding most quickly across England's logistics corridors.
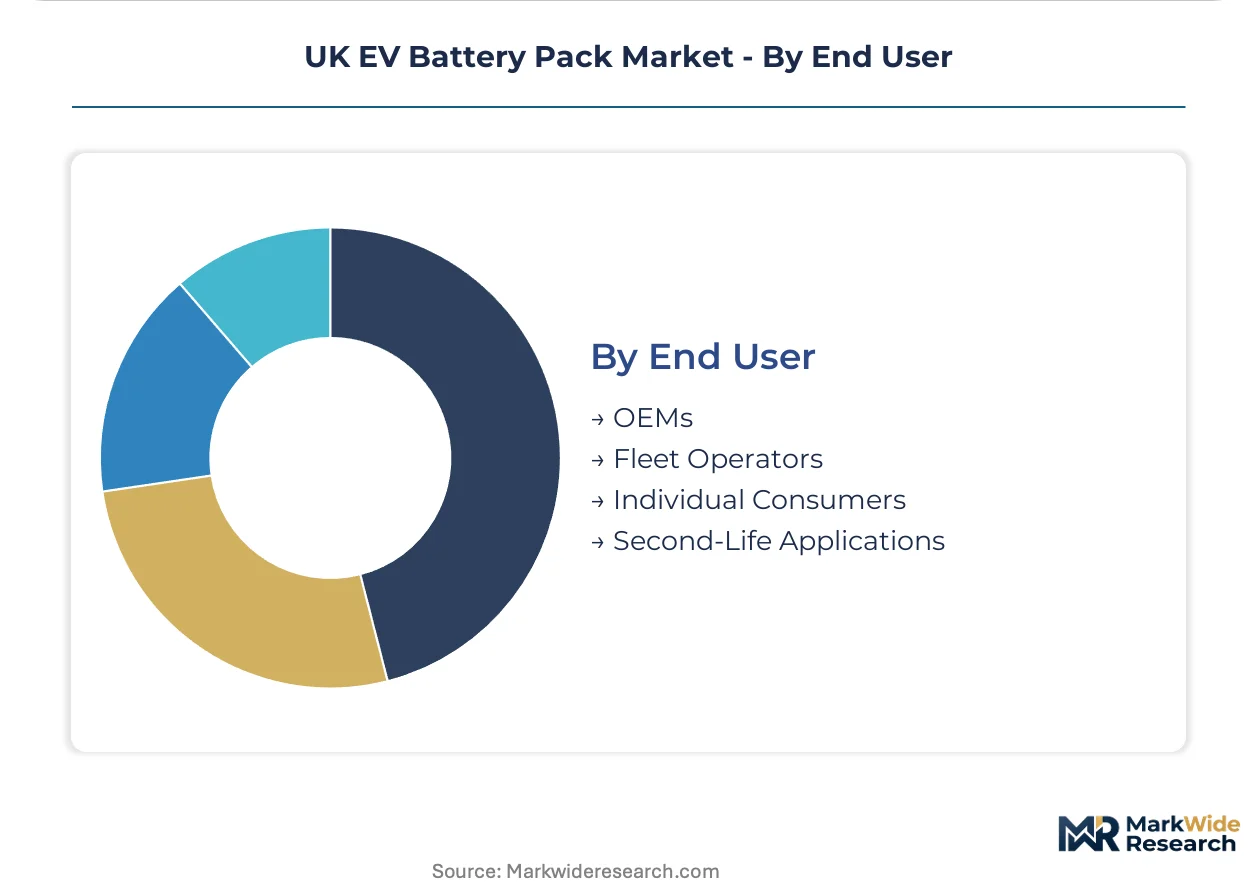
End User:
Procurement authority and volume scale determine contract structures and technical specification influence.
- OEMs:Volume commitments and platform-specific qualification requirements dominate UK pack capacity allocation. Sunderland and Derbyshire facilities prioritize captive supply agreements with domestic vehicle manufacturers.
- Fleet Operators:Power purchase agreements bundle pack capacity with charging infrastructure, shifting capital structures toward operational expenditure models. Birmingham-based distribution firms are consolidating procurement through fleet management platforms.
- Individual Consumers:Aftermarket replacement demand concentrates in warranty extension and performance upgrade segments.
- Second-Life Applications:Grid storage and stationary power operators source retired automotive packs through certified refurbishment channels.
OEMs retain procurement volume leadership. Fleet operators are gaining share fastest through electrified logistics mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs source UK-assembled battery packs through cross-channel supply agreements, while Asian cell manufacturers route cylindrical production through Midlands distribution hubs serving European vehicle assembly plants.
Midlands
Coventry and Warwickshire host the UK's densest gigafactory clustering, with Envision AESC UK Ltd operating large-format cylindrical cell lines for Nissan's Sunderland vehicle plant. The Department for Transport's ZEV mandate requires escalating zero-emission sales shares from 2024. Derbyshire pack integrators are expanding cleanroom capacity ahead of 2026 platform qualification deadlines.
North England
Sunderland anchors Nissan's electric vehicle export production, generating captive demand for localized battery procurement. The Environment Agency's battery waste regulations mandate end-of-life collection infrastructure investment. Newcastle engineering consultancies specialize in battery management system software certification for ASIL-D functional safety standards.
Southwest England
Somerset's Agratas Energy Storage Solutions facility leverages Tata Group capital to build lithium-ion cell scale for commercial vehicle applications. BIS standards for cell safety and recycling compliance filter market access for imported packs. Bristol-based thermal management specialists supply liquid cooling plates to Midlands pack assemblers.
Scotland
Scottish Highlands wind farm operators deploy containerized second-life EV packs for grid frequency regulation, creating non-automotive demand channels. The Scottish Government's Net Zero targets accelerate public fleet electrification mandates. Dundee battery research facilities pilot solid-state ceramic electrolyte architectures for 2028 OEM qualification.
Greater London
London's Ultra Low Emission Zone drives last-mile delivery fleet electrification, concentrating demand for modular rapid-swap pack designs. Transport for London's zero-emission bus procurement targets reshape commercial vehicle battery specifications. Croydon-based fleet management platforms consolidate power purchase agreements bundling pack capacity with depot charging infrastructure.
UK EV Battery Pack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure concentrates around three strategic archetypes: integrated cell-to-pack manufacturers, independent pack integrators serving multiple OEMs, and technology licensors monetizing battery management system IP. Capacity expansion and strategic partnerships dominate competitive moves, with Midlands facilities prioritizing captive supply agreements over merchant sales.
Within the integrated manufacturing tier, Envision AESC UK Ltd and Agratas Energy Storage Solutions occupy positions anchoring large-format production scale. AMTE Power plc exemplifies the specialist archetype, focusing on high-performance automotive cell development. These three entities represent distinct competitive vectors: cross-border corporate capital deployment, domestic industrial group diversification, and publicly-traded technology development.
| Leading Market Players |
|---|
| Envision AESC UK Ltd |
| Agratas Energy Storage Solutions |
| AMTE Power plc |
| Nyobolt Ltd |
| LEAPENERGY |
| Ricardo |
| Zenobē |
| Nexeon |
| Denchi Group |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on high-nickel cylindrical cells from South Korean suppliers determines both the premium commanded by UK-assembled packs and the three-tier supply chain structure bifurcating captive OEM agreements from merchant spot sales.
Pricing Analysis
The lithium-ion-to-solid-state pricing gap separates incumbent nickel-manganese-cobalt packs from next-generation ceramic electrolyte architectures still in pilot qualification. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and volume commitment scale. Cost compression in standard-tier packs is intensifying because cathode material spot volatility forces long-term offtake renegotiations. Fleet operators leasing through power purchase agreements exhibit highest price sensitivity; premium OEMs sourcing cell-to-pack designs show lowest.
Supply Chain Analysis
Envision AESC UK Ltd and Agratas Energy Storage Solutions hold the dominant contract-manufacturing capacity across Midlands and Southwest England facilities. Raw material flows draw from Australian lithium spodumene, Chilean lithium carbonate, and Indonesian nickel matte. Single-source vulnerability concentrates in high-nickel cathode precursor supply from South Korean refiners. Distribution runs through Midlands gigafactory clusters serving Nissan Sunderland and Jaguar Land Rover assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state chemistry substitution threatens incumbent lithium-ion pack assemblers who fail to secure ceramic electrolyte qualification timelines ahead of 2028 OEM platform launches.
For Market Incumbents: Build captive supply moats through backward integration into Midlands cell manufacturing capacity. Secure long-term offtake agreements with Australian and Chilean miners to lock cathode material cost positions. Accelerate dry-electrode coating equipment deployment before incumbent lithium-ion asset depreciation accelerates. For New Entrants and Emerging Players: Scottish Highlands grid storage represents the most penetrable geography outside automotive channels. Target containerized second-life pack refurbishment for wind farm frequency regulation contracts. Enter through power purchase agreement structures that bypass capital-intensive OEM qualification cycles. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors battery management system IP holders over commodity pack assemblers. Five-to-ten-year viability hinges on solid-state chemistry execution rather than lithium-ion scale. Watch ASIL-D certification completion rates as the inflection signal for pack integrator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Scale-Up | Somerset and Oxfordshire facilities advance ceramic electrolyte prototypes toward OEM qualification deadlines. |
| Cell-to-Pack Architecture Adoption | Eliminating modular housings reduces weight and assembly labor for premium vehicle platforms. |
| Backward Integration into Cathode Supply | Long-term offtake contracts with Australian and Chilean miners compress material cost volatility exposure. |
| Second-Life Refurbishment Certification | Environment Agency compliance for grid storage applications opens non-automotive revenue channels. |
| ASIL-D Functional Safety Investment | Software-defined battery management systems command premium pricing through predictive thermal algorithms. |
Research Methodology
The analysis maps lithium-ion pack assembly, solid-state pilot production, battery management systems, and second-life refurbishment channels, each validated through procurement directors at Midlands gigafactories, fleet operators consolidating power purchase agreements, thermal management specialists, and Environment Agency compliance officers. Primary interview findings triangulate against UK Department for Transport ZEV mandate filings, BIS standards documentation, SEC filings from battery material suppliers, and IHS Markit vehicle production databases. Bottom-up capacity assessments and top-down demand modeling converge on segment-level outputs.
Assumptions held ZEV mandate enforcement timelines and EU Battery Regulation alignment trajectory fixed; cathode material price volatility and solid-state chemistry yield rates varied across sensitivity scenarios. Segmentation dimensions span chemistry type, pack architecture, vehicle class, and end-user procurement authority. CAGRs derive from installed capacity buildout curves against vehicle electrification mandates. Forecast inputs incorporate Midlands gigafactory ramp schedules and Scottish Highlands renewable energy storage procurement pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian cell manufacturers establishing UK tolling arrangements would shift outcomes. Quarterly review of solid-state pilot yield rates and OEM qualification timeline accelerations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Traction Battery Market
EV Batteries
EV Batteries Market
EV Batteries
US EV Battery Pack Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market