
 Europe Electric Vehicle Battery Materials Market | 2026-2036
Europe Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Materials Market Insights
Multi-source cathode procurement is repositioning supply security as the dominant concern for European cell manufacturers. Northvolt AB leverages vertical integration into precursor production to reduce import dependency. BASF SE anchors its position through dedicated CAM facilities in Schwarzheide. Umicore N.V. competes via closed-loop recycling technology that recovers nickel, cobalt, and lithium from production scrap.
Europe Electric Vehicle Battery Materials encompasses the refined compounds, substrates, and functional coatings that enable electrochemical energy storage in traction battery packs. Cathode active materials typically comprise lithium nickel manganese cobalt oxide or lithium iron phosphate formulations sintered at controlled atmospheres above 800°C, determining cell voltage, capacity, and thermal stability for automotive propulsion. Cathode materials command the largest value share given cobalt and nickel price exposure, while solid-state battery chemistry represents the fastest-growing segment as OEMs pursue energy density above 400 Wh per kilogram. Electrolyte formulations concentrate margin pools among fluorinated additive suppliers serving high-voltage cathode architectures.
The EU Green Deal, REACH, and the Battery Regulation shape material compliance through mandatory recycled content thresholds and carbon footprint declarations at the cell level. ECHA substance restrictions on nickel compounds and PFAS additives force reformulation of separator coatings and electrolyte salts. Stakeholders must monitor delegated acts under the Battery Regulation that will define calculation methodologies for recycled content quotas before compliance deadlines crystallize competitive advantage.
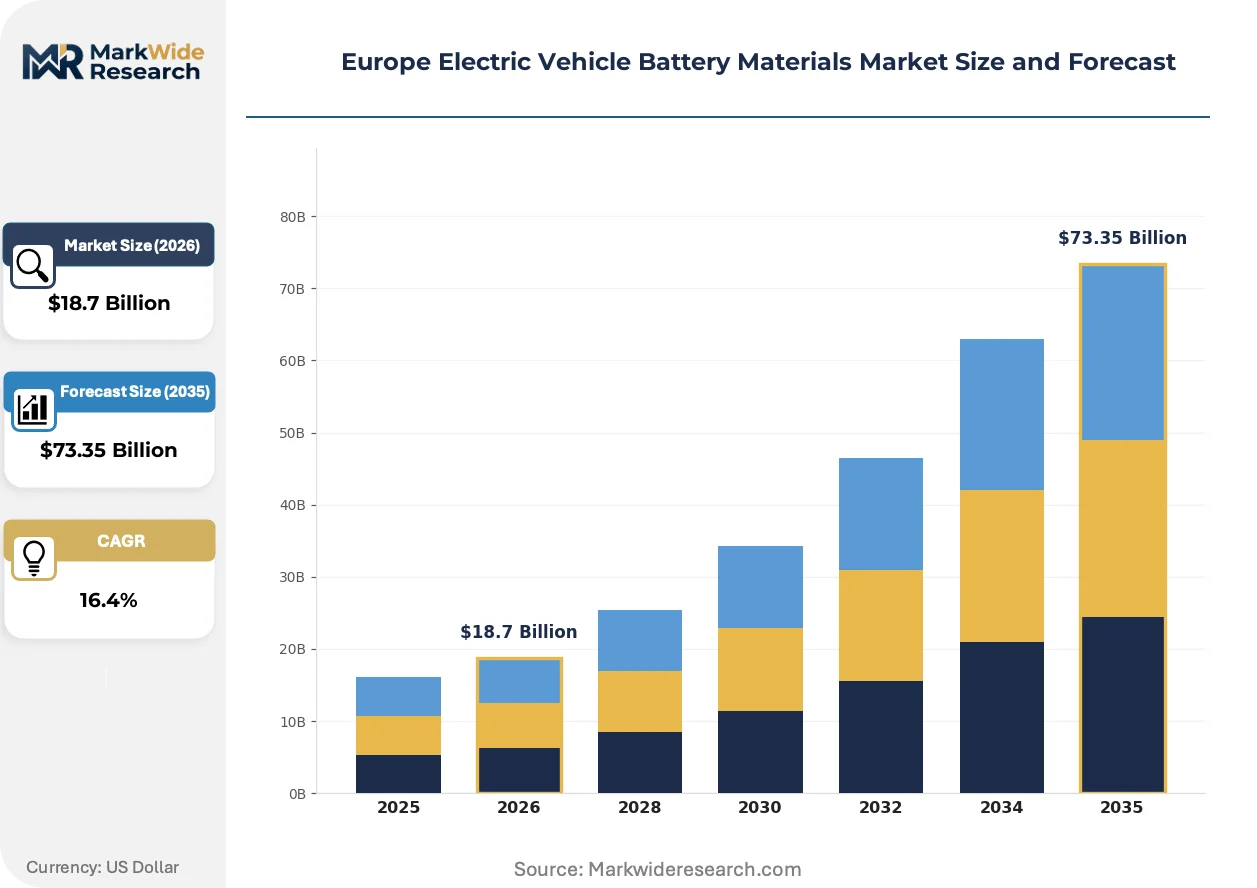
Market Dynamics
EU Green Deal mandates on recycled content and carbon footprint declarations are compressing cell manufacturers' sourcing timelines, forcing immediate reconfiguration of cathode active material supply chains across Germany, Poland, and Hungary.
Growth Catalysts
- Battery Regulation recycled content quotas:The EU Battery Regulation's delegated acts on recovery thresholds compel OEMs to secure qualified scrap streams, accelerating investment in hydrometallurgical refining capacity.
- Cell gigafactory clustering:Production concentration in Germany's industrial corridor creates localized demand pull for precursor chemicals, anode copper foil, and electrolyte formulations within 300-kilometer radii.
- Solid-state chemistry maturation:Sulfide-based solid electrolytes are progressing from pilot lines toward automotive qualification, opening new material specifications for lithium metal anodes and ceramic separators.
Market Restraints
- Nickel sulfate import dependency:European cell producers source over 70 percent of Class 1 nickel feedstock from Indonesian and Russian refiners, exposing margin structures to export duty volatility and sanctions risk.
- PFAS restriction cascade:ECHA proposals to limit per- and polyfluoroalkyl substances threaten fluorinated electrolyte additives and separator binders, requiring multiyear reformulation timelines without guaranteed performance parity.
- Cobalt price volatility:Democratic Republic of Congo concentrate dominance concentrates ethical sourcing audits and price spikes in a single jurisdiction, compressing working capital for cathode precursors.
Strategic Opportunities
- Eastern European refining greenfield:Poland and Hungary offer lower industrial electricity rates and proximity to German OEM assembly plants for cathode active material facilities not yet saturated by incumbent players.
- Battery passport data infrastructure:Mandatory digital product passports under EU Battery Regulation create service revenue streams for traceability software and third-party verification platforms.
- Lithium iron phosphate penetration:Energy storage and entry-level passenger vehicle segments are adopting LFP cathodes for cost and safety advantages, diversifying material demand beyond nickel-rich chemistries.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturing expansion outpaces European university output of specialists in solid-state ionics, coating process engineering, and dry electrode fabrication.
- Commissioning timeline compression:Gigafactory construction cycles of 18-24 months collide with 36-48 month electrolyte additive qualification periods, creating supply-ready but chemistry-unproven capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cathode, Anode, Electrolyte, Separator Battery Chemistry: Lithium-ion, Nickel-Metal Hydride, Solid State, Lithium Iron Phosphate End User: OEMs, Aftermarket Providers, Commercial Fleets, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Energy Storage |
| Companies Covered | Northvolt AB, BASF SE, Umicore N.V., Johnson Matthey Plc, BMZ Group, Lithium Werks B.V., Faradion Limited, Lanxess AG, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Materials Market Trends and Innovations
Silicon-dominant anode architectures and dry electrode coating processes are absorbing the majority of European cell manufacturers' R&D allocation, redirecting capital from incremental liquid electrolyte improvements toward next-generation solid-state platforms.
Silicon-carbon composite anodes are absorbing manufacturing investment from established graphite suppliers as cell producers target energy density above 300 watt-hours per kilogram. BMW Group and Volkswagen Group have specified silicon oxide blending ratios above 10 percent for 2026 platform launches. This transition is compressing demand for spherical natural graphite from Mozambique and Tanzania while expanding chemical vapor deposition coating capacity in Scandinavia.
REACH authorization requirements for nickel compounds and cobalt salts are tightening precursor import documentation, forcing non-EU refiners to establish EU-based legal entities for substance registration. The European Chemicals Agency's 2024 update to Annex XIV candidate list entries has extended compliance timelines for existing uses but closed loopholes for toll manufacturing arrangements. Cathode material producers in Finland and Belgium are leveraging this regulatory friction to defend domestic market share against Asian competitors.
Automotive OEMs are consolidating cathode procurement under direct offtake agreements with precursor manufacturers, bypassing trading houses and merchant chemical distributors. This channel compression is most visible in Germany, where Mercedes-Benz Group and Porsche AG have signed binding supply contracts with Umicore and BASF extending through 2030. The shift eliminates price discovery transparency for spot market participants and locks formulation specifications years ahead of cell production ramp.
Europe Electric Vehicle Battery Materials Market Segmentation
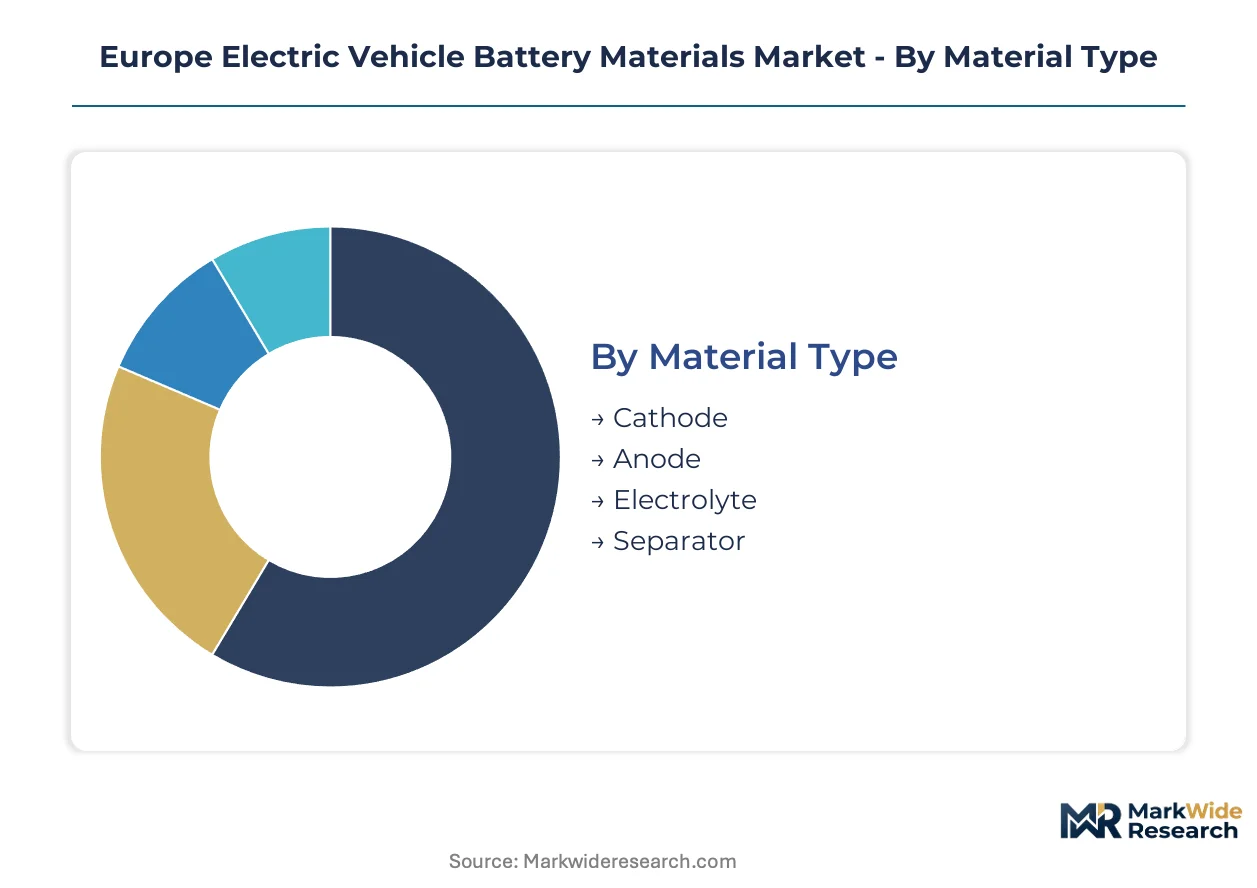
Material specifications determine cell performance, cost structure, and regulatory compliance pathways across European manufacturing footprints. Segmentation reveals where supply bottlenecks concentrate and which chemistry transitions will reshape procurement priorities.
Material Type:
Supply concentration for precursor chemicals varies dramatically by material category, with cathode active materials commanding the most complex multi-metal sourcing requirements.
- Cathode:Lithium nickel manganese cobalt oxide and lithium iron phosphate formulations require controlled atmosphere sintering above 800°C. German cell producers in the industrial corridor anchor demand for these high-value compounds as OEMs specify nickel-rich architectures for premium platforms.
- Anode:Synthetic and natural graphite substrates dominate, though silicon-carbon composites are displacing conventional formulations in next-generation designs. Scandinavian coating facilities are expanding chemical vapor deposition capacity to serve this transition.
- Electrolyte:Lithium hexafluorophosphate salts dissolved in carbonate solvents enable ionic conductivity between electrodes. REACH restrictions on PFAS additives are forcing reformulation timelines for fluorinated compounds.
- Separator:Polyolefin microporous membranes with ceramic coatings prevent internal short circuits while allowing lithium-ion transport. ECHA substance restrictions on nickel compounds affect coating binder selection.
Today's leader: Cathode. Tomorrow's challenger: Anode as silicon-dominant architectures mature.
Battery Chemistry:
Cost tier differentiation separates mass-market applications from performance-oriented platforms, with chemistry selection directly determining energy density, cycle life, and thermal safety profiles.
- Lithium-ion:NMC and NCA variants remain the workhorse chemistry for passenger vehicles, offering balanced energy density and manufacturing scalability. Polish and Hungarian gigafactories source these materials for German OEM assembly plants.
- Solid State:Sulfide-based ceramic electrolytes and lithium metal anodes promise energy density above 400 Wh per kilogram. Pilot line qualification is accelerating as BMW Group and Volkswagen Group target 2026 platform integration.
- Lithium Iron Phosphate:Entry-level passenger vehicles and stationary storage applications favor LFP for cost stability and thermal safety. The chemistry eliminates cobalt and nickel exposure, simplifying ESG compliance documentation.
- Nickel-Metal Hydride:Hybrid electric vehicle applications in commercial fleets retain demand for this mature chemistry, though volumes are plateauing as full-electric platforms displace mild-hybrid architectures.
Current volume concentrates in lithium-ion. Steepest expansion trajectory belongs to solid-state platforms.
End User:
Customer type determines contract structure, with direct OEM offtake agreements displacing merchant chemical distribution channels across Germany.
- OEMs:Mercedes-Benz Group and Porsche AG have signed binding supply contracts extending through 2030, locking formulation specifications years ahead of production ramp. These agreements eliminate spot market price discovery for cathode precursors.
- Commercial Fleets:Logistics operators specify standardized battery packs for van and truck electrification, creating volume demand for LFP chemistries with extended cycle life requirements.
- Aftermarket Providers:Replacement cell demand for early-generation EVs is emerging as a secondary material consumption channel, though volumes remain fragmented across independent service networks.
- Research Institutions:Pilot-scale material orders for solid-state and sodium-ion experimentation support technology validation, representing minimal revenue but strategic intelligence value for suppliers.
Procurement power sits with OEMs. Emerging leverage: commercial fleets as electrification scales.
Application:
Geography of demand clusters around German automotive manufacturing, with application mix determining chemistry and material specification requirements.
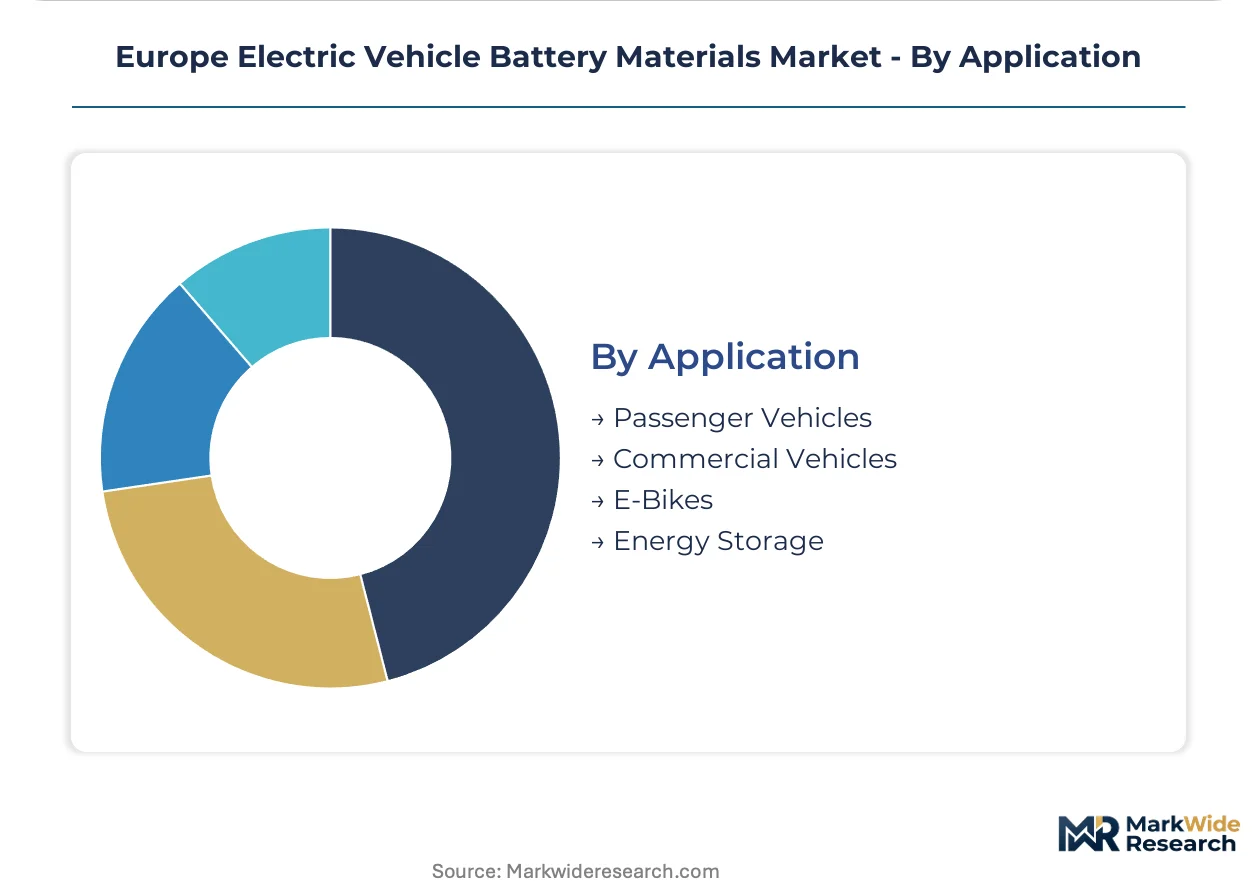
- Passenger Vehicles:Premium platforms specify nickel-rich cathodes for range performance, while entry-level models adopt LFP for cost containment. Stuttgart and Munich anchor this demand concentration.
- Commercial Vehicles:Heavy-duty truck and bus electrification requires high-cycle-life chemistries resistant to deep discharge patterns. Regional distribution hubs in the Netherlands and Belgium service this segment.
- Energy Storage:Grid-scale battery installations favor LFP for safety and calendar life, creating demand pull separate from automotive specifications. Nordic wind integration projects are expanding this application.
- E-Bikes:Light electric mobility uses lower-capacity cylindrical cells with simplified material requirements, though volumes are growing across urban European markets.
Passenger vehicles dominate current procurement. Energy storage is climbing fastest as grid decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors European cell manufacturing, with gigafactory clustering in Saxony, Lower Saxony, and Baden-Württemberg creating localized demand pull for cathode precursors, anode substrates, and electrolyte formulations within tight supply radii.
Germany
Cell gigafactories operated by Northvolt AB and Tesla anchor precursor demand in Saxony and Brandenburg. The country's Federal Ministry for Economic Affairs enforces Battery Regulation compliance through national implementation acts. Stuttgart and Munich concentrate OEM engineering headquarters that lock multi-year cathode offtake specifications.
Poland
Lower industrial electricity rates attract cathode active material greenfield investments from Korean and Chinese suppliers. Poland's Environmental Protection Law transposes REACH substance restrictions into national permitting procedures. The Legnica Special Economic Zone hosts precursor refining capacity serving German assembly plants across the border.
Hungary
Samsung SDI and SK On operations in Göd and Komárom create demand for nickel sulfate and lithium hexafluorophosphate. Hungary's National Directorate General for Disaster Management enforces Seveso III chemical storage regulations for electrolyte solvent inventories. The Budapest-Vienna industrial axis is emerging as a secondary logistics hub for anode copper foil distribution.
Sweden
Northvolt AB's Skellefteå gigafactory drives demand for Arctic-sourced renewable electricity in cell production. The Swedish Chemicals Agency (KEMI) implements EU Battery Regulation delegated acts on recycled content verification. Västerbotten County concentrates hydrometallurgical recycling pilot capacity for production scrap recovery.
Belgium
Umicore N.V.'s Hoboken facility anchors closed-loop refining for nickel, cobalt, and lithium from end-of-life batteries. Belgium's Federal Public Service Health enforces REACH authorization requirements for nickel compound imports. The Port of Antwerp-Bruges handles concentrate feedstock arrivals from Indonesian and African refiners.
Europe Electric Vehicle Battery Materials Market Competitive Landscape
Global majors compete with regional champions across cathode active material supply, creating a tiered structure where integrated chemical conglomerates face specialized battery material pure-plays. The vendor base concentrates around three strategic archetypes: vertically integrated European cell producers with captive precursor capacity, diversified chemical majors leveraging existing infrastructure, and dedicated recycling specialists extracting margin from circular material flows. Dominant competitive moves include backward integration into mining partnerships and capacity expansion into Eastern European low-cost manufacturing zones.
Among European-anchored suppliers, Northvolt AB exemplifies the integrated cell producer archetype through its upstream precursor investments, while BASF SE represents the diversified chemical major leveraging Schwarzheide infrastructure for cathode active material output. Umicore N.V. occupies the recycling specialist position, recovering nickel, cobalt, and lithium from production scrap and end-of-life batteries through hydrometallurgical refining.
| Leading Market Players |
|---|
| Northvolt AB |
| BASF SE |
| Umicore N.V. |
| Johnson Matthey Plc |
| BMZ Group |
| Lithium Werks B.V. |
| Faradion Limited |
| Lanxess AG |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Electrochemical engineering talent scarcity in Germany's industrial corridor widens pricing-tier spreads between premium cathode formulations and standard-grade imports, as labor-cost differentials compound raw material volatility across European cell manufacturing footprints.
Pricing Analysis
Input-cost pass-through from Indonesian nickel sulfate and DRC cobalt concentrate dominates contract negotiations, with long-term offtake agreements locking formulation specifications years ahead of production ramp. Price differentiation rests on REACH compliance certification and carbon footprint declaration tiers, with German OEMs paying premiums for qualified scrap-stream documentation. Cost compression in entry-level LFP chemistries is intensifying because Chinese precursor suppliers are expanding European tolling capacity. Commercial fleet operators exhibit highest price sensitivity due to standardized pack requirements, while premium passenger vehicle platforms remain least sensitive to cathode active material costs.
Supply Chain Analysis
Reverse-logistics flows for end-of-life batteries and production scrap are concentrating hydrometallurgical refining investment in Belgium and Sweden, creating closed-loop material recovery channels that bypass virgin concentrate markets. Geographic supply concentration centers on Indonesia for Class 1 nickel, the Democratic Republic of Congo for cobalt, and Chile and Australia for lithium spodumene. Raw material dependencies hinge on nickel sulfate, cobalt hydroxide, and lithium hexafluorophosphate salt feedstocks. Single-source vulnerability from Indonesian export duty volatility threatens margin structures. Distribution runs through direct OEM offtake agreements that displace merchant chemical trading houses across Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Vehicle Battery Materials Market functions as a stable compounder, with EU Battery Regulation recycled content quotas and carbon footprint mandates driving steady, policy-anchored demand growth across the analysis window.
For Market Incumbents: To counter Korean and Chinese precursor suppliers establishing Eastern European tolling capacity, BASF SE and Umicore N.V. must accelerate backward integration into Arctic-sourced renewable electricity for Schwarzheide and Hoboken facilities. Channel control through binding multi-year offtake agreements with Mercedes-Benz Group and Volkswagen Group locks formulation specifications and eliminates spot market price discovery for competitors. For New Entrants and Emerging Players: Solid-state battery chemistry qualification delays create a technology-first wedge for sulfide-based ceramic electrolyte specialists to secure pilot-line partnerships with BMW Group before incumbent liquid-electrolyte suppliers adapt. Poland and Hungary offer the most penetrable geography for cathode active material greenfield investment given lower industrial electricity rates and proximity to German OEM assembly plants. A go-to-market angle targeting battery passport data infrastructure and traceability software services captures regulatory-compliance service revenue. For Investors and Strategic Acquirers: European automotive OEMs are the most active acquirer in this space, consolidating cathode procurement under direct offtake agreements that compress distribution channels and eliminate merchant margins. Long-term viability over a 5-10 year window favors recycling specialists with hydrometallurgical refining capabilities and closed-loop material recovery technology. The signal to watch is delegated act publication timing under EU Battery Regulation that crystallizes recycled content quota calculation methodologies before compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Northvolt AB's upstream investments reduce dependency on Indonesian nickel sulfate imports. |
| Green Manufacturing Transition | Arctic-sourced renewable electricity in Skellefteå lowers carbon footprint declarations for EU Battery Regulation compliance. |
| Long-term Supply Agreement | Mercedes-Benz Group and Porsche AG binding contracts through 2030 lock cathode formulation specifications. |
| Joint Venture | Korean suppliers in Poland's Legnica Special Economic Zone establish tolling capacity serving German assembly plants. |
| Technology Licensing | Umicore N.V.'s closed-loop hydrometallurgical refining technology enables production scrap recovery for qualified recycled content. |
Research Methodology
Coverage spans Germany, Poland, Hungary, Sweden, and Belgium, with primary inputs from each market combining interviews with cell manufacturing executives, cathode material procurement leads, ECHA regulatory affairs specialists, and automotive OEM platform engineers. Secondary validation draws from EU Battery Regulation delegated acts, REACH Annex XIV candidate list updates, customs and trade data for nickel sulfate and cobalt concentrate flows, and SEC filings from diversified chemical majors. Bottom-up cell production capacity modeling triangulates against top-down cathode active material demand forecasts.
Rate-of-change decomposition separates volume growth from price and mix effects across the projection horizon. Segmentation dimensions modeled include material type, battery chemistry, end-user category, and application, with additional granularity on regional production cluster and carbon footprint declaration tier. CAGRs derive from installed gigafactory capacity ramp schedules and chemistry transition assumptions. Industry-specific forecast inputs incorporate solid-state battery pilot line qualification timelines and ECHA PFAS restriction implementation pathways.
The model holds under stable EU Green Deal policy implementation; deviation in delegated act publication timing or Indonesian export duty regime shifts would revise capacity investment schedules. Practitioners should monitor ECHA substance restriction proposals and Battery Regulation recycled content methodology releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Lifepo4 Battery Market