
 Electric Vehicle Battery Market | 2026-2036
Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Market Analysis
EU Battery Regulation is recalibrating the cost-of-entry calculus for manufacturers seeking European market access. Contemporary Amperex Technology Co. Limited anchors its position through massive lithium-ion production scale across multiple continents. LG Energy Solution Ltd. differentiates via advanced nickel-cobalt-manganese chemistry and deep OEM partnerships. BYD Company Ltd. leverages full vertical control from raw materials to finished vehicles, insulating its battery division from supply shocks.
An electric vehicle battery is an electrochemical energy storage system, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes, engineered to deliver sustained power densities above 250 Wh/kg for traction applications. The device stores and releases electrical energy through reversible lithium-ion intercalation, enabling zero-emission propulsion for passenger automobiles, delivery trucks, and municipal buses. Lithium-ion chemistry dominates installed capacity owing to mature supply chains and declining cell costs, while solid-state architectures attract R&D capital for their potential to eliminate thermal runaway risks and extend cycle life. Among end user segments, commercial fleets command premium pricing for high-cycle-duty contracts, whereas two-wheeler electrification in dense urban centers opens volume opportunities at lower per-unit margins.
The EPA tailpipe standards in the United States and China's MIIT new-energy vehicle mandates jointly dictate production volume requirements and battery performance thresholds across the two largest manufacturing jurisdictions. REACH compliance in Europe and evolving GB standards in China impose traceability and recycling obligations that favor producers with closed-loop material recovery capabilities. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent chemistry restrictions and carbon-border adjustments will determine which cell technologies secure preferential market access and long-term procurement contracts.
Market Dynamics
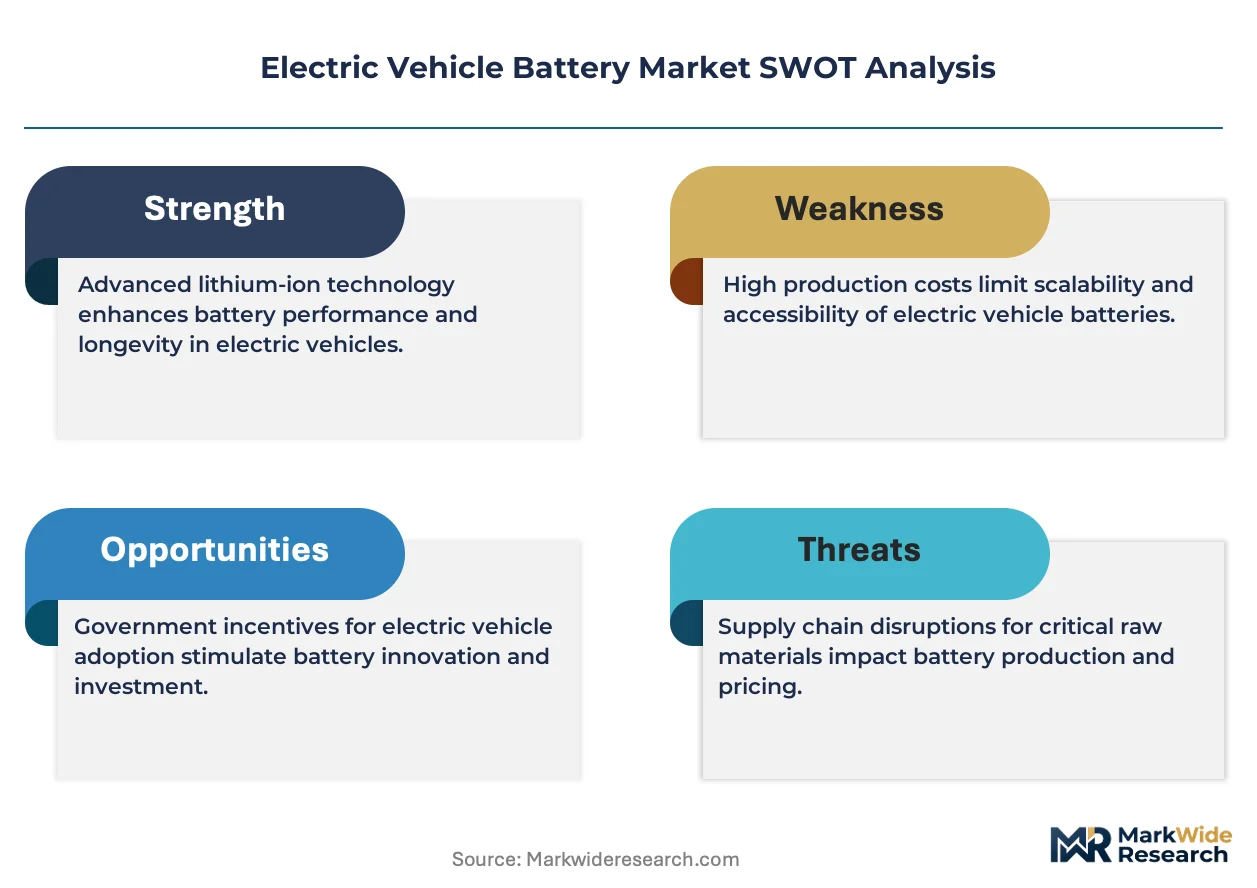
The battery sector faces a structural squeeze between cathode material cost volatility and OEM demands for higher energy density. Cell manufacturers must simultaneously absorb lithium price swings and fund solid-state R&D while maintaining contract pricing discipline with automotive customers.
Growth Catalysts
- China's MIIT new-energy vehicle mandates:Production quotas force domestic automakers to secure long-term cell supply, locking in volume commitments that stabilize factory utilization for producers.
- Commercial fleet electrification:Logistics operators in Germany and the United States are signing multi-year service contracts requiring high-cycle-duty battery configurations, creating premium pricing tiers.
- Lithium-iron-phosphate chemistry:The technology's thermal stability and cobalt-free composition is capturing share in entry-level passenger segments and grid storage applications.
Market Restraints
- Refined lithium supply concentration:Processing capacity clusters in China's Sichuan and Qinghai provinces, exposing cell makers to single-jurisdiction export policy shifts.
- Nickel price volatility:High-nickel cathode formulations remain vulnerable to Indonesian ore export restrictions and London Metal Exchange contract fluctuations.
- EU Battery Regulation traceability:Mandatory carbon-footprint declarations and recycled-content thresholds impose compliance costs that favor incumbent producers with established recovery networks.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Production-linked incentives are attracting manufacturing investment to serve domestic two-wheeler and three-wheeler electrification.
- Battery-as-a-service models:Swappable pack architectures are emerging in dense urban corridors, decoupling vehicle purchase from energy storage ownership.
- Sodium-ion convergence with lithium systems:Hybrid pack designs pairing sodium cells for base load with lithium for peak discharge are opening cost-optimized configurations.
Industry Challenges
- Electrolyte formulation expertise:Solid-state development requires scarce polymer chemistry and ceramic engineering talent, constraining prototype-to-production timelines.
- Gigafactory capex intensity:Dry electrode coating and in-house precursor synthesis demand billion-dollar facility commitments before revenue realization.
- UN 38.3 certification complexity:Transport safety testing for new cell formats creates multi-month approval bottlenecks that delay cross-border supply chain integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Market |
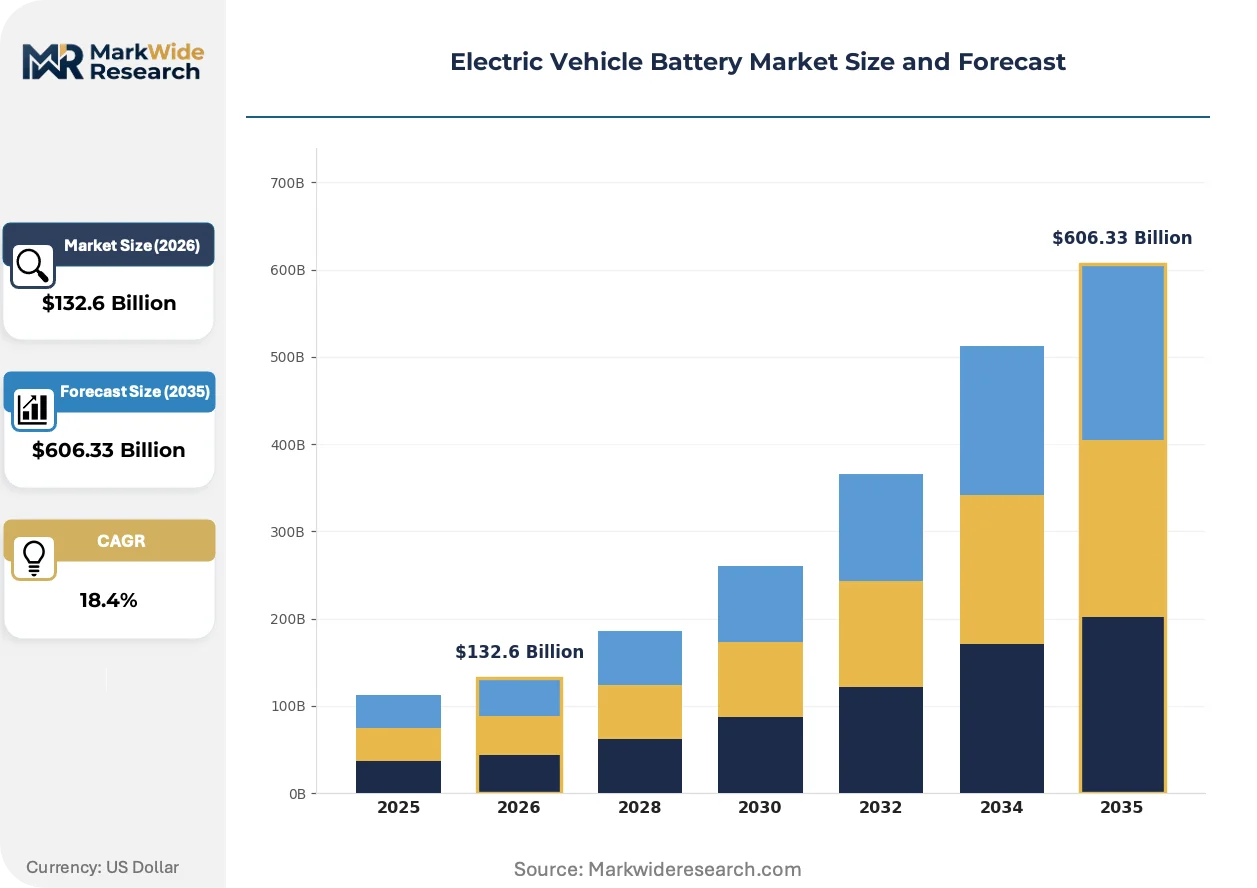
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $606.33 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Solid-state, Lead-acid End User: Personal Vehicles, Commercial Fleets, Public Transportation, Two-wheelers Capacity: 50 kWh, 100 kWh, 150 kWh, 200 kWh Charging Technology: Fast Charging, Wireless Charging, Standard Charging, Smart Charging |
| Companies Covered | Contemporary Amperex Technology Co. Limited, BYD Company Ltd., LG Energy Solution Ltd., Panasonic Energy, Samsung SDI, SK On, CALB, Gotion High-Tech, Sunwoda Electronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Market Emerging Trajectories
Cell architecture and manufacturing process innovation is compressing cost curves while regulatory pressure accelerates chemistry diversification. The competitive frontier has shifted from scale economies to materials science breakthroughs and circular supply chain design.
Solid-state electrolyte technology is unifying safety and energy density objectives that conventional liquid systems could not simultaneously achieve. Automotive OEMs in South Korea and Japan are pilot-testing sulfide-based cells for 2027 platform launches. The technology is unifying previously separate thermal management and structural battery pack functions, enabling cell-to-chassis integration that reduces vehicle weight.
The EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of electrolyte solvents and binder materials used in electrode manufacturing. Cell producers must now qualify alternative fluorinated compounds and water-based slurry processes to maintain European market access. High-voltage cathode chemistries face the tightest substitution timelines, driving partnerships between material suppliers and European recycling operators.
Fleet operators are consolidating procurement around total-cost-of-ownership contracts that bundle hardware, software, and residual value guarantees. This displaces traditional per-kWh component purchasing in municipal bus and delivery van segments. The shift is most visible in California and the Netherlands, where public transit authorities now require decade-long performance warranties with guaranteed degradation curves.
Electric Vehicle Battery Market Segmentation
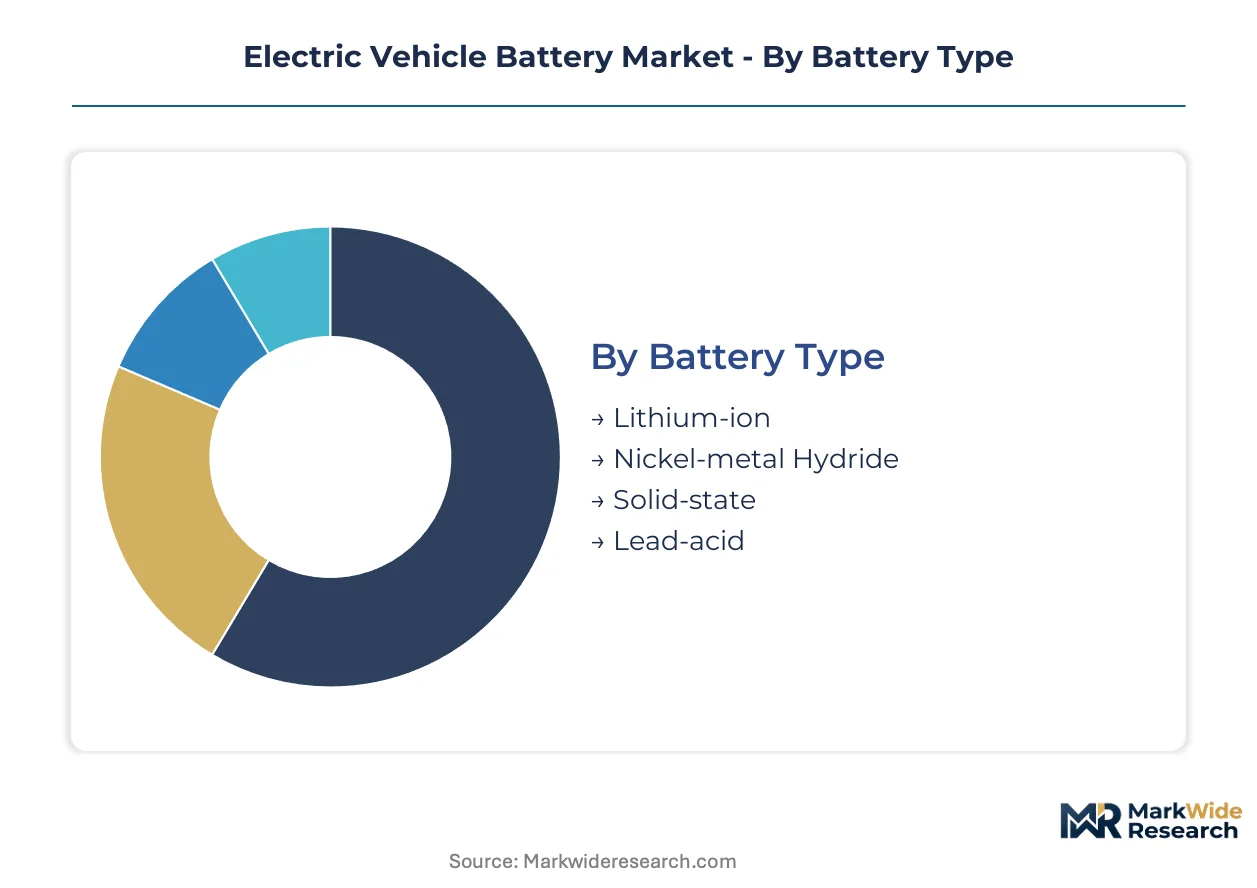
Segmentation in the Electric Vehicle Battery Market reveals how chemistry choices, duty cycles, and infrastructure availability partition value capture. Manufacturers align product portfolios to specific integration depths, from standalone aftermarket packs to embedded chassis-integrated systems.
Battery Type:
Integration depth varies sharply across chemistries, with some formats engineered for drop-in replacement and others locked into vehicle platform architectures.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants deliver energy densities above 250 Wh/kg through liquid electrolyte architectures. Demand clusters in Germany's industrial corridor for premium passenger platforms, where OEMs specify cell-to-pack designs that eliminate module housings.
- Solid-state:Sulfide and oxide electrolyte chemistries eliminate thermal runaway risks while enabling anode-less configurations. South Korean automotive OEMs are pilot-testing these cells for platform launches, targeting the safety-critical commercial fleet segment where downtime costs dwarf cell premiums.
- Nickel-metal Hydride:Mature chemistry retains share in hybrid-electric transitional architectures requiring shallow discharge cycles.
- Lead-acid:Low-voltage auxiliary applications in commercial vehicle starter systems persist where cost floors dominate performance requirements.
Volume placements concentrate in Lithium-ion; the faster expansion belongs to Solid-state.
End User:
Cost tier differentiation separates warranty-backed OEM supply from price-sensitive aftermarket procurement.
- Commercial Fleets:Logistics operators in California and the Netherlands negotiate total-cost-of-ownership contracts bundling hardware, software, and decade-long degradation guarantees. High-cycle-duty configurations command premium pricing tiers unavailable to passenger segments.
- Personal Vehicles:Individual ownership models drive per-kWh component purchasing with residual value risk carried by consumers. Entry-level segments in India favor lithium-iron-phosphate chemistries that trade energy density for thermal stability and cobalt elimination.
- Public Transportation:Municipal bus authorities specify overnight depot charging infrastructure paired with high-capacity packs.
- Two-wheelers:Dense urban corridors in India and Southeast Asia create volume opportunities at compressed per-unit margins, with swappable pack architectures decoupling vehicle purchase from energy storage ownership.
Margin capture peaks with Commercial Fleets; Two-wheelers expand most quickly through government electrification mandates.
Capacity:
Application duty cycles determine whether packs serve as primary traction sources or range-extending supplements.
- 100 kWh:Mid-size passenger platforms targeting 400-kilometer nominal range dominate contemporary OEM lineups. China's MIIT new-energy vehicle mandates effectively standardize this capacity class for domestic market compliance.
- 150 kWh:Premium sedans and light commercial vans require this tier for highway-speed range assurance. South Korean cathode material clusters supply the high-nickel formulations enabling these energy densities.
- 50 kWh:Urban commuter segments and two-wheeler applications optimize for curb weight and charging frequency over absolute range.
- 200 kWh:Heavy-duty municipal buses and regional delivery trucks specify this capacity for full-shift operation without opportunity charging.
Procurement concentrates at 100 kWh; the steepest expansion trajectory tracks 150 kWh as fast-charging infrastructure reduces range anxiety penalties.
Charging Technology:
Customer type stratification separates infrastructure-constrained residential users from fleet operators with dedicated depot facilities.
- Fast Charging:DC systems delivering 150-350 kW enable 20-minute recharge windows critical for commercial fleet utilization rates. Deployment concentrates along German autobahn corridors and California interstate corridors where logistics operators prioritize vehicle uptime.
- Smart Charging:Grid-integrated systems with vehicle-to-load capability allow fleet operators to monetize parked capacity through frequency regulation services. Dutch public transit authorities mandate this functionality for new procurements.
- Standard Charging:AC Level 2 residential and workplace installations serve overnight dwell-time applications.
- Wireless Charging:Inductive pad systems target premium passenger segments and autonomous shuttle applications where connector wear poses operational risks.
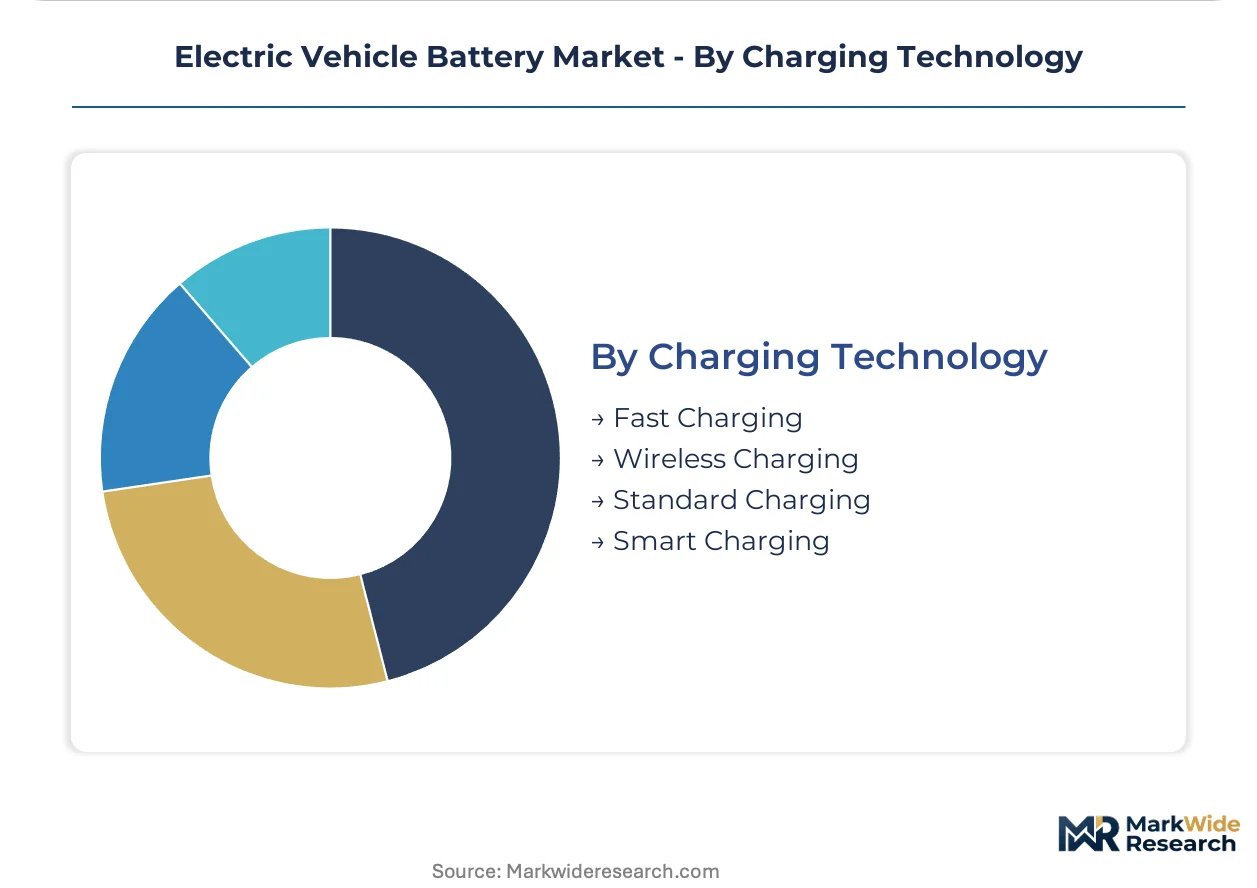
Fast Charging claims the dominant installation base; Smart Charging gains share fastest through utility rate structures rewarding demand response participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo's battery-grade lithium refining special economic zone concentrates cathode precursor capacity for export-oriented manufacturers serving European OEM compliance timelines.
China
MIIT production quotas force domestic automakers to secure multi-year cell supply contracts, stabilizing factory utilization for producers. The dual carbon goals mandate carbon-footprint declarations across the battery value chain. Sichuan and Qinghai provinces host refined lithium processing clusters where hydrometallurgical extraction expands to meet cathode material demand.
Germany
Premium passenger OEMs specify cell-to-pack designs eliminating module housings for weight reduction. The EU Battery Regulation imposes mandatory recycled-content thresholds and carbon-border adjustments favoring established recovery networks. Thuringia's gigafactory corridor attracts Korean cathode suppliers seeking European market access compliance.
United States
Commercial fleet operators in California negotiate decade-long performance warranties with guaranteed degradation curves. EPA tailpipe standards tighten production volume requirements and battery performance thresholds. Michigan's automotive engineering cluster hosts solid-state R&D partnerships between domestic OEMs and material science startups.
South Korea
Automotive OEMs pilot-test sulfide-based solid-state cells for platform launches targeting safety-critical commercial segments. The national industrial policy supports high-nickel cathode formulation development through targeted R&D subsidies. Gyeonggi Province's battery material cluster supplies advanced chemistries enabling energy densities above industry benchmarks.
India
Two-wheeler electrification in dense urban corridors creates volume opportunities at compressed per-unit margins. The PLI scheme for advanced chemistry cells attracts manufacturing investment to serve domestic electrification mandates. Tamil Nadu's industrial corridor hosts emerging cell assembly operations targeting three-wheeler and urban mobility applications.
Electric Vehicle Battery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across cell manufacturing tiers. The market structure consolidates around scale-driven producers with captive raw material access and technology licensing partnerships. Three archetypes dominate: vertically integrated vehicle-battery combinations, standalone cell specialists with deep OEM relationships, and materials-science ventures advancing solid-state architectures. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure cathode supply and manufacturing footprint.
Within the conglomerate tier, BYD Company Ltd. and Contemporary Amperex Technology Co. Limited occupy positions reflecting different integration models. LG Energy Solution Ltd. exemplifies the specialist archetype through its Korean corporate structure and concentrated focus on electrochemical systems. These three anchors represent the geographic distribution of manufacturing gravity across East Asian production networks.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| BYD Company Ltd. |
| LG Energy Solution Ltd. |
| Panasonic Energy |
| Samsung SDI |
| SK On |
| CALB |
| Gotion High-Tech |
| Sunwoda Electronic |
| Others |
Supply Flow & Price Mechanics
Commercial fleet operators in California and the Netherlands negotiate decade-long total-cost-of-ownership contracts that compress supplier margins while locking in volume commitments. This buyer concentration forces cell manufacturers toward contract-based long-term offtake pricing with performance guarantees that shift residual value risk onto producers.
Pricing Analysis
Premium pricing attaches to short lead-time deliveries for high-nickel cathode formulations, while spot inventory of lithium-iron-phosphate cells trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified supply from aftermarket and grid storage tiers. Pricing pressure stems from OEM demands for higher energy density without proportional cost pass-through. Two-wheeler electrification segments in India exhibit highest price sensitivity; commercial fleets with uptime penalties show least sensitivity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and proposed US IRA compliance rules are reshaping sourcing toward regional cathode precursor plants. Manufacturing gravity centers on China, South Korea, and Japan for cell assembly, with refined lithium processing concentrated in China's Sichuan and Qinghai provinces. The chain draws from nickel ore in Indonesia, lithium brine in Chile, and cobalt from the DRC. Single-source vulnerability in Chinese lithium refining exposes cell makers to export policy shifts. Distribution runs through OEM direct supply contracts and tiered distributor networks serving aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell manufacturing economics favor scale consolidation as gigafactory capex intensity and EU Battery Regulation compliance costs force sub-scale producers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into cathode precursor synthesis to insulate against nickel and lithium price volatility. Secure carbon-border-adjustment-compliant recycling networks in Germany and Thuringia's industrial corridor before EU Battery Regulation thresholds tighten. Lock in multi-year offtake contracts with South Korean automotive OEMs piloting solid-state platforms. For New Entrants and Emerging Players: Launch via battery-as-a-service models in Indian two-wheeler and three-wheeler corridors where asset-light swappable architectures bypass cell manufacturing scale requirements. Target Tamil Nadu's industrial corridor for contract assembly partnerships serving domestic electrification mandates. Pursue sodium-ion hybrid pack designs as a chemistry differentiation angle. For Investors and Strategic Acquirers: The window for entry favors materials-science ventures with sulfide-based solid-state electrolyte patents and captive polymer chemistry talent. Solid-state prototype-to-production timelines and UN 38.3 certification bottlenecks will determine which ventures achieve automotive qualification. Watch for OEM platform launch delays as the inflection signal for M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Synthesis | Captive nickel and lithium processing in Sichuan and Qinghai insulates against Indonesian ore export restrictions. |
| Solid-State Electrolyte Platform Partnership | Sulfide-based cell qualification with South Korean OEMs secures 2027 platform launch slots ahead of competitors. |
| Battery-as-a-Service Model Deployment | Swappable pack architectures in Indian urban corridors decouple vehicle purchase from energy storage ownership. |
| EU Recycling Network Acquisition | Closed-loop material recovery capabilities satisfy REACH compliance and carbon-footprint declaration mandates. |
| Sodium-Ion Hybrid Pack Development | Cost-optimized configurations pairing sodium base load with lithium peak discharge target two-wheeler volume segments. |
Methodological Framework
Multi-period observation of cathode material pricing spreads, OEM platform launch timelines, and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with cell manufacturing executives, cathode material procurement leads, automotive platform engineers, and recycling facility operators. Secondary validation drew from MIIT production quota disclosures, EPA tailpipe standard rulemakings, EU Battery Regulation implementation texts, and customs trade data for lithium compound flows. Bottom-up cell shipment estimates and top-down OEM electrification targets were triangulated to constrain forecast variance.
Segment-weighting applied chemistry type, end-user duty cycle, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from installed capacity buildout schedules and OEM platform electrification ratios. Industry-specific inputs included solid-state pilot production announcements, UN 38.3 certification timelines, and PLI scheme disbursement trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state commercialization or sodium-ion scale-up would alter the outlook. Forecasts reflect assumptions regarding OEM platform launch timing, cathode material cost trajectories, and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Traction Battery Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
EV Battery Heating System Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market