
 DCIM Market | 2026-2036
DCIM Market Size, Share, and Industry Trends Forecast 2026-2036
DCIM Market Analysis
The capital-intensity divergence between integrated platform vendors and point-solution specialists is bifurcating competitive dynamics across the DCIM landscape. Vertiv leverages its power and thermal infrastructure heritage to bundle hardware-software solutions for hyperscale operators. Schneider Electric anchors its position through EcoStruxure IT, extending from edge deployments to enterprise colocation facilities. Siemens competes via its building-to-IT integration capabilities, connecting DCIM layers with broader smart infrastructure portfolios.
Data center infrastructure management encompasses software and hardware systems that monitor, manage, and optimize facility resources including power distribution units, cooling systems, and physical assets through real-time telemetry and predictive algorithms. The primary commercial purpose centers on reducing operational expenditure while ensuring uptime compliance against tiered reliability standards. Monitoring Software dominates current procurement volumes as operators retrofit legacy facilities with sensor networks, while Analytics Tools represents the fastest-expanding margin pool where machine learning models transform raw telemetry into actionable capacity forecasts. Cloud-Based deployment is displacing traditional on-premises installations among mid-tier enterprises seeking subscription flexibility without dedicated IT operations staff.
EPA ENERGY STAR certification requirements and the EU Energy Efficiency Directive shape product roadmaps by mandating granular power usage effectiveness reporting across commercial data center operations. ISO 50001 energy management standards and ASHRAE thermal guidelines further constrain equipment specifications and software validation protocols for vendors seeking multinational contracts. Stakeholders must weigh interoperability investments against proprietary ecosystem lock-in as regulatory fragmentation across jurisdictions complicates single-platform standardization strategies.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for DCIM platforms as multi-megawatt facility buildouts accelerate across Northern Virginia, Frankfurt, and Singapore. This buyer concentration is forcing vendors to rearchitect pricing models and integration protocols around single-tenant deployment specifications.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates granular power usage effectiveness reporting across commercial data center operations in Germany, France, and the Netherlands. Operators retrofit legacy facilities with sensor networks to achieve compliance deadlines.
- Edge computing buildouts:Telecommunications carriers deploy micro-data centers in secondary cities, creating demand for compact DCIM modules with remote telemetry capabilities. These installations require real-time thermal monitoring without on-site technical staff.
- Carbon reporting mandates:France's mandatory environmental disclosure rules and Germany's supply chain due diligence laws compel colocation providers to document energy consumption through certified DCIM analytics platforms.
Market Restraints
- Semiconductor input volatility:Sensor chip shortages and power management integrated circuit allocation constraints extend hardware delivery timelines for DCIM appliance vendors. Lead times for industrial-grade temperature sensors now stretch 26-34 weeks.
- Proprietary protocol lock-in:Legacy building management systems from established automation vendors resist interoperability with modern DCIM software layers. BACnet and Modbus integration requires expensive middleware development.
- Substitution by in-house development:Amazon Web Services, Microsoft Azure, and Google Cloud maintain captive engineering teams that build proprietary monitoring tools rather than licensing third-party platforms.
Strategic Opportunities
- India data center expansion:Mumbai and Chennai hyperscale projects under the country's PLI scheme create first-mover positioning for DCIM vendors offering tropical climate cooling optimization. Domestic operators lack legacy infrastructure baggage.
- AI-driven predictive maintenance:Machine learning models trained on historical thermal and power telemetry enable failure prediction 48-72 hours before critical events. This convergence reduces unplanned downtime costs for financial services colocation clients.
- Subscription revenue migration:Mid-tier enterprises prefer cloud-based DCIM deployments with monthly SaaS pricing over perpetual license models. Channel partners in the United Kingdom and Ireland report 40% faster sales cycles for hosted solutions.
Industry Challenges
- Multi-protocol integration complexity:Facilities mixing IT equipment from Dell, HPE, and Cisco with cooling infrastructure from Carrier, Trane, and Stulz require custom API development. Each integration project demands 4-6 months of professional services engagement.
- ISO 50001 certification timelines:Energy management system validation requires 12-18 months of continuous monitoring data before auditors approve compliance. Vendors must maintain proof-of-concept installations through extended evaluation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DCIM Market |
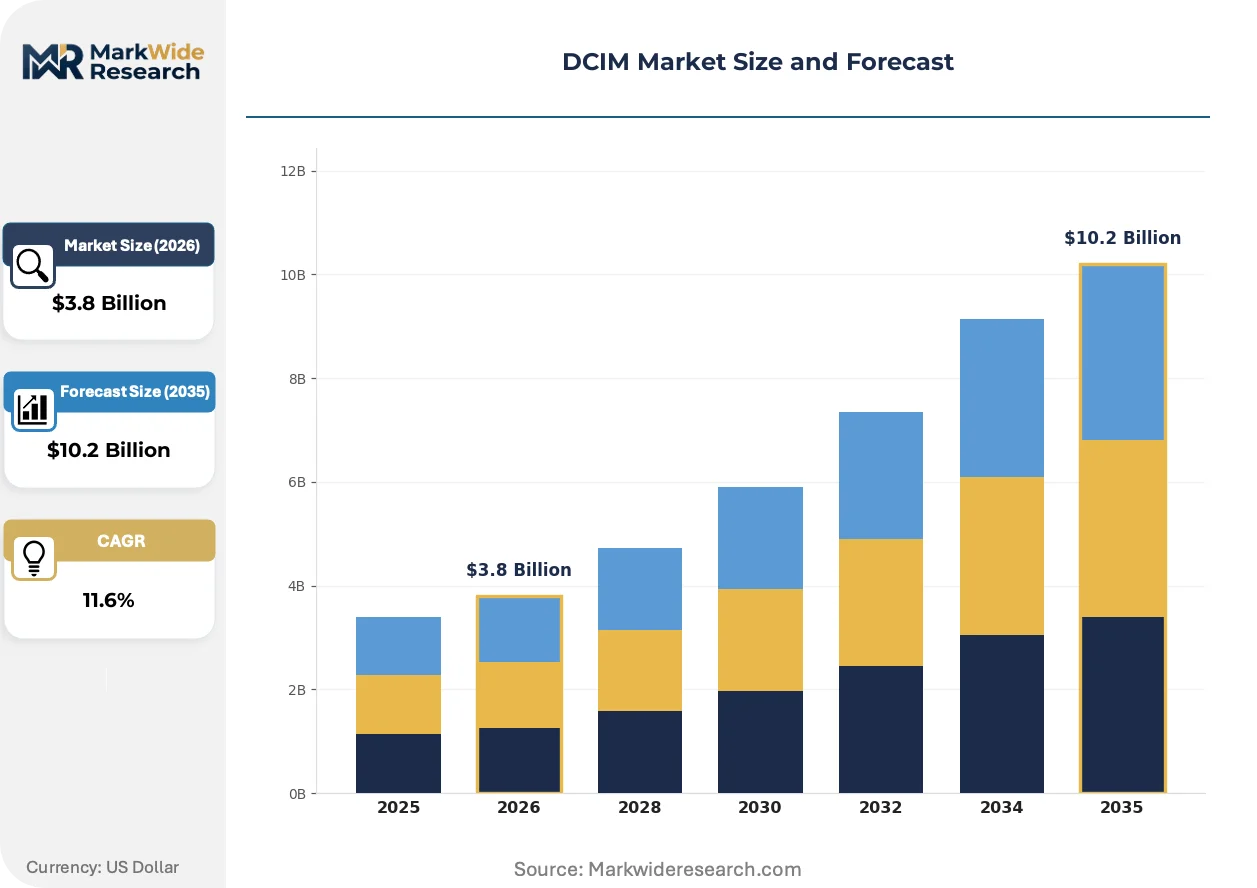
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Software, Management Software, Analytics Tools, Integration Platforms Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Data Centers, Enterprises, Colocation Providers, IT Service Providers Feature: Capacity Planning, Power Management, Environmental Monitoring, Asset Tracking |
| Companies Covered | Vertiv, EkkoSense, Sunbird Software, IBM, Siemens, Nlyte Software, FNT Software, Cormant (BGIS), Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DCIM Market Emerging Trajectories
DCIM architecture is fragmenting from monolithic platforms into composable microservices that operators deploy selectively. This modularization enables faster iteration cycles and reduces vendor lock-in risks for facility managers managing heterogeneous infrastructure estates.
Digital twin technology is decomposing traditional DCIM visualization layers into physics-based simulation engines that model airflow, heat distribution, and power flow in real time. Colocation providers in Singapore and Sydney deploy these tools to optimize cooling setpoints before physical changes. The technology compresses commissioning timelines for new data hall builds from months to weeks.
CSRD disclosure requirements are mandating granular Scope 2 emissions reporting across EU-based data center operations. Operators must now trace electricity consumption to specific generation sources and document carbon intensity by facility. Financial services and cloud computing segments in Frankfurt and Amsterdam face the steepest compliance curves, driving procurement of certified monitoring platforms with audit-ready data architectures.
Facility managers increasingly unbundle hardware procurement from software licensing and professional services contracts. Large enterprises negotiate direct relationships with sensor manufacturers while sourcing analytics platforms through systems integrators. This tripartite purchasing pattern is most visible in United States federal government and healthcare verticals, where contracting officers demand price transparency across component categories.
DCIM Market Segmentation
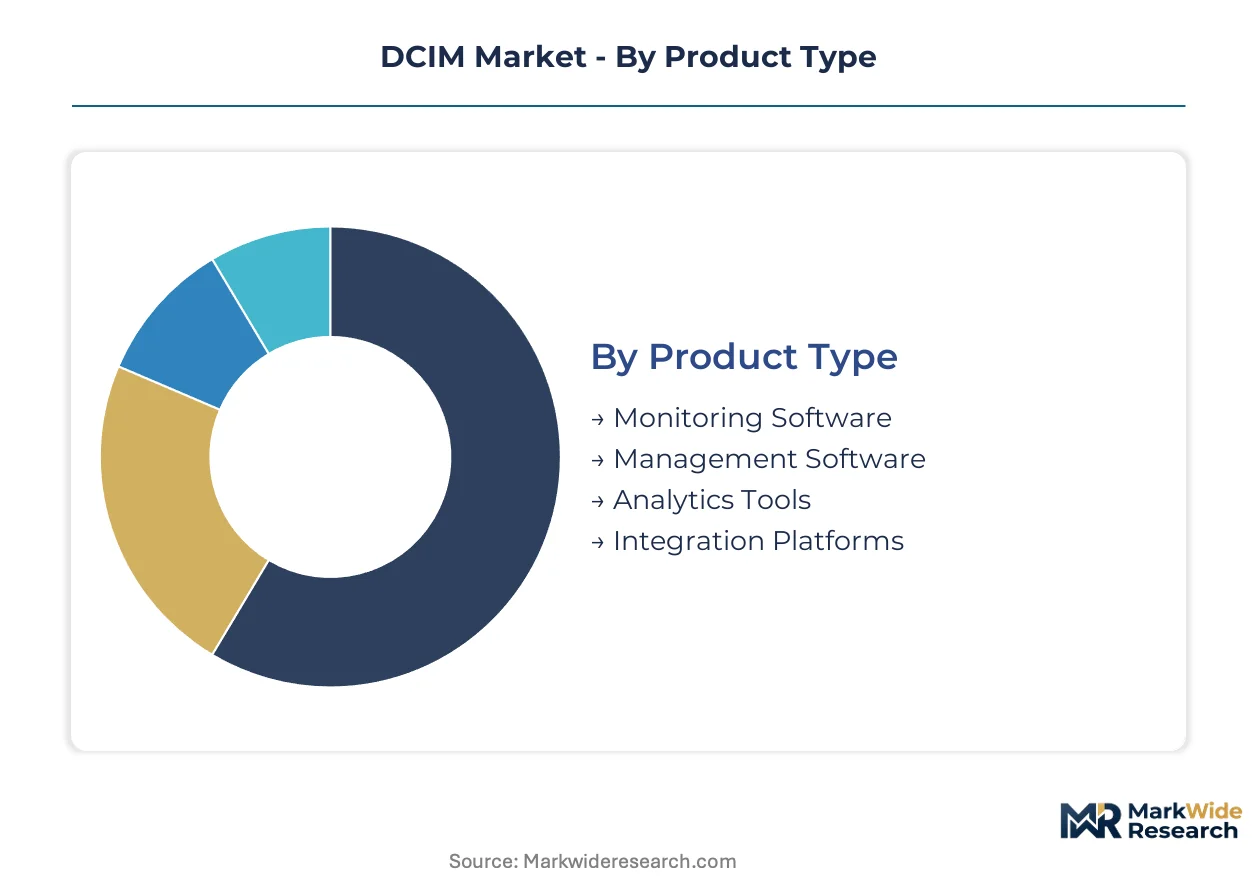
DCIM procurement patterns diverge sharply across deployment scales and regulatory environments. Facility operators select product architectures based on legacy infrastructure constraints, compliance deadlines, and in-house technical capacity.
Product Type:
Domestic procurement concentrates in monitoring software for retrofit projects, while analytics tools command premium pricing in export-led deployments across EU carbon-reporting jurisdictions.
- Monitoring Software:Real-time sensor networks track power distribution units, cooling systems, and physical assets through telemetry dashboards. Demand clusters in United States federal facilities and German industrial zones facing EU Energy Efficiency Directive retrofit deadlines. Operators prioritize BACnet and Modbus protocol compatibility to bridge legacy building management investments.
- Analytics Tools:Machine learning models transform raw telemetry into capacity forecasts and failure predictions. Singapore and Sydney colocation providers deploy these for cooling setpoint optimization ahead of physical infrastructure changes. CSRD disclosure requirements in Frankfurt and Amsterdam accelerate procurement of audit-ready platforms.
- Management Software:Workflow automation for change management and ticketing integration.
- Integration Platforms:API middleware connecting heterogeneous infrastructure estates.
Monitoring Software holds the largest share; momentum sits with Analytics Tools.
Deployment:
Cost-tier stratification separates hyperscale single-tenant builds from mid-tier subscription preferences.
- Cloud-Based:SaaS delivery eliminates dedicated IT operations staff requirements. United Kingdom and Ireland channel partners report accelerated sales cycles for hosted solutions among mid-tier enterprises. Monthly pricing models displace perpetual licenses in healthcare and financial services verticals seeking capital expenditure flexibility.
- On-Premises:Air-gapped installations serve defense and intelligence community facilities with classified operational requirements. United States federal contracting officers mandate direct sensor manufacturer relationships with price transparency across component categories.
- Hybrid:Split architectures for edge computing micro-data centers with centralized analytics cores.
- Multi-Cloud:Orchestration layers spanning AWS, Azure, and Google Cloud environments.
On-Premises retains the installed base; Cloud-Based is climbing the fastest.
End User:
Application intensity varies by uptime tier and regulatory exposure across facility types.
- Colocation Providers:Multi-tenant facilities require granular tenant billing and sub-metering capabilities. France's mandatory environmental disclosure rules and Germany's supply chain due diligence laws compel certified DCIM platform deployment. Financial services clients in Frankfurt demand 48-72 hour failure prediction horizons.
- Data Centers:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore compress procurement cycles for single-tenant specifications. Amazon Web Services, Microsoft Azure, and Google Cloud maintain captive engineering teams building proprietary tools rather than licensing third-party platforms.
- Enterprises:Corporate IT departments with limited facilities management expertise.
- IT Service Providers:Managed service offerings for distributed infrastructure estates.
Data Centers command the deepest per-facility investment; Colocation Providers show the steepest expansion trajectory.
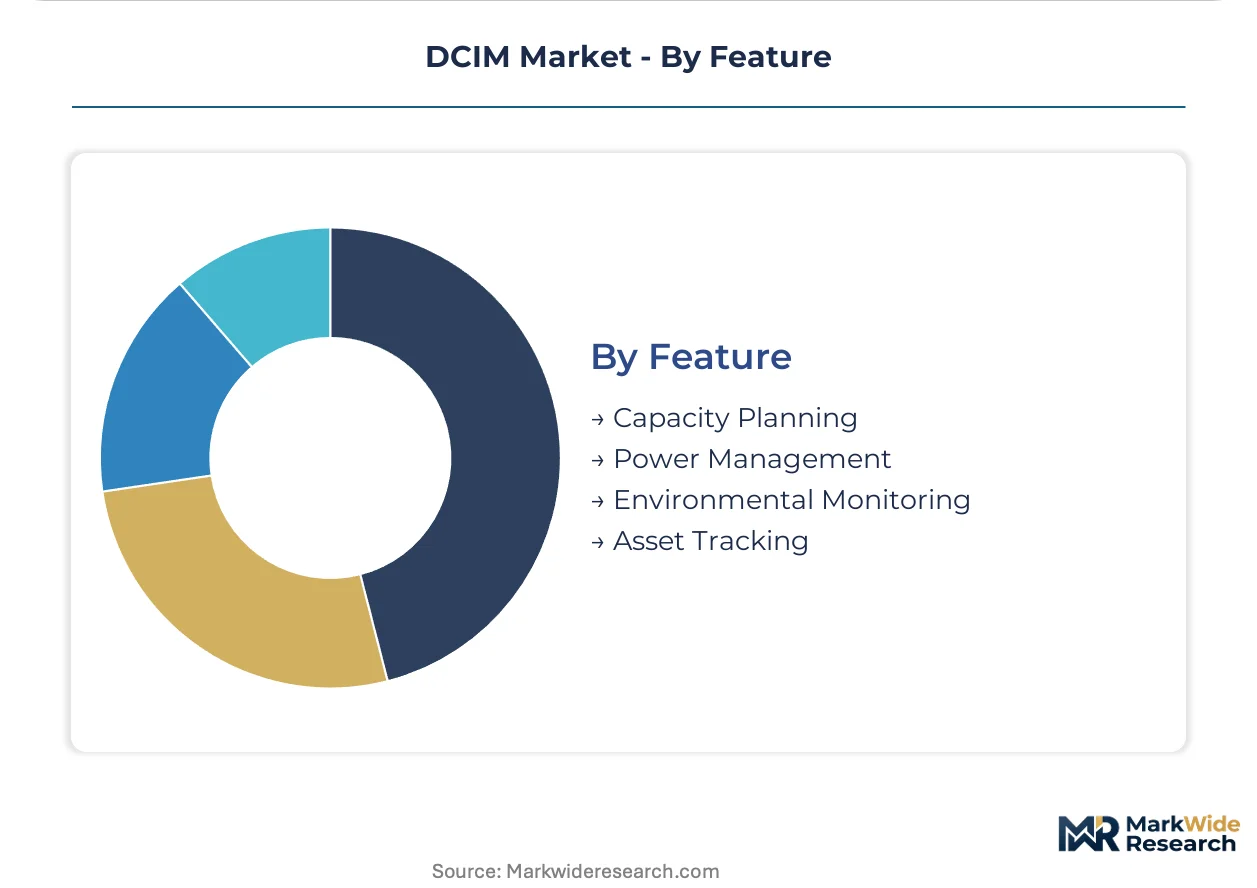
Feature:
Maturity differentiation separates established capabilities from emerging margin pools.
- Power Management:Real-time power usage effectiveness tracking and circuit-level monitoring. EPA ENERGY STAR certification requirements mandate granular reporting across commercial United States operations. ISO 50001 validation demands 12-18 months of continuous monitoring data before auditor approval.
- Environmental Monitoring:Temperature, humidity, and airflow sensing with ASHRAE guideline compliance. Semiconductor input volatility extends industrial-grade sensor lead times to 26-34 weeks, constraining hardware delivery timelines.
- Capacity Planning:Space, power, and cooling availability forecasting for growth scenarios.
- Asset Tracking:RFID and barcode-based physical inventory management.
Power Management anchors current procurement volumes; Environmental Monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Northern Virginia, where hyperscale procurement cycles compress vendor margins, while European operators in Frankfurt and Amsterdam absorb premium analytics costs driven by CSRD disclosure mandates.
United States
Virginia's data center corridor drives the largest regional procurement of DCIM analytics tools, with hyperscale operators demanding single-tenant deployment specifications. EPA ENERGY STAR certification requirements mandate granular power usage effectiveness reporting across commercial operations. Northern Virginia facility buildouts accelerate as cloud providers expand multi-megawatt campuses.
Germany
Frankfurt's financial services colocation sector demands 48-72 hour failure prediction horizons from certified DCIM platforms. The EU Energy Efficiency Directive compels operators to retrofit legacy facilities with sensor networks before compliance deadlines. Industrial zones in North Rhine-Westphalia prioritize BACnet and Modbus protocol compatibility for building management integration.
France
Paris-based colocation providers face mandatory environmental disclosure rules requiring documented energy consumption through certified analytics platforms. ANSM and CNIL oversight shapes data handling protocols for monitoring systems. Île-de-France hyperscale projects deploy real-time thermal monitoring without on-site technical staff.
Singapore
Colocation providers deploy digital twin technology to optimize cooling setpoints before physical infrastructure changes, compressing commissioning timelines from months to weeks. Tropical climate conditions create demand for specialized cooling optimization modules. Domestic operators lack legacy infrastructure baggage, enabling first-mover positioning for modular DCIM architectures.
India
Mumbai and Chennai hyperscale projects under the PLI scheme create procurement opportunities for vendors offering tropical climate optimization. The country's national energy regulator mandates efficiency standards for commercial data center operations. Domestic facility operators bypass legacy protocol constraints through greenfield deployment strategies.
DCIM Market Vendor Landscape
Concentration sits with integrated platform vendors leveraging infrastructure heritage to bundle hardware-software solutions. The competitive terrain bifurcates between these full-stack providers and point-solution specialists targeting retrofit sensor networks. Three archetypes dominate: power-thermal integrators extending from physical infrastructure, building-to-IT connectors bridging smart infrastructure portfolios, and analytics-first vendors capturing machine learning margin pools. M&A activity targets middleware capabilities for multi-protocol integration, while capacity expansion concentrates in hyperscale-aligned engineering teams.
Within the integrated platform tier, Vertiv and Schneider Electric exemplify contrasting heritage strategies. Vertiv occupies a position anchored in power and thermal infrastructure, translating physical equipment relationships into bundled software opportunities. Schneider Electric represents the building automation extension model, leveraging EcoStruxure IT to span edge deployments through enterprise colocation. Siemens sits within the smart infrastructure convergence archetype, connecting DCIM layers with broader industrial digitalization portfolios. These three demonstrate how vendor origin shapes competitive trajectory without guaranteeing segment capture.
| Leading Market Players |
|---|
| Vertiv |
| EkkoSense |
| Sunbird Software |
| IBM |
| Siemens |
| Nlyte Software |
| FNT Software |
| Cormant (BGIS) |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
ISO 50001 certification requirements gate both vendor qualification and price differentiation simultaneously, compelling DCIM providers to absorb extended validation costs while segmenting offerings across audit-ready and basic monitoring tiers. Buyers in regulated European jurisdictions absorb premium pricing for certified platforms, while federal facilities in the United States demand component-level cost transparency that compresses bundled margins.
Pricing Analysis
The customization-premium spread separates standard SaaS subscriptions from configured-to-order deployments with proprietary protocol middleware. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and integration complexity. Cost compression in the standard tier is intensifying because hyperscale operators negotiate direct sensor procurement, bypassing vendor markups. Mid-tier enterprises show greatest price sensitivity, while financial services colocation clients in Frankfurt demonstrate willingness to pay for predictive failure horizons.
Supply Chain Analysis
China and Taiwan anchor semiconductor sensor fabrication for DCIM hardware, with Germany and Japan supplying precision power management components. Industrial-grade temperature sensors and power distribution monitoring modules draw from concentrated Asian foundry capacity. Single-source vulnerability runs through 26-34 week lead times for specialized environmental sensors. Distribution runs through systems integrators and direct vendor relationships, with federal contracting officers mandating unbundled component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU CSRD disclosure mandates and EPA ENERGY STAR certification requirements are accelerating DCIM procurement cycles, creating a high-growth disruption as operators retrofit legacy facilities before compliance deadlines.
For Market Incumbents: Fortify middleware capabilities for BACnet and Modbus integration to defend against point-solution specialists capturing retrofit sensor network contracts. Expand engineering capacity in Northern Virginia and Frankfurt to compress hyperscale deployment timelines. ISO 50001 certification investment represents the priority defensive lever against audit-ready platform competitors. For New Entrants and Emerging Players: ISO 50001 fast-track certification creates positioning for mid-tier European colocation providers facing compressed compliance timelines. White-space concentrates in India's tropical climate optimization segment under the PLI scheme, where domestic operators lack legacy protocol constraints. SaaS-native deployment with monthly pricing models offers the most penetrable go-to-market angle for healthcare and financial services verticals seeking capital expenditure flexibility. For Investors and Strategic Acquirers: CSRD implementation reshapes the acquisition landscape toward middleware specialists with multi-protocol integration capabilities. Long-term viability centers on vendors bridging building automation and IT infrastructure layers. The acquisition target archetype combines physics-based digital twin technology with established sensor hardware relationships. Watch hyperscale captive engineering team expansion as the signal indicating substitution risk for third-party platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Predictive Maintenance Development | Machine learning models trained on thermal telemetry reduce unplanned downtime for financial services colocation clients. |
| Digital Twin Platform Integration | Physics-based simulation engines compress commissioning timelines for Singapore and Sydney facility buildouts. |
| Cloud-Based SaaS Migration | Subscription pricing accelerates sales cycles among United Kingdom and Ireland mid-tier enterprise buyers. |
| Middleware Acquisition for Protocol Integration | API development capabilities address 4-6 month professional services demands for heterogeneous infrastructure estates. |
| Tropical Climate Optimization Module Launch | Specialized cooling algorithms capture first-mover positioning in Mumbai and Chennai hyperscale projects. |
Methodological Framework
The analysis maps monitoring software, analytics tools, management software, and integration platforms, each validated through facility operators, systems integrators, DCIM procurement officers, and building automation engineers. Primary interviews with data center infrastructure directors and colocation facility managers combine with secondary validation against EPA ENERGY STAR filings, EU Energy Efficiency Directive implementation reports, hyperscaler capital expenditure disclosures, and ISO 50001 certification databases. Bottom-up facility deployment tracking and top-down vendor revenue analysis enable triangulation across estimation approaches.
Consistency checks validate volume and value outputs against external benchmarks spanning deployment model penetration rates and regional procurement intensity patterns across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and feature capability tier. CAGRs derive from fitted growth curves applied to base-year market sizing, with inputs incorporating regulatory compliance deadline schedules and hyperscale facility buildout pipelines.
Underlying assumptions cover sustained regulatory enforcement timelines and semiconductor supply normalization, with deviation risk concentrated in tariff exposure for sensor hardware and substitution by hyperscale captive engineering teams. Recalibration cycles align with material shifts in carbon reporting mandate implementation schedules and hyperscale procurement specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market