
 Pharmaceutical Blockchain Market | 2026-2036
Pharmaceutical Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Blockchain Market Analysis
Pharmaceutical distribution networks are rewriting how drug provenance data flows from manufacturer to patient. IBM leverages its Hyperledger Fabric deployments to anchor enterprise-grade supply chain visibility across multinational drugmakers. Chronicled specializes in MediLedger protocol governance, competing on pharmaceutical-specific network standards rather than generic infrastructure. SAP SE extends its existing ERP dominance into blockchain modules that integrate with batch record systems already installed at major manufacturers.
Pharmaceutical blockchain denotes distributed ledger architectures applied to drug lifecycle verification, employing immutable hashing, smart contract automation, and node consensus typically executed on permissioned networks with sub-second finality requirements. Its primary purpose is to create tamper-evident audit trails for regulatory submission and counterfeit interdiction. Supply Chain Management solutions lead in deployment velocity because serialization mandates in the United States and Europe create immediate compliance deadlines with penalties. Permissioned Blockchain configurations capture the dominant architecture share, as pharmaceutical companies require identity-verified participants and confidential transaction visibility that public chains cannot guarantee. Data Integrity applications sit at the core of buyer value propositions, since immutable batch records directly satisfy FDA and EMA inspection protocols.
The FDA DSCSA requirements and the EU Falsified Medicines Directive are forcing pharmaceutical manufacturers to demonstrate interoperable traceability by statutory deadlines, which blockchain vendors position their platforms to satisfy. Health Canada and the UK's MHRA are aligning with similar serialization frameworks, expanding the addressable regulatory footprint for compliant solution providers. Stakeholders must weigh network governance models and cross-border data residency rules before committing to consortium architectures that lock in participant structures for decade-long operational horizons.
Market Dynamics
Serialization mandates from the FDA and EMA are forcing pharmaceutical manufacturers to replace paper-based batch records with immutable distributed ledgers that satisfy track-and-trace deadlines. This regulatory compression is restructuring procurement priorities across drugmakers, contract manufacturers, and wholesale distributors simultaneously.
Growth Catalysts
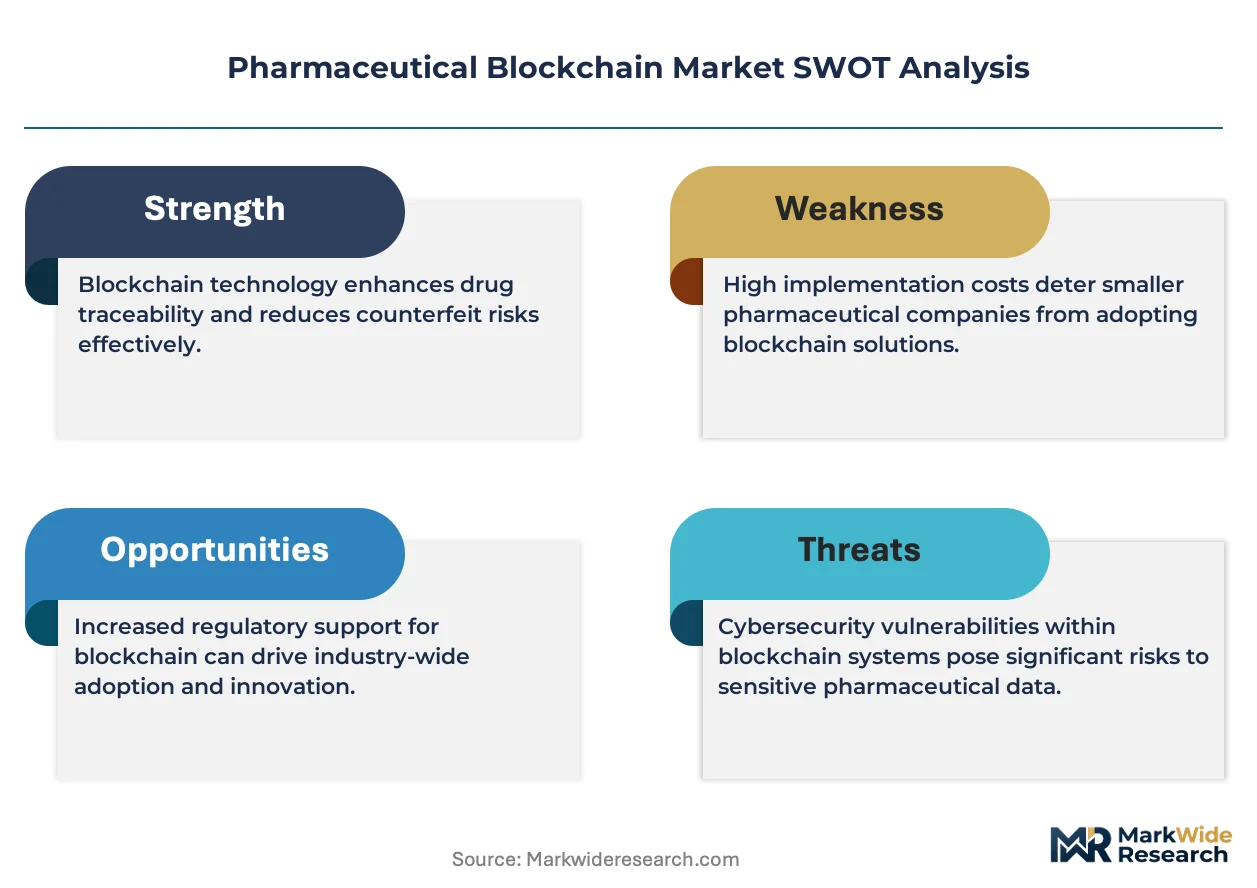
- DSCSA Interoperability Deadline:The FDA's Drug Supply Chain Security Act requires electronic, interoperable systems for prescription drug tracing, compelling manufacturers to deploy blockchain for verification at the package level.
- EU Falsified Medicines Directive:European serialization requirements for safety features and unique identifiers on medicines are expanding addressable demand for compliant ledger infrastructure across EU member states.
- Batch Record Digitization:Pharmaceutical quality systems are migrating from paper master batch records to hash-anchored electronic systems that satisfy FDA 21 CFR Part 11 and EMA GMP Annex 11 requirements.
Market Restraints
- Consortium Governance Friction:Permissioned pharmaceutical networks require locked-in participant structures that create decade-long operational dependencies and limit vendor switching flexibility.
- Cross-Border Data Residency:Divergent national data localization laws between the United States, Germany, and Switzerland fragment network architectures and inflate compliance architecture costs.
- Legacy ERP Integration Burden:SAP and Oracle systems at major manufacturers require custom middleware development to interface with blockchain nodes, extending deployment timelines.
Strategic Opportunities
- Clinical Trial Data Integrity:Immutable timestamping of patient consent forms and protocol amendments offers blockchain vendors entry into contract research organization workflows beyond supply chain applications.
- Health Canada Alignment:Canadian serialization requirements are converging with FDA standards, creating contiguous North American demand for unified traceability platforms.
- AI-Blockchain Convergence:Machine learning models for counterfeit detection are integrating with distributed ledgers to automate anomaly flagging within pharmaceutical distribution networks.
Industry Challenges
- Qualified Personnel Scarcity:Pharmaceutical companies face acute shortages of professionals combining GMP compliance expertise with distributed systems architecture skills.
- Validation Protocol Complexity:Computer system validation for blockchain deployments under FDA guidelines requires extensive IQ/OQ/PQ documentation that extends implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Blockchain Market |
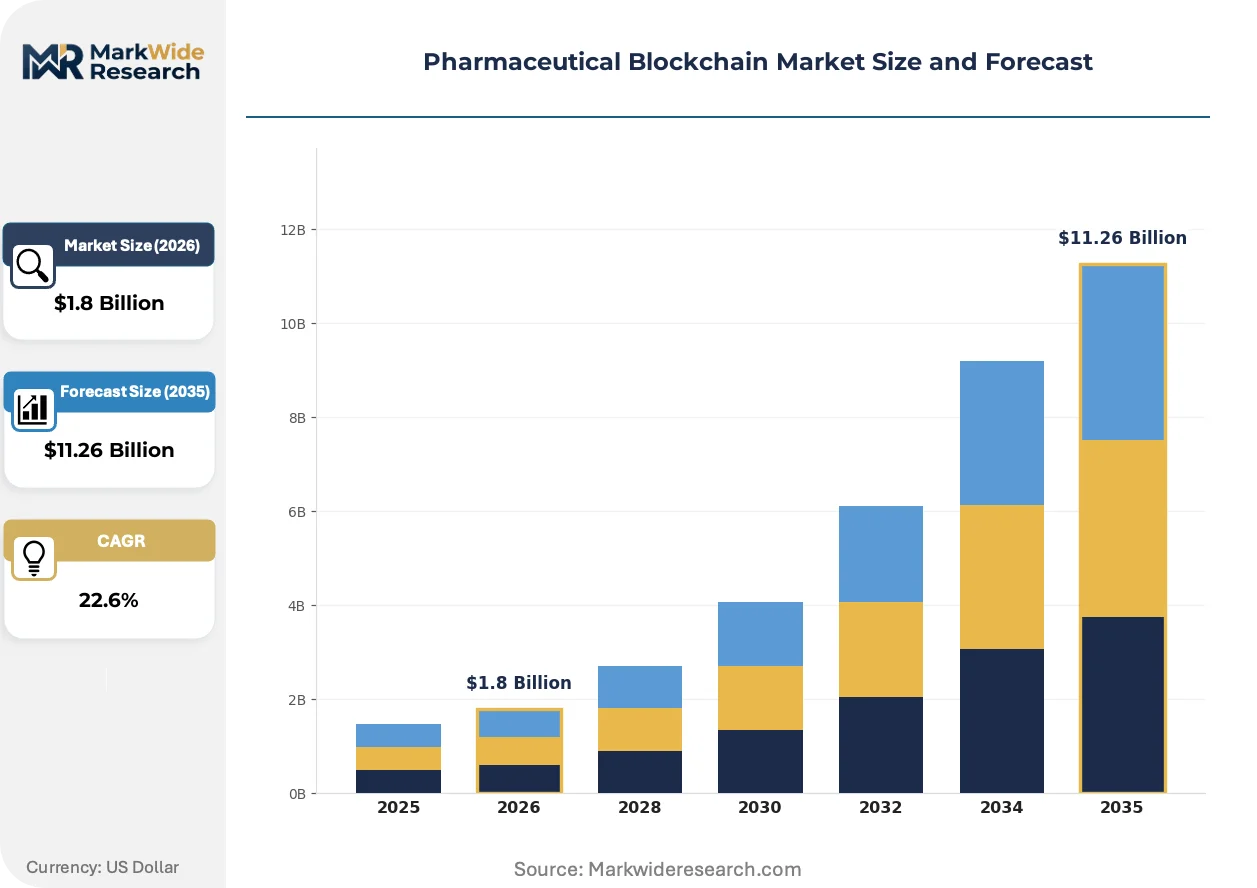
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.26 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Supply Chain Management, Clinical Trials, Medication Tracking, Drug Discovery Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Permissioned Blockchain End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Regulatory Authorities Application: Data Integrity, Patient Safety, Fraud Prevention, Compliance Monitoring |
| Companies Covered | IBM, Microsoft, Oracle, SAP SE, Tibco Software, Chronicled, Auxesis Group, VeChain Foundation, MediLedger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Blockchain Market Emerging Trajectories
Zero-knowledge proof architectures are entering pharmaceutical blockchain deployments, enabling manufacturers to verify drug authenticity without exposing proprietary formulation data to network participants. This privacy-preserving shift is restructuring competitive requirements for enterprise ledger vendors.
Private permissioned networks with sub-second finality are collapsing the latency gap between distributed ledgers and traditional database systems, enabling real-time serialization verification at high-throughput distribution centers. Large wholesale distributors are deploying these configurations to handle millions of package scans daily without batch processing delays. The compression of confirmation times is eliminating the historical throughput objection that blocked blockchain adoption in high-volume pharmaceutical logistics.
The EU AI Act's risk classification framework is intersecting with pharmaceutical traceability requirements, creating dual compliance obligations for automated decision systems in supply chain verification. Drug manufacturers deploying machine learning for counterfeit detection must now document algorithmic transparency alongside immutable audit trails. German and French regulators are inspecting these combined systems first, establishing enforcement precedents that other EU member states are adopting.
Hospital procurement departments are consolidating vendor qualification around pre-certified blockchain platforms, displacing fragmented due diligence processes with network-level trust assumptions. This concentration of buying criteria favors established pharmaceutical ledger consortia over newer entrants lacking health system validation. The shift is most visible in the United States, where group purchasing organizations for hospital systems are embedding blockchain verification into standard supplier contracts.
Pharmaceutical Blockchain Market Segmentation
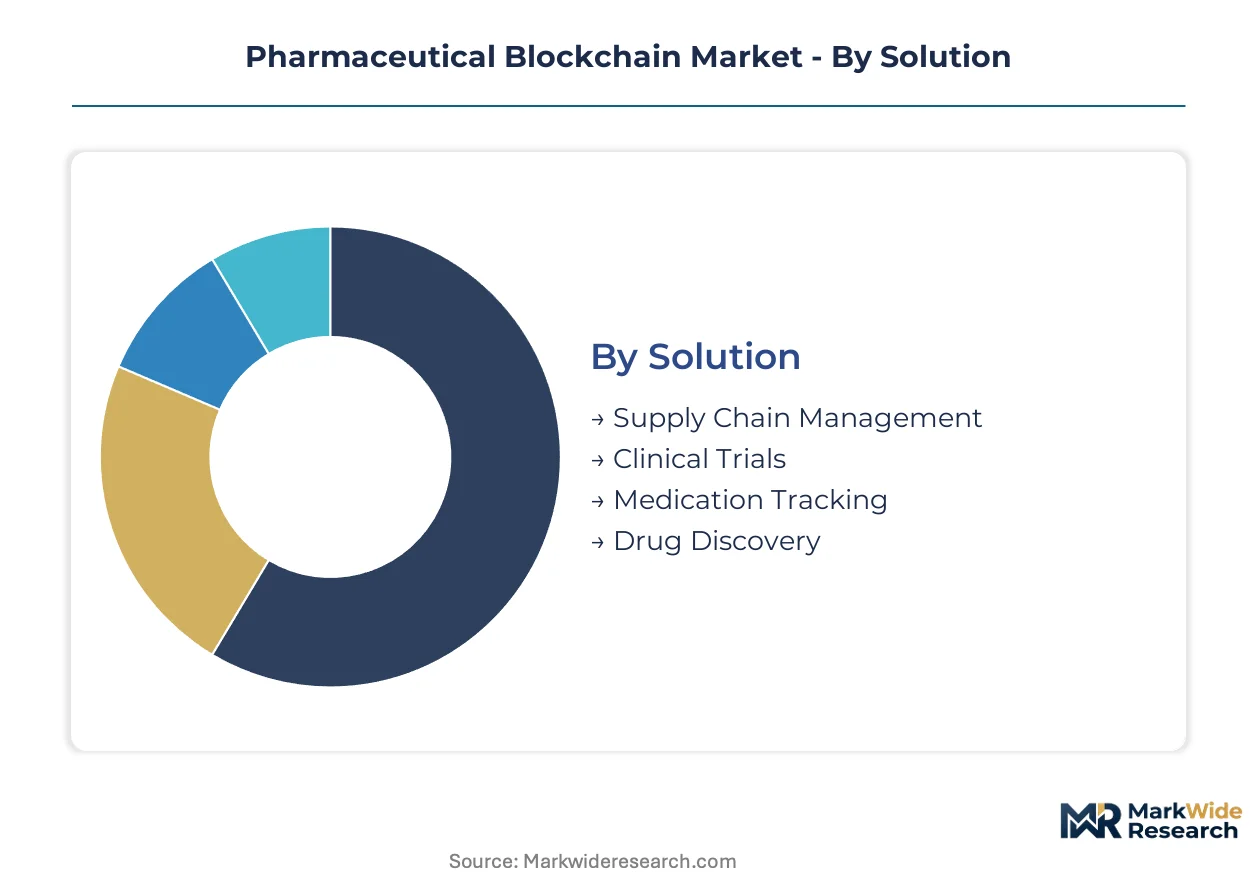
Pharmaceutical blockchain deployments fragment across solution maturity, infrastructure architecture, and stakeholder complexity. Each segmentation dimension reveals distinct procurement patterns, with regulatory deadlines forcing prioritization among competing investment pathways.
Solution:
Mature compliance-driven applications dominate procurement budgets, while emerging use cases in R&D accelerate experimental spending.
- Supply Chain Management:Distributed ledger architectures for serialization verification, cold chain monitoring, and wholesale distributor reconciliation. Demand concentrates at US wholesale distributors facing FDA DSCSA deadlines, with penalties for non-compliance driving enterprise-scale deployments.
- Clinical Trials:Immutable timestamping of patient consent, protocol amendments, and investigator site data. Research institutions in Switzerland and Germany are piloting these systems to satisfy EMA inspection protocols for trial data integrity.
- Medication Tracking:Package-level traceability from manufacturer to dispenser.
- Drug Discovery:Secure multi-party computation for preclinical data sharing.
Supply Chain Management handles the majority of throughput; Clinical Trials is expanding most quickly on share.
Technology:
Cost tier stratification separates high-assurance permissioned deployments from lower-cost public alternatives, with mid-range consortium models capturing collaborative networks.
- Permissioned Blockchain:Identity-verified nodes with confidential transaction channels and sub-second finality. Pharmaceutical companies in the United States require these configurations for FDA 21 CFR Part 11 compliance, with validated computer systems documentation.
- Consortium Blockchain:Multi-stakeholder governance with pre-defined participant rights. The MediLedger network exemplifies this architecture, with manufacturers, wholesalers, and dispensers sharing verification costs across the drug distribution chain.
- Private Blockchain:Single-organization node control with internal audit authority.
- Public Blockchain:Open participation with cryptocurrency settlement layers.
Permissioned Blockchain anchors the largest installed base; Consortium Blockchain is climbing the fastest as multi-party networks achieve critical mass.
End User:
Customer type determines procurement authority, with enterprise pharmaceutical manufacturers holding budget concentration versus distributed healthcare provider adoption.
- Pharmaceutical Companies:Enterprise deployments spanning manufacturing, distribution, and quality systems. Pfizer and Merck anchor demand in the United States, with serialization mandates forcing cross-functional blockchain integration.
- Regulatory Authorities:Inspection infrastructure for verifying manufacturer-submitted ledger data. The FDA and EMA are building technical capacity to audit distributed systems, creating vendor qualification requirements.
- Research Institutions:Academic medical centers and contract research organizations.
- Healthcare Providers:Hospital pharmacy departments and retail dispensers.
Pharmaceutical Companies control the dominant procurement volume; Regulatory Authorities are gaining share fastest as inspection protocols formalize.
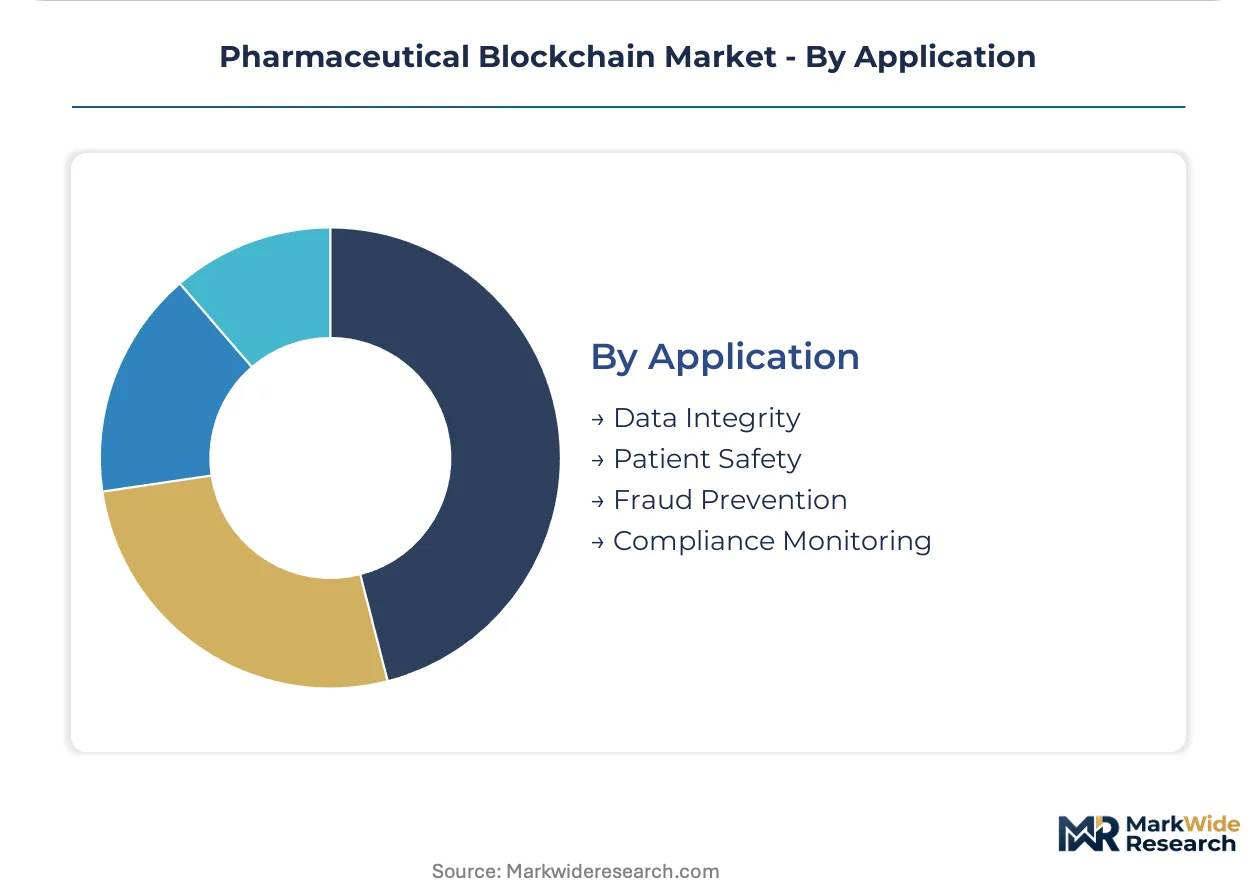
Application:
Application focus separates defensive compliance spending from proactive risk management investments, with fraud prevention emerging as a differentiated value proposition.
- Data Integrity:Immutable batch records, environmental monitoring logs, and quality system documentation. FDA warning letters for data integrity violations drive replacement of paper-based systems at US and EU manufacturing sites.
- Fraud Prevention:Counterfeit detection through package authentication and diversion monitoring. Indian pharmaceutical exporters deploy these systems to protect brand reputation in regulated markets.
- Compliance Monitoring:Automated regulatory submission and inspection readiness.
- Patient Safety:Adverse event traceability and recall acceleration.
Data Integrity commands the largest implementation footprint; Fraud Prevention shows the steepest expansion trajectory as counterfeit incidents trigger insurance and liability pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Switzerland, where FDA enforcement and Swissmedic inspection protocols command premium compliance spending that lags in emerging markets by 40-60 percent. German and Indian manufacturers absorb these asymmetries through differential platform licensing. Japanese and Australian regulators are accelerating toward parity through mutual recognition agreements.
United States
Wholesale distributors in Memphis and Louisville drive demand for sub-second finality networks handling millions of daily package scans. The FDA DSCSA interoperability deadline forces enterprise-scale deployments with validated computer systems documentation. New Jersey and Massachusetts pharmaceutical clusters anchor Hyperledger Fabric implementations for serialization verification.
Germany
Baden-Württemberg chemical manufacturers prioritize zero-knowledge proof architectures protecting proprietary formulation data during authenticity verification. The EU Falsified Medicines Directive safety feature requirements expand addressable demand for compliant ledger infrastructure. Bavaria's contract manufacturing hubs pilot MediLedger consortium governance for cross-border distribution.
Switzerland
Basel-based drugmakers deploy permissioned networks satisfying Swissmedic inspection protocols for immutable batch records. The country's data residency framework fragments network architectures with neighboring EU states, inflating compliance costs. Geneva and Zurich host specialized validation consultancies bridging GMP expertise with distributed systems architecture.
India
Hyderabad and Ahmedabad pharmaceutical exporters deploy fraud prevention systems protecting brand reputation in regulated markets. CDSCO serialization requirements for export-oriented units converge with FDA and EMA standards. Maharashtra's API manufacturers anchor demand for cost-optimized consortium models sharing verification infrastructure.
Japan
Osaka and Tokyo pharmaceutical companies migrate from paper master batch records to hash-anchored electronic systems. PMDA alignment with FDA data integrity guidelines accelerates replacement cycles at manufacturing sites. Kansai region contract research organizations pilot clinical trial timestamping for EMA inspection readiness.
Pharmaceutical Blockchain Market Vendor Landscape
Enterprise software conglomerates and pharmaceutical-specialized network operators split the market into distinct capability tiers. Consolidation pressures favor vendors with existing ERP relationships and validated installation bases. Technology infrastructure providers and vertical-specific protocol governors represent the dominant archetypes. Strategic partnerships with wholesale distributors and technology licensing to contract manufacturers constitute the primary competitive moves reshaping positioning.
Within the enterprise infrastructure tier, IBM and Microsoft represent technology providers anchoring cross-industry Hyperledger deployments with pharmaceutical compliance modules. SAP SE occupies a position bridging existing ERP dominance into blockchain modules that integrate with batch record systems. Chronicled exemplifies the vertical-specialist archetype, competing on pharmaceutical-specific network standards rather than generic infrastructure. These three anchors illustrate the strategic choice facing drugmakers between extending incumbent technology relationships versus adopting purpose-built pharmaceutical protocols.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| SAP SE |
| Tibco Software |
| Chronicled |
| Auxesis Group |
| VeChain Foundation |
| MediLedger |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Hyperledger Fabric deployment capacity across New Jersey and Massachusetts consulting shops is compressing implementation margins while simultaneously expanding buyer negotiating leverage for multi-year enterprise contracts. This utilization dynamic rewards pharmaceutical manufacturers with delayed DSCSA deadlines, who extract pricing concessions from vendors hungry to fill implementation pipelines ahead of regulatory enforcement.
Pricing Analysis
The customization-premium spread between configured-to-order permissioned networks and standard consortium templates runs wide in pharmaceutical blockchain procurement. Three-tier pricing structure across premium, standard, and economy levels separates validated FDA 21 CFR Part 11 compliant deployments from unaudited pilot configurations. Price differentiation hinges on computer system validation documentation depth and geographic data residency compliance. Pricing pressure stems from wholesale distributors consolidating vendor lists around pre-certified platforms. Contract research organizations exhibit highest price sensitivity, while Big Pharma manufacturers prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Contract manufacturing concentration among Indian API producers and German chemical specialists shapes blockchain verification demand patterns. Supply concentrates in India, Switzerland, and the United States for pharmaceutical-grade distributed ledger infrastructure. Raw material dependencies include cryptographic hardware security modules, consensus algorithm licensing, and validated cloud compute instances. Single-source vulnerability runs through IBM's Hyperledger Fabric dominance in FDA-compliant deployments. Distribution runs through systems integrators with existing SAP relationships at major manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical blockchain sits in early-cycle expansion, with DSCSA interoperability deadlines forcing adoption decisions among previously skeptical procurement committees. Penetration remains below saturation across mid-tier generic manufacturers and contract research organizations.
For Market Incumbents: Build switching-cost moats through deep ERP integration at FDA-inspected manufacturing sites. Incumbents should anchor validated computer system documentation at Pfizer-scale deployments to block challenger entry. Consolidation of MediLedger governance rights offers defensive positioning against zero-knowledge proof startups. SAP and Oracle relationship leverage remains the priority lever for multi-year contract renewal. For New Entrants and Emerging Players: Build out clinical trial timestamping capabilities as the most penetrable white-space segment beyond saturated supply chain applications. New entrants should target Swiss and German research institutions piloting EMA inspection protocols. Zero-knowledge proof architectures for formulation confidentiality offer differentiated go-to-market positioning against incumbent permissioned networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across validation consultancy services as FDA inspection protocols formalize. Long-term viability favors vertical-specialist protocol governors over generic infrastructure providers. Acquisition targets should combine GMP compliance expertise with distributed systems architecture talent. Watch Health Canada serialization alignment announcements as the signal for North American demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Partnership | SAP blockchain modules lock in existing manufacturing customers with validated batch record systems. |
| Zero-Knowledge Proof Development | Privacy-preserving verification protects proprietary formulation data from network participants. |
| Consortium Governance Expansion | MediLedger network standards capture multi-stakeholder cost-sharing across distribution chains. |
| Clinical Trial Timestamping Pilot | EMA inspection protocols drive demand at Swiss and German research institutions. |
| Health Canada Alignment Certification | North American regulatory convergence creates contiguous demand for unified traceability platforms. |
Methodological Framework
A standing panel of pharmaceutical supply chain executives, regulatory affairs directors, wholesale distributor IT leads, and contract manufacturer quality officers provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from FDA DSCSA guidance documents, EMA falsified medicines safety feature specifications, Health Canada serialization advisories, and Swissmedic inspection protocols. Bottom-up deployment sizing at major manufacturers triangulated against top-down regulatory deadline modeling.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning solution maturity, infrastructure architecture, stakeholder complexity, and regional regulatory cluster. CAGRs derived from regulatory deadline enforcement schedules and enterprise procurement cycle timing. Forecast inputs included wholesale distributor scan volume requirements and contract research organization pilot program expansion rates.
Stress conditions across FDA enforcement timing, EU member state implementation variance, and zero-knowledge proof adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory alignment and vendor consolidation trajectories. Cross-checking against FDA warning letter issuance rates for data integrity violations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Automotive Blockchain Market