
 OTA Transmission Platform Market | 2026-2036
OTA Transmission Platform Market Size, Share, and Industry Trends Forecast 2026-2036
OTA Transmission Platform Market Intelligence
ATSC 3.0 certification is reorganizing competitive access for broadcast infrastructure vendors. Harmonic Inc. leverages its encoder and stream processing portfolio to anchor next-generation transmitter deployments. GatesAir Inc. sustains its position through RF transmission hardware specialization for terrestrial broadcast networks. Sinclair Broadcast Group Inc. dominates local station group volume, controlling one of the largest fleets of ATSC 3.0-capable transmitters nationwide.
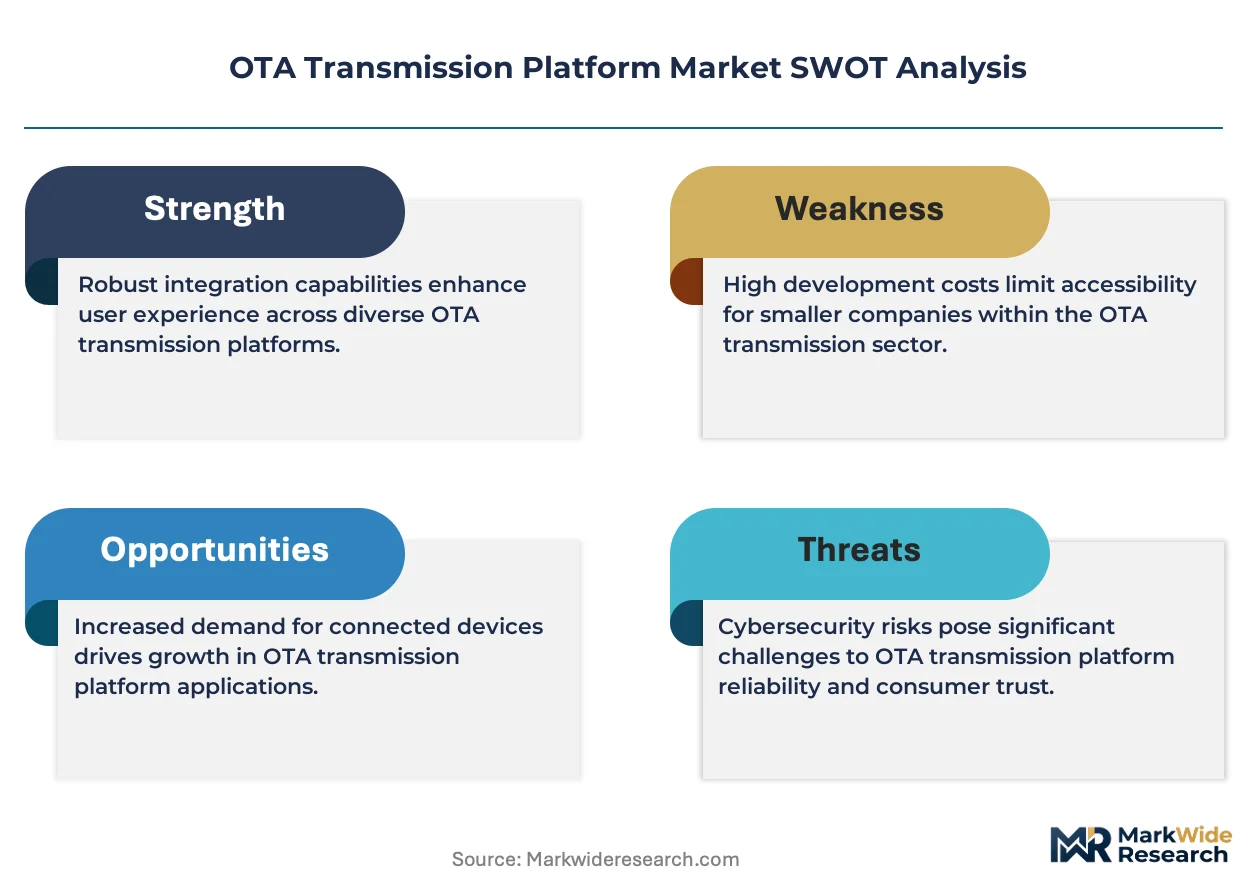
An OTA transmission platform comprises the software, hardware, and network infrastructure that enables wireless delivery of firmware, media content, or application updates to endpoint devices without physical connectivity. Core specifications include IP-based transport streams, AES-128 encryption protocols, and adaptive bitrate algorithms operating across VHF and UHF broadcast bands. Cloud Services within the deployment segment command expanding margin pools as broadcasters shift capex to recurring operational expenditure models. Hardware Modules retain structural importance in markets where on-premise transmitter sites face mandatory spectrum efficiency upgrades.
The FCC governs spectrum allocation and broadcast transmitter licensing in the United States, directly conditioning infrastructure investment timing for station groups. ETSI standards in Europe and the ITU-R framework for digital terrestrial television shape interoperability requirements that equipment vendors must satisfy for market access. Stakeholders should monitor regulatory deadlines for analog switch-off completion and spectrum repacking schedules, as these dictate replacement windows and procurement urgency across broadcast markets.
Market Dynamics
The ATSC 3.0 transition is compressing replacement cycles for terrestrial broadcast infrastructure while automotive OTA mandates force convergence between broadcast and unicast delivery architectures. This dual-track pressure is restructuring procurement priorities across station groups and OEMs simultaneously.
Growth Catalysts
- Automotive OTA Mandates:OEMs now require connected vehicle fleets to support firmware-over-the-air capabilities. This creates parallel demand for robust transmission infrastructure capable of hybrid broadcast-broadcast delivery.
- Spectrum Repacking Schedules:The FCC's broadcast television spectrum reallocation rules are accelerating transmitter infrastructure replacement cycles. Station groups face hard deadlines for equipment migration.
- Cloud-Native Encoding:IP-based transport stream processing is displacing legacy ASIC-based architectures. Broadcasters adopt software-defined workflows to reduce hardware refresh burdens.
Market Restraints
- GaN Component Supply Concentration:RF power amplifier supply chains cluster in East Asian foundries. Transmitter OEMs face input cost volatility and single-source exposure for gallium nitride substrates.
- ATSC 3.0 Patent Pool Complexity:Licensing frameworks for next-generation broadcast standards remain fragmented. Equipment vendors navigate multiple essential patent holders with conflicting royalty terms.
- Terrestrial Broadcast Substitution:Streaming platforms and 5G multicast services are capturing viewer hours. Station groups confront revenue pressure that dampens capex enthusiasm for transmitter upgrades.
Strategic Opportunities
- India Digital Terrestrial Television:The country's analog switch-off timeline creates greenfield infrastructure demand. Equipment vendors can establish early positions before procurement patterns solidify.
- Automotive Firmware Delivery Convergence:Broadcast-broadcast hybrid architectures enable simultaneous mass vehicle updates. This emerging application opens new revenue streams for transmission platform operators.
- EU Green Deal Alignment:Energy efficiency mandates for broadcast infrastructure favor next-generation transmitter designs. Vendors with low-power RF amplification portfolios gain preferential positioning.
Industry Challenges
- ATSC 3.0 Certification Timelines:Laboratory validation cycles for transmitter interoperability extend 18-24 months. Product launches slip as testing queues lengthen at accredited facilities.
- RF Engineering Talent Scarcity:Broadcast transmission expertise concentrates among retiring specialists. Vendors and station groups compete for limited pools of VHF/UHF propagation engineers.
- Hybrid Workflow Integration:Broadcasters operate parallel SDI and IP routing infrastructures during transition periods. Operational complexity spikes as technical staff manage dual operational modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTA Transmission Platform Market |
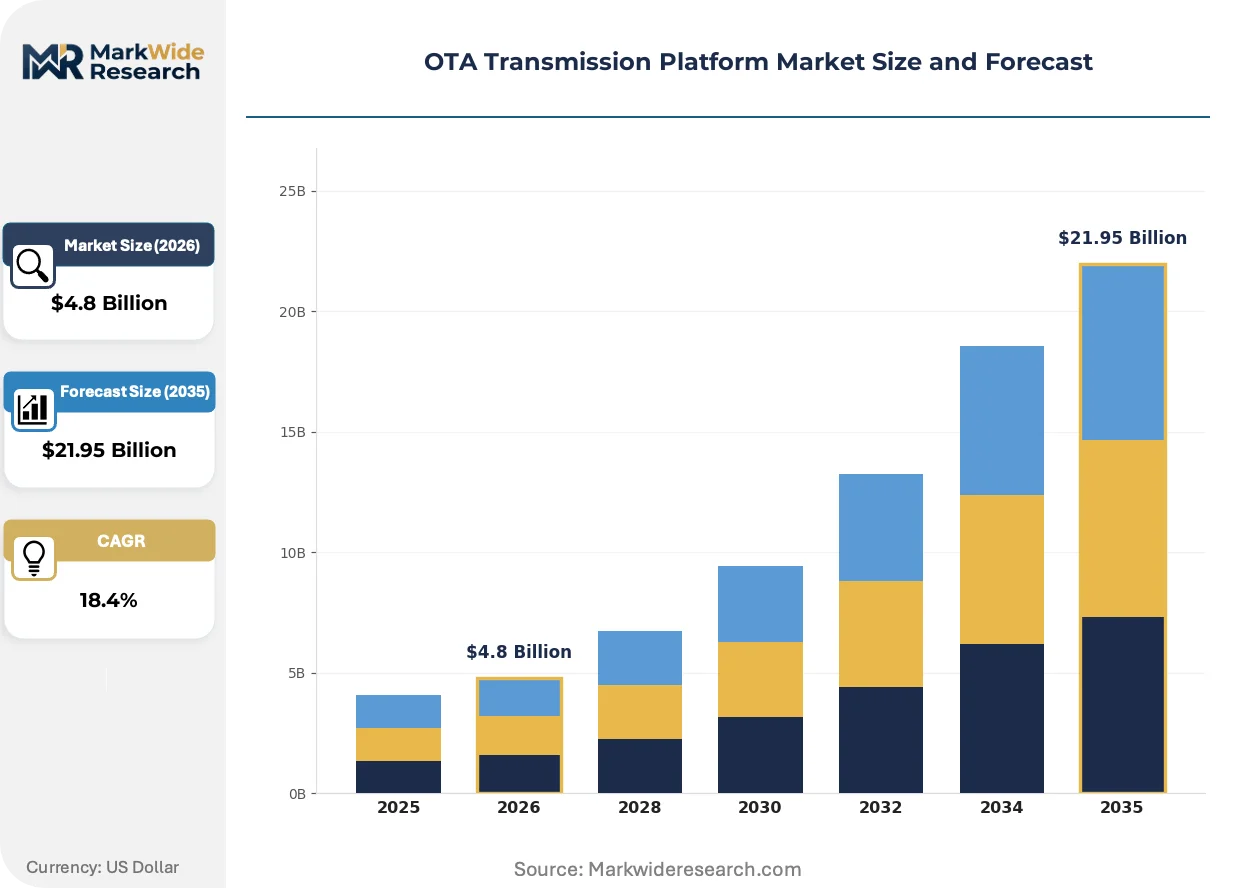
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $21.95 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Modules, Cloud Services, Integration Tools End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Managed Services Service Type: Consultation, Implementation, Maintenance, Support Services |
| Companies Covered | Sinclair Broadcast Group Inc., AirTV L.L.C, Harmonic Inc., SK Telecom Co. Ltd., Channel Master, GatesAir Inc., TiVo Corporation, Nuvyyo Inc., LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTA Transmission Platform Market Strategic Shifts & Innovations
Software-defined architectures are displacing purpose-built hardware across the transmission chain. This shift enables broadcasters to decouple signal processing from RF amplification, creating modular upgrade paths.
Cloud-native encoding platforms are decomposing traditional integrated transmitter designs. Harmonic and peers now deliver transport stream processing as containerized microservices. Station groups adopt these architectures to collapse capital intensity and enable geographic redundancy. The technology is decomposing vendor lock-in by standardizing interfaces between encoding and RF stages.
The FCC's spectrum repacking deadlines are forcing transmitter site reconfigurations. Station groups must relocate facilities, replace antennas, and retune RF chains under compressed timelines. The United States market is responding with accelerated procurement of wideband-capable exciters and liquid-cooled power amplifiers.
Broadcasters now demand usage-based service models rather than perpetual license purchases. Cloud service providers capture recurring revenue by hosting transport stream processing and monitoring functions. This transition is most advanced in the United States, where ATSC 3.0 deployments have normalized operational expenditure treatment for core infrastructure.
OTA Transmission Platform Market Segmentation
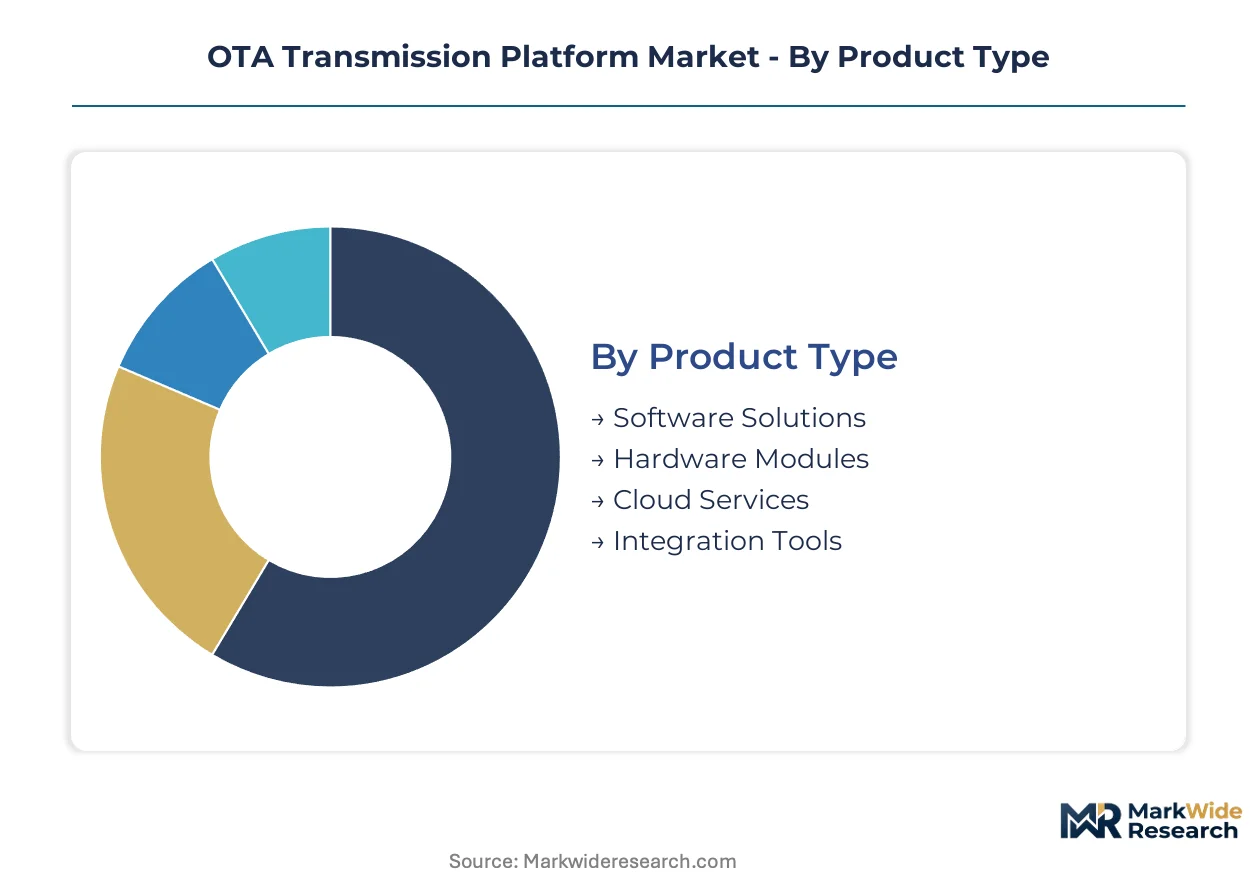
Segmentation in the OTA transmission platform market reveals divergent procurement patterns between broadcast infrastructure and automotive firmware delivery. Equipment buyers prioritize different performance specifications, licensing models, and integration requirements based on their core operational mandates.
Product Type:
Domestic demand concentrates in hardware modules and cloud services for US broadcast infrastructure, while software solutions and integration tools serve export markets adapting ATSC 3.0 architectures to local standards.
- Software Solutions:Encoder and stream processing platforms enable IP-based transport stream management with AES-128 encryption protocols. Broadcasters in the United States deploy these for ATSC 3.0 transitions, while automotive OEMs license firmware delivery orchestration layers for connected vehicle fleets.
- Hardware Modules:RF power amplifiers, exciters, and antenna systems form the physical transmission layer. Station groups across the United States procure these under FCC-mandated spectrum repacking deadlines, driving concentrated domestic volume.
- Cloud Services:Containerized microservices for transport stream processing reduce capital intensity.
- Integration Tools:Middleware bridging SDI and IP routing infrastructures during hybrid transition periods.
Hardware Modules holds the largest share; momentum sits with Cloud Services.
End User:
Cost tier stratification separates enterprise-grade deployments from mid-market implementations, with OEMs and Tier-1 Suppliers commanding premium pricing for automotive-grade certification requirements.
- OEMs:Automotive manufacturers mandate firmware-over-the-air capabilities across connected vehicle fleets, requiring broadcast-unicast hybrid architectures. These buyers negotiate multi-year platform licenses with stringent uptime SLAs and cybersecurity attestations.
- Tier-1 Suppliers:Component integrators embed OTA transmission capabilities into telematics control units and infotainment systems. Their procurement focuses on modular SDKs and certification support for vehicle platform integration.
- Aftermarket Providers:Retrofit solution vendors serving legacy vehicle fleets.
- Fleet Operators:Commercial vehicle managers seeking centralized firmware management.
OEMs dominate absolute spending; Aftermarket Providers are expanding most quickly as retrofit demand accelerates.
Deployment:
Application context determines architecture preference, with broadcasters favoring hybrid models and automotive players splitting between on-premise security and cloud-native scalability.
- On-Premise:Transmitter site installations with dedicated RF chains and local encoding hardware. Station groups in the United States maintain these for primary broadcast transmission under FCC licensing requirements.
- Cloud-Based:Fully hosted transport stream processing with geographic redundancy. Early adopters include national broadcast networks seeking operational expenditure treatment for core infrastructure.
- Hybrid Solutions:Split architectures combining edge encoding with cloud orchestration.
- Managed Services:Outsourced platform operation with performance-based contracting.
Hybrid Solutions holds the largest share; Cloud-Based deployment shows the steepest expansion trajectory.
Service Type:
Customer maturity shapes service mix, with early-phase buyers concentrating spending on implementation and established operators prioritizing maintenance renewals.
- Consultation:Spectrum planning, site engineering, and ATSC 3.0 migration strategy. Broadcast station groups in the United States procure these services for FCC repacking compliance and transmitter relocation projects.
- Implementation:System integration, interoperability testing, and certification support. Vendors deliver 18-24 month project timelines for transmitter validation at accredited laboratories.
- Maintenance:Preventive service contracts and spare parts management.
- Support Services:Technical helpdesk and field engineering dispatch.
Implementation commands the largest share; Support Services gains share fastest as installed base expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's spectrum reallocation mandates have compressed infrastructure replacement timelines across multiple jurisdictions. National regulators are synchronizing digital terrestrial television transitions with automotive connectivity mandates. Equipment procurement now clusters where broadcast modernization intersects with connected vehicle deployment.
United States
ATSC 3.0 transmitter deployments dominate procurement volumes as station groups face hard FCC repacking deadlines. The FCC's broadcast television spectrum reallocation rules force facility relocations and antenna replacements under compressed schedules. Dallas-Fort Worth and Los Angeles anchor the largest concentration of next-generation transmitter installations.
South Korea
Terrestrial broadcasters are integrating automotive firmware delivery into existing transmission infrastructure. The Korea Communications Commission coordinates spectrum policy with the Ministry of Science and ICT for connected vehicle services. Seoul's broadcast technology cluster drives regional equipment demand for hybrid broadcast-unicast architectures.
Germany
Energy efficiency mandates under the EU Green Deal are accelerating transmitter fleet modernization. The Federal Network Agency enforces spectrum coordination rules for digital terrestrial television alongside automotive frequency allocation. Bavaria's RF engineering concentration supports transmitter manufacturing and systems integration activity.
India
Analog switch-off timelines are creating greenfield demand for digital terrestrial television infrastructure. TRAI's broadcast sector regulations and the Ministry of Information and Broadcasting's digitization mandates shape procurement urgency. Maharashtra and Karnataka host emerging transmitter deployment clusters as station groups expand coverage.
Japan
ISDB-T transmitter upgrades are converging with automotive V2X communication requirements. METI coordinates spectrum policy between broadcast services and intelligent transport systems. The Nagoya automotive corridor is driving demand for transmission platforms capable of simultaneous media and firmware delivery.
OTA Transmission Platform Market Key Industry Players
Player mix skews toward broadcast infrastructure specialists with RF transmission heritage and video processing technology providers. The vendor base separates into three tiers: integrated platform vendors, component specialists, and broadcast station groups with captive technology development. Two strategic archetypes dominate competitive positioning: RF hardware specialists leveraging gallium nitride amplifier expertise, and software-defined encoding platforms pursuing recurring revenue models. Capacity expansion and technology licensing represent the primary competitive vectors as vendors race ATSC 3.0 certification timelines.
Among broadcast-focused technology providers, Harmonic Inc., GatesAir Inc., and Sinclair Broadcast Group Inc. exemplify distinct archetypes within the competitive structure. Harmonic Inc. occupies a position representing software-defined encoding and stream processing specialization. GatesAir Inc. anchors the RF transmission hardware tier with terrestrial broadcast network focus. Sinclair Broadcast Group Inc. represents the station-group-as-technology-player model, controlling transmitter fleet scale that influences vendor procurement patterns.
| Leading Market Players |
|---|
| Sinclair Broadcast Group Inc. |
| AirTV L.L.C |
| Harmonic Inc. |
| SK Telecom Co. Ltd. |
| Channel Master |
| GatesAir Inc. |
| TiVo Corporation |
| Nuvyyo Inc. |
| LG Electronics Inc. |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month laboratory validation cycles for ATSC 3.0 transmitter certification concentrate procurement leverage among accredited testing facilities, compressing vendor margins while amplifying pricing power for certification-ready hardware portfolios. This lead-time bottleneck intersects with gallium nitride substrate scarcity to reshape cost structures across broadcast infrastructure tiers.
Pricing Analysis
Certification level for automotive-grade firmware delivery creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ATSC 3.0 patent pool complexity, with cloud-native encoding platforms commanding recurring subscription premiums over perpetual hardware licenses. Cost compression in mid-market transmitter modules is intensifying because station groups face simultaneous FCC repacking deadlines and streaming revenue erosion. Tier-1 automotive suppliers exhibit highest price sensitivity due to vehicle platform integration costs, while national broadcast networks prioritize uptime SLAs over unit economics.
Supply Chain Analysis
Inventory buffers for RF power amplifiers rarely exceed sixty days as gallium nitride foundry capacity concentrates in Taiwan, South Korea, and Japan. Transmitter OEMs draw from specialized substrate suppliers, precision machining clusters, and liquid-cooled thermal management component networks. Single-source vulnerability for GaN-on-SiC wafers creates acute disruption risk during spectrum repacking surges. Distribution runs through direct OEM relationships for station group volume and regional systems integrators for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ATSC 3.0 transition and automotive OTA mandate convergence represent a dual-track technological inflection reshaping procurement priorities across broadcast and mobility sectors simultaneously.
For Market Incumbents: Shield core transmitter hardware margins through backward integration into gallium nitride substrate sourcing, while accelerating software-defined encoding certification to defend against cloud-native entrants. Patent pool licensing fragmentation threatens royalty stacking; incumbent leverage rests on early essential patent positioning and accredited laboratory queue priority. For New Entrants and Emerging Players: Differentiate on energy efficiency metrics aligned with EU Green Deal transmitter mandates, targeting India's analog switch-off greenfield procurement before vendor relationships solidify. White-space concentration sits with hybrid broadcast-unicast architectures for automotive firmware delivery, where certification partnerships with Tier-1 telematics integrators unlock vehicle platform access. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-recurring-revenue play because cloud-native encoding transitions transform capital expenditure into operational expenditure, extending customer lifetime value through subscription retention. Acquisition focus should center on software-defined stream processing specialists with ATSC 3.0 accreditation. The signal to watch is FCC spectrum auction timing, which compresses replacement windows and accelerates procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Substrate Supply Agreement | Secures RF amplifier input cost stability against East Asian foundry concentration risk. |
| ATSC 3.0 Certification Acceleration | Compresses eighteen-to-twenty-four month validation queues at FCC-accredited laboratories. |
| Cloud-Native Encoding Platform Launch | Captures recurring revenue from broadcasters shifting capex to opex treatment models. |
| Automotive Firmware Delivery Partnership | Opens hybrid broadcast-unicast revenue streams through OEM telematics integration. |
| India Market Entry Joint Venture | Establishes early positioning before TRAI-mandated analog switch-off procurement patterns solidify. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with broadcast station group CTOs, RF transmission hardware procurement leads, automotive OEM connected vehicle platform engineers, and Tier-1 supplier integration specialists; and secondary validation through FCC equipment authorization databases, ETSI interoperability specifications, SEC 10-K filings from listed infrastructure vendors, and customs records for GaN substrate trade flows. Bottom-up transmitter deployment tallies across United States DMAs were triangulated against top-down market sizing from cloud services revenue disclosures.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type, deployment architecture, end-user category, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, spectrum repacking deadline phasing, and automotive fleet penetration curves for firmware-over-the-air capability. Key inputs included FCC facility registration data for transmitter site counts and Korea Communications Commission connected vehicle spectrum allocation timelines.
The analysis sits within stated boundaries; outcomes outside FCC repacking schedule adherence or GaN supply chain stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding ATSC 3.0 adoption velocity and automotive OTA mandate enforcement timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
France ICT Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
US Transcription Market
Digital Solutions
Revenue Management Software Market