
 Belgium Data Center Rack Market | 2026-2036
Belgium Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Rack Market Insights
Market Context
Belgium is rewriting data center rack procurement dynamics as hyperscale operators expand campus capacity near Brussels and Antwerp. Schneider Electric SE leverages its integrated power and cooling portfolio to dominate turnkey rack infrastructure deployments across the Benelux corridor. Rittal GMBH & Co.KG sustains engineering leadership through its TS 8 modular platform, which anchors high-density computing configurations for financial services clients in Luxembourg-adjacent facilities. Eaton Corporation differentiates via intelligent power distribution units embedded within rack enclosures, competing on energy monitoring precision rather than pure enclosure specifications.
Technical Definition and Segment Structure
Data center racks are standardized metal frameworks, typically fabricated from cold-rolled steel or aluminum extrusions in heights measured in rack units, designed to mount servers, switches, and power equipment while enabling cable management and thermal airflow control. Enclosed rack configurations command premium positioning in Belgium's banking and telecommunications verticals, where physical security compliance and acoustic containment justify higher expenditure against open frame alternatives. Steel dominates material procurement due to load-bearing requirements for GPU-intensive AI clusters, though aluminum gains traction in edge deployments where weight reduction simplifies transport and installation logistics. Wall mount segments occupy niche but stable demand from healthcare and education end users retrofitting legacy buildings with constrained floor space.
Regulatory Environment and Outlook
Belgium's federal energy efficiency regulations, layered atop EU Green Deal obligations and REACH material compliance standards administered by ECHA, mandate recyclable rack components and documented thermal performance metrics. CE marking requirements enforce mechanical stability and electrical safety benchmarks, while Flanders Region building codes impose specific fire resistance ratings for data center rack assemblies. Stakeholders must monitor evolving federal carbon reporting thresholds that will likely expand scope from facility-level to equipment-level disclosure, forcing rack vendors to embed lifecycle emissions data directly into product specifications.
Market Dynamics
Belgium's data center rack market is compressing procurement timelines as hyperscale operators race to deploy AI-ready infrastructure before federal carbon reporting mandates take full effect in 2026.
Growth Catalysts
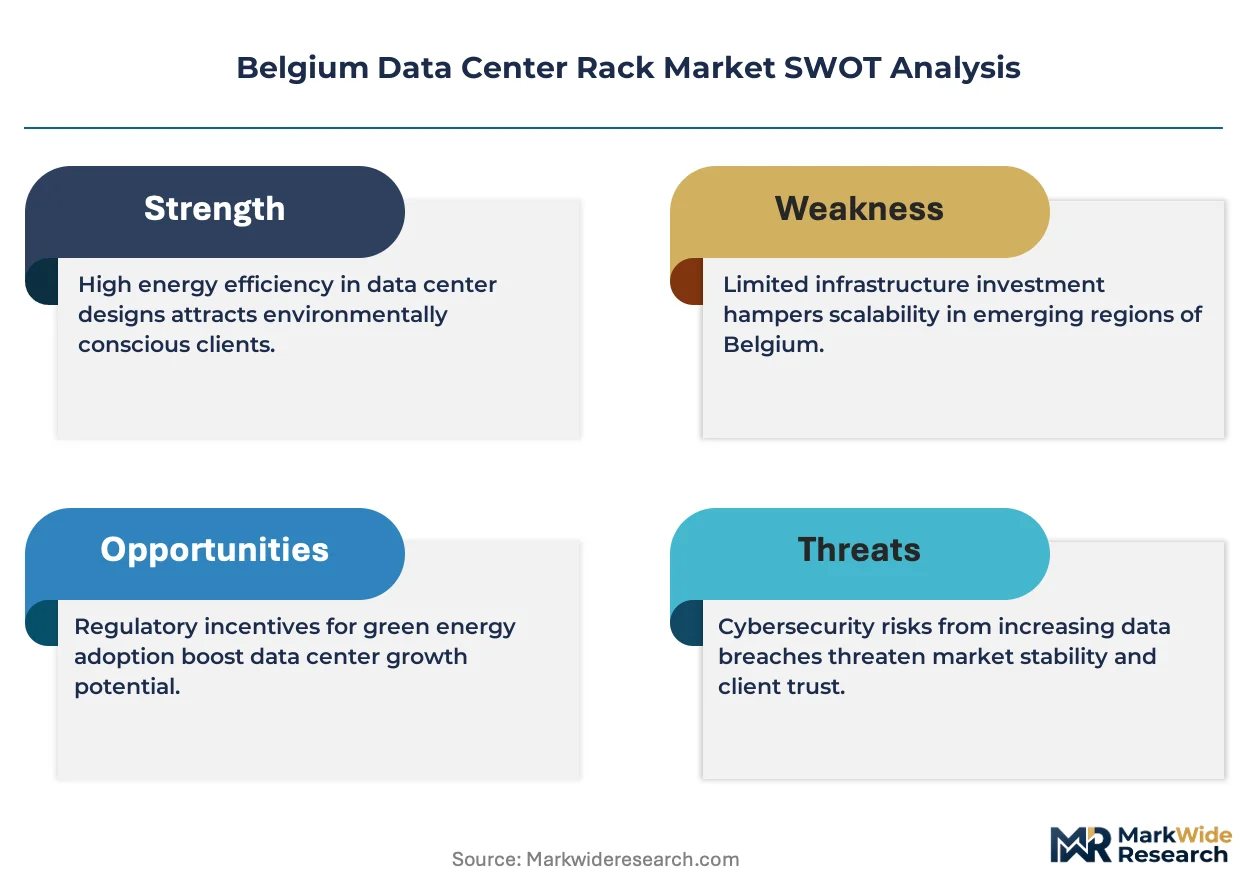
- EU Energy Efficiency Directive:Mandatory PUE disclosures are forcing facility operators to replace legacy racks with thermally optimized enclosures, accelerating refresh cycles across Brussels-Capital and Flanders regions.
- AI cluster densification:GPU-intensive workloads are driving demand for 52U+ high-capacity racks capable of supporting liquid cooling manifolds and 50kW+ per-rack power densities.
- Antwerp hyperscale corridor:Cloud service providers are expanding campus capacity along the E19 fiber route, concentrating rack procurement volumes in this logistics-adjacent cluster.
Market Restraints
- Steel price volatility:Cold-rolled steel input costs fluctuate with European energy markets, compressing enclosure margins for fabricators serving price-sensitive colocation tenants.
- German supply concentration:Precision cooling integration components for high-density racks originate predominantly from Baden-Württemberg suppliers, creating single-source vulnerability.
- REACH compliance friction:ECHA substance restrictions on certain rack coatings and fire-retardant materials extend product qualification timelines by 8-14 months.
Strategic Opportunities
- Wallonia edge retrofit:Underpenetrated secondary cities like Liège and Namur present white space for wall-mount rack deployments serving latency-sensitive manufacturing IoT applications.
- Flanders building code alignment:Regional fire resistance mandates for data center assemblies create premium positioning for pre-certified rack-integrated containment systems.
- Modular-factory convergence:Prefabricated rack-and-power skids are collapsing deployment timelines for hyperscale tenants seeking rapid capacity expansion.
Industry Challenges
- Liquid cooling integration expertise:Shortage of technicians qualified to install manifold-connected racks is delaying commissioning schedules for AI training facilities.
- CE marking complexity:Evolving mechanical stability test protocols under harmonized EN standards create certification bottlenecks for new enclosure designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Rack Market |
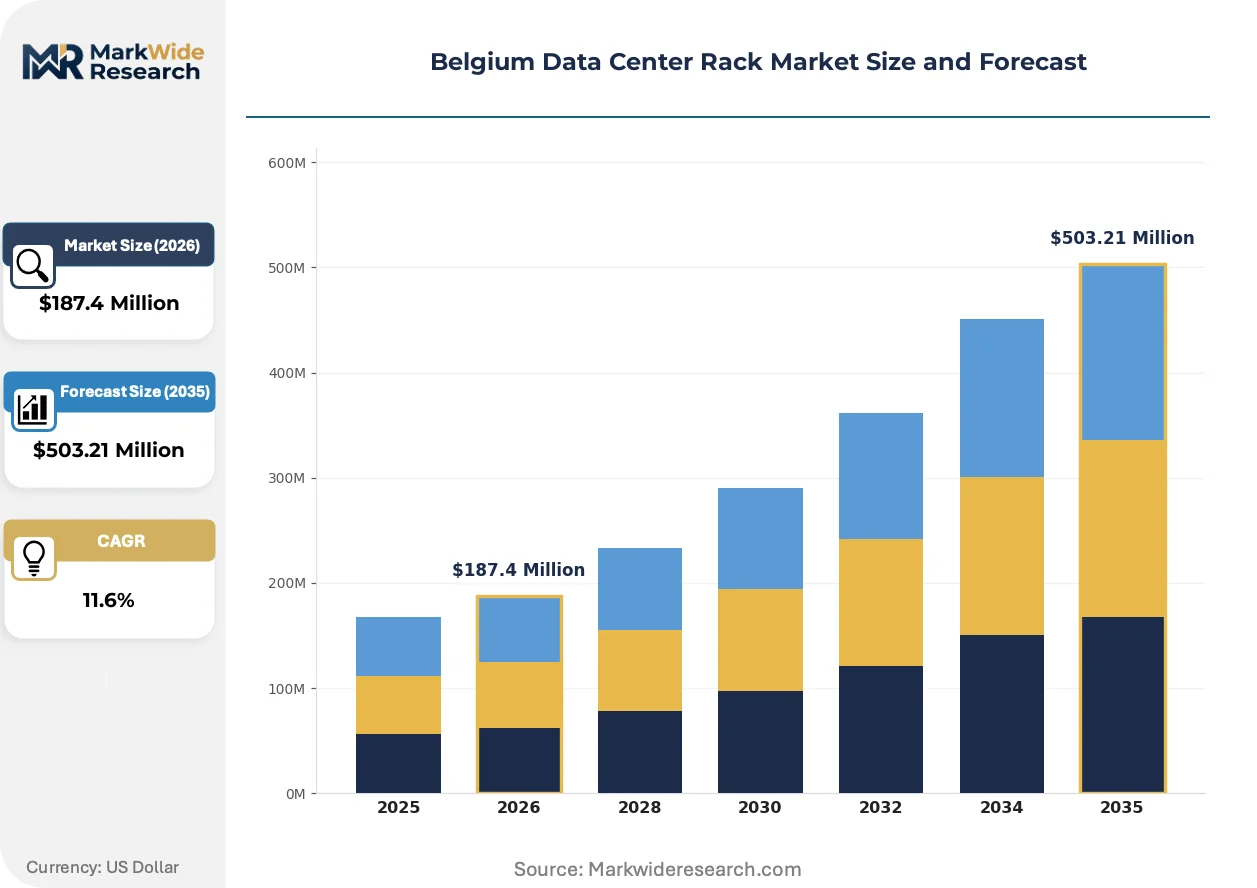
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rack Type: Open Frame, Enclosed Rack, Wall Mount, Portable Rack End User: Telecommunications, Banking, Education, Healthcare Material: Steel, Aluminum, Plastic, Composite Size: 1U, 2U, 4U, 6U |
| Companies Covered | Schneider Electric SE, Rittal GMBH & Co.KG, Eaton Corporation, Vertic Group Corp., CE+T Group, Automation & Industrial Controls (AIC), Minkels, Delta Racks, nVent Electric PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Rack Market Trends and Innovations
Rack architecture is converging with power and cooling infrastructure as a single optimized system, displacing the traditional model of procuring enclosures, PDUs, and thermal management as separate specifications.
Aluminum extrusion framing is collapsing the weight penalty that previously constrained edge deployment logistics. Telecommunications operators retrofitting central offices and mobile switching centers are specifying sub-80kg rack assemblies to avoid structural reinforcement of legacy buildings. This material shift is compressing total installed cost for distributed infrastructure by eliminating crane rental and floor-loading assessments.
Belgium's federal data center sustainability mandates are accelerating embedded lifecycle emissions tracking. The national climate authority requires documented carbon footprint data for rack components exceeding 50kg mass, pushing fabricators to adopt Environmental Product Declarations. Banking and telecommunications verticals in Brussels-Capital are now prioritizing suppliers with ISO 14040-compliant lifecycle assessments.
Specification authority is migrating from facilities engineering to procurement functions with total-cost-of-ownership mandates. Colocation tenants are unbundling rack procurement from construction contracts, directly negotiating enclosure specifications with manufacturers to optimize residual value at lease exit. This pattern is most visible among financial services clients in Luxembourg-adjacent facilities seeking asset portability across European deployments.
Belgium Data Center Rack Market Segmentation
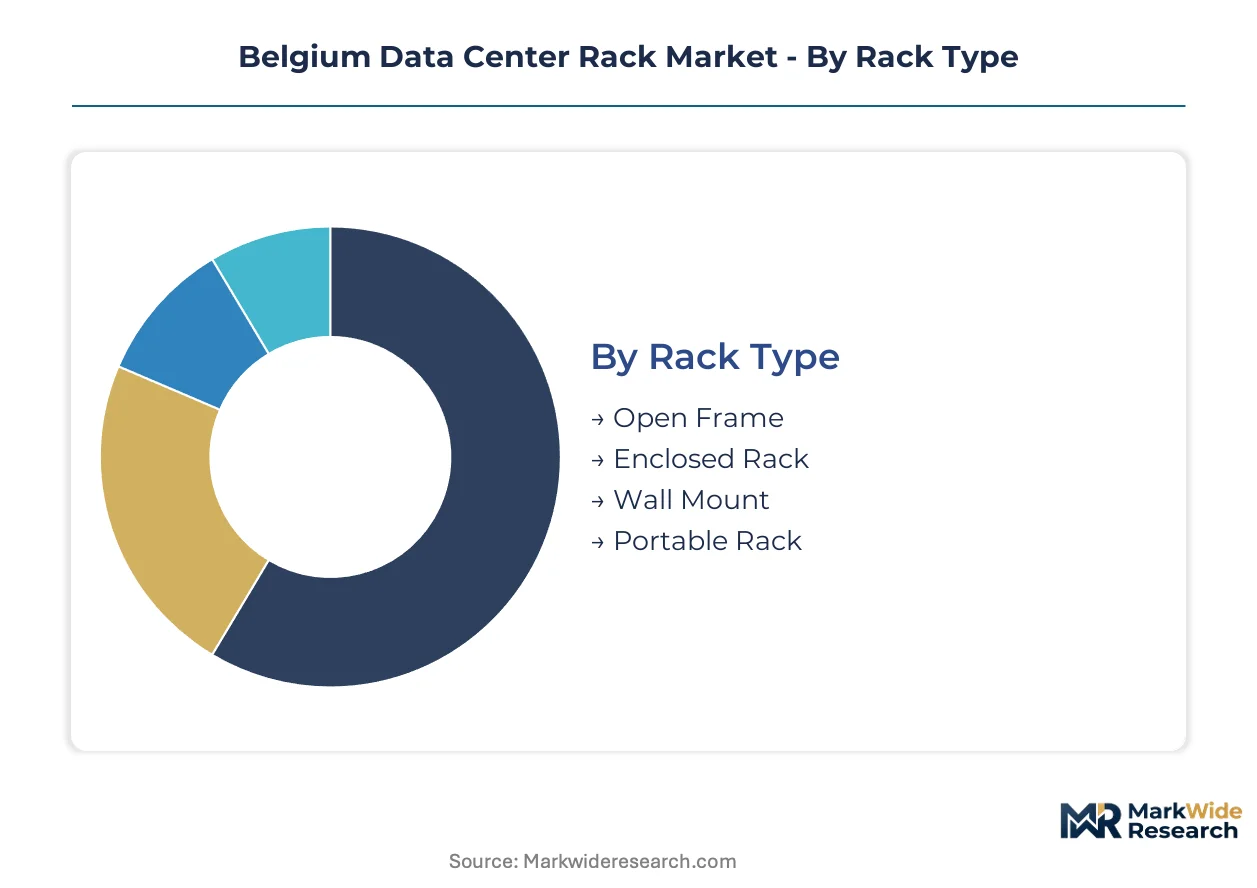
Belgium's data center rack market fragments across four structural dimensions that determine procurement patterns, thermal engineering requirements, and compliance obligations. Rack type and material specifications dominate capital allocation decisions, while end-user verticals and size configurations shape regional deployment density across Flanders and Wallonia.
Rack Type:
Cost tier stratification separates open infrastructure from security-hardened enclosures, with premium positioning commanding measurable price multiples for compliance-driven buyers.
- Open Frame:Unenclosed four-post structures maximize airflow for high-density GPU clusters. Hyperscale operators in Antwerp's E19 corridor specify these for AI training facilities where thermal efficiency outweighs physical security requirements.
- Enclosed Rack:Lockable steel housings with integrated cable management and acoustic dampening. Banking and telecommunications clients in Brussels-Capital mandate these for PCI-DSS and NIS2 compliance, accepting weight penalties for audit traceability.
- Wall Mount:Compact hinged enclosures for constrained floor plates. Healthcare retrofits in Liège and Namur deploy these where structural load limits prohibit free-standing infrastructure.
- Portable Rack:Castor-mounted mobile frames for temporary edge deployments. Manufacturing IoT pilots in Wallonia's automotive belt use these for rapid relocation between production lines.
Enclosed Rack holds installed capacity. Wall Mount is rotating up the share rankings.
End User:
Application workload characteristics determine rack specification authority, with latency sensitivity and data sovereignty requirements fragmenting procurement across four verticals.
- Telecommunications:Central office retrofits drive demand for sub-80kg aluminum assemblies. Proximus and Telenet specify these for 5G edge nodes in Flanders to avoid crane deployment and structural reinforcement costs.
- Banking:Financial services clients prioritize ISO 14040-compliant lifecycle assessments. ING and BNP Paribas Fortis mandate documented carbon footprint data for components exceeding 50kg mass under federal climate authority rules.
- Education:University research clusters in Leuven and Ghent require liquid-cooling-ready 52U+ enclosures for AI compute density.
- Healthcare:Hospital IT departments in Brussels-Capital specify antimicrobial-coated rack surfaces for clinical data environments.
Telecommunications dominates procurement volumes. Healthcare is climbing the fastest as federal digital health infrastructure mandates expand.
Material:
Volume throughput and transport economics divide procurement between structural steel and lightweight alternatives, with sustainability disclosure requirements reshaping supplier qualification.
- Steel:Cold-rolled carbon steel delivers 1,500kg+ static load ratings for GPU-intensive AI clusters. Hyperscale campuses near Brussels specify these for 50kW+ per-rack power densities despite European energy market price volatility.
- Aluminum:Extruded aluminum framing reduces assembly weight by 40-60%. Telecommunications edge deployments across Flanders favor these to eliminate floor-loading assessments and crane rental in legacy buildings.
- Plastic:Glass-reinforced polymer housings for electromagnetic isolation in healthcare imaging suites.
- Composite:Carbon-fiber hybrid structures for satellite ground stations requiring thermal expansion coefficient matching.
Steel retains volume leadership. Aluminum is gaining share fastest as edge deployment accelerates outside Brussels-Capital.
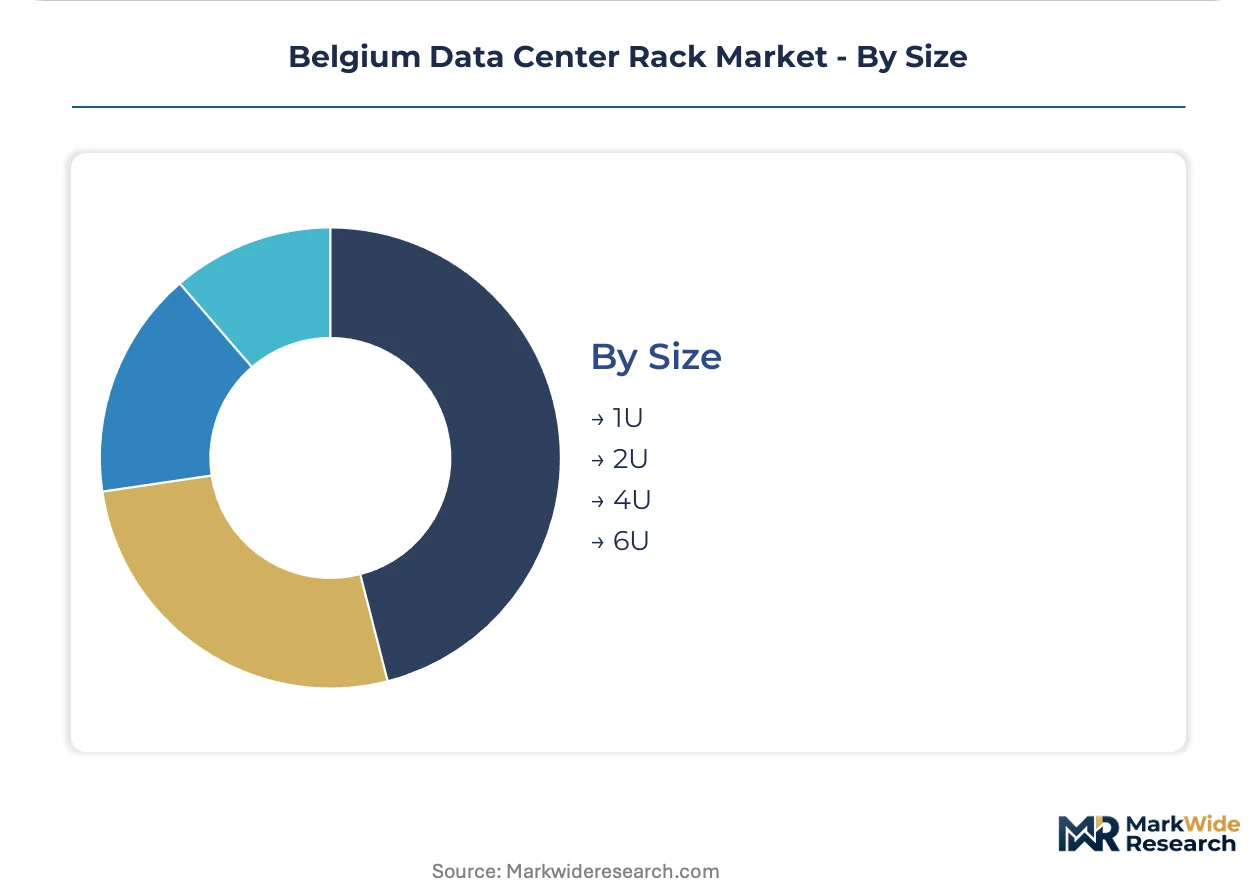
Size:
Customer type and facility generation determine height unit procurement, with legacy constraints and next-generation density requirements creating specification divergence.
- 1U:Single-unit height for network appliance mounting. Colocation tenants in Antwerp hyperscale facilities specify these for top-of-rack switch consolidation.
- 2U:Standard server form factor dominating general-purpose compute. Flanders enterprise data centers deploy these for virtualization clusters with moderate thermal output.
- 4U:Storage-optimized height for high-capacity disk arrays. Banking disaster recovery sites specify these for tape library integration.
- 6U:Blade chassis and GPU server enclosures. AI training facilities require these for NVIDIA H100 and AMD MI300X deployments.
2U maintains installed base dominance. 6U is expanding most quickly as GPU cluster densification accelerates rack refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Energy Efficiency Directive anchors procurement dynamics across Belgium's three federal regions, with Flanders, Wallonia, and Brussels-Capital each enforcing distinct building codes and sustainability mandates that reshape rack deployment patterns.
Flanders
Hyperscale operators cluster along the E19 fiber corridor connecting Brussels to Antwerp, driven by cloud service provider campus expansions and 5G edge node densification. The Flanders Region building code imposes specific fire resistance ratings for data center rack assemblies, accelerating demand for pre-certified containment systems. Proximus and Telenet specify sub-80kg aluminum rack assemblies for central office retrofits in Ghent and Leuven to avoid structural reinforcement costs.
Wallonia
Manufacturing IoT applications in Liège and Namur generate latency-sensitive demand for wall-mount rack deployments in legacy industrial buildings with constrained floor plates. The Walloon government's digital infrastructure subsidies for healthcare and education sectors are expanding procurement volumes for compact hinged enclosures. Automotive belt facilities near Charleroi deploy portable castor-mounted racks for rapid relocation between production lines.
Brussels-Capital Region
Financial services clients including ING and BNP Paribas Fortis concentrate AI-ready infrastructure investments in the hyperscale corridor, mandating ISO 14040-compliant lifecycle assessments for components exceeding 50kg mass. Belgium's federal climate authority enforces documented carbon footprint disclosure requirements that prioritize suppliers with embedded emissions tracking. Banking disaster recovery sites specify 4U storage-optimized enclosures for tape library integration.
Luxembourg-Adjacent Corridor
Cross-border data center campuses serving Luxembourg's fund administration sector drive specification authority migration toward procurement functions with total-cost-of-ownership mandates. Colocation tenants unbundle rack procurement from construction contracts to optimize residual value at lease exit. CE marking requirements under harmonized EN standards enforce mechanical stability and electrical safety benchmarks for asset-portable deployments.
Antwerp Port Logistics Zone
Maritime-adjacent fiber infrastructure and cooling water access attract liquid-cooling-ready 52U+ rack deployments for GPU-intensive AI training facilities. German supply concentration for precision cooling integration components from Baden-Württemberg suppliers creates single-source vulnerability for high-density configurations. Shortage of qualified technicians for manifold-connected rack installation is delaying commissioning schedules.
Belgium Data Center Rack Market Competitive Landscape
Capability concentration sits with integrated power-cooling specialists; scale advantage sits with modular enclosure fabricators serving hyperscale volume contracts. The vendor base organizes around three strategic archetypes: turnkey infrastructure integrators, precision engineering specialists, and intelligent power distribution innovators. Competitive dynamics center on M&A activity consolidating cooling integration expertise and strategic partnerships collapsing deployment timelines through prefabricated skid solutions.
Among Benelux-anchored engineering groups, Schneider Electric SE and Rittal GMBH & Co.KG exemplify divergent positioning within the integrated infrastructure tier. Schneider represents turnkey system convergence, while Rittal occupies the precision-modular fabrication position. Eaton Corporation anchors the intelligent power distribution archetype, competing on embedded monitoring capabilities rather than pure enclosure specifications. CE+T Group and Vertic Group Corp. sit within the specialist tier serving compliance-driven verticals with pre-certified containment configurations.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GMBH & Co.KG |
| Eaton Corporation |
| Vertic Group Corp. |
| CE+T Group |
| Automation & Industrial Controls (AIC) |
| Minkels |
| Delta Racks |
| nVent Electric PLC |
| Others |
Pricing and Supply Chain Analysis
German supply concentration for precision cooling integration components from Baden-Württemberg suppliers compresses both pricing tier spreads and supply chain resilience across Belgium's data center rack market. This single-source dependency for high-density rack manifolds forces Belgian hyperscale operators to absorb premium pricing for liquid-cooling-ready configurations while simultaneously exposing procurement timelines to cross-border logistics bottlenecks.
Pricing Analysis
Antwerp commands measurable premiums over Wallonia for enclosed rack assemblies, reflecting logistics-adjacent demand concentration along the E19 fiber corridor. Three-tier pricing structure across premium certified, standard compliant, and economy open-frame levels separates banking clients with ISO 14040 mandates from price-sensitive colocation tenants. Cost compression in steel-intensive configurations is intensifying because European energy market volatility feeds directly into cold-rolled carbon steel input costs. Colocation tenants unbundling rack procurement from construction contracts demonstrate highest price sensitivity, while financial services clients in Brussels-Capital prioritize lifecycle assessment documentation over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and Belgium dominates supply chain risk calculus for precision cooling integration components essential to AI-ready rack deployments. Manufacturing concentration centers on Germany for manifold systems, China for aluminum extrusions, and domestic Belgian fabricators for final enclosure assembly. Raw material dependencies rest on cold-rolled steel from European mills, extruded aluminum from Asian suppliers, and fire-retardant coatings subject to REACH compliance friction. Single-source vulnerability for Baden-Württemberg cooling components creates commissioning delays when qualified technician availability constrains installation capacity. Distribution runs through direct manufacturer relationships with hyperscale operators, bypassing traditional distribution channels for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium's data center rack market is experiencing high-growth disruption as federal carbon reporting mandates and AI cluster densification compress procurement timelines and reshape supplier qualification requirements.
For Market Incumbents: Insulate market position by deepening backward integration into precision cooling component manufacturing to offset German supply concentration risk. Prioritize ISO 14040 certification investment to capture financial services procurement mandates in Brussels-Capital. Defend against emerging modular-factory specialists by embedding lifecycle emissions tracking directly into product specifications before federal disclosure requirements expand to equipment-level reporting. For New Entrants and Emerging Players: Wallonia edge retrofit opportunities in Liège and Namur represent the most penetrable entry point for wall-mount rack specialists serving latency-sensitive manufacturing IoT applications. Healthcare digital infrastructure mandates in Brussels-Capital hospitals create demand for antimicrobial-coated rack surfaces where incumbent coverage remains thin. Go-to-market execution should target direct procurement relationships with colocation tenants seeking asset portability across European deployments rather than construction-contract bundling. For Investors and Strategic Acquirers: Liquid cooling integration specialists with qualified technician networks and manifold installation expertise present the most attractive acquisition target archetype given commissioning bottlenecks delaying AI facility deployments. Long-term viability across the projection horizon hinges on regulatory alignment with evolving EU Energy Efficiency Directive enforcement and federal carbon disclosure expansion. Monitor Flanders Region building code amendments for fire resistance rating changes that would force rack refresh cycles and concentrate demand for pre-certified containment systems.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Rack-and-Power Skid Deployment | Collapses commissioning timelines for hyperscale tenants racing against federal carbon reporting deadlines. |
| Liquid Cooling Manifold Integration | Captures AI training facility demand as GPU densities exceed 50kW per rack across Antwerp hyperscale corridor. |
| Environmental Product Declaration Adoption | Qualifies suppliers for ING and BNP Paribas Fortis procurement mandates under federal climate authority rules. |
| Aluminum Extrusion Weight Reduction | Eliminates crane deployment costs for Proximus and Telenet central office retrofits in Flanders legacy buildings. |
| REACH-Compliant Coating Qualification | Accelerates product approval timelines currently extended by ECHA substance restriction friction. |
Research Methodology
A standing panel of data center facilities engineers, colocation procurement directors, rack manufacturer product managers, and ECHA regulatory compliance specialists provided ongoing calibration throughout the study period. Primary interviews with hyperscale operators in Antwerp and Brussels-Capital, combined with secondary validation against EU Energy Efficiency Directive implementation documents and Flanders Region building code amendments, anchored demand-side intelligence. Customs records for steel and aluminum inputs, SEC filings from publicly traded infrastructure vendors, and hyperscaler capex disclosure databases supplied supply-side triangulation. Bottom-up rack deployment counts across Flanders, Wallonia, and Brussels-Capital regions were cross-referenced against top-down facility capacity announcements.
Scenario-bracketing around regulatory enforcement timelines and AI investment cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include rack type, material specification, end-user vertical, and size configuration, with additional granularity for liquid-cooling-readiness and certification compliance tiers. CAGRs were derived from installed base growth rates adjusted for refresh cycle acceleration under federal sustainability mandates. Forecast inputs incorporated steel price volatility indices, ECHA substance restriction update schedules, and hyperscale campus development pipelines.
Practitioners should monitor federal carbon reporting threshold expansions and Flanders building code amendment proposals for early signals of demand inflection. Forecasts reflect assumptions regarding EU Energy Efficiency Directive enforcement consistency, REACH compliance timeline stability, and hyperscale investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Italy Data Center Rack Market