
 Mini Data Center Market | 2026-2036
Mini Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Data Center Market Analysis
Subscription-based thermal management services is rebalancing vendor economics toward recurring revenue rather than one-time hardware sales. Schneider Electric leverages its integrated power and cooling portfolio to anchor large enterprise deployments across Europe. Vertiv sustains competitive intensity through specialized precision cooling architectures purpose-built for edge environments. Huawei Technologies dominates price-sensitive segments in Asia through captive manufacturing of power distribution and enclosure systems.
A mini data center denotes a self-contained, prefabricated IT infrastructure enclosure typically housing 10 to 100 kW of compute capacity with integrated power, cooling, and security subsystems in a footprint under 500 square feet, designed to deliver low-latency data processing at the network edge or within enterprise premises. Micro data centers lead current shipment volumes due to their plug-and-play deployment profile for retail and branch office applications. Edge data centers represent the fastest-expanding product category as 5G network densification and autonomous systems require sub-10 millisecond response times. Monitoring systems technology commands disproportionate margin attention because predictive analytics on thermal and power performance reduce unplanned downtime costs for remote, unmanned installations.
The US EPA ENERGY STAR program and the EU Code of Conduct for Data Centres establish efficiency benchmarks that filter non-compliant equipment from public-sector and large enterprise procurement lists. China's GB 50174 standard for electronic information system rooms imposes fire suppression and redundancy requirements that shape domestic product specifications. Stakeholders must weigh certification breadth against regional customization costs when configuring platform architectures for multi-country deployment.
Market Dynamics
Telecommunications carriers are accelerating procurement of self-contained, prefabricated units as edge computing deployments compress latency requirements below 10 milliseconds for autonomous systems and industrial automation.
Growth Catalysts
- EU Energy Efficiency Directive:Tightening operational standards for distributed IT infrastructure are filtering non-compliant equipment from public-sector and large enterprise procurement lists across member states.
- 5G network densification:Telecommunications infrastructure buildouts are creating immediate demand for edge data centers capable of sub-10 millisecond response times in urban corridors.
- Germany's industrial automation clusters:Factory floor proximity requirements for low-latency processing are concentrating demand in manufacturing-heavy regions like Bavaria and Baden-Württemberg.
Market Restraints
- Precision cooling component concentration:Specialized thermal management subsystems rely on concentrated supply bases in East Asian manufacturing zones, exposing procurement to geopolitical friction.
- Copper and aluminum price volatility:Power distribution and enclosure raw material costs swing with commodity markets, compressing margin predictability for fixed-price contracts.
- China's GB 50174 standard:Fire suppression and redundancy requirements for electronic information system rooms create technical barriers for foreign equipment seeking domestic certification.
Strategic Opportunities
- Subscription-based thermal management:Recurring revenue service models are rebalancing vendor economics away from one-time hardware sales toward long-term customer relationships.
- India's PLI scheme for electronics manufacturing:Production-linked incentives for domestic data center component fabrication are attracting assembly investment away from traditional import dependencies.
- Predictive analytics convergence:Machine learning integration with monitoring systems technology is creating disproportionate margin capture through unplanned downtime prevention.
Industry Challenges
- Multi-country certification breadth:Stakeholders face configuration complexity when reconciling US EPA ENERGY STAR benchmarks against EU Code of Conduct requirements and China's GB standards for platform architectures.
- Legacy facility integration:Brownfield deployments require custom engineering to interface prefabricated enclosures with existing building management systems and power feeds.
- Remote unmanned operations talent:Predictive maintenance algorithm development and thermal performance analytics require scarce data science and mechanical engineering skill sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Data Center Market |
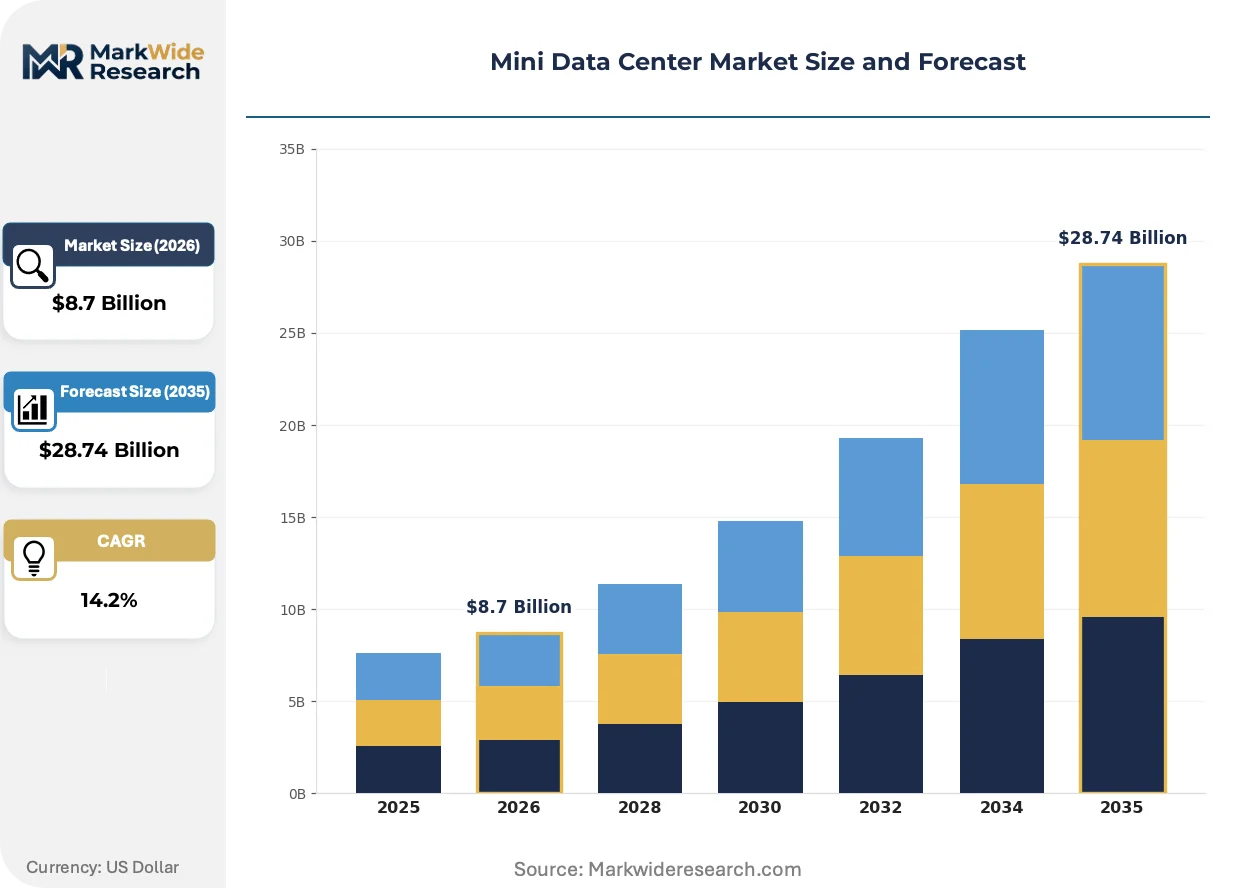
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Micro Data Centers, Edge Data Centers, Hybrid Data Centers Technology: Cooling Systems, Power Management, Security Solutions, Monitoring Systems End User: SMBs, Enterprises, Government, Educational Institutions Deployment: On-Premises, Colocation, Cloud, Hosted |
| Companies Covered | Schneider Electric, Vertiv, Eaton, Huawei Technologies, Dell Technologies, Hewlett Packard Enterprise, Cisco Systems, IBM, Rittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Data Center Market Emerging Trajectories
Edge computing architectures are fragmenting traditional centralized data center economics, forcing infrastructure vendors to engineer for distributed deployment models and service-based revenue recognition.
Liquid immersion cooling is decentralizing thermal management from facility-scale systems to rack-level enclosures. Automotive manufacturers with electric vehicle battery testing facilities are adopting single-phase immersion at 40% faster deployment cycles than air-cooled alternatives. This compression is decentralizing vendor relationships from mechanical contractors to direct equipment procurement by end-users.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in precision cooling equipment. Industrial cooling system manufacturers must reformulate heat transfer fluids and redesign compressor architectures to maintain CE marking eligibility. Edge data center product lines face the steepest compliance timelines due to smaller batch production runs and limited engineering bandwidth.
Buyers are unbundling after-sales service contracts from initial hardware procurement. Retail and branch office segments now source thermal management and remote monitoring through third-party service integrators rather than original equipment channels. This disintermediation is most visible in Germany's Mittelstand manufacturing sector, where procurement departments prioritize multi-vendor service level agreements over single-source accountability.
Mini Data Center Market Segmentation
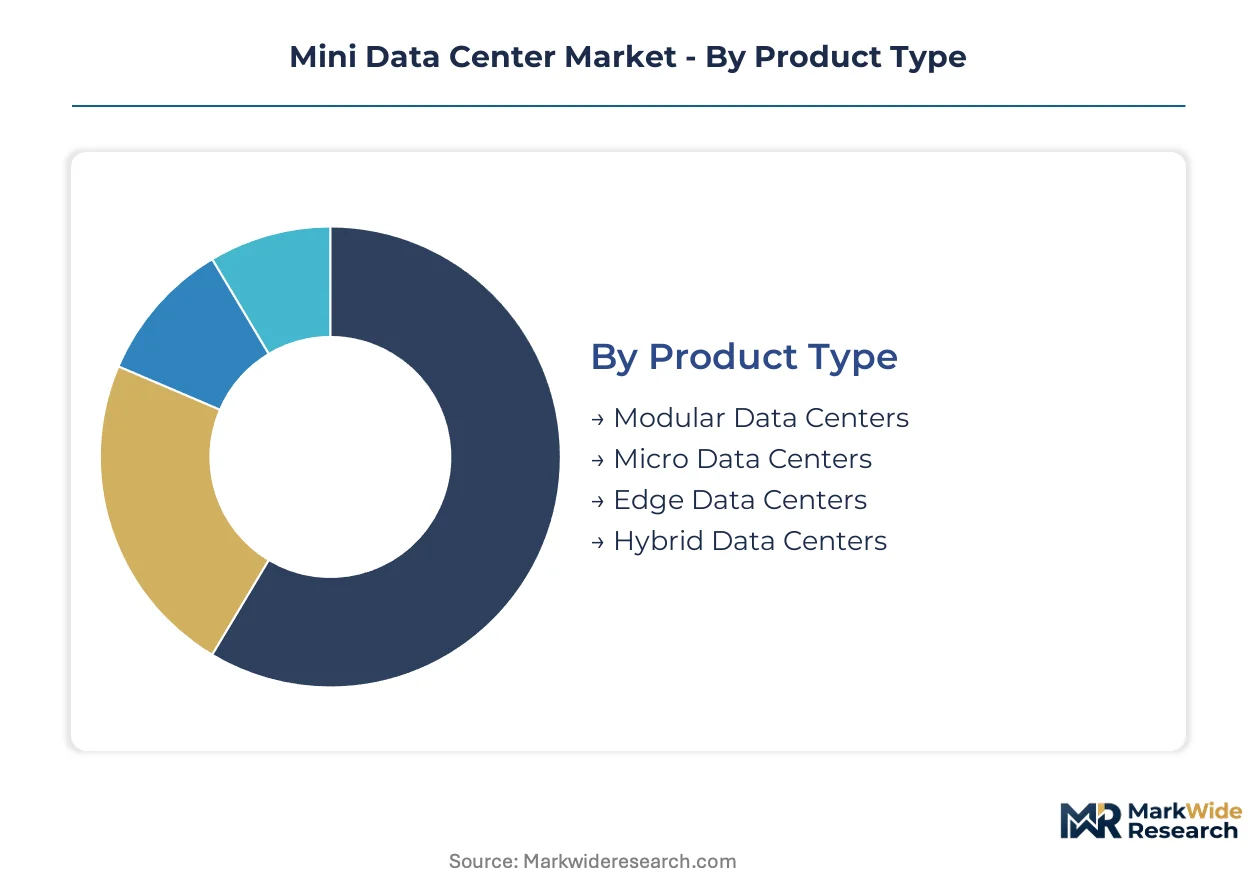
Mini data center configurations diverge sharply across deployment scale, thermal architecture, and operational control requirements. Procurement patterns cluster around latency sensitivity, energy compliance mandates, and capital versus operational expenditure preferences.
Product Type:
Standardization decreases and customization intensity rises as unit scale expands from plug-and-play micro formats to hybrid architectures integrating legacy infrastructure.
- Micro Data Centers:Self-contained enclosures under 100 kW with factory-integrated power, cooling, and security subsystems enable same-day activation. Retail banking networks in Germany deploy these for branch-level transaction processing under EU Code of Conduct efficiency benchmarks.
- Edge Data Centers:Distributed compute nodes positioned within 10 milliseconds of end-users demand precision thermal management for unmanned operation. Telecommunications carriers across urban corridors in France, Italy, and Spain are densifying these units to support autonomous vehicle telemetry and industrial IoT control loops.
- Modular Data Centers:Scalable prefabricated halls assembled from standardized IT, power, and cooling blocks suit enterprise campus expansion.
- Hybrid Data Centers:Architectures blending on-premises enclosures with cloud burst capacity address workload volatility in financial services.
Leading the category by volume: Micro Data Centers. Growing fastest: Edge Data Centers.
Technology:
Margin capture concentrates where predictive capabilities reduce unplanned downtime in remotely operated installations.
- Monitoring Systems:Sensor networks feeding machine learning models for thermal and power anomaly detection command premium pricing. These systems are displacing reactive maintenance contracts in Germany's Mittelstand manufacturing sector through uptime guarantees.
- Cooling Systems:Precision air handlers and liquid immersion architectures face steep reformulation timelines under EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants.
- Power Management:Uninterruptible power supplies and intelligent distribution units stabilize edge deployments against grid fluctuation.
- Security Solutions:Biometric access controls and environmental threat detection protect unmanned enclosures from physical intrusion.
Highest margin capture: Monitoring Systems. Steepest compliance pressure: Cooling Systems.
End User:
Procurement sophistication scales with IT staff depth and regulatory exposure to data sovereignty requirements.
- Enterprises:Manufacturing conglomerates in Bavaria and Baden-Württemberg mandate sub-10 millisecond latency for factory floor automation, driving specification of edge data centers with integrated precision cooling.
- Government:Public-sector procurement lists filter for EPA ENERGY STAR and EU Code of Conduct compliance, excluding non-certified equipment from tender eligibility.
- SMBs:Mid-sized enterprises favor subscription-based thermal management to convert capital expenditure into operational budgets.
- Educational Institutions:Research universities deploy micro data centers for high-performance computing clusters with intermittent utilization patterns.
Dominant demand source: Enterprises. Fastest policy-driven procurement: Government.
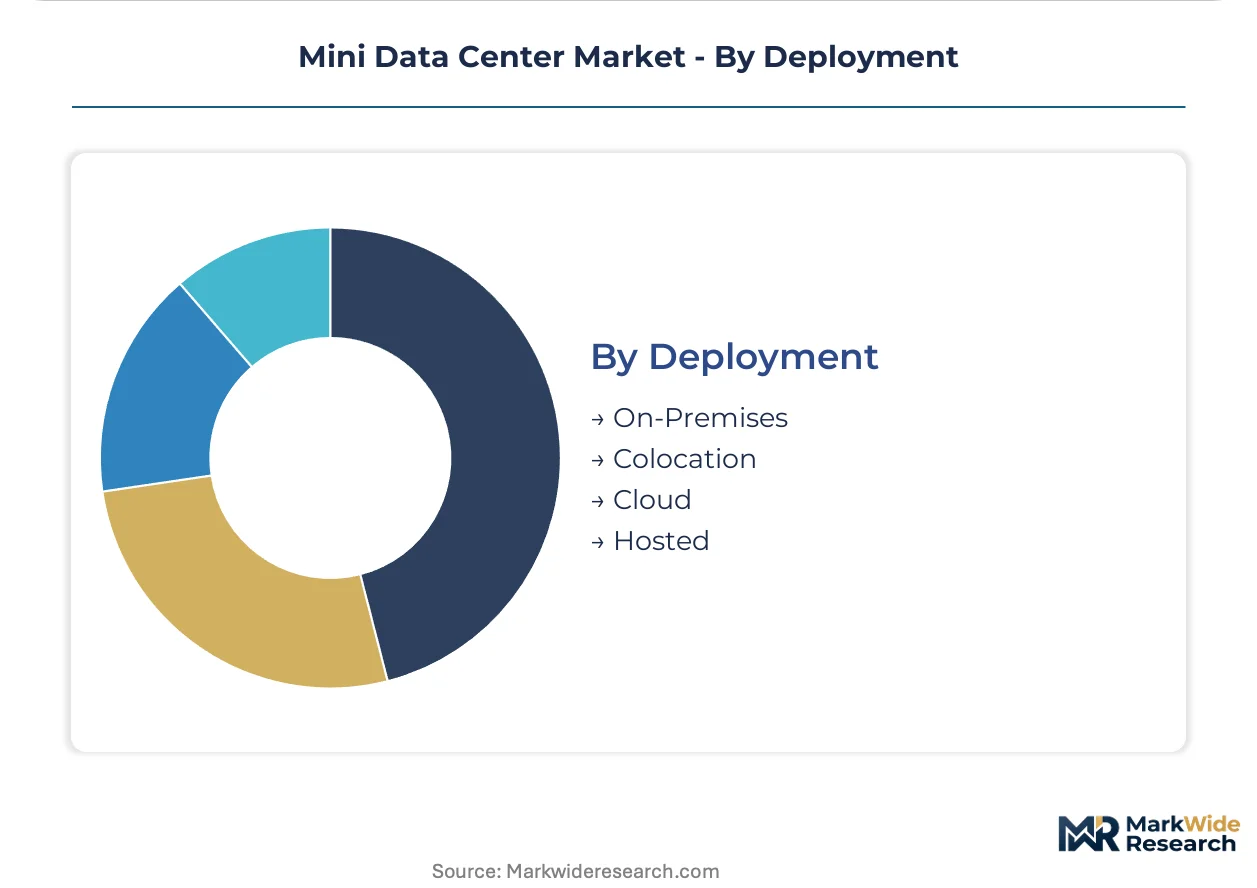
Deployment:
Control retention versus infrastructure outsourcing defines the configuration trade-off across this spectrum.
- On-Premises:Full operational control over physical security and network segmentation satisfies financial services compliance in Frankfurt and Munich. Capital intensity here is highest but latency guarantees are absolute.
- Colocation:Shared facility access reduces facility engineering burden while preserving hardware autonomy. Multi-tenant precision cooling in Amsterdam and Frankfurt addresses EU Energy Efficiency Directive reporting obligations through consolidated metering.
- Cloud:Consumption-based compute and storage abstracts infrastructure management entirely.
- Hosted:Managed service providers assume operational responsibility for hardware lifecycle and thermal performance.
Largest installed base: On-Premises. Fastest commercial model shift: Colocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian precision cooling component zones while consumption clusters in German industrial corridors and US telecommunications infrastructure. European regulatory pressure through the EU Energy Efficiency Directive is filtering procurement toward certified equipment. Asian markets exhibit price sensitivity that favors integrated power and enclosure manufacturing.
Germany
Bavaria and Baden-Württemberg host dense industrial automation clusters demanding sub-10 millisecond latency for factory floor processing. The EU Code of Conduct for Data Centres mandates efficiency benchmarks that exclude non-compliant equipment from public-sector tenders. Stuttgart's manufacturing conglomerates are deploying edge data centers with integrated precision cooling to satisfy proximity requirements for robotics control systems.
United States
Telecommunications carriers across urban corridors are densifying 5G infrastructure with self-contained prefabricated units. The EPA ENERGY STAR program establishes procurement filters for federal and large enterprise buyers. Dallas-Fort Worth and Atlanta metro areas exhibit concentrated deployment activity for autonomous vehicle telemetry and smart city sensor networks.
China
Domestic demand for electronic information system rooms operates under GB 50174 fire suppression and redundancy requirements that shape local product specifications. The MIIT oversees standards compliance for distributed IT infrastructure in manufacturing zones. Shenzhen and Shanghai manufacturing bases are capturing assembly investment through integrated power distribution and enclosure system production.
India
Production-linked incentives under the PLI scheme for electronics manufacturing are attracting data center component fabrication investment. The CEA regulates power infrastructure standards for distributed computing deployments. Karnataka and Maharashtra are emerging as assembly locations for micro data center enclosures targeting retail banking and branch office networks.
France
Telecommunications infrastructure buildouts in Île-de-France and Provence-Alpes-Côte d'Azur are creating demand for edge nodes with unmanned operation capabilities. The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in precision cooling equipment with steep compliance timelines for smaller batch production. Lyon and Marseille industrial zones are specifying monitoring systems with predictive analytics to reduce downtime costs.
Mini Data Center Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the mini data center value chain, with integrated infrastructure vendors holding structural advantages in large enterprise deployments. The vendor base separates into three strategic archetypes: diversified electrical equipment conglomerates with power and cooling portfolios, specialized thermal management firms with edge-optimized architectures, and vertically integrated Asian manufacturers with captive component supply. Dominant competitive moves include strategic partnerships with telecommunications carriers for 5G edge densification and geographic expansion through localized assembly to satisfy regional certification requirements.
Among diversified electrical equipment providers, Schneider Electric and Eaton occupy positions anchoring enterprise and industrial segments through integrated power distribution portfolios. Vertiv exemplifies the specialized thermal management archetype with precision cooling architectures purpose-built for unmanned edge environments. Huawei Technologies represents the vertically integrated Asian manufacturer model, leveraging captive production of power distribution and enclosure systems to serve price-sensitive procurement segments across domestic and export markets.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Eaton |
| Huawei Technologies |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Cisco Systems |
| IBM |
| Rittal |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU Code of Conduct-compliant precision cooling systems and uncertified commodity enclosures manifests in pricing spreads exceeding hardware-only differentials, while supply chains fragment between East Asian component concentration for thermal management and regional assembly investments chasing India's PLI incentives and Germany's Mittelstand procurement mandates.
Pricing Analysis
Cost-down pressure on precision cooling subsystems accelerates because copper and aluminum commodity volatility compresses margin predictability for fixed-price contracts. Three-tier pricing structure across premium, standard, and economy levels separates Schneider Electric's integrated power-cooling bundles from Vertiv's specialized edge architectures and Huawei's captive-manufactured enclosure systems. Government and large enterprise buyers exhibit lowest price sensitivity due to ENERGY STAR and EU Code of Conduct compliance requirements, while retail banking networks and SMBs prioritize operational expenditure conversion through subscription thermal management.
Supply Chain Analysis
CE marking and EPA ENERGY STAR qualification gates concentrate precision cooling component sourcing in China, South Korea, and Taiwan, with final assembly migrating to India under production-linked incentives. Thermal management subsystems draw from concentrated refrigerant compressor and heat exchanger manufacturing zones, exposing procurement to EU F-Gas Regulation phase-down timelines. Single-source vulnerability in specialized immersion cooling fluids creates bottleneck risk. Distribution runs through telecommunications carrier direct procurement channels and third-party service integrators disintermediating original equipment vendors in Germany's Mittelstand sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration depth, with upstream control over power distribution and precision cooling components offering defensible margin structures against commodity enclosure commoditization.
For Market Incumbents: Deepen captive production of thermal management subsystems to offset East Asian component concentration risk and copper price volatility. Secure multi-year service contracts with Germany's industrial automation clusters before third-party integrators capture recurring revenue relationships. Invest in liquid immersion cooling engineering bandwidth ahead of EU F-Gas Regulation compliance deadlines. For New Entrants and Emerging Players: Direct-to-telecom-carrier digital procurement platforms offer lowest friction entry for edge data center deployments in France and Spain's 5G densification corridors. Target India's PLI-supported assembly locations for micro data center enclosures serving retail banking networks. Position predictive analytics monitoring systems as standalone SaaS offerings to bypass hardware margin compression. For Investors and Strategic Acquirers: Re-rating potential sits with specialized thermal management firms given machine learning convergence with remote monitoring capabilities and unplanned downtime prevention economics. Long-term viability favors vendors with backward integration into power distribution and cooling component supply. Watch for inflection in telecommunications carrier capex acceleration for sub-10 millisecond edge deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Cooling Components | Captive compressor and heat exchanger production insulates margins from EU F-Gas Regulation supply constraints. |
| Subscription-Based Thermal Management Service Launch | Recurring revenue conversion addresses Mittelstand procurement preference for operational expenditure models in Germany. |
| India PLI Scheme Assembly Investment | Domestic enclosure fabrication reduces import dependency for retail banking network deployments across Maharashtra. |
| Predictive Analytics Platform Integration | Machine learning-enabled monitoring systems command premium pricing through uptime guarantees for unmanned edge installations. |
| Telecommunications Carrier Strategic Partnership | 5G network densification contracts in Dallas-Fort Worth and Atlanta secure multi-year edge data center deployment pipelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with data center infrastructure procurement officers, telecommunications network planning executives, precision cooling system engineers, and thermal management service operations managers. EPA ENERGY STAR certification databases, EU Code of Conduct submissions, China's GB 50174 compliance filings, and India's PLI scheme beneficiary disclosures provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down capex analysis across telecommunications carriers and industrial automation clusters.
Granularity-level modeling captured product type, thermal architecture, deployment mode, and end-user vertical at the country level across the projection horizon. CAGRs derived from logistic adoption curves fitted to 5G infrastructure buildout timelines and industrial IoT penetration rates. Forecast inputs incorporated EU Energy Efficiency Directive enforcement intensity, copper futures trajectory assumptions, and edge computing latency requirement evolution for autonomous systems.
The model holds under sustained telecommunications infrastructure investment and stable commodity input costs; deviation in central bank rate policy or East Asian trade friction would shift deployment timelines. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or India's PLI scheme extension decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Taiwan Data Center Server Market