
 Data Center Colocation Market | 2026-2036
Data Center Colocation Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Colocation Market Intelligence
Hyperscale cloud service providers is broadening the end-use vertical mix for colocation capacity, pulling ahead of traditional enterprise tenants. Equinix leverages its global interconnection platform to capture cross-border traffic flows between cloud regions. Digital Realty sustains its position through hyperscale-focused campus developments in key metro areas. NTT Ltd. anchors its competitive stance with deep fiber assets and local regulatory expertise across Asia-Pacific markets.
Data center colocation refers to the provision of physical space, power, cooling, and network connectivity for third-party IT equipment within multi-tenant facilities, typically engineered to Tier III or Tier IV reliability standards with power usage effectiveness ratios below 1.4. The primary commercial purpose is to convert fixed infrastructure costs into variable operating expenditures while providing deterministic latency to cloud on-ramps and internet exchanges. Wholesale colocation commands the largest revenue pool due to megawatt-scale commitments from cloud service providers, while retail colocation retains higher per-unit margins from smaller tenants with less bargaining power. Managed services and interconnection segments are expanding fastest as customers seek operational offload and direct cloud access without traversing the public internet.
The EU Green Deal and EPA emissions frameworks in the United States are mandating renewable power sourcing and carbon disclosure for facility operators, directly influencing site selection and power procurement strategies. ISO 27001 and national cybersecurity standards in Germany, Singapore, and India impose audit requirements that determine market access for providers serving regulated industries. Stakeholders must monitor evolving grid interconnection queues and permitting timelines as these constraints increasingly determine delivery schedules more than construction capacity itself.
Market Dynamics
Hyperscale cloud providers are compressing colocation contract cycles from five-year terms to three-year renewals with embedded expansion clauses, forcing facility operators to pre-position modular power and cooling corridors ahead of signed commitments.
Growth Catalysts
- AI Training Clusters:Large language model deployments from cloud operators require 10-50MW contiguous blocks that only wholesale colocation campuses can provision at speed.
- EU Green Deal:Carbon disclosure mandates under CSRD are pushing enterprises out of owned data centers into multi-tenant facilities with verified renewable power purchase agreements.
- Liquid Cooling:Direct-to-chip and immersion systems are unlocking 50kW+ rack densities for GPU-heavy workloads that traditional raised-floor facilities cannot support.
Market Restraints
- Transformer Lead Times:Utility-scale power distribution equipment from European and Asian manufacturers now extends 18-24 months, gating facility energization regardless of construction completion.
- Permitting Gridlock:Local zoning boards in Northern Virginia and Frankfurt am Main are imposing 12-18 month environmental review cycles on hyperscale campus expansions.
- On-Premise Repatriation:Some financial services firms are reversing cloud migration to captive facilities driven by data sovereignty rulings from national regulators.
Strategic Opportunities
- India:Mumbai and Chennai are emerging as interconnection bridges between Middle Eastern oil-funded cloud regions and Southeast Asian manufacturing corridors.
- Edge Micro-Facilities:500kW-2MW modular deployments at cell tower bases and manufacturing plants are capturing autonomous vehicle telemetry and industrial IoT processing.
- Green Hydrogen:Japanese METI subsidies for hydrogen-ready fuel cells are creating first-mover positioning for colocation operators in Osaka and Tokyo metro markets.
Industry Challenges
- Electrical Trade Shortage:Certified medium-voltage technicians capable of terminating 15kV switchgear are concentrated among retiring union workforces in Germany and the United States.
- Legacy Integration:Enterprises migrating from owned facilities struggle to replicate mainframe connectivity and deterministic latency guarantees within multi-tenant network fabrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Colocation Market |
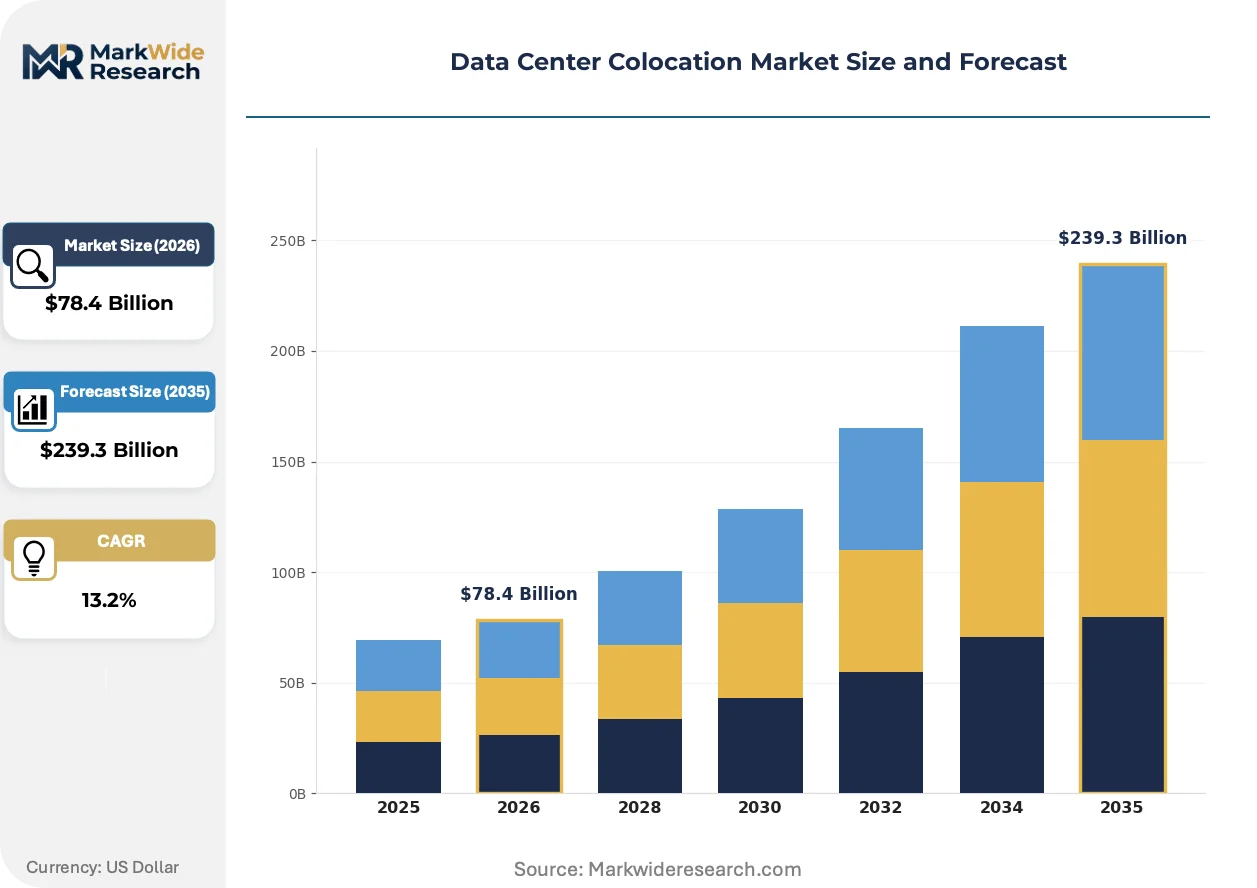
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $239.3 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Colocation, Wholesale Colocation, Managed Services, Interconnection End User: SMBs, Enterprises, Cloud Service Providers, Telecommunications Deployment: On-Premises, Off-Premises, Hybrid, Multi-Cloud Solution: Infrastructure as a Service, Disaster Recovery as a Service, Backup Solutions, Security Services |
| Companies Covered | Vantage Data Centers, NTT Ltd., Equinix, Element Critical, Global Switch, Digital Realty, Flexential, China Telecom Corporation Limited, NTT Global Data Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Colocation Market Strategic Shifts & Innovations
Facility architecture is bifurcating between air-cooled enterprise shells and liquid-cooled AI factories, with engineering teams retraining on thermal design software originally developed for semiconductor fabs.
High-density liquid cooling is electrifying competitive positioning among wholesale operators. Direct-to-chip cold plates and single-phase immersion tanks are enabling 100kW racks in footprints previously capped at 15kW. Hyperscale cloud engineers are specifying these systems in 80% of new RFPs issued since mid-2024. The technology is electrifying site selection criteria toward markets with abundant water access and industrial wastewater discharge permits.
EPA emissions frameworks in the United States are mandating hourly-matched renewable energy accounting for facilities above 100kW nameplate capacity. This industrial consequence is compressing power procurement timelines and forcing operators into 15-20 year solar and wind contracts. Wholesale colocation campuses in Texas and Arizona are most affected, responding by co-losing generation assets behind the meter.
Enterprise procurement of colocation services is fragmenting from centralized IT sourcing to distributed business-unit decisions. Individual application owners now sign direct contracts with edge facilities, bypassing traditional vendor management offices. This pattern is most visible in Germany's automotive sector, where plant engineers procure local capacity for quality-control computer vision without corporate data center team involvement.
Data Center Colocation Market Segmentation
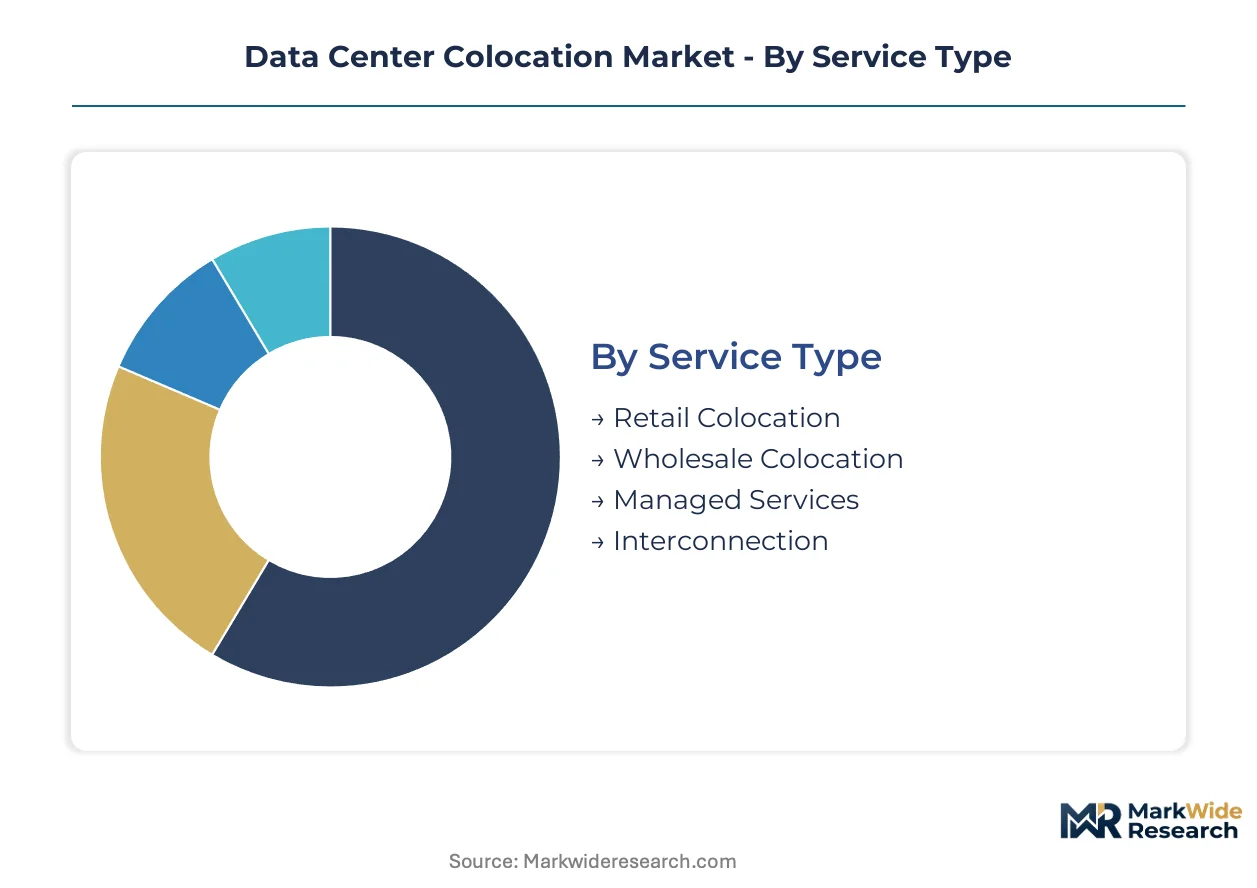
Colocation segmentation tracks how infrastructure consumption fragments across procurement scales, operational control preferences, and workload criticality. Each dimension reveals distinct margin structures and capital intensity requirements that determine provider strategy.
Service Type:
Standardization decreases from retail to wholesale, while customization depth inverts—retail tenants accept uniform specifications, wholesale clients dictate power density and network architecture.
- Retail Colocation:Multi-tenant cabinets and partial racks with standardized power and cross-connect pricing. Demand concentrates among German automotive suppliers and Singapore fintech startups seeking ISO 27001-certified facilities without capital deployment. The EU CSRD disclosure mandates are accelerating migration from captive server rooms into verified multi-tenant environments.
- Wholesale Colocation:Dedicated data halls or buildings with 500kW-50MW power commitments and tenant-specified cooling topologies. Northern Virginia and Frankfurt absorb the majority of cloud service provider expansion for AI training clusters requiring contiguous megawatt blocks. Transformer lead times now determine delivery schedules more than concrete and steel.
- Managed Services:Operational offload encompassing remote hands, hardware break-fix, and operating system administration. Japanese enterprises under METI digital transformation directives are the primary adopters.
- Interconnection:Private cloud on-ramps, internet exchange cross-connects, and software-defined networking fabrics. Mumbai and Chennai exchanges are capturing Middle East-to-Southeast Asia traffic flows.
Leading the category by volume: Wholesale Colocation. Growing fastest: Interconnection.
End User:
Procurement sophistication scales inversely with tenancy size—cloud providers negotiate 20-year power contracts directly with utilities, while SMBs purchase through channel partners.
- Cloud Service Providers:Hyperscale operators consuming 10-50MW blocks with liquid cooling specifications and renewable energy hourly-matching requirements. These tenants are compressing contract cycles to three-year terms with embedded expansion clauses across Texas, Arizona, and Northern Virginia campuses.
- Enterprises:Fortune 500 manufacturers and financial institutions migrating mainframe connectivity to colocation fabrics. German banks under BaFin operational resilience mandates are the most active segment in Frankfurt.
- SMBs:Regional healthcare clinics, law firms, and SaaS vendors purchasing 2-10kW cabinets. Price sensitivity drives concentration in secondary markets like Phoenix and Amsterdam.
- Telecommunications:Mobile network operators deploying 5G core functions and edge computing nodes. Indian operators under TRAI infrastructure sharing rules are consolidating into Mumbai metro facilities.
Cloud Service Providers command the largest committed capacity. SMBs are expanding most quickly as distributed procurement bypasses central IT.
Deployment:
Control retention versus operational offload defines the spectrum—on-premises maintains full sovereignty, multi-cloud fragments it across providers.
- Hybrid:Workload orchestration across owned facilities and colocation with unified management planes. Japanese automotive manufacturers under METI supply chain resilience guidelines are the dominant adopters.
- Multi-Cloud:Deliberate distribution across AWS, Azure, and GCP regions with colocation as the interconnection layer. Singapore and Mumbai host the densest multi-cloud exchange fabrics.
- On-Premises:Captive facilities retained for latency-sensitive trading systems or classified government workloads. US defense contractors under CMMC requirements maintain this posture.
- Off-Premises:Complete infrastructure exit to third-party facilities. German enterprises facing CSRD carbon disclosure deadlines are accelerating this shift.
Hybrid deployments retain the largest installed base. Multi-Cloud configurations are climbing the fastest as application owners bypass corporate data center teams.
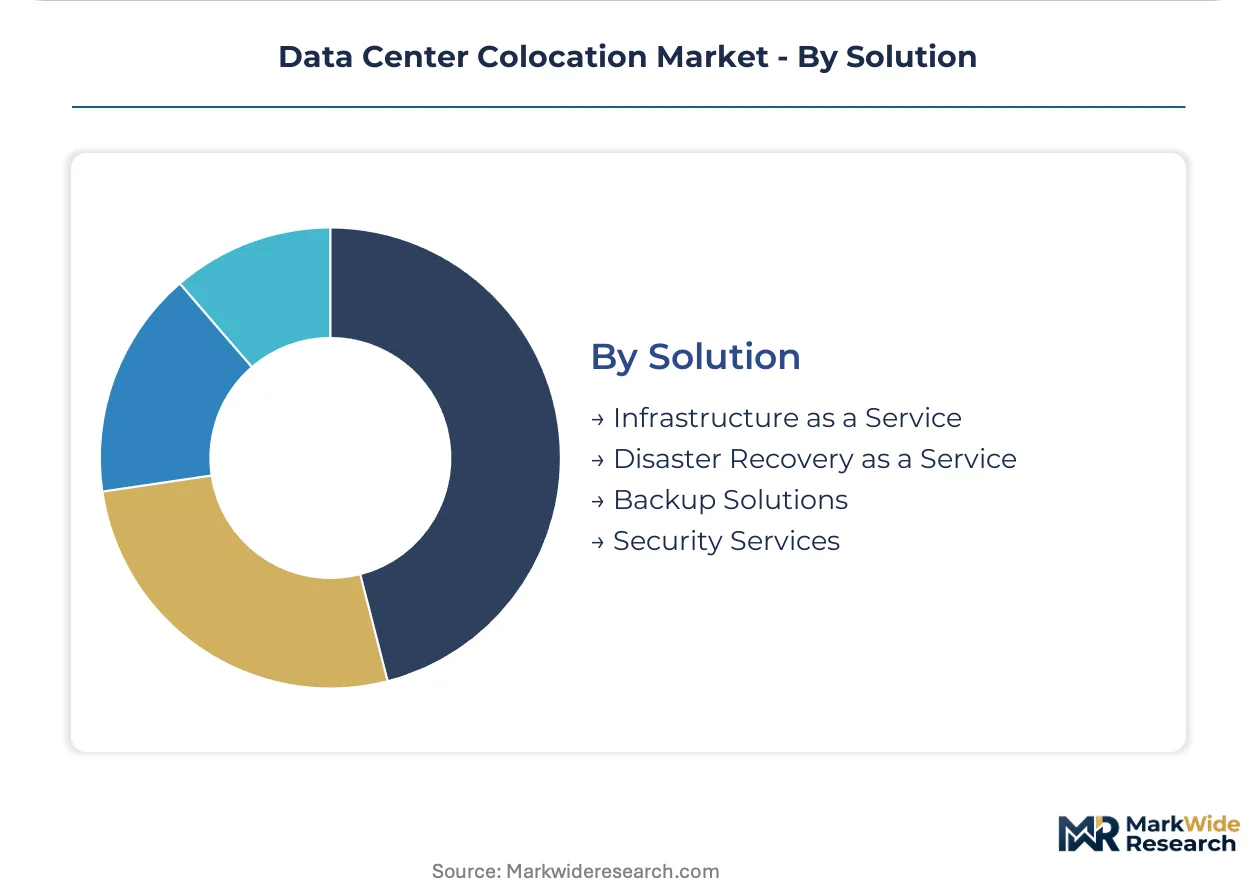
Solution:
Margin accretion follows operational complexity—commoditized rack space yields lowest returns, managed security services highest.
- Security Services:DDoS mitigation, web application firewalls, and zero-trust network access delivered as colocation-adjacent offerings. Financial services firms in Singapore and Frankfurt are the primary consumers under national cybersecurity authority directives.
- Disaster Recovery as a Service:Synchronous and asynchronous replication with RPO/RTO guarantees enforced by SLA. Indian banks under RBI business continuity mandates are driving adoption in Chennai secondary sites.
- Infrastructure as a Service:Compute and storage hardware leased within colocation footprints. US federal contractors under FedRAMP authorization requirements concentrate in Northern Virginia.
- Backup Solutions:Immutable object storage for ransomware recovery and long-term retention. German healthcare providers under BSI IT-Grundschutz standards are the core segment.
Infrastructure as a Service leads by committed revenue. Security Services are gaining share fastest as attack surface complexity outpaces enterprise SOC capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virginia's Data Center Market Development Program grants sales and use tax exemptions on qualifying equipment, concentrating hyperscale investment in Loudoun and Prince William counties. This fiscal architecture has reshaped interconnection density across multiple continents.
United States
AI training clusters from cloud operators drive 10-50MW contiguous power commitments across Northern Virginia and Phoenix metro markets. EPA emissions frameworks mandate hourly-matched renewable energy accounting for facilities above 100kW nameplate capacity. Dallas-Fort Worth campuses absorb secondary demand as transformer lead times extend delivery schedules in primary markets.
Germany
BaFin operational resilience mandates accelerate financial services migration from captive facilities to certified multi-tenant environments. The EU Green Deal's CSRD disclosure requirements push enterprises toward verified renewable power purchase agreements. Frankfurt am Main hosts the densest interconnection fabric between cloud regions, though local zoning boards impose 12-18 month environmental review cycles on expansions.
India
TRAI infrastructure sharing rules consolidate mobile network operator deployments into Mumbai and Chennai metro facilities. RBI business continuity mandates drive disaster recovery adoption across banking sectors. These cities function as interconnection bridges between Middle Eastern oil-funded cloud regions and Southeast Asian manufacturing corridors.
Japan
METI digital transformation directives elevate managed services procurement among enterprise tenants. Subsidies for hydrogen-ready fuel cells create first-mover positioning in Osaka and Tokyo metro markets. Japanese automotive manufacturers under supply chain resilience guidelines dominate hybrid deployment adoption.
Singapore
National cybersecurity authority directives elevate security services consumption among financial services firms. The city-state's energy efficiency mandates reshape facility design standards for tropical operating conditions. Multi-cloud exchange fabrics here capture densest traffic distribution across AWS, Azure, and GCP regions in Southeast Asia.
Data Center Colocation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with wholesale operators commanding committed capacity while retail-focused providers retain margin advantages. Facility operators bifurcate between hyperscale campus developers and interconnection platform operators. Strategic archetypes include global platform operators with exchange fabrics, regional wholesale specialists with power-forward land positions, and telecom-anchored providers with fiber depth. Competitive moves concentrate on pre-positioning modular power corridors ahead of signed commitments and securing 15-20 year renewable energy contracts.
Among exchange-centric platform operators, Equinix occupies a position exemplifying global interconnection architecture, while Digital Realty represents the hyperscale-focused campus development archetype. NTT Ltd. anchors the telecom-anchored category with deep fiber assets across Asia-Pacific markets. These three entities collectively illustrate the strategic segmentation between network fabric operators, power-intensive wholesale developers, and regionally integrated infrastructure providers.
| Leading Market Players |
|---|
| Vantage Data Centers |
| NTT Ltd. |
| Equinix |
| Element Critical |
| Global Switch |
| Digital Realty |
| Flexential |
| China Telecom Corporation Limited |
| NTT Global Data Centers |
| Others |
Cost & Logistics Intelligence
Liquid cooling retrofits across legacy facilities are compressing depreciation schedules while concentrating procurement leverage among European transformer manufacturers and Asian pump suppliers. This technology transition simultaneously elevates capital recovery risk for operators and tightens vendor concentration in critical thermal infrastructure.
Pricing Analysis
Premium pricing for sub-12-month transformer delivery now commands 15-25% markups over standard lead-time contracts, while spot inventory of modular cooling units trades at discounts in oversupplied secondary markets. Wholesale colocation pricing stratifies across premium liquid-cooled AI halls, standard air-cooled enterprise suites, and economy remote-hands-only tiers. Cost compression in retail segments is intensifying because hyperscale tenants extract volume discounts exceeding 40% on multi-megawatt commitments. SMBs purchasing sub-100kW cabinets exhibit highest price sensitivity, while cloud providers with direct utility relationships are least sensitive to published rate cards.
Supply Chain Analysis
Reverse logistics for decommissioned UPS batteries and retired server racks now flow through certified refurbishment centers in Germany, Singapore, and Texas before re-entry into secondary equipment markets. Primary manufacturing concentrates in China for precision cooling components, Germany for medium-voltage switchgear, and South Korea for advanced power semiconductors. The supply chain draws from copper rod mills in Chile, rare earth processors in China, and epoxy resin suppliers in Japan. Single-source vulnerability sits with European transformer OEMs facing order backlogs exceeding 18 months. Distribution runs through direct utility procurement for power infrastructure, specialized HVAC distributors for cooling equipment, and integrator channels for rack-and-stack hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer lead times and certified electrical labor scarcity are the binding constraints propping pricing power for operators with pre-positioned power corridors and union-trained workforces.
For Market Incumbents: Anchor market position by securing 15-20 year renewable energy contracts with hourly-matching provisions before EPA emissions frameworks tighten further. Pre-position modular power and cooling corridors in Northern Virginia and Frankfurt ahead of signed hyperscale commitments to compress delivery cycles. Vertical integration into electrical construction crews mitigates the certified technician shortage threatening project energization timelines. For New Entrants and Emerging Players: System integrators with liquid cooling deployment expertise represent the most accessible channel partner type for bypassing incumbent relationships. Target edge micro-facility deployments in Indian manufacturing corridors and Japanese industrial zones where hyperscale operators lack presence. White-space opportunities concentrate in hydrogen-ready fuel cell integration for Osaka and Tokyo metro markets under METI subsidy programs. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale campus developers with secured land and power entitlements in primary interconnection hubs. Long-term viability favors operators with 20-year utility contracts and Tier III+ certifications across multiple regulatory jurisdictions. The signal to watch is grid interconnection queue priority shifts that advantage early applicants over late entrants in constrained power markets.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Power Corridor Pre-Positioning | Compresses delivery schedules for hyperscale AI training clusters in Northern Virginia and Frankfurt. |
| Hourly-Matched Renewable Energy Contracting | Satisfies EPA emissions frameworks for facilities above 100kW nameplate capacity in Texas and Arizona. |
| Liquid Cooling Engineering Partnership | Unlocks 100kW rack densities for GPU-heavy workloads that air-cooled facilities cannot support. |
| Certified Electrical Workforce Development | Mitigates medium-voltage technician shortage concentrated among retiring union workforces in Germany. |
| Hydrogen-Ready Fuel Cell Integration | Captures METI subsidies for first-mover positioning in Osaka and Tokyo metro markets. |
Research Approach
Independent corroboration across facility operators, hyperscale cloud procurement executives, and electrical construction contractors underwrites the qualitative findings on transformer lead-time impacts. Primary interviews with data center development officers, utility interconnection planners, and cooling system engineers combined with secondary validation through EIA power plant databases, FERC interconnection filings, and hyperscaler capex disclosures. Bottom-up capacity build tracking and top-down revenue triangulation anchored market sizing across wholesale, retail, and interconnection segments.
Comparable-period analysis anchored the forecast window to historical deployment cycles spanning pre-pandemic, supply-constrained, and AI-demand-acceleration phases. Segmentation dimensions modeled include service type, end-user archetype, deployment configuration, and solution category alongside power density tier and cooling topology as industry-specific variables. CAGRs derived from facility absorption rates, power commitment trajectories, and interconnection port growth curves across the analysis window. Forecast inputs incorporated grid interconnection queue depths, permitting timeline distributions, and renewable energy procurement velocity by metro market.
Caveats apply where transformer manufacturing capacity expansion, immigration policy shifts affecting electrical trades, or AI demand plateauing could materially shift the outlook. Practitioners should monitor grid interconnection priority shifts and EPA emissions rulemakings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
New York Data Center Market