
 Italy Data Center Cooling Market | 2026-2036
Italy Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Cooling Market Insights
Data center mechanical and electrical engineering talent is unwinding supply bottlenecks as Italian universities expand specialized HVAC and thermal management curricula. Schneider Electric SE leverages its European manufacturing footprint to anchor domestic service response times. Vertiv Group Corp competes through direct expansion and chiller product lines calibrated to Mediterranean ambient conditions. Stulz GmbH specializes in precision cooling systems for high-density compute environments, sustaining technical differentiation against broader portfolio rivals.
Italy data center cooling encompasses engineered thermal management systems that regulate temperature and humidity within server environments, typically operating across supply air setpoints of 18-27°C per ASHRAE guidelines to prevent hardware degradation and ensure continuous uptime. These systems employ vapor compression cycles, liquid coolant distribution networks, or hybrid architectures to reject heat loads generated by IT equipment ranging from 5 kW per rack in legacy facilities to exceeding 50 kW in AI-optimized deployments. Liquid cooling solutions are capturing accelerated interest as rack densities climb, while air cooling retains dominance in retrofitted enterprise facilities where infrastructure replacement cycles extend operational continuity. CRAC units and in-row coolers constitute the mature installed base, though immersion cooling represents an emerging margin pool for specialized high-performance computing applications.
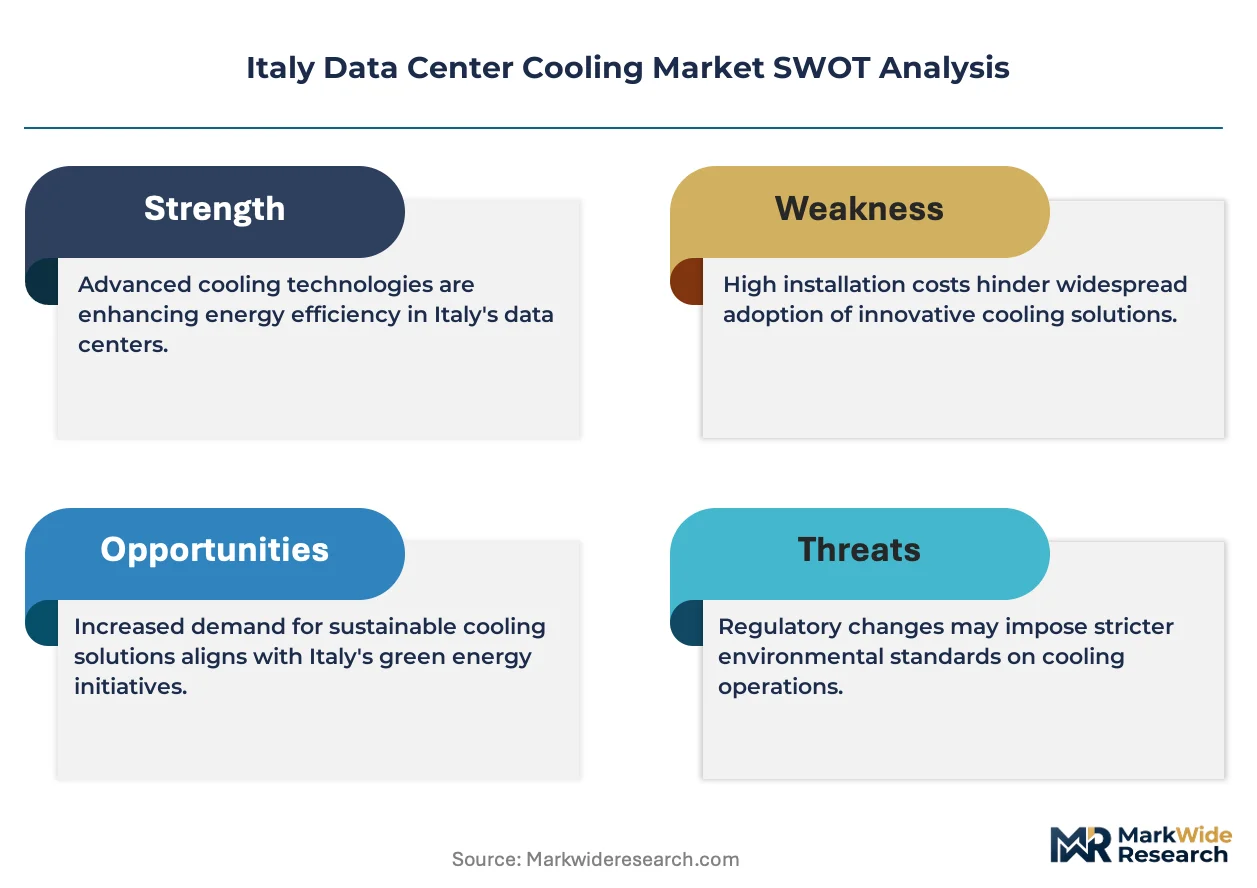
Italy's Ministry of Enterprise and Made in Italy (MIMIT) coordinates with the National Cybersecurity Agency (ACN) to enforce data center resilience standards under the PNRR digital infrastructure framework. CE marking and EU Energy Efficiency Directive compliance shape product certification requirements for cooling equipment deployed across Italian territory. Stakeholders must monitor how the EU AI Act's infrastructure provisions and evolving ETS carbon pricing mechanisms will recalibrate thermal efficiency thresholds and capital allocation priorities for new facility construction.
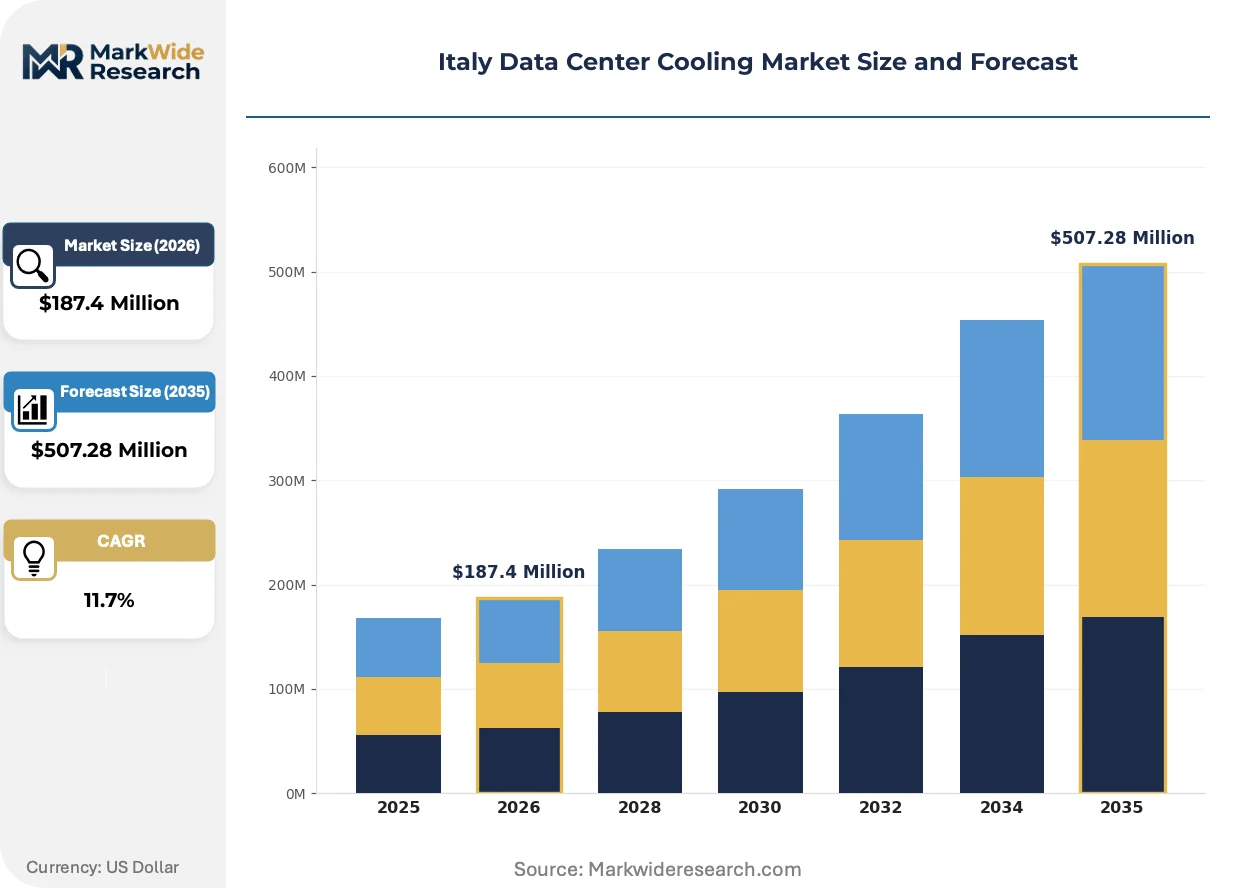
Market Dynamics
AI-optimized rack densities exceeding 50 kW are compressing cooling infrastructure replacement cycles across Italian facilities, forcing thermal management architectures toward liquid-based rejection systems that legacy air-cooled plants cannot accommodate without structural overhaul.
Growth Catalysts
- PNRR Digital Infrastructure Allocation:Italy's National Recovery and Resilience Plan channels public capital toward data center modernization, accelerating facility upgrades that incorporate advanced cooling systems compliant with EU energy efficiency mandates.
- Hyperscale Cluster Concentration:Cloud service providers are scaling facilities across Lombardy and Lazio, generating concentrated demand for high-capacity chillers and precision cooling systems calibrated to Mediterranean ambient conditions.
- Liquid Cooling Maturation:Direct-to-chip and immersion cooling technologies are reaching commercial viability for high-performance computing workloads, enabling thermal rejection densities that air-based systems cannot match.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger and piping input costs fluctuate with commodity markets, compressing equipment margins and complicating long-term project quoting for mechanical contractors.
- German Component Supply Concentration:Precision valves, compressors, and control systems for large-scale chillers originate from a concentrated supplier base north of the Alps, exposing Italian integrators to cross-border logistics friction.
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation mandates refrigerant transition timelines that strand existing vapor compression assets before full depreciation, forcing premature capital redeployment.
Strategic Opportunities
- Southern Italy Latency Arbitrage:Underdeveloped data center capacity in Sicily and Calabria offers greenfield development potential where submarine cable landing points intersect with lower land and power costs than northern metros.
- Waste Heat Recovery Integration:District heating network interconnection enables cooling systems to monetize thermal output, converting energy cost centers into revenue streams under municipal sustainability frameworks.
- AI Act Infrastructure Provisions:Emerging EU AI Act requirements for high-performance computing resilience create compliance-driven demand for redundant cooling architectures in facilities hosting frontier model training.
Industry Challenges
- Thermal-Fluid Engineering Talent Scarcity:Italian universities are expanding HVAC curricula but graduate output lags facility construction timelines, forcing operators to recruit from German and Swiss labor markets.
- ASHRAE Guideline Compliance Complexity:Continuous updates to thermal environmental standards for data processing equipment require ongoing recalibration of control system setpoints and documentation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Cooling Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Hybrid Cooling, Direct Expansion End User: Colocation Providers, Cloud Service Providers, Enterprises, Government Agencies System Type: Chillers, CRAC Units, In-row Coolers, Immersion Cooling Service Type: Maintenance Services, Installation Services, Consulting Services, Managed Services |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Stulz GmbH, Rittal GMBH & Co KG, Johnson Controls International PLC, Asetek A/S, Hitachi Ltd, Mitsubishi Electric Hydronics & IT Cooling Systems S p A, Alfa Laval AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Cooling Market Trends and Innovations
Thermal management architectures are bifurcating between liquid-cooled high-density zones and air-cooled legacy footprints, creating hybrid facility designs that demand flexible infrastructure investment strategies from Italian operators.
Immersion cooling is fragmenting the high-performance computing segment as hyperscale operators deploy dielectric fluid baths for AI training clusters. Financial services and research institutions in Milan are piloting single-phase immersion for GPU-intensive workloads. This technology is fragmenting vendor competitive sets, separating specialists with fluid chemistry expertise from traditional air-conditioning manufacturers.
The EU F-Gas Regulation is accelerating refrigerant transition roadmaps for vapor compression equipment deployed across Italian territory. Equipment manufacturers must recalibrate chiller product lines toward low-global-warming-potential alternatives before 2030 phase-down milestones. Data center operators in the Milan metropolitan area are responding by front-loading replacement cycles to avoid stranded asset risk.
Service contracting is unbundling from equipment procurement as facility operators seek performance-guaranteed thermal management outcomes. Colocation providers are shifting from capital purchase models to long-term service agreements that transfer operational risk to cooling system vendors. This pattern is most visible among cloud-adjacent enterprises in Lombardy seeking to minimize in-house mechanical engineering headcount.
Italy Data Center Cooling Market Segmentation
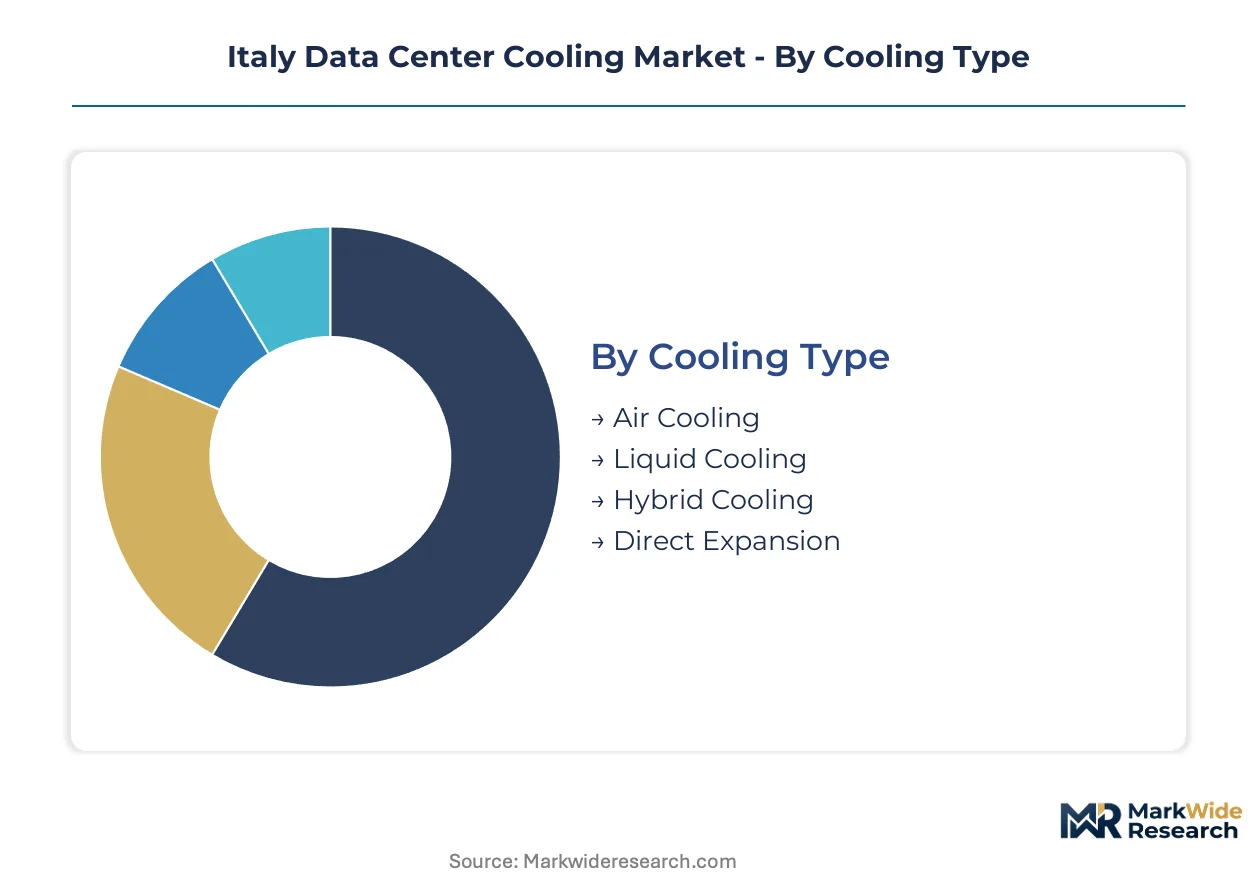
Thermal management architectures in Italian data centers diverge sharply by workload density and facility vintage. Cooling type selection determines capital intensity and operational flexibility, while end-user concentration shapes service contracting models across Lombardy and Lazio.
Cooling Type:
Air cooling systems dominate domestic retrofit demand from legacy enterprise facilities, while liquid cooling solutions concentrate in export-oriented AI training clusters serving pan-European cloud workloads.
- Air Cooling:Vapor compression and raised-floor distribution architectures serve rack densities below 15 kW across Milan's established colocation corridors. Operators in retrofitted banking facilities prioritize operational continuity over efficiency gains, extending replacement cycles despite rising energy costs.
- Liquid Cooling:Direct-to-chip and cold plate configurations reject heat loads exceeding 50 kW for GPU-intensive training workloads. Hyperscale deployments in the Milan metropolitan area drive specification standards that Italian integrators export to comparable Mediterranean climate zones.
- Hybrid Cooling:Zoned architectures combine air-cooled legacy footprints with liquid-cooled high-density pods. Financial services operators in Lombardy deploy this approach to phase infrastructure transitions without full facility shutdowns.
- Direct Expansion:Self-contained refrigerant loops serve edge computing nodes and distributed enterprise sites. Lower upfront capital attracts regional logistics operators building latency-sensitive capacity outside primary metro markets.
Air cooling commands the established base. The steepest expansion runs through liquid cooling.
End User:
Customer type stratifies by procurement sophistication — hyperscale operators negotiate long-term service agreements while government tenders emphasize compliance documentation.
- Colocation Providers:Multi-tenant facility operators in Milan and Rome standardize on redundant cooling architectures to guarantee uptime SLAs. These stakeholders drive demand for performance-contracted maintenance services that transfer operational risk to equipment vendors.
- Cloud Service Providers:Hyperscale operators deploy custom thermal management systems optimized for uniform rack densities. Their Lombardy and Lazio facilities establish reference designs that cascade to secondary Italian markets.
- Enterprises:Corporate data centers in Turin and Bologna prioritize retrofit compatibility over peak efficiency. Extended depreciation schedules delay cooling infrastructure refresh cycles.
- Government Agencies:Public sector procurement under PNRR digital infrastructure mandates emphasizes CE marking and EU Energy Efficiency Directive compliance. ACN cybersecurity resilience standards shape redundant cooling specifications for critical national systems.
Colocation providers anchor current installed capacity. Cloud service providers are gaining share fastest.
System Type:
Equipment category selection tracks facility scale — central chillers serve campus deployments while modular units address constrained urban footprints.
- Chillers:Centralized refrigeration plants with cooling towers dominate hyperscale campuses in the Milan metropolitan area. Mediterranean ambient temperature profiles require condenser designs calibrated to higher wet-bulb conditions than northern European reference standards.
- CRAC Units:Computer room air conditioning systems constitute the legacy installed base across Italian enterprise facilities. Replacement demand concentrates where F-Gas Regulation phase-down timelines strand refrigerant-dependent assets.
- In-row Coolers:Proximity cooling units enable higher rack densities without raised-floor infrastructure. These systems attract colocation providers retrofitting older buildings with structural load constraints.
- Immersion Cooling:Dielectric fluid baths serve specialized high-performance computing applications. Research institutions and financial services operators in Milan pilot single-phase immersion for GPU clusters.
CRAC units command the established base. The steepest expansion runs through immersion cooling.
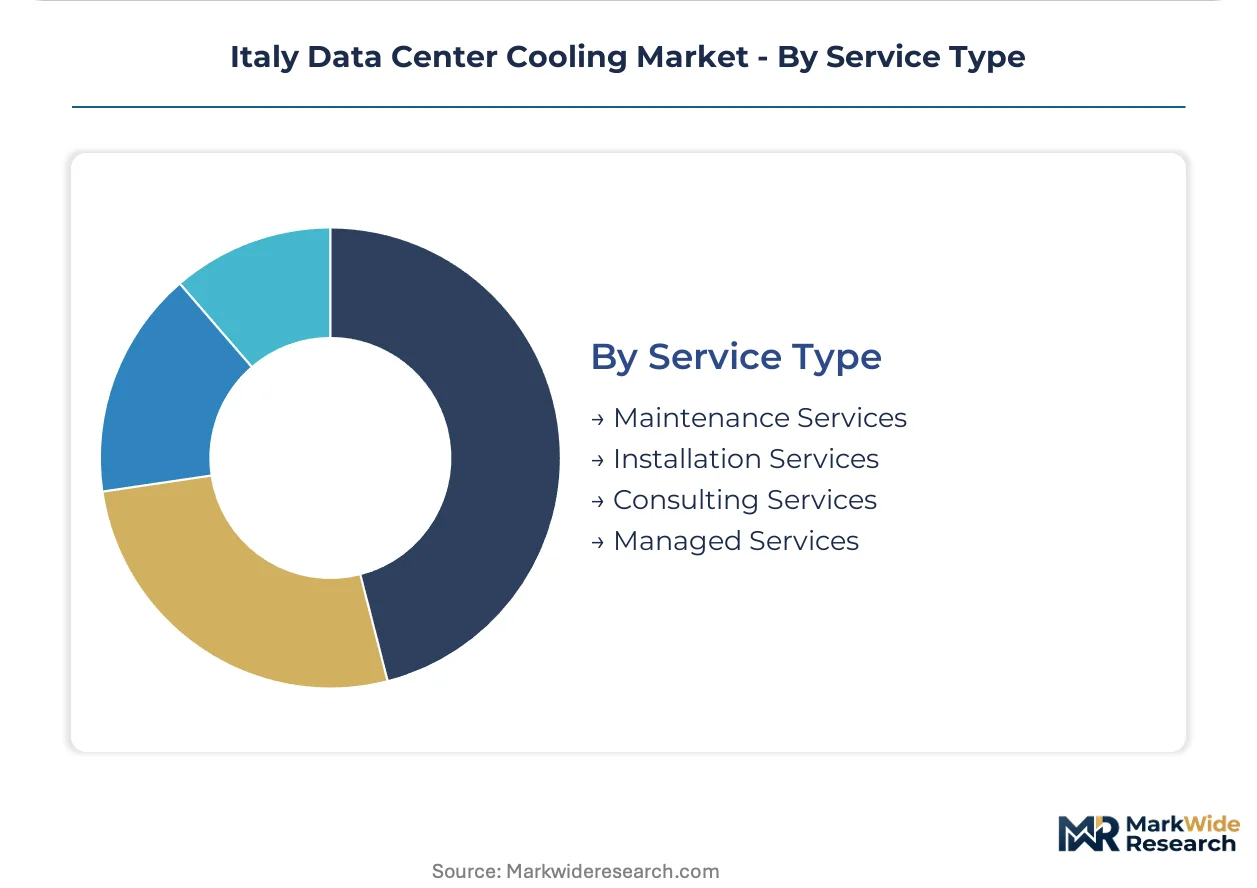
Service Type:
Service contracting unbundles from equipment procurement as facility operators seek outcome-guaranteed thermal management.
- Maintenance Services:Preventive and corrective maintenance contracts preserve uptime guarantees. Colocation providers in Lombardy shift toward vendor-operated service agreements to minimize in-house mechanical engineering headcount.
- Installation Services:Mechanical and electrical integration for new construction and retrofit projects. Demand concentrates in hyperscale greenfield developments across Lombardy and Lazio.
- Consulting Services:Thermal assessment and infrastructure planning for facility upgrades. Enterprises navigating F-Gas Regulation compliance drive advisory demand.
- Managed Services:Full operational responsibility for cooling system performance. Cloud-adjacent enterprises adopt this model to focus capital on core IT rather than facilities infrastructure.
Maintenance services command the established base. Managed services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIMIT anchors Italy's data center cooling governance through PNRR digital infrastructure coordination with ACN cybersecurity standards. Regional development concentrates in northern industrial corridors where power density and fiber connectivity intersect.
Lombardy
Milan's metropolitan area generates concentrated demand for high-capacity chillers serving hyperscale cloud campuses. MIMIT infrastructure allocations under PNRR accelerate facility upgrades with EU Energy Efficiency Directive compliance. The Milan-Turin corridor hosts Italy's densest colocation cluster where liquid cooling adoption outpaces national averages.
Lazio
Rome's public sector procurement drives redundant cooling specifications for critical national systems under ACN resilience mandates. CE marking requirements shape equipment certification for government data centers. The capital region attracts cloud service provider expansion where latency-sensitive workloads serve central-southern European markets.
Piedmont
Turin's automotive and industrial automation heritage feeds enterprise data center retrofit demand with extended depreciation schedules. F-Gas Regulation phase-down timelines pressure refrigerant-dependent assets in legacy banking facilities. The Alpine foothill location offers natural cooling advantages for free-air economization during winter months.
Emilia-Romagna
Bologna's research institutions pilot immersion cooling for GPU-intensive scientific computing workloads. University-industry partnerships expand thermal-fluid engineering curricula to address talent scarcity. The region's manufacturing base supplies precision components to northern European chiller integrators.
Veneto
Padua and Verona host edge computing nodes serving logistics operators with distributed direct-expansion cooling systems. Lower land costs relative to Milan attract latency-sensitive capacity for e-commerce fulfillment networks. The Adriatic corridor positions facilities for submarine cable interconnection to Balkan and eastern Mediterranean markets.
Italy Data Center Cooling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational electrical engineering conglomerates commanding scale advantages in chiller manufacturing and service networks. Italian integrators compete through proximity maintenance relationships with Lombardy colocation providers. Strategic archetypes include full-stack infrastructure vendors, precision cooling specialists, and component-technology licensors. Competitive dynamics center on M&A for thermal management IP and geographic expansion into underserved southern markets.
Among European-headquartered electrical engineering groups, Schneider Electric SE and Vertiv Group Corp exemplify integrated infrastructure positions spanning power distribution through thermal management. German precision cooling specialist Stulz GmbH occupies a technical differentiation tier calibrated to high-density compute environments. These three anchors represent distinct competitive vectors: manufacturing scale, service network density, and application-specific engineering depth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Stulz GmbH |
| Rittal GMBH & Co KG |
| Johnson Controls International PLC |
| Asetek A/S |
| Hitachi Ltd |
| Mitsubishi Electric Hydronics & IT Cooling Systems S p A |
| Alfa Laval AB |
| Others |
Pricing and Supply Chain Analysis
CE marking requirements under the EU Energy Efficiency Directive gate both supplier qualification and price differentiation in Italian data center cooling procurement. Equipment vendors must absorb certification costs to access public sector tenders under PNRR digital infrastructure mandates, compressing margins on standard-tier products while enabling premium positioning for compliant high-efficiency systems.
Pricing Analysis
Milan metropolitan pricing for precision cooling equipment runs 15-20% above Turin and Bologna benchmarks due to hyperscale concentration and faster replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked high-efficiency chillers from legacy CRAC units and direct-expansion edge systems. Pricing pressure stems from F-Gas Regulation phase-down timelines that accelerate asset replacement before full depreciation. Colocation providers in Lombardy exhibit lowest price sensitivity due to uptime SLA penalties, while regional logistics operators building edge capacity in Veneto prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Inventory buffers for precision valves and compressor assemblies have compressed to 6-8 weeks as German component suppliers prioritize domestic hyperscale demand. Manufacturing concentration centers on Germany for precision cooling subsystems, Italy for integrated chiller assembly, and China for heat exchanger components. Copper and aluminum price volatility feeds directly into equipment quoting cycles, complicating long-term project contracting for mechanical integrators. Single-source vulnerability concentrates in electronic expansion valves and variable-frequency drive controllers sourced from Bavarian suppliers. Distribution runs through authorized integrator networks serving Lombardy and Lazio, with direct OEM relationships emerging for hyperscale cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators in Lombardy and Lazio, fragmenting procurement leverage for mid-tier colocation providers and enterprise operators. This consolidation among the largest demand nodes reshapes vendor negotiation dynamics across the Italian market.
For Market Incumbents: Secure long-term service contracting relationships with Milan-area colocation providers before liquid cooling specialists capture high-density retrofit demand. Deepen backward integration into refrigerant transition technologies to offset F-Gas Regulation compliance costs. Vertiv Group Corp and Schneider Electric SE already anchor domestic manufacturing footprints that enable faster response times than German competitors.
For New Entrants and Emerging Players: Anchor in southern Italy's latency arbitrage opportunity where submarine cable landing points in Sicily and Calabria intersect with underdeveloped cooling infrastructure. Target government agency procurement under PNRR digital infrastructure mandates, where ACN cybersecurity resilience standards create compliance-driven demand for redundant architectures. Partner with Emilia-Romagna research institutions to pilot immersion cooling for GPU-intensive scientific computing workloads.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid cooling subsystems as direct-to-chip and immersion technologies displace air-cooled legacy footprints. Acquisition targets should cluster around thermal-fluid engineering specialists with fluid chemistry expertise rather than traditional HVAC manufacturers. Monitor hyperscale capex allocation announcements as the primary signal for cooling infrastructure demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Investment | F-Gas Regulation compliance protects installed base value against stranded asset risk in Milan facilities. |
| Southern Italy Greenfield Development | Sicily and Calabria submarine cable landing points unlock latency-sensitive capacity at lower land costs. |
| Service Contracting Unbundling | Performance-guaranteed thermal management transfers operational risk from colocation providers to equipment vendors. |
| University Partnership Expansion | Bologna and Milan HVAC curricula address talent scarcity forcing recruitment from German labor markets. |
| Waste Heat Recovery Integration | District heating network interconnection converts cooling energy costs into revenue streams under municipal sustainability frameworks. |
Research Methodology
Operator-level perspectives from data center facility managers, mechanical engineering directors, procurement leads at colocation providers, and MIMIT infrastructure planners anchored the qualitative base. Primary interviews triangulated against secondary validation from EU Energy Efficiency Directive compliance databases, PNRR digital infrastructure allocation disclosures, F-Gas Regulation implementation reports, and hyperscaler capex filings. Bottom-up equipment shipment analysis and top-down infrastructure investment tracking converged on market sizing estimates.
Sensitivity analysis tested demand elasticity across cooling type, end user, and system type segmentations over the projection horizon. The analytical framework modeled rack density evolution, F-Gas Regulation phase-down timelines, and hyperscale facility construction pipelines as primary demand drivers. CAGRs derived from facility-level cooling capacity additions and replacement cycle compression rather than aggregate spending trends. Thermal efficiency standards under evolving EU AI Act infrastructure provisions served as scenario-weighting inputs.
Material uncertainties — commodity price volatility, cross-border logistics friction, and regulatory timeline acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about hyperscale expansion continuity and PNRR funding disbursement schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market