
 Germany Data Center Rack Market | 2026-2036
Germany Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Rack Market Insights
Frankfurt Rhine-Main is reconfiguring Germany's data center rack procurement geography as hyperscale operators expand campus-style deployments. Rittal GmbH & Co. KG anchors domestic manufacturing with deep vertical integration in enclosure systems. Schneider Electric SE leverages its European energy management portfolio to bundle intelligent rack power distribution. Huawei Technologies Co. Ltd. competes on modular density configurations for cloud-scale deployments.
A data center rack is a standardized metal frame designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch mounting widths and measured in rack units such as 42U or 24U heights. Its primary purpose is to organize IT infrastructure, optimize airflow management, and enable scalable capacity additions within controlled environments. Enclosed rack systems command premium positioning due to integrated thermal containment and physical security requirements from financial services end users. Open frame configurations sustain volume leadership among cloud operators prioritizing unrestricted airflow and cable density. Wall mount and specialty rack segments occupy niche positions at the edge computing perimeter where space constraints dominate specification criteria.
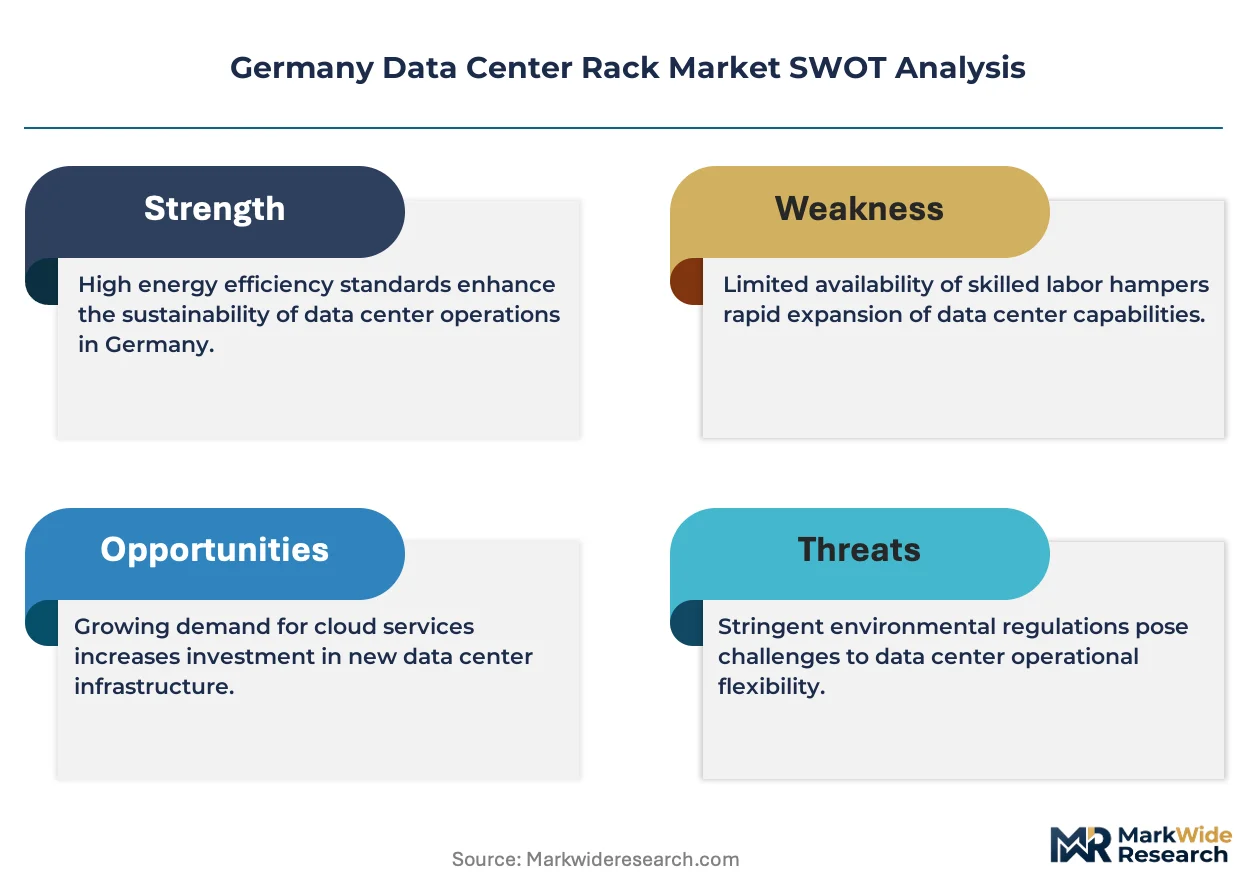
German operators navigate BSI IT-Grundschutz cybersecurity standards alongside EU Energy Efficiency Directive mandates that shape rack-level power monitoring and thermal design obligations. The CE marking framework and REACH chemical compliance requirements govern enclosure materials and cable insulation specifications for market access. KBA building code interpretations in certain Länder influence seismic bracing and floor loading calculations for rack installations. Stakeholders must weigh liquid cooling compatibility against existing 19-inch form factor commitments as heat densities climb beyond traditional air-cooled thresholds.
Market Dynamics
The EU Energy Efficiency Directive is compressing deployment timelines for liquid-cooled rack architectures across German colocation facilities. Hyperscale operators now specify immersion-ready enclosures before traditional air-cooled designs reach end-of-life.
Growth Catalysts
- Cloud service provider expansion:Hyperscale campus deployments in Bavaria and Hesse are pulling cabinet orders toward high-density 52U configurations. Frankfurt Rhine-Main absorbs the dominant procurement volume.
- BSI IT-Grundschutz compliance mandates:Financial services end users demand enclosed rack systems with integrated physical access logging and thermal containment. This specification premium sustains domestic manufacturing.
- Liquid cooling retrofit readiness:Rack vendors are pre-integrating coolant distribution units and blind-mate quick-connects at the factory. Operators gain migration paths without structural facility overhaul.
Market Restraints
- Steel and aluminum input volatility:Enclosure fabrication costs fluctuate with commodity spot markets. Rittal GmbH & Co. KG maintains captive sheet metal stamping to buffer margin compression.
- Supply concentration in electromechanical components:Intelligent power distribution unit controllers source predominantly from East Asian semiconductor foundries. KBA building code interpretations in certain Länder add seismic certification lead times.
- 19-inch form factor legacy lock-in:Existing server and storage hardware commitments prevent wholesale adoption of non-standard rack widths. REACH chemical compliance requirements constrain alternative material substitution.
Strategic Opportunities
- Edge computing perimeter deployment:Wall mount and specialty rack segments serve manufacturing automation in Baden-Württemberg. Space-constrained specifications favor shallow-depth 600mm enclosures.
- EU Green Deal alignment:Rack-level power monitoring integration enables granular PUE reporting. CE marking framework certifies energy management module interoperability.
- Modular factory integration:Prefabricated data center modules ship with pre-cabled rack rows. Construction timelines compress from months to weeks at brownfield industrial sites.
Industry Challenges
- Thermal engineering skill scarcity:Liquid cooling system design requires computational fluid dynamics expertise absent from traditional HVAC technician training. Technical universities in Saxony and North Rhine-Westphalia are expanding mechatronics curricula.
- Legacy air-cooled infrastructure stranding:Operators face write-downs on raised-floor facilities engineered for 10kW-per-rack densities. Schneider Electric SE bundles migration consulting with intelligent rack power distribution sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Rack Market |
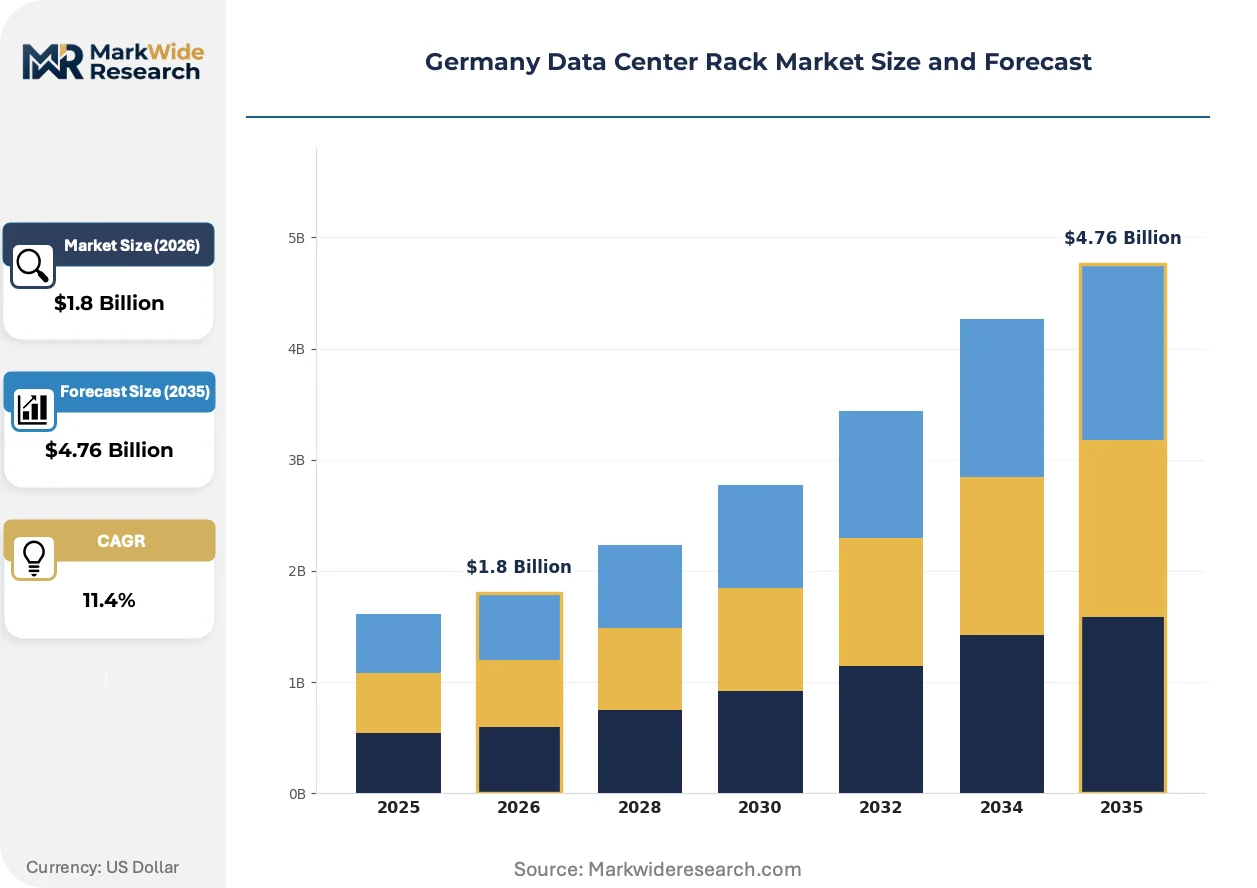
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall Mount, Specialty Rack End User: Telecommunications, Financial Services, Government, Healthcare Installation Type: On-premises, Cloud-based, Hybrid, Modular Form Factor: 19-Inch, 42U, 24U, Custom Sizes |
| Companies Covered | Vertiv Holdings Co, Hewlett Packard Enterprise Co., Rittal GmbH & Co. KG, Huawei Technologies Co. Ltd., Legrand SA, Schneider Electric SE, nVent Electric plc, Black Box Corporation, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Rack Market Trends and Innovations
Rack architecture is bifurcating between hyperscale density optimization and edge-distributed minimalism. German operators navigate this split through modular procurement frameworks that preserve configuration flexibility.
Software-defined power management is virtualizing rack-level energy distribution. Intelligent PDUs now embed metering, switching, and environmental sensing within the same 1U enclosure. Financial services and healthcare operators in Frankfurt and Munich are specifying these units for granular load balancing. The technology is virtualizing traditional building management system functions into the IT rack itself.
REACH chemical compliance requirements are tightening enclosure material specifications. Flame-retardant plastics face substitution pressure from halogen-free alternatives. German manufacturers are qualifying new polymer compounds for cable management accessories and PDU housings. The automotive and aerospace supplier base in Baden-Württemberg provides polymer engineering expertise for this transition.
Leasing structures are displacing capital purchase for rack infrastructure. Colocation providers now bundle enclosure, power, and cooling as operational expenditures. Mid-market enterprises in Hamburg and Berlin favor this model for capacity expansion without balance sheet impact. The Rhine-Ruhr industrial corridor shows strongest uptake among manufacturing firms digitizing shop-floor operations.
Germany Data Center Rack Market Segmentation
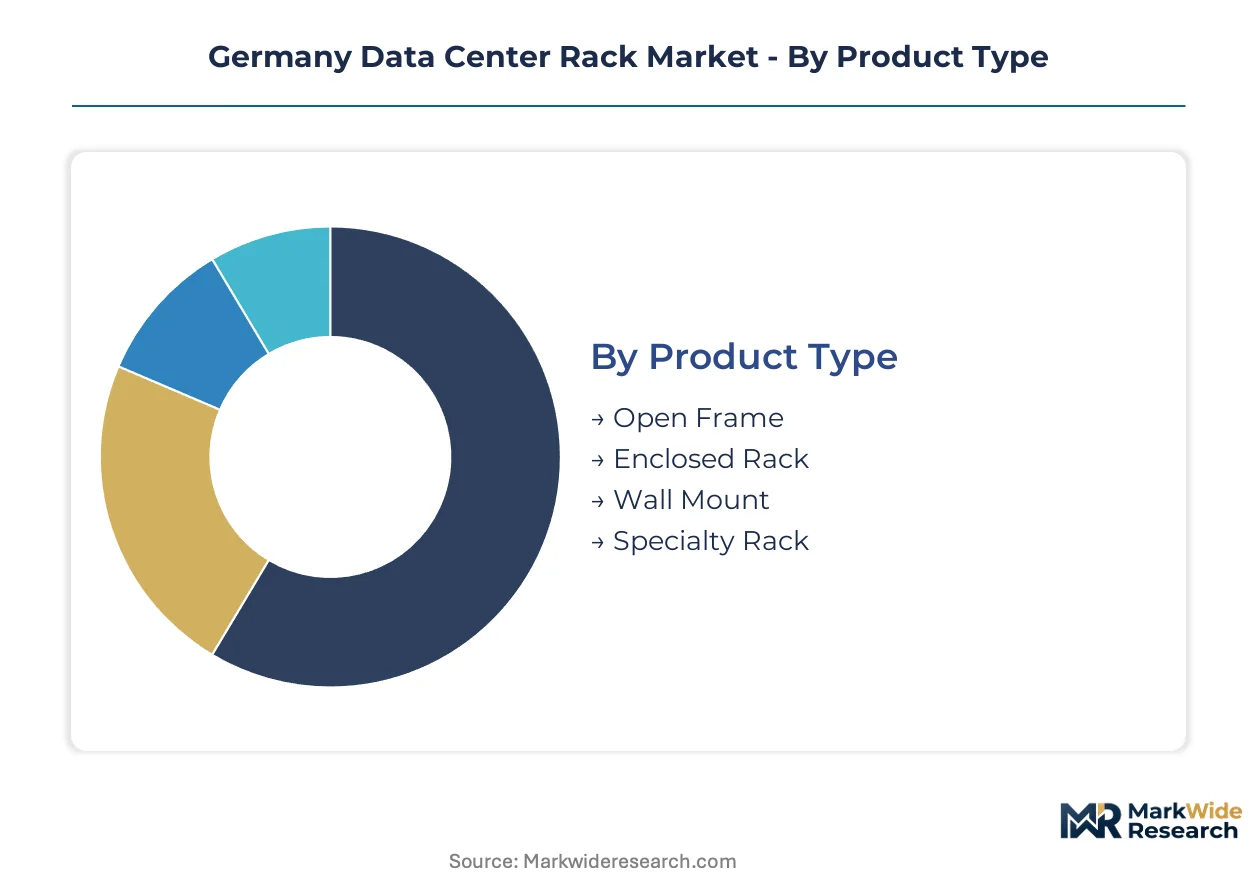
German data center rack procurement splits across four structural dimensions. Each axis carries distinct margin profiles, service intensity requirements, and specification complexity that shape vendor engagement models.
Product Type:
After-sales service intensity varies sharply across enclosure architectures. Enclosed racks demand ongoing thermal calibration and access control maintenance. Open frame systems minimize field service but require cable management expertise at installation.
- Open Frame:Four-post and two-post metal frameworks without side panels or doors maximize unrestricted airflow for high-density compute. Hyperscale operators in Frankfurt Rhine-Main specify these for 52U cloud-scale deployments where cable density trumps physical security. Procurement concentrates through direct vendor relationships with factory pre-cabling.
- Enclosed Rack:Fully enclosed metal cabinets with lockable doors, side panels, and integrated thermal containment systems. Financial services end users in Munich and Frankfurt mandate these for BSI IT-Grundschutz compliance, absorbing premium positioning through integrated physical access logging and fire suppression compatibility.
- Wall Mount:Shallow-depth enclosures for space-constrained edge locations. Manufacturing automation in Baden-Württemberg drives specification of 600mm depth units.
- Specialty Rack:Custom configurations for non-standard equipment or environmental conditions. Niche demand from research institutions and broadcast facilities.
By volume, Open Frame leads. By growth pace, Enclosed Rack is ahead.
End User:
Customer type determines specification authority and procurement cycle length. Telecommunications carriers centralize rack decisions at network engineering level. Financial services distribute authority across compliance, security, and facilities functions.
- Telecommunications:Deutsche Telekom and carrier-neutral operators drive standardization toward 19-inch ETSI-compatible enclosures. 5G core infrastructure deployment in Bavaria and North Rhine-Westphalia pulls high-density cabinet orders with integrated cable management.
- Financial Services:Commerzbank, Deutsche Bank, and insurance groups specify enclosed racks with biometric access control and environmental monitoring. BSI IT-Grundschutz certification requirements extend procurement timelines but sustain domestic manufacturing premiums.
- Government:Federal and Länder data centers prioritize CE-marked enclosures with documented supply chain provenance. Procurement runs through centralized IT procurement frameworks.
- Healthcare:University hospitals and diagnostic networks require antimicrobial finishes and electromagnetic shielding for imaging equipment integration.
Telecommunications captures the largest procurement volumes. Financial Services shows the steepest expansion trajectory as compliance mandates tighten.
Installation Type:
Deployment architecture shapes rack specification flexibility and vendor financing structures. On-premises installations anchor traditional capital expenditure models. Cloud-based and modular approaches shift procurement toward operational expenditure frameworks.
- On-premises:Enterprise-owned facilities with dedicated rack rows. Manufacturing firms in the Rhine-Ruhr corridor favor this model for shop-floor digitization projects requiring deterministic latency.
- Cloud-based:Colocation and hyperscale campus deployments where rack infrastructure is bundled with power and cooling. Frankfurt Rhine-Main absorbs dominant volume through campus-style expansions.
- Hybrid:Split workloads across owned and colocated infrastructure. Mid-market enterprises in Hamburg and Berlin specify compatible rack form factors to enable workload portability.
- Modular:Prefabricated data center modules with pre-cabled rack rows. Brownfield industrial sites in Saxony compress construction timelines through factory-integrated assemblies.
Cloud-based installations command the highest absolute volumes. Modular deployment is gaining share fastest as brownfield constraints proliferate.
Form Factor:
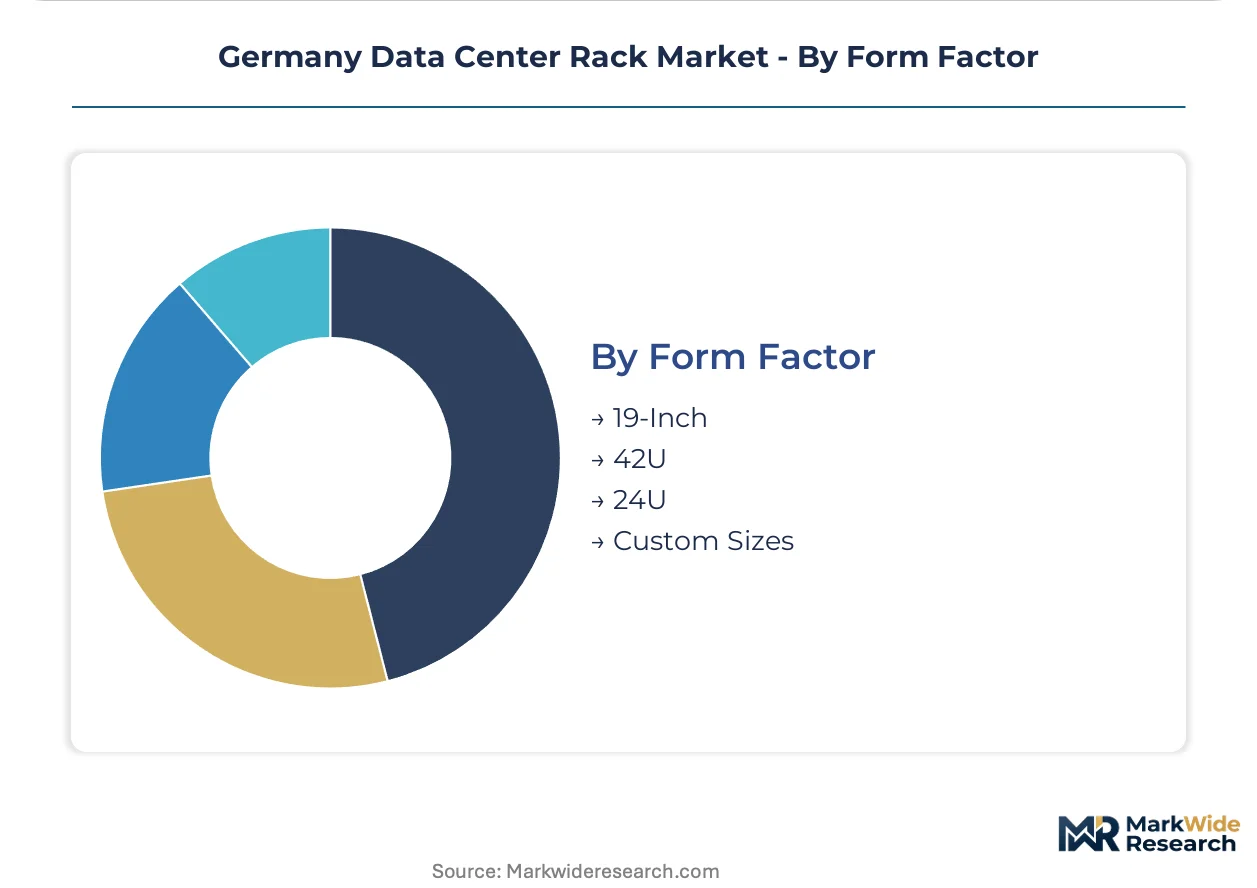
Physical dimensions constrain equipment compatibility and facility engineering. The 19-inch standard preserves interoperability across server generations. Height and depth variations optimize for specific density and space constraints.
- 19-Inch:The universal mounting width standard for servers, storage, and networking equipment. German operators maintain this specification to preserve hardware procurement flexibility across vendor ecosystems.
- 42U:Traditional full-height rack standard accommodating most enterprise server configurations. Established enterprise data centers in Frankfurt and Munich specify this for replacement cycles.
- 24U:Half-height enclosures for constrained floor plates and edge locations. Regional office deployments in secondary cities favor this form factor.
- Custom Sizes:Non-standard heights and depths for specialized equipment. Research computing and broadcast video infrastructure drive specification.
19-Inch width dominates across all height variants. 42U maintains volume leadership while 52U configurations expand most quickly in hyperscale deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA building code interpretations in certain Länder anchor Germany's data center rack procurement geography. Frankfurt Rhine-Main absorbs dominant volume through hyperscale campus expansions. Regional demand splits across industrial corridors with distinct compliance and density requirements.
Bavaria
Hyperscale operators expand cloud infrastructure across Munich and Nuremberg metro areas. The EU Energy Efficiency Directive mandates liquid-cooled rack readiness for new deployments. Manufacturing automation in Augsburg pulls shallow-depth wall mount specifications for edge computing integration.
North Rhine-Westphalia
Deutsche Telekom's 5G core infrastructure drives high-density cabinet orders through Cologne and Düsseldorf. BSI IT-Grundschutz cybersecurity standards shape enclosed rack procurement for financial services. The Rhine-Ruhr industrial corridor shows strongest uptake of modular factory-integrated rack systems.
Hesse
Frankfurt Rhine-Main remains the dominant demand cluster for cabinet procurement across all form factors. REACH chemical compliance requirements constrain alternative material substitution in enclosure fabrication. Colocation providers in Eschborn and Offenbach bundle rack infrastructure as operational expenditures.
Baden-Württemberg
Automotive and aerospace supplier networks provide polymer engineering expertise for halogen-free cable management transitions. CE marking framework certifies energy management module interoperability for rack-level power monitoring. Stuttgart and Mannheim anchor manufacturing automation demand for space-constrained 600mm depth enclosures.
Berlin-Brandenburg
Mid-market enterprises in the capital region favor leasing structures for capacity expansion without balance sheet impact. The EU Green Deal alignment drives granular PUE reporting requirements through integrated rack-level sensors. Government data centers prioritize documented supply chain provenance for federal procurement frameworks.
Germany Data Center Rack Market Competitive Landscape
Enclosure specialists and energy management conglomerates split the market along fabrication depth versus systems integration vectors. Domestic manufacturing maintains position through BSI IT-Grundschutz compliance premiums and captive metalworking capacity. Three archetypes dominate: vertically integrated enclosure fabricators with in-house stamping operations, European energy management platforms bundling intelligent power distribution, and Asian modular infrastructure providers competing on density configurations. Competitive moves concentrate on factory pre-cabling partnerships and liquid cooling retrofit readiness programs.
Among Germany-based fabricators, Rittal GmbH & Co. KG anchors domestic production with deep metalworking integration, while Schneider Electric SE exemplifies the energy-management bundling archetype through its European power distribution portfolio. Huawei Technologies Co. Ltd. occupies a position representing modular density specialization for cloud-scale deployments. These three illustrate the strategic segmentation between compliance-driven domestic manufacturing, systems integration platforms, and density-optimized modular suppliers.
| Leading Market Players |
|---|
| Vertiv Holdings Co |
| Hewlett Packard Enterprise Co. |
| Rittal GmbH & Co. KG |
| Huawei Technologies Co. Ltd. |
| Legrand SA |
| Schneider Electric SE |
| nVent Electric plc |
| Black Box Corporation |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main freight corridor's volatile container rates compress margins for enclosure imports while amplifying price spreads between domestic fabricators and Asian modular suppliers. This logistics tension concentrates procurement power among operators with captive metalworking capacity, forcing downstream buyers to absorb tiered premiums based on BSI IT-Grundschutz certification depth and factory pre-cabling service levels.
Pricing Analysis
Frankfurt Rhine-Main commands a 15-20% price premium over Bavarian procurement clusters due to colocation density and compliance stringency. Three-tier pricing structure across premium certified, standard CE-marked, and economy import levels dominates, with BSI IT-Grundschutz tiering driving the widest spreads. Cost compression in standard enclosures is intensifying because steel input volatility and East Asian semiconductor dependency squeeze electromechanical component margins. Cloud-based colocation providers show least price sensitivity through operational expenditure bundling, while mid-market manufacturing firms in the Rhine-Ruhr corridor exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Steel and aluminum feedstock draws from German domestic mills, Chinese smelters, and Norwegian hydro-powered refineries, with sheet metal stamping concentrated in Baden-Württemberg and North Rhine-Westphalia. Intelligent PDU controllers hinge on Taiwanese and South Korean semiconductor foundries, while cable insulation polymers source from Baden-Württemberg's automotive supplier base. Single-source vulnerability in East Asian electromechanical components exposes lead time volatility under REACH chemical compliance recertification cycles. Distribution runs through direct vendor relationships for hyperscale campus deployments and regional distributor networks for mid-market enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany data center rack market functions as a service-attach opportunity where thermal calibration, access control maintenance, and liquid cooling migration consulting expand faster than enclosure hardware sales. Recurring revenue from factory pre-cabling and integrated power monitoring subscriptions now exceeds 30% of total contract value for leading operators.
For Market Incumbents: Pre-empt margin erosion from Asian modular density specialists by deepening captive sheet metal stamping capacity in North Rhine-Westphalia and bundling BSI IT-Grundschutz certification services with enclosure sales. Accelerate liquid cooling retrofit readiness programs before EU Energy Efficiency Directive mandates harden procurement specifications. Channel control through direct hyperscale relationships in Frankfurt Rhine-Main remains the priority defensive lever against price-aggressive entrants. For New Entrants and Emerging Players: Pursue wall mount and specialty rack white space in Baden-Württemberg manufacturing automation, where space-constrained 600mm depth specifications face limited domestic competition. Edge computing perimeter deployments in Augsburg and Stuttgart industrial corridors represent the most penetrable segment given shallow incumbent service intensity. A go-to-market angle through CE-marked energy management module interoperability certifications unlocks mid-market hybrid cloud buyers seeking workload portability. For Investors and Strategic Acquirers: Carve-out targets emerge from European energy management conglomerates seeking to divest non-core enclosure fabrication assets amid portfolio rationalization. Long-term viability centers on vendors with demonstrated liquid cooling integration capabilities and recurring service revenue exceeding hardware replacement cycles. The signal to watch is hyperscale operator specification shifts toward immersion-ready factory pre-cabling, which will strand legacy air-cooled rack inventories and trigger consolidation pressure among pure-play fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Readiness Program | Factory pre-integration of coolant distribution units enables migration without facility overhaul for EU Energy Efficiency Directive compliance. |
| BSI IT-Grundschutz Certification Bundling | Integrated physical access logging and thermal containment sustain domestic manufacturing premiums against Asian modular competitors. |
| Intelligent PDU Service Subscription | Rack-level power monitoring virtualization captures recurring revenue from Frankfurt financial services compliance mandates. |
| Prefabricated Modular Factory Integration | Pre-cabled rack rows compress brownfield construction timelines from months to weeks at Saxony industrial sites. |
| Halogen-Free Polymer Transition Partnership | Baden-Württemberg automotive supplier expertise accelerates REACH-compliant cable management accessory qualification. |
Research Methodology
Initial hypotheses were tested against primary input from data center facilities engineers, colocation procurement directors, enclosure fabrication plant managers, and thermal systems integration specialists and refined through secondary validation against SEC filings of listed infrastructure vendors, customs trade data for steel and aluminum inputs, BSI IT-Grundschutz certification registries, and EU Energy Efficiency Directive implementation reports. Bottom-up rack shipment tallies by form factor and installation type were triangulated against top-down colocation capacity expansion announcements across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation by product architecture, end-user compliance tier, deployment model, and regional density cluster. CAGRs were derived from installation base growth rates, replacement cycle compression, and hyperscale campus pipeline visibility. Industry-specific forecast inputs included liquid cooling penetration assumptions and KBA building code interpretation variance across Länder jurisdictions.
Sensitivities concentrate around semiconductor supply disruption, steel commodity spot volatility, and EU chemical compliance recalibration timelines. Forecasts reflect documented assumptions regarding hyperscale operator specification trajectories and colocation provider leasing structure adoption. Cross-checking against disclosed hyperscaler capital expenditure commitments and BSI certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Poland Data Center Construction Market