
 Saudi Arabia Data Center Physical Security Market | 2026-2036
Saudi Arabia Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Physical Security Market Insights
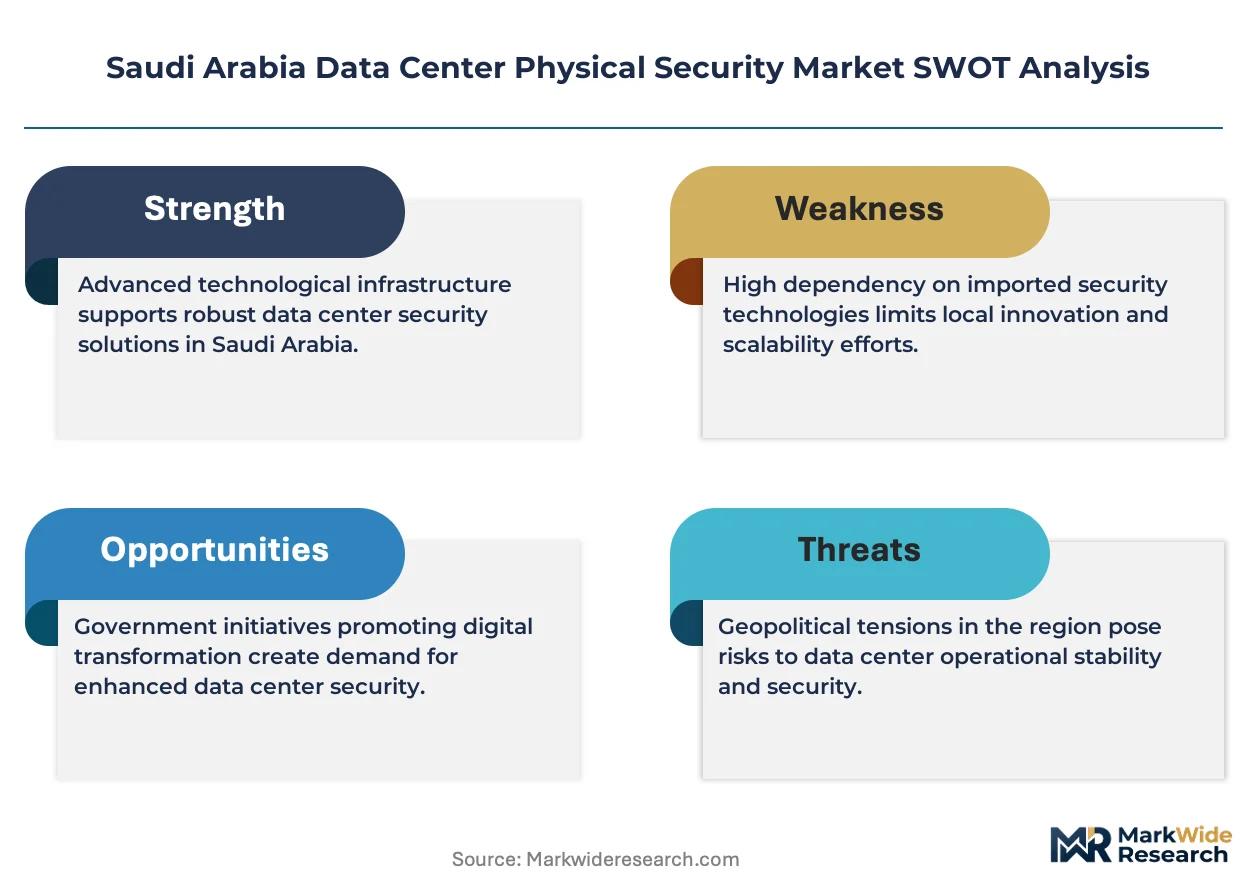
SFDA facility integrity standards for pharmaceutical-grade data hosting is decoupling legacy security architectures from new-build specifications. Honeywell International Inc. leverages its building automation heritage to anchor integrated fire-protection and access-control bundles. Bosch Sicherheitssysteme GmbH competes through video analytics specialization calibrated for Middle Eastern climate conditions.
Saudi Arabia data center physical security encompasses perimeter barriers, biometric access control, surveillance infrastructure, and fire suppression systems engineered to NCA Tier III and Tier IV resilience standards with 99.982% uptime protection. These systems safeguard mission-critical compute environments against unauthorized entry, environmental failure, and deliberate intrusion. Access control systems and biometric systems capture disproportionate capital allocation as giga-project operators specify multi-factor authentication for all personnel zones. Surveillance cameras integrated with video analytics represent the fastest-expanding technology pairing as operators demand real-time anomaly detection across unmanned perimeter stretches.
NCA cybersecurity mandates, MOHAP facility certification protocols, and SASO technical regulations collectively dictate minimum physical security thresholds for operational licensing. Compliance timelines compress as new data center construction accelerates under Vision 2030 targets. Stakeholders must monitor evolving NCA guidance on critical infrastructure protection as classification criteria expand beyond financial and government sectors into healthcare and energy data custodians.
Market Dynamics
Vision 2030 giga-project execution is compressing procurement timelines for Tier III and Tier IV physical security infrastructure, forcing integrators to pre-certify bundled solutions before construction mobilization begins.
Growth Catalysts
- NEOM and Red Sea Project Data Zones:Government-backed developments mandate NCA-compliant security architectures from groundbreaking, creating captive demand for perimeter hardening and biometric access systems.
- SFDA Pharmaceutical Data Hosting Rules:Cold-chain integrity requirements for vaccine and biologics storage are expanding climate-controlled data center construction with specialized fire suppression and access logging.
- Multi-factor Authentication Mandates:NCA critical infrastructure classifications now require biometric-plus-credential verification for all personnel zones in Tier III facilities and above.
Market Restraints
- Specialized Engineering Talent Scarcity:Saudi Arabia's domestic workforce lacks sufficient NCA-certified security systems engineers, forcing reliance on expatriate labor with extended mobilization lead times.
- Imported Component Concentration:Biometric sensors and video analytics processors originate predominantly from East Asian manufacturing hubs, exposing projects to shipping volatility and customs clearance delays.
- Legacy Facility Retrofit Complexity:Pre-2020 data centers in Riyadh and Jeddah face structural limitations integrating modern perimeter barriers without compromising existing cooling and power distribution layouts.
Strategic Opportunities
- Eastern Province Industrial Corridor:Aramco and SABIC digital transformation initiatives are generating demand for edge data centers with hardened physical security in Jubail and Dammam.
- AI-Video Analytics Convergence:Machine learning-enabled anomaly detection layered onto thermal imaging cameras addresses Middle Eastern climate challenges of dust, heat, and low-light perimeter monitoring.
- SASO Pre-Certification Pathways:Streamlined technical regulation compliance processes are enabling faster market entry for integrated fire-access-surveillance bundles.
Industry Challenges
- NCA Tier Certification Backlogs:Accreditation body capacity constraints are extending facility commissioning timelines, delaying revenue recognition for operators and integrators.
- Interoperability with Legacy Access Control:Migration from card-based systems to biometric platforms requires phased credential transitions that complicate security zone management during construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Physical Security Market |
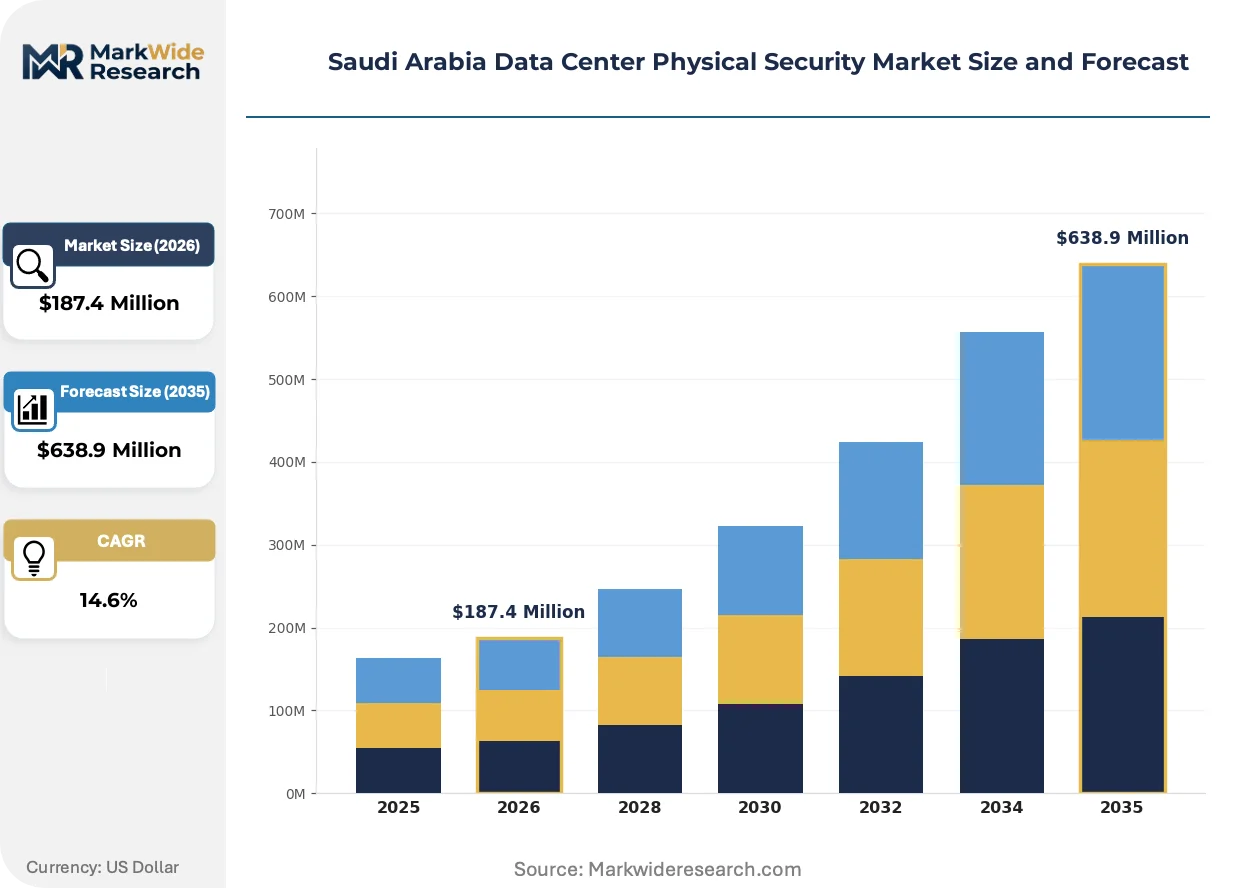
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control Systems, Surveillance Cameras, Intrusion Detection Systems, Fire Protection Systems Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Telecommunications, Government, BFSI, IT & Services Technology: Biometric Systems, Video Analytics, RFID, IoT Solutions |
| Companies Covered | Securitas Technology, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Siemens AG, Johnson Controls International, Schneider Electric SE, LenelS2, Convergint Technologies LLC, Ctelecoms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Physical Security Market Trends and Innovations
Physical security architecture is converging with building automation and IT infrastructure management, collapsing procurement silos that previously separated fire, access, and surveillance systems into distinct vendor relationships.
Edge-deployed video analytics is decentralizing surveillance decision-making from centralized security operations centers to camera-mounted processors. Hyperscale operators in Riyadh are specifying on-device inference engines that trigger perimeter alerts without network latency to cloud or on-premise servers. This architecture compresses response times for unmanned facility stretches while reducing backbone bandwidth consumption.
NCA cybersecurity mandates are tightening physical-logical security integration requirements for critical infrastructure classification. Facility operators must now demonstrate biometric access logs feed directly into SIEM platforms with tamper-evident audit trails. Healthcare data custodians under MOHAP jurisdiction face the steepest compliance ramps as pharmaceutical-grade hosting specifications expand.
Consolidated procurement of integrated security bundles is displacing point-solution purchasing across giga-project developments. NEOM and Red Sea Project developers are issuing single-source contracts for fire suppression, access control, and video surveillance to reduce vendor coordination overhead. This pattern concentrates specification influence with building automation heritage providers who can credential unified system performance guarantees.
Saudi Arabia Data Center Physical Security Market Segmentation
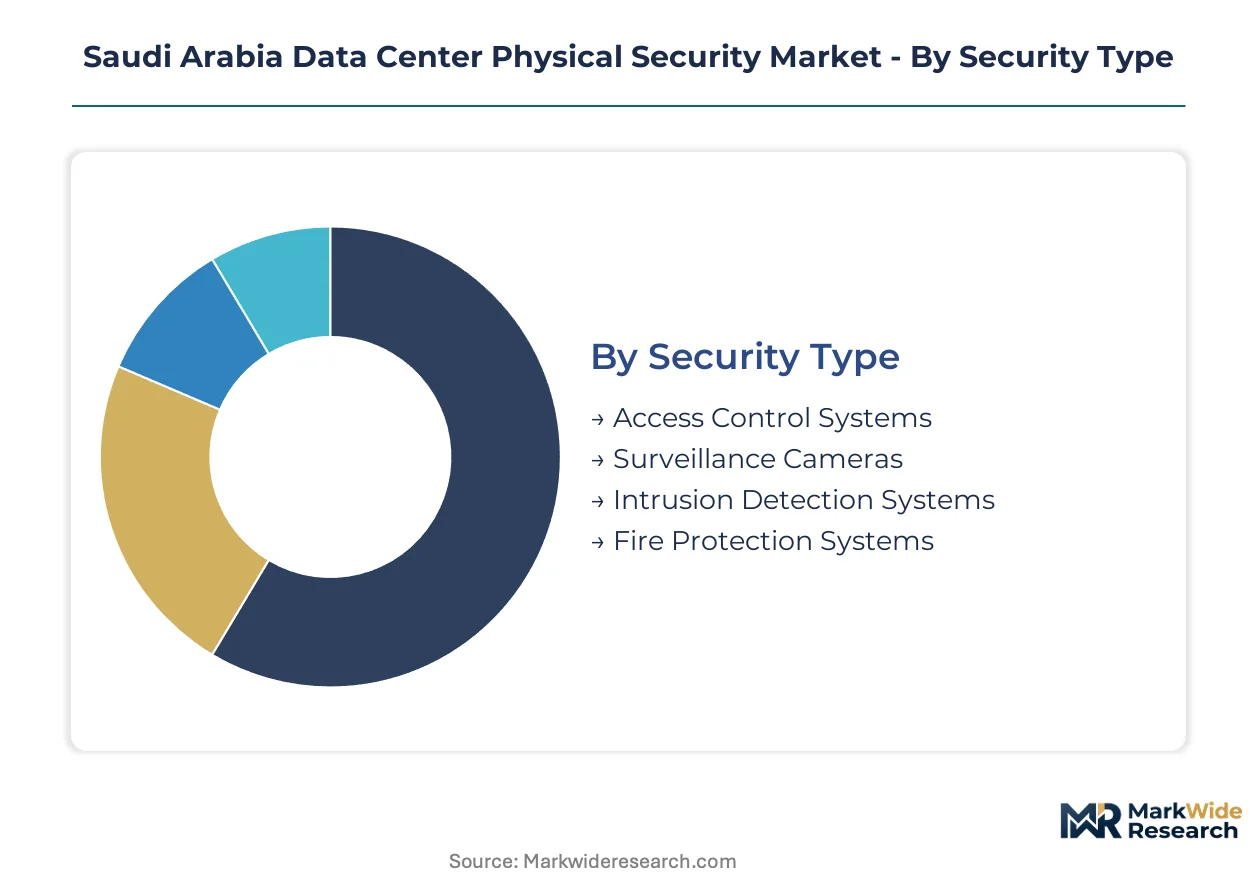
Physical security procurement in Saudi data centers fragments across technology maturity tiers and integration architectures. Understanding which segments operate as standalone purchases versus embedded bundles clarifies vendor positioning and margin capture.
Security Type:
Integration depth varies sharply—fire suppression and access control anchor unified building automation platforms, while surveillance and intrusion detection often deploy as point solutions.
- Access Control Systems:Multi-factor biometric platforms with NCA Tier III credential requirements dominate new giga-project specifications. Riyadh corridor developments mandate palm-vein and facial recognition for all personnel zones, compressing procurement timelines for integrators.
- Surveillance Cameras:Thermal and visible-spectrum devices with edge-deployed video analytics processors. NEOM and Red Sea Project data zones specify on-device inference engines to eliminate network latency for unmanned perimeter stretches.
- Intrusion Detection Systems:Perimeter sensors and volumetric detectors calibrated for Middle Eastern dust and heat conditions. Typically procured separately from access control in legacy facility retrofits.
- Fire Protection Systems:Clean-agent suppression with very early smoke detection apparatus. Integrated into building automation heritage platforms with unified commissioning guarantees.
Volume placements concentrate in Access Control Systems; the faster expansion belongs to Surveillance Cameras.
Deployment Model:
Cost tiering separates capital-intensive on-premises builds from operational-expense cloud security platforms, with hybrid architectures capturing giga-project phased rollouts.
- On-Premises:Dedicated security infrastructure with local SIEM integration and tamper-evident audit trails. Government and BFSI data centers mandate on-premises architectures for NCA critical infrastructure classification.
- Cloud-Based:Centralized security-as-a-service with subscription licensing. Smaller edge facilities in Jubail and Dammam adopt cloud-based video management to reduce capital burden.
- Hybrid:Edge analytics with cloud backup and centralized policy management. Red Sea Project developers specify hybrid models for phased facility commissioning.
- Mobile:Portable credentialing and temporary perimeter monitoring for construction-phase security. Limited to pre-operational giga-project stages.
Capital deployment favors On-Premises; Hybrid architectures gain share fastest in new construction pipelines.
End User:
Customer type determines compliance stringency—government-backed giga-projects set specifications that cascade to private sector procurement.
- Telecommunications:Hyperscale cloud operators expanding Riyadh and Jeddah footprints. STC and Mobily drive demand for NCA Tier IV resilience with 99.982% uptime protection.
- Government:Vision 2030 giga-projects and sovereign data centers with mandatory NCA compliance from groundbreaking. NEOM and Red Sea Project developments issue single-source security bundles.
- BFSI:SAMA-regulated financial institutions with dual physical-logical security mandates. Biometric-plus-credential verification required for all personnel zones.
- IT & Services:Colocation operators and managed service providers serving pharmaceutical and energy sector clients. SFDA and Aramco specifications increasingly dictate procurement.
Government verticals anchor current volume; BFSI requirements are climbing the fastest as SAMA tightens critical infrastructure classifications.
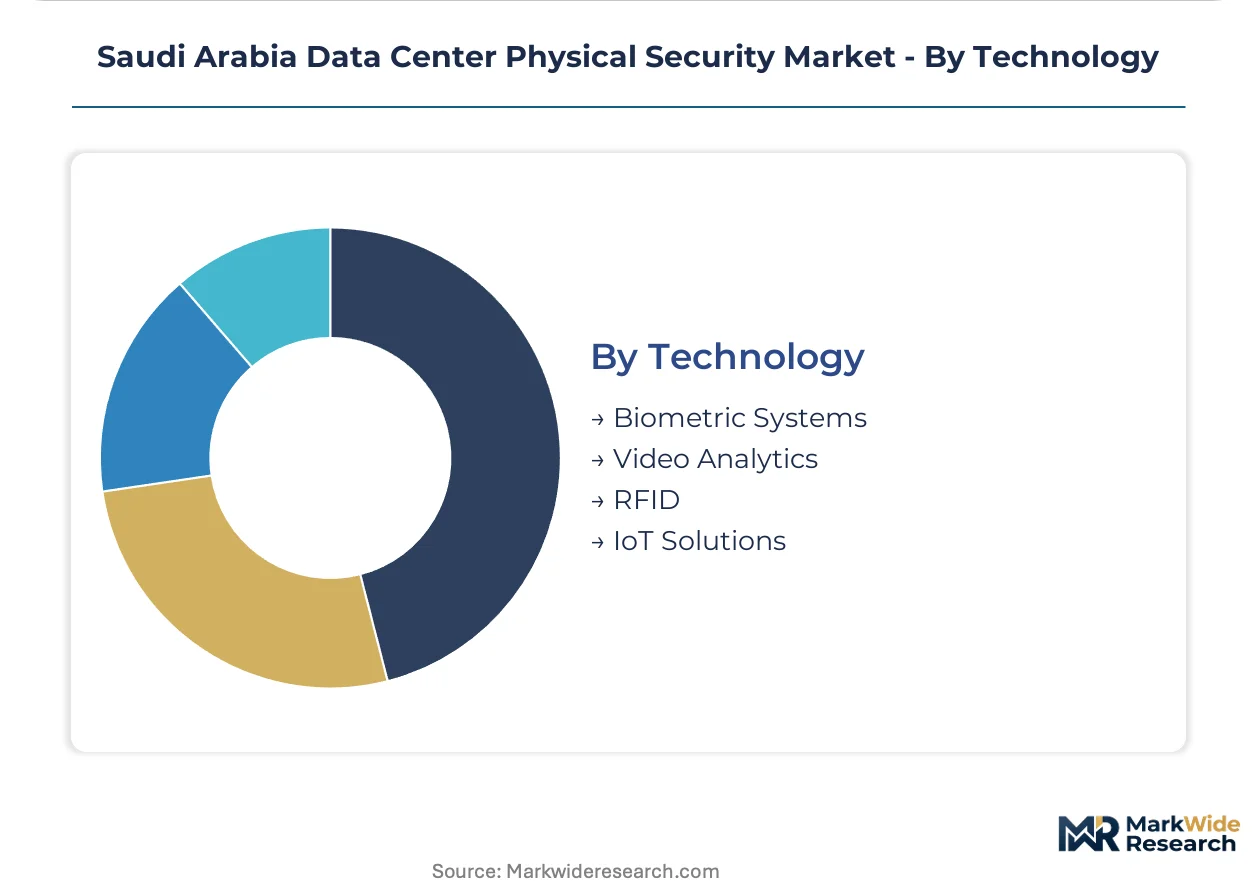
Technology:
Maturity curves separate proven biometric deployments from emerging IoT convergence plays.
- Biometric Systems:Palm-vein, facial recognition, and iris scanning platforms with liveness detection. NCA mandates now require biometric-plus-credential verification for Tier III facilities and above.
- Video Analytics:Machine learning-enabled anomaly detection layered onto thermal imaging. Addresses Middle Eastern climate challenges of dust, heat, and low-light perimeter monitoring.
- RFID:Legacy credentialing systems in transition to biometric platforms. Card-based access persists in pre-2020 Riyadh and Jeddah facilities facing retrofit complexity.
- IoT Solutions:Sensor fusion platforms integrating environmental monitoring with security events. Emerging specification in pharmaceutical-grade data centers under SFDA jurisdiction.
Biometric Systems capture dominant placement; Video Analytics shows the steepest expansion trajectory as edge AI processors penetrate new builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for physical security systems concentrates in East Asian manufacturing hubs, while consumption clusters in Riyadh and Jeddah where hyperscale data center construction accelerates under Vision 2030 targets.
Riyadh Metro Corridor
Government-backed giga-projects including NEOM and Qiddiya generate concentrated demand for NCA Tier IV physical security infrastructure. The National Cybersecurity Authority mandates biometric-plus-credential verification from groundbreaking for all critical data facilities. STC and Mobily hyperscale expansions in Riyadh anchor procurement volumes for integrated fire-access-surveillance bundles.
Eastern Province
Aramco and SABIC digital transformation initiatives drive edge data center construction requiring hardened perimeter security in Jubail and Dammam. The Saudi Food and Drug Authority extends pharmaceutical-grade hosting specifications to energy sector digital infrastructure. Industrial corridor developments specify climate-calibrated video analytics for dust and heat conditions.
Western Region
Jeddah data center clusters serve Red Sea Project logistics and pilgrimage-related digital services with MOHAP-certified facility requirements. The Saudi Standards, Metrology and Quality Organization tightens technical regulations for imported biometric components entering through King Abdulaziz Port. Legacy facility retrofits face structural constraints integrating modern perimeter barriers.
NEOM Northwest
Tabuk Province hosts the flagship cognitive city development with mandatory NCA compliance from initial infrastructure deployment. Single-source security procurement bundles reduce vendor coordination overhead for linear city construction phases. Edge-deployed video analytics with on-device inference engines eliminate network latency across unmanned facility stretches.
Saudi Arabia Data Center Physical Security Market Competitive Landscape
The competitive structure tilts toward building automation heritage providers with unified commissioning capabilities. Market concentration favors integrators capable of pre-certifying bundled fire-access-surveillance solutions before construction mobilization. Three archetypes dominate: multinational conglomerates with Middle Eastern regional offices, specialized security technology vendors with video analytics specialization, and local system integrators with NCA certification relationships. M&A activity targets biometric platform capabilities, while strategic partnerships focus on SASO pre-certification pathways.
Within the multinational conglomerate tier, Honeywell International Inc. and Bosch Sicherheitssysteme GmbH exemplify building automation heritage positioning. Siemens AG occupies a position spanning electrical infrastructure and security integration. Among regional specialists, Securitas Technology and Convergint Technologies LLC represent service-led deployment models. Schneider Electric SE anchors the critical power and cooling convergence vector. These players collectively illustrate how procurement consolidation toward bundled solutions favors vendors with unified system performance guarantees.
| Leading Market Players |
|---|
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Siemens AG |
| Johnson Controls International |
| Schneider Electric SE |
| LenelS2 |
| Convergint Technologies LLC |
| Ctelecoms |
| Others |
Pricing and Supply Chain Analysis
NCA-certified security systems engineers concentrated in Riyadh and Jeddah command wage premiums that compress integrator margins and widen spreads between Tier III and Tier IV installation pricing tiers. Labor-cost differentials between domestic certification holders and expatriate mobilization timelines translate directly into project-based quotation bands that separate premium bundled solutions from economy point-product procurement.
Pricing Analysis
Margin tightening in economy-tier access control reflects expatriate engineer mobilization delays and customs clearance volatility for biometric sensors. Project-based pricing dominates, with three-tier pricing structure across premium, standard, and economy levels differentiated by NCA Tier certification grade and after-sales service bundling. Cost compression in standard-tier surveillance accelerates as East Asian manufacturers expand thermal camera volumes. Government-backed giga-projects show least price sensitivity; smaller Jubail edge facilities exhibit highest.
Supply Chain Analysis
Workforce availability constraints in Chinese and South Korean manufacturing hubs extend lead times for edge AI processors and biometric sensors. Component supply draws from specialized fabs in Taiwan, clean-agent suppression chemical production in Germany, and steel perimeter barrier fabrication in Turkey. Single-source vulnerability concentrates in advanced video analytics chipsets. Distribution runs through Jeddah's King Abdulaziz Port customs clearance, with Riyadh corridor serving as final-mile logistics hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained NCA certification capacity props pricing power for pre-certified integrators, compressing procurement timelines for bundled fire-access-surveillance solutions.
For Market Incumbents: Extend SASO pre-certification pathways to lock specification influence before construction mobilization begins. Deepen relationships with building automation heritage platforms to defend against specialized video analytics vendors. Prioritize biometric platform capability investment as NCA Tier III mandates harden multi-factor authentication requirements. For New Entrants and Emerging Players: Cloud-based security-as-a-service channels offer lowest barrier-to-entry for Jubail and Dammam edge facility operators seeking reduced capital burden. Target pharmaceutical-grade data hosting under SFDA jurisdiction, where climate-controlled specifications create specialized procurement windows. Pursue partnership routes with local system integrators holding existing NCA certification relationships. For Investors and Strategic Acquirers: The window for entry favors building automation heritage providers with unified commissioning capabilities and regional office infrastructure. Long-term viability centers on consolidation plays capturing biometric platform technology and SASO pre-certification assets. Watch NCA critical infrastructure classification expansion beyond financial and government sectors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Acquisition | Captures NCA Tier III multi-factor authentication mandate compliance capability. |
| SASO Pre-Certification Investment | Accelerates market entry timelines for integrated fire-access-surveillance bundles. |
| Edge AI Processor Supply Agreement | Secures on-device inference engine allocation for NEOM unmanned perimeter specifications. |
| Regional Engineering Talent Development | Reduces expatriate labor dependency and compresses project mobilization lead times. |
| Pharmaceutical-Grade Hosting Certification | Unlocks SFDA cold-chain integrity specification revenue in vaccine data storage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary fieldwork engaged data center operators, physical security integrators, NCA certification auditors, and MOHAP facility inspectors across Riyadh, Jeddah, and Dammam corridors. Secondary sources included NCA critical infrastructure guidelines, SASO technical regulations, SFDA pharmaceutical hosting standards, hyperscaler capex disclosures, and import manifest records. Bottom-up project pipeline enumeration triangulated against top-down Vision 2030 giga-project budget allocations.
Data-stream reconciliation across hardware shipment volumes, installation contractor capacity, and facility commissioning timelines informed the analytical framework. Segmentation dimensions modeled encompass security type, deployment model, end user vertical, and technology maturity tier across the projection horizon. CAGRs derived from installer backlog analysis, import growth trajectories, and regulatory compliance deadline clustering. Edge AI processor penetration rates and NCA Tier certification queue lengths served as industry-specific forecast inputs.
The model holds under sustained Vision 2030 capital commitment and stable East Asian component supply; deviation in NCA auditor capacity expansion or biometric sensor export restrictions would shift trajectory. Forecasts embed assumptions regarding regulatory timeline adherence and giga-project construction pacing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Hong Kong Data Center Rack Market