
 Australia Data Center Physical Security Market | 2026-2036
Australia Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Physical Security Market Insights
The Critical Infrastructure Risk Management Program is realigning capital allocation for data center operators across Australia, mandating systematic physical threat assessments and layered perimeter defenses. Honeywell International Inc. leverages its integrated building management portfolio to anchor multi-site security deployments. Schneider Electric competes through energy-efficient security infrastructure that reduces operational overhead. Bosch Sicherheitssysteme GmbH specializes in video analytics and access control systems calibrated for high-availability environments.
Australia Data Center Physical Security encompasses the hardware, software, and procedural safeguards protecting mission-critical computing facilities from unauthorized physical access, environmental threats, and deliberate sabotage, incorporating specifications such as biometric multi-factor authentication, mantrap portals with interlocking doors, and video surveillance systems delivering sub-200-millisecond latency for real-time incident response. Access Control dominates current procurement volumes as operators retrofit legacy credential systems with biometric and mobile-enabled platforms. Surveillance Systems represents the fastest-expanding category, driven by AI-enhanced video analytics demand across hyperscale and colocation facilities. Installation services command premium pricing due to specialized integration requirements for multi-technology environments.
The Australian Signals Directorate's Information Security Manual and state-level building codes enforced by state and territory work health and safety regulators shape product certification pathways and facility design standards. ASIO's security vetting requirements for critical infrastructure personnel create additional compliance layers that filter vendor selection criteria. Stakeholders must weigh the trade-off between proprietary integrated platforms and open-architecture systems that permit component substitution as regulatory specifications evolve.
Market Dynamics
Australia's Critical Infrastructure Risk Management Program is compressing procurement cycles for layered perimeter defenses as operators face mandatory systematic threat assessments. Cloud service providers are accelerating security upgrades across Sydney and Melbourne hyperscale facilities to meet tightened compliance timelines.
Growth Catalysts
- Critical Infrastructure Risk Management Program:Mandated systematic physical threat assessments are pulling forward capital expenditure on biometric multi-factor authentication and mantrap portals across New South Wales and Victoria data center construction sites.
- Hyperscale construction intensity:Colocation and cloud operators are expanding facility footprints in Sydney and Melbourne, concentrating demand for integrated video surveillance with sub-200-millisecond latency specifications.
- AI-enhanced video analytics:Machine learning-enabled threat detection is replacing rule-based monitoring, driving retrofit demand across legacy facilities seeking automated incident response capabilities.
Market Restraints
- Specialized installation labor scarcity:Multi-technology security integration requires certified technicians familiar with interlocking door systems and biometric calibration, creating bottlenecks in Sydney and Melbourne construction schedules.
- Proprietary platform lock-in:Integrated building management systems from dominant vendors create switching costs that limit component substitution as ASIO security vetting requirements evolve.
- Capex intensity of layered defenses:Simultaneous deployment of perimeter barriers, access control, and surveillance infrastructure strains operator balance sheets during concurrent facility expansion cycles.
Strategic Opportunities
- Western Australia and Queensland underpenetration:Data center construction activity outside Sydney-Melbourne corridors remains limited, creating first-mover advantage for security vendors establishing regional service capabilities.
- Mobile-enabled credential convergence:Smartphone-based access control is displacing physical card systems, opening retrofit opportunities across existing colocation facilities seeking reduced credential management overhead.
- Energy-efficient security infrastructure:Schneider Electric's approach to low-power surveillance and access systems aligns with state-level building code pressures for reduced operational carbon intensity.
Industry Challenges
- ASIO security vetting bottlenecks:Personnel clearance requirements for critical infrastructure roles are extending deployment timelines and filtering available vendor field teams.
- Legacy credential system integration:Retrofitting biometric and mobile platforms into existing Wiegand-protocol access networks requires custom middleware development, complicating multi-site standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Physical Security Market |
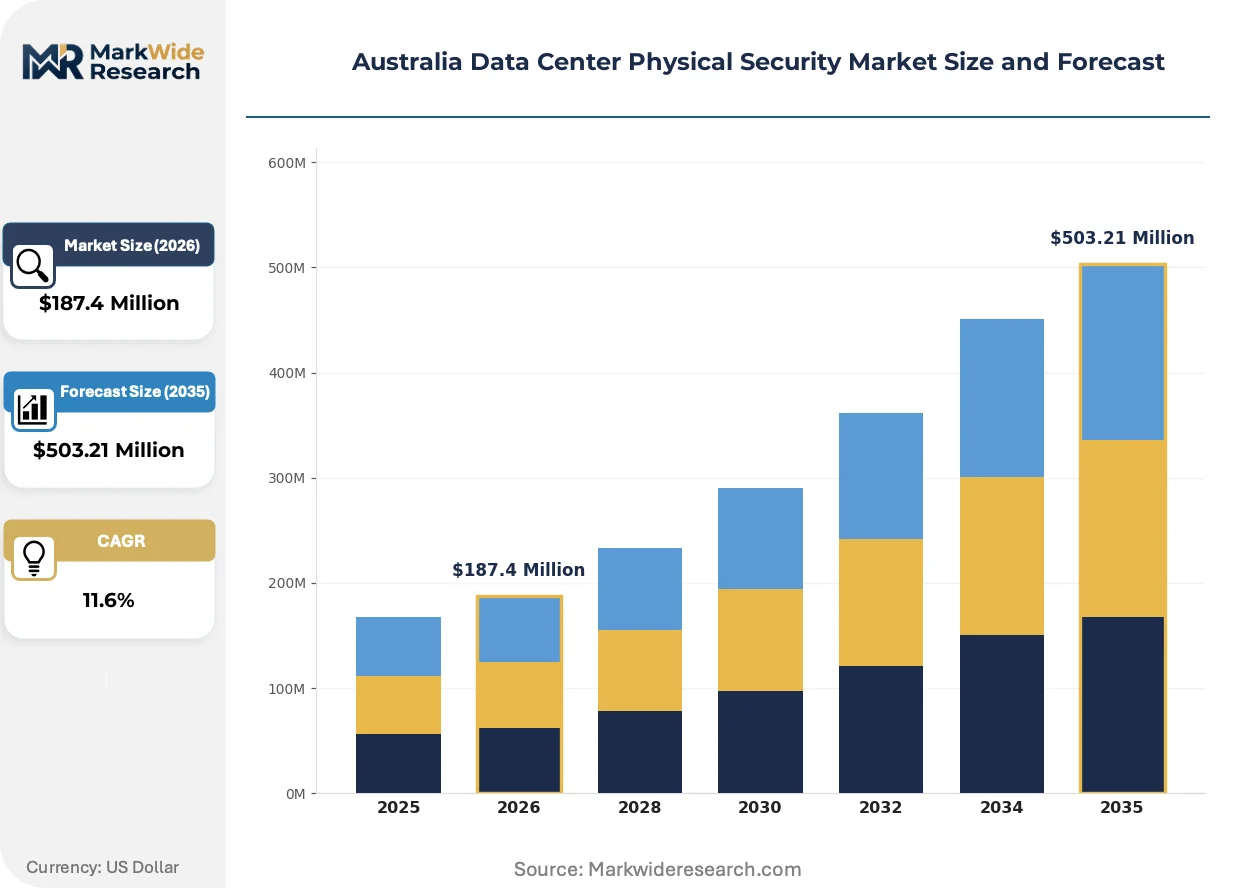
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Surveillance Systems, Fire Detection, Intrusion Detection End User: Telecommunications, Financial Services, Government, Healthcare Service Type: Consulting, Installation, Maintenance, Monitoring Technology: Biometric Systems, IP Cameras, RFID, Barrier Systems |
| Companies Covered | Axis Communications AB, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Johnson Controls, ABB Ltd, Cisco Systems, Genetec Inc., Schneider Electric, Boon Edam Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Physical Security Market Trends and Innovations
Physical security architecture in Australian data centers is converging around real-time threat intelligence and automated response orchestration. Operators are prioritizing systems that reduce human monitoring dependency while satisfying regulatory audit requirements.
Edge-computing video analytics is integrating on-camera processing for immediate threat classification without cloud latency. Hyperscale operators in Sydney are deploying these systems at facility perimeters to enable sub-second gate lockdown protocols. The technology is integrating standalone surveillance into centralized building management platforms, compressing vendor consolidation timelines.
Australia's Critical Infrastructure Risk Management Program is mandating documented resilience testing for physical security systems. Facility operators must demonstrate failover capabilities for access control and surveillance during power or network interruptions. Colocation providers are responding by hardening backup power architectures and diversifying communication pathways for security system telemetry.
Consumption patterns among Australian data center operators are favoring security-as-a-service models over capital purchase. Mid-tier colocation facilities are leasing integrated surveillance and access platforms with bundled maintenance, shifting supplier relationships toward recurring revenue structures. This transition is most visible in Victoria, where operators seek to preserve balance sheet capacity for core infrastructure expansion.
Australia Data Center Physical Security Market Segmentation
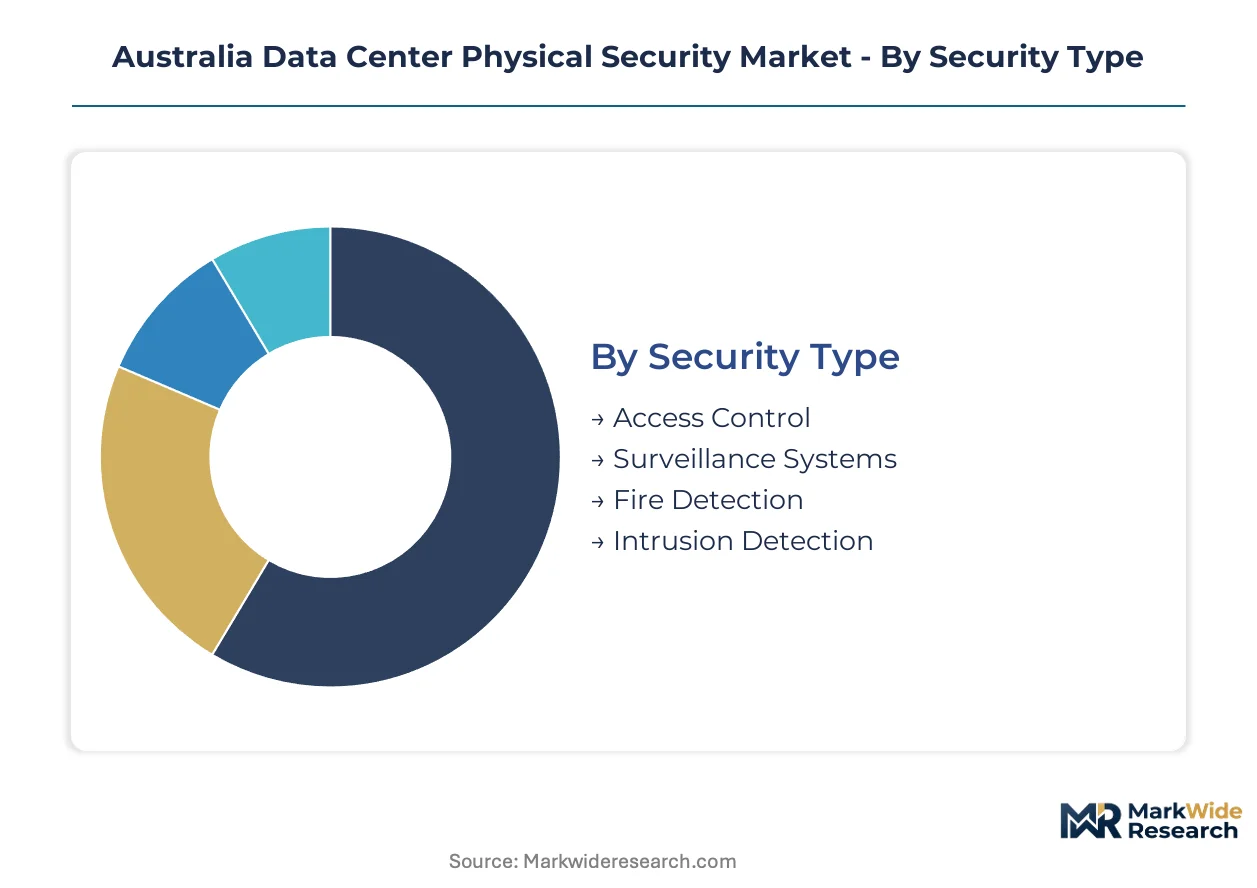
Segmentation in the Australia Data Center Physical Security Market reveals how compliance obligations and facility scale reshape procurement priorities across security technologies and service models. Understanding these divisions exposes where capital concentrates and which vendor capabilities align with operator requirements.
Security Type:
The Critical Infrastructure Risk Management Program imposes distinct certification burdens across security categories, with biometric access systems requiring ASIO-aligned personnel vetting and surveillance platforms demanding Australian Signals Directorate Information Security Manual compliance.
- Access Control:Biometric multi-factor authentication systems with mantrap portal integration dominate procurement volumes across New South Wales and Victoria hyperscale construction. Operators retrofit legacy credential systems to satisfy tightened compliance timelines for systematic threat assessments.
- Surveillance Systems:AI-enhanced video analytics platforms delivering sub-200-millisecond latency specifications are displacing rule-based monitoring across Sydney and Melbourne facilities. Cloud service providers prioritize automated incident response capabilities to reduce human dependency during perimeter breaches.
- Fire Detection:Early warning systems integrated with building management platforms satisfy state-level building codes enforced by work health and safety regulators.
- Intrusion Detection:Perimeter barrier sensors and motion detection arrays protect facility boundaries across colocation sites facing documented resilience testing mandates.
Access Control sits at the top of the volume ranking, with Surveillance Systems climbing the fastest.
End User:
End user segments diverge sharply in procurement scale, with hyperscale cloud operators outspending mid-tier colocation providers by multiples on integrated security architectures.
- Telecommunications:Telco-operated data centers anchor demand for redundant perimeter defenses across Sydney and Melbourne metro areas, driven by carrier-neutral facility expansion and interconnection density requirements.
- Financial Services:Banking and insurance operators prioritize biometric access control with audit-grade logging to satisfy prudential regulator expectations for operational risk management.
- Government:Commonwealth and state agencies mandate ASIO security vetting for all personnel accessing critical infrastructure, filtering vendor selection to cleared integration teams.
- Healthcare:Health sector data centers balance physical security investment against clinical IT budget constraints, favoring leased security-as-a-service models over capital purchase.
Telecommunications commands the largest procurement volumes, while Financial Services expands most quickly as digital banking infrastructure scales.
Service Type:
Service model selection reflects operator capital constraints and internal technical capacity, with bundled offerings gaining traction among facilities prioritizing balance sheet preservation.
- Consulting:Systematic physical threat assessment services align with Critical Infrastructure Risk Management Program mandates, pulling forward demand across New South Wales and Victoria construction pipelines.
- Installation:Multi-technology integration requiring certified technicians familiar with interlocking door systems and biometric calibration commands premium pricing in Sydney and Melbourne.
- Maintenance:Recurring service contracts ensure failover capability demonstration for regulatory audit compliance.
- Monitoring:Security-as-a-service models shift supplier relationships toward recurring revenue structures, particularly visible among Victoria colocation operators.
Installation services generate the highest revenue per engagement, with Monitoring gaining share fastest as consumption patterns favor operational expenditure models.
Technology:
Technology selection increasingly favors platforms that reduce power consumption and enable open-architecture substitution as regulatory specifications evolve.
- Biometric Systems:Fingerprint, iris, and facial recognition platforms calibrated for high-availability environments dominate access control retrofit demand across legacy facilities.
- IP Cameras:Edge-computing video analytics with on-camera processing enable immediate threat classification without cloud latency, compressing vendor consolidation timelines for hyperscale operators.
- RFID:Mobile-enabled credential systems displace physical card infrastructure across existing colocation facilities seeking reduced credential management overhead.
- Barrier Systems:Mantrap portals with interlocking doors and vehicle crash barriers satisfy layered perimeter defense requirements under tightened compliance frameworks.
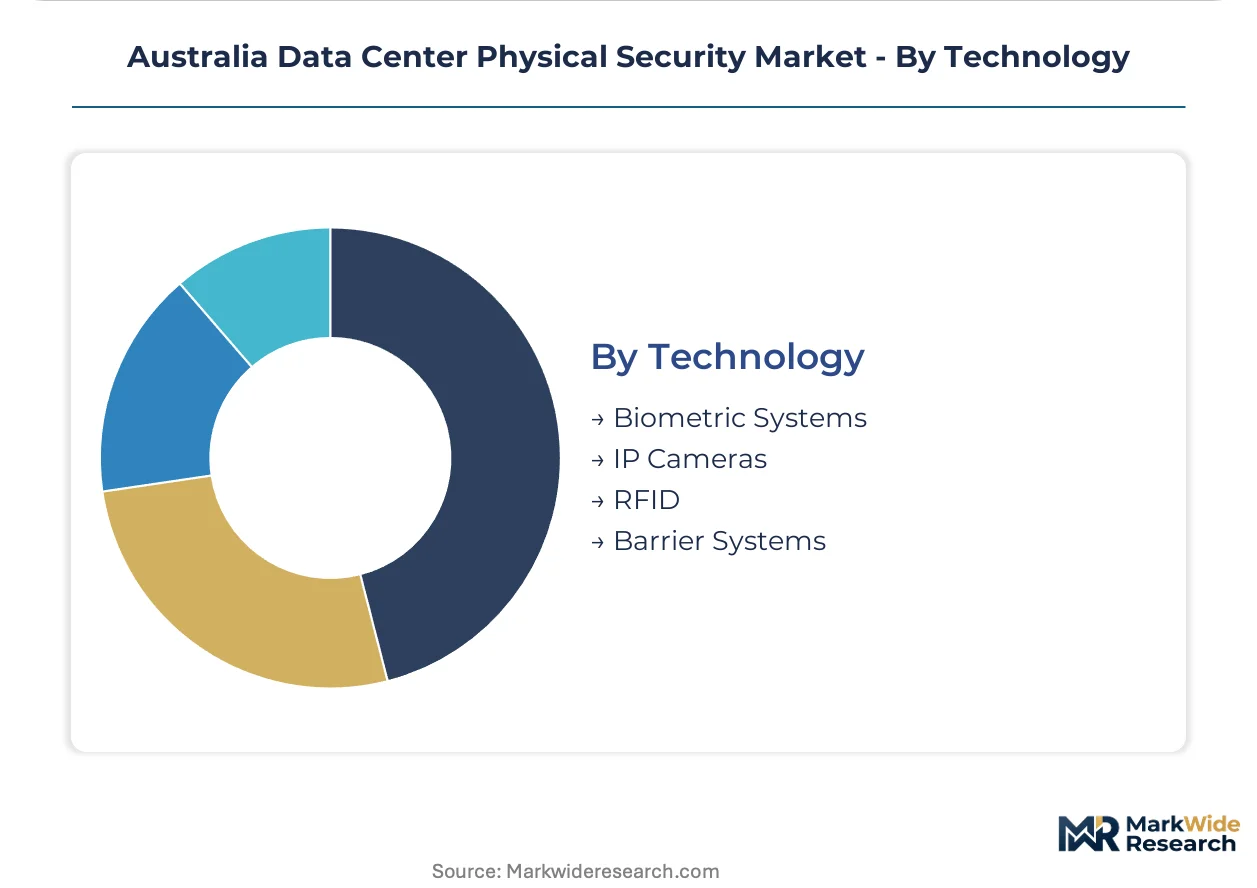
IP Cameras lead technology procurement volumes, with Biometric Systems showing the steepest expansion trajectory as mobile credential convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified security technicians cluster in Sydney and Melbourne, anchoring national deployment capacity for biometric and surveillance integration.
New South Wales
Sydney's hyperscale construction pipeline drives procurement of mantrap portals and sub-200-millisecond latency video systems. The Critical Infrastructure Risk Management Program mandates systematic threat assessments for all new facilities. Western Sydney's emerging data center precincts concentrate demand for layered perimeter defenses among cloud service providers.
Victoria
Melbourne's colocation expansion pulls security-as-a-service adoption to preserve operator balance sheet capacity. State-level building codes enforced by WorkSafe Victoria shape certification pathways for access control hardware. The city's northern technology corridors host intensifying competition among integrated building management vendors.
Queensland
Brisbane's emerging data center activity creates first-mover opportunity for security vendors establishing regional service capabilities. The state's work health and safety regulator enforces facility design standards that align with national critical infrastructure frameworks. Limited local technician pools extend deployment timelines compared to southern markets.
Western Australia
Perth's isolated data center market remains underpenetrated relative to construction activity in eastern states. The state's building commission administers codes that require documented resilience testing for physical security failover systems. Mining sector data infrastructure sustains baseline demand for perimeter barrier systems.
Australia Data Center Physical Security Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with integrated building management portfolios. Consolidation pressure favors vendors offering bundled hardware, software, and maintenance contracts across multi-site deployments. Three archetypes dominate: diversified technology conglomerates, specialized physical security pure-plays, and building automation specialists extending into security verticals. Strategic moves concentrate on geographic service expansion and platform integration partnerships.
Within the diversified technology tier, Honeywell International Inc. and Schneider Electric occupy positions reflecting integrated building management heritage. Bosch Sicherheitssysteme GmbH exemplifies the specialized physical security archetype with European engineering lineage. These three anchors illustrate how vendor selection filters through ASIO security vetting requirements and state-level compliance frameworks.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Johnson Controls |
| ABB Ltd |
| Cisco Systems |
| Genetec Inc. |
| Schneider Electric |
| Boon Edam Australia |
| Others |
Pricing and Supply Chain Analysis
Steel price indices from Australian steel producers cascade through security infrastructure manufacturing, compressing margins on mantrap portals and vehicle crash barriers while elevating tiered pricing across biometric and surveillance system bundles.
Pricing Analysis
Bundled security-as-a-service contracts command premium positioning against unbundled hardware procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by ASIO vetting depth and integration complexity. Price differentiation rests on certification grade for Critical Infrastructure Risk Management Program compliance and geographic delivery cost to Western Australia and Queensland. Pricing pressure stems from specialized installation labor scarcity in Sydney and Melbourne, forcing margin compression on fixed-bid projects. Mid-tier colocation operators exhibit highest price sensitivity, while hyperscale cloud providers prioritize performance specifications over unit cost.
Supply Chain Analysis
Reverse-logistics flows for surveillance camera refurbishment and biometric sensor recalibration create secondary supply channels that extend equipment lifecycles and dampen replacement demand. Component manufacturing concentrates in China, South Korea, and Taiwan for IP camera sensors and edge-computing processors. Raw material dependencies span rare earth elements for magnetics in access control locks, copper for cabling infrastructure, and semiconductor wafers for video analytics chipsets. Single-source vulnerability in ASIO-cleared technician pools creates deployment bottlenecks. Distribution runs through certified systems integrators with national security clearance rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's data center physical security market functions as a geographic-arbitrage play where Perth and Brisbane construction timelines extend 40-60 percent longer than Sydney-Melbourne corridors due to technician scarcity, rewarding early regional service investments.
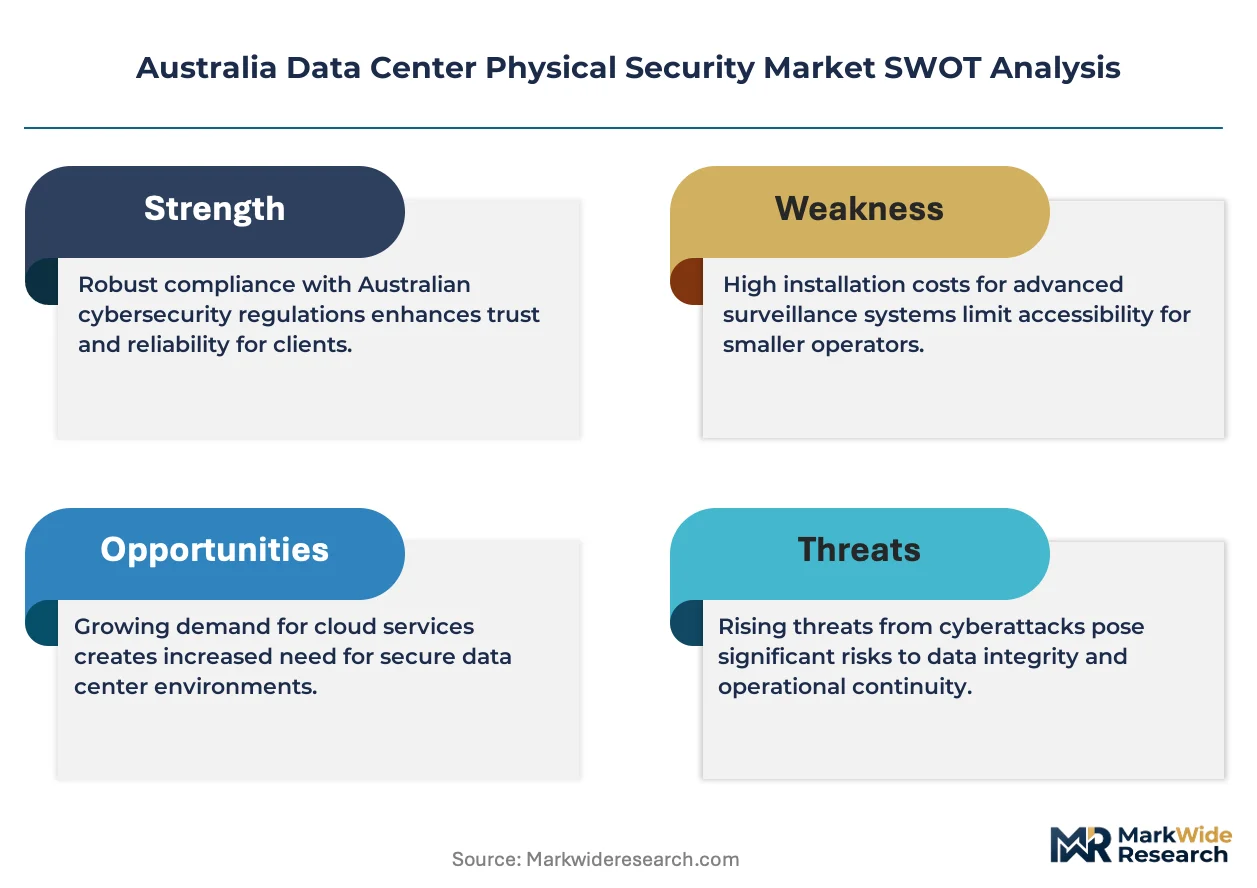
For Market Incumbents: To counter proprietary platform lock-in threats from integrated building management vendors, Honeywell and Schneider Electric should deepen backward integration into biometric calibration services and expand cleared technician certification programs in Western Australia. Channel control through exclusive ASIO-vetted installation partnerships represents the critical defensive lever. For New Entrants and Emerging Players: Regional construction contractors in Queensland and Western Australia offer the most penetrable partnership channel for security vendors lacking eastern seaboard presence. White-space targets include mobile-enabled credential retrofit for legacy Wiegand-protocol facilities and energy-efficient surveillance for state-level building code compliance. A security-as-a-service go-to-market angle bypasses capital-constrained mid-tier colocation procurement barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized physical security pure-plays possessing ASIO-cleared field teams and open-architecture software platforms. Long-term viability across the analysis window favors vendors capable of component substitution as Australian Signals Directorate specifications evolve. Monitor Critical Infrastructure Risk Management Program audit failure rates as an inflection indicator for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ASIO-Cleared Technician Certification Expansion | Addresses installation labor scarcity compressing deployment timelines in Perth and Brisbane markets. |
| Security-as-a-Service Platform Launch | Aligns with Victoria colocation operator preference for operational expenditure models over capital purchase. |
| Edge-Computing Video Analytics Integration | Enables sub-200-millisecond latency specifications demanded by Sydney hyperscale cloud providers. |
| Mobile-Enabled Credential Convergence | Displaces legacy card systems across existing facilities seeking reduced credential management overhead. |
| Western Australia Regional Service Hub Establishment | Captures first-mover advantage in underpenetrated market with documented resilience testing mandates. |
Research Methodology
Bottom-up data center operator modeling reconciled against top-down security vendor shipment tracking forms the analytical core of this study. Primary interviews with facility security directors, ASIO-cleared systems integrators, colocation procurement managers, and critical infrastructure compliance officers combined with secondary validation against Australian Signals Directorate Information Security Manual updates, state-level work health and safety regulator enforcement patterns, and hyperscaler capex disclosure filings. Triangulation across these sources ensures segmentation accuracy for access control, surveillance, and service type categories.
Input-output matrix framing connects security technology procurement volumes to construction pipeline data across New South Wales, Victoria, Queensland, and Western Australia. Segmentation dimensions modeled include security type, end-user industry, service model, and technology platform across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against compliance mandate implementation timelines, with AI-enhanced video analytics adoption curves and mobile credential displacement rates as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Critical Infrastructure Risk Management Program enforcement intensity and ASIO security vetting processing capacity. Practitioners should monitor state-level building code amendment cycles and hyperscale facility announcement pipelines for early signals of procurement inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
South Africa Data Center Market