
 Austria Data Center Power Market | 2026-2036
Austria Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Data Center Power Market Insights
Central European data center corridor expansion is fragmenting traditional supply relationships across Austria's alpine-adjacent markets. Schneider Electric SE leverages its integrated energy management portfolio to anchor large-scale deployments near Vienna. Siemens AG competes through localized manufacturing scale and channel control across German-speaking utilities. Eaton Corporation differentiates via power distribution specialization for enterprise colocation sites.
Austria data center power encompasses electrical infrastructure engineered to deliver uninterruptible power with 99.999% uptime reliability to server halls, incorporating redundant UPS systems, diesel or gas generators, and precision cooling circuits operating within 1-2 degree tolerance bands. Its primary purpose is eliminating downtime cost exposure for financial services, healthcare records, and cloud workloads. UPS systems and cooling technologies capture the dominant margin pools as operators face thermal density thresholds from AI training clusters. Generators and power distribution units serve mature replacement cycles rather than greenfield expansion. Hybrid power architectures spanning AC and DC feeds are gaining traction among hyperscale operators seeking efficiency gains.
Austria's national implementation of EU Green Deal efficiency standards and F-Gas Regulation phase-down timelines shapes equipment procurement through mandatory carbon disclosure and refrigerant constraints. BIS-aligned product safety certifications and CE marking requirements govern market access for imported electrical components. Stakeholders must monitor how Vienna's municipal heat reuse mandates and grid interconnection queue delays reshape site selection economics before committing capital to new builds.
Market Dynamics
AI training clusters are forcing thermal density thresholds that exhaust legacy cooling capacity across Vienna-area facilities. Operators must re-engineer power architectures while navigating Austria's EU Green Deal efficiency mandates and F-Gas refrigerant phase-down timelines.
Growth Catalysts
- EU Green Deal efficiency mandates:Austria's national implementation of stricter energy disclosure requirements accelerates equipment refresh cycles. Colocation operators near Linz upgrade UPS systems to meet carbon reporting thresholds.
- Cloud computing expansion:Hyperscale providers are scaling Vienna-area footprints. Demand concentrates for redundant power distribution serving financial services and healthcare workloads.
- Thermal density thresholds:AI training clusters exceed legacy cooling tolerance bands. Precision cooling technologies capture dominant margin pools as operators retrofit server halls.
Market Restraints
- Grid interconnection queue delays:Vienna's municipal permitting processes extend site energization timelines. New builds face 18-24 month waits for utility connection approvals.
- F-Gas Regulation phase-down:Refrigerant constraints limit cooling equipment options. Operators must source alternative chemistries or absorb premium pricing for compliant systems.
- Alpine topography constraints:Seismic and flood risk zones near Graz restrict site selection. Underground construction costs escalate in karst geology regions.
Strategic Opportunities
- Municipal heat reuse mandates:Vienna requires waste heat recovery from data centers above 500kW capacity. District heating integration creates new revenue streams for operators.
- Hybrid AC-DC architectures:Hyperscale facilities are piloting direct current feeds to server racks. Efficiency gains from eliminating conversion losses reshape power distribution specifications.
- Enterprise colocation underpenetration:Mid-market manufacturers in Upper Austria lack redundant infrastructure. Localized edge deployments serve latency-sensitive industrial automation.
Industry Challenges
- Electrical engineering talent scarcity:Specialized skills for 99.999% uptime system design concentrate in Vienna and Linz. Rural facility staffing requires premium compensation or remote monitoring architectures.
- Legacy diesel generator integration:Existing backup power assets must interface with battery energy storage additions. Control system harmonization extends commissioning timelines.
- BIS-aligned certification timelines:Product safety approvals for imported electrical components face 4-6 month validation cycles. Procurement planning must accommodate CE marking documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Data Center Power Market |
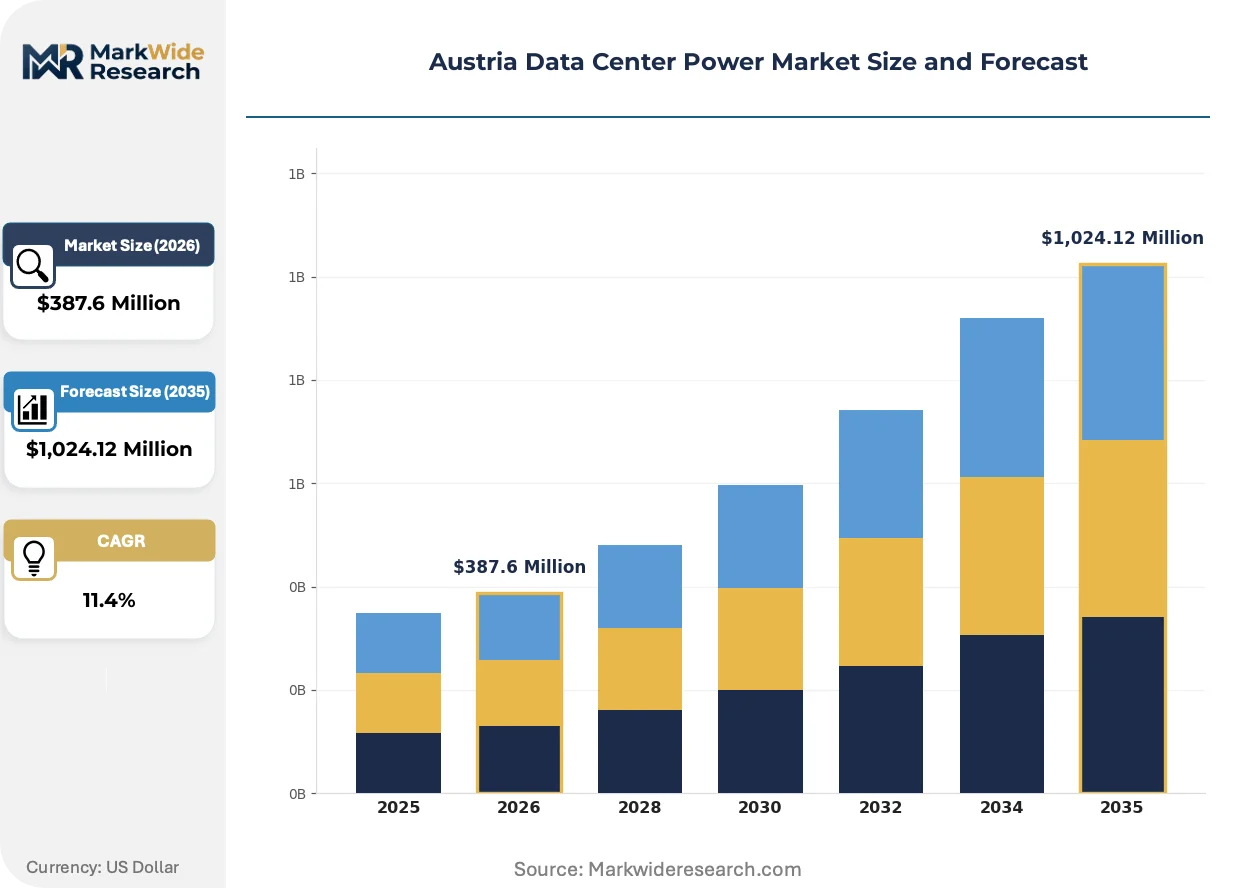
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: AC Power, DC Power, Hybrid Systems, Renewable Sources End User: Colocation Providers, Enterprises, Government, Hyper-scale Operators Application: Cloud Computing, Disaster Recovery, Big Data Processing, Storage Solutions Technology: UPS Systems, Generators, Cooling Systems, Power Distribution Units |
| Companies Covered | Schneider Electric SE, ABB Ltd, Eaton Corporation, Vertiv Group Corp, Legrand Group, Siemens AG, Rittal GmbH & Co. KG, Cummins Inc., Delta Electronics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Data Center Power Market Trends and Innovations
Liquid cooling technologies are compressing the gap between thermal design power and air-cooling limits. Regulatory pressure on refrigerants and carbon disclosure is accelerating equipment architecture decisions across Austrian facilities.
Immersion cooling systems using dielectric fluids are collapsing the physical footprint required for high-density GPU clusters. Hyperscale operators in Vienna are piloting single-phase and two-phase designs for AI training workloads. This technology is collapsing the traditional 1-2 degree tolerance bands that constrained rack densities, enabling 50-100kW per rack configurations that exhaust conventional precision air handlers.
Austria's implementation of EU Green Deal efficiency standards mandates granular carbon disclosure for facilities above defined capacity thresholds. The F-Gas Regulation phase-down timeline restricts refrigerant options for new cooling equipment. Colocation providers near Graz are responding by accelerating heat pump and liquid cooling deployments ahead of 2030 compliance deadlines.
Power purchase agreements with renewable generators are displacing traditional utility tariff structures for large-load facilities. Enterprise buyers in financial services and healthcare verticals now require contractual carbon intensity guarantees. This procurement evolution is most visible in Vienna, where municipal heat reuse mandates intersect with corporate sustainability commitments to reshape supplier qualification criteria.
Austria Data Center Power Market Segmentation
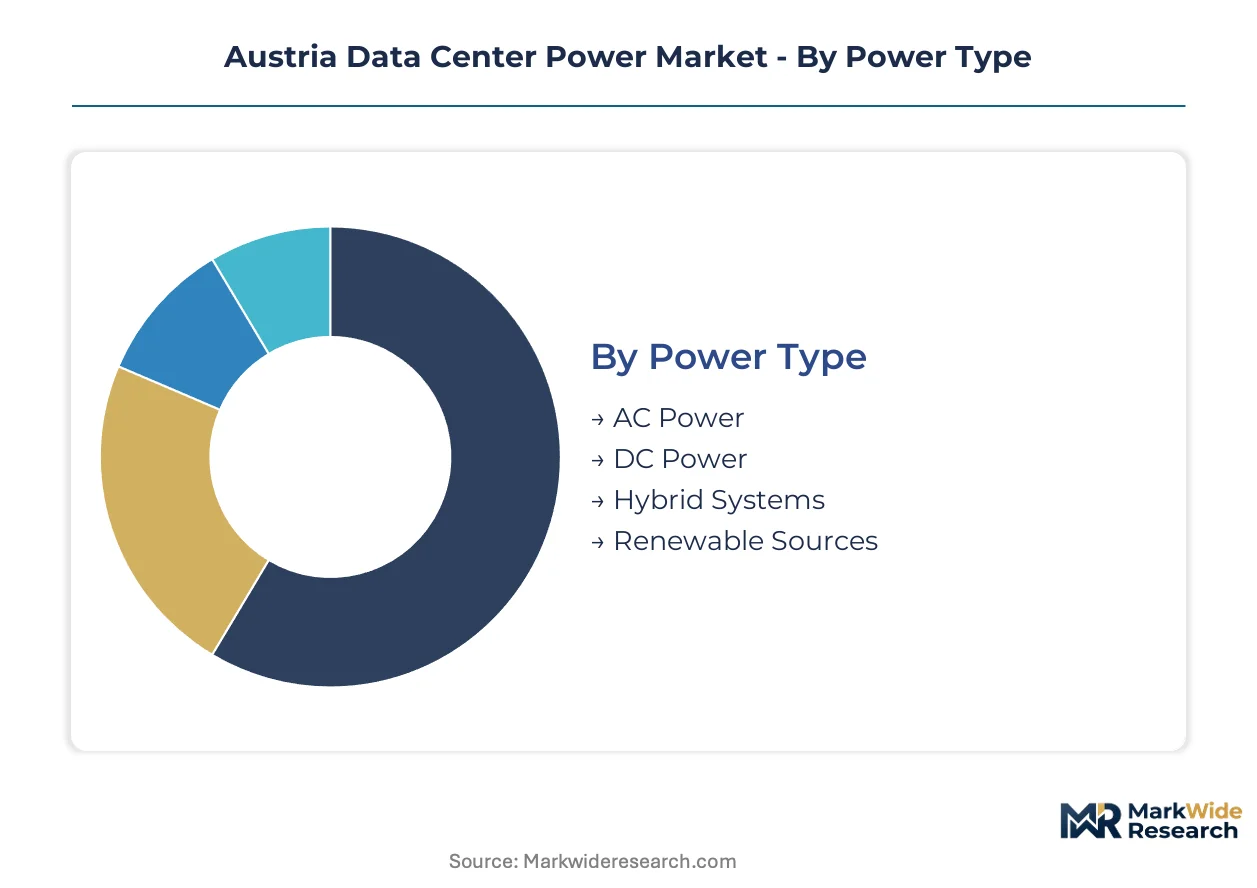
Equipment procurement cycles in Austria's data center power market diverge sharply between mature replacement markets and emerging technology categories. Understanding these turnover velocities helps vendors align inventory planning with Vienna-area hyperscale expansion timelines.
Power Type:
AC Power cycles through 10-15 year replacement windows while DC architectures and renewable integration move on 3-5 year refresh timelines driven by efficiency mandates.
- AC Power:Traditional alternating current feeds remain the backbone of legacy facilities across Linz and Graz. Three-phase 400V distribution dominates established colocation sites where operators prioritize compatibility over conversion efficiency.
- Hybrid Systems:Architectures blending AC and DC feeds are capturing expansion budgets as hyperscale operators pilot direct current server rack connections. Vienna municipal heat reuse mandates accelerate these deployments where waste heat recovery justifies higher capital outlays.
- DC Power:Pure direct current infrastructure serves specialized high-performance computing clusters. Limited penetration reflects skill scarcity in 380V DC system design across Austrian electrical engineering labor pools.
- Renewable Sources:On-site solar and battery storage integration responds to EU Green Deal carbon disclosure requirements. Power purchase agreements with Austrian wind and hydro generators reshape procurement for facilities above 500kW capacity thresholds.
AC Power dominates installed base. Hybrid Systems is where expansion concentrates.
End User:
Procurement authority concentrates differently across customer types, with hyperscale operators driving standardization while enterprises prioritize customization.
- Hyper-scale Operators:Cloud computing providers standardize power specifications across Vienna-area campuses. Their volume purchasing extracts preferential pricing for redundant UPS configurations serving financial services workloads.
- Colocation Providers:Multi-tenant facilities near Linz upgrade cooling and power distribution to meet EU Green Deal efficiency thresholds. Their equipment refresh cycles accelerate as tenant contracts increasingly mandate carbon intensity disclosures.
- Enterprises:Manufacturing and healthcare verticals in Upper Austria deploy edge infrastructure for latency-sensitive automation. Capital constraints limit these buyers to modular UPS systems rather than integrated campus architectures.
- Government:Federal and municipal data centers face BIS-aligned certification requirements for imported electrical components. Procurement timelines extend 4-6 months for CE marking documentation.
Colocation Providers dominate installed base. Hyper-scale Operators is where expansion concentrates.
Application:
Workload characteristics dictate power architecture choices, with AI training clusters forcing thermal density thresholds that exhaust conventional cooling.
- Cloud Computing:Hyperscale virtualization platforms require N+1 redundant power distribution across Vienna-area facilities. Demand concentrates for precision cooling systems operating within 1-2 degree tolerance bands.
- Big Data Processing:GPU-intensive analytics workloads exceed 50kW per rack densities. Liquid cooling deployments are climbing the fastest as operators retrofit server halls for AI training clusters.
- Disaster Recovery:Secondary site requirements prioritize rapid generator startup and UPS bridging time. Graz-area facilities face alpine topography constraints that extend underground construction timelines.
- Storage Solutions:Archive and backup workloads tolerate higher temperature variance. These applications absorb legacy air-cooled infrastructure displaced by denser compute deployments.
Cloud Computing dominates installed base. Big Data Processing is where expansion concentrates.
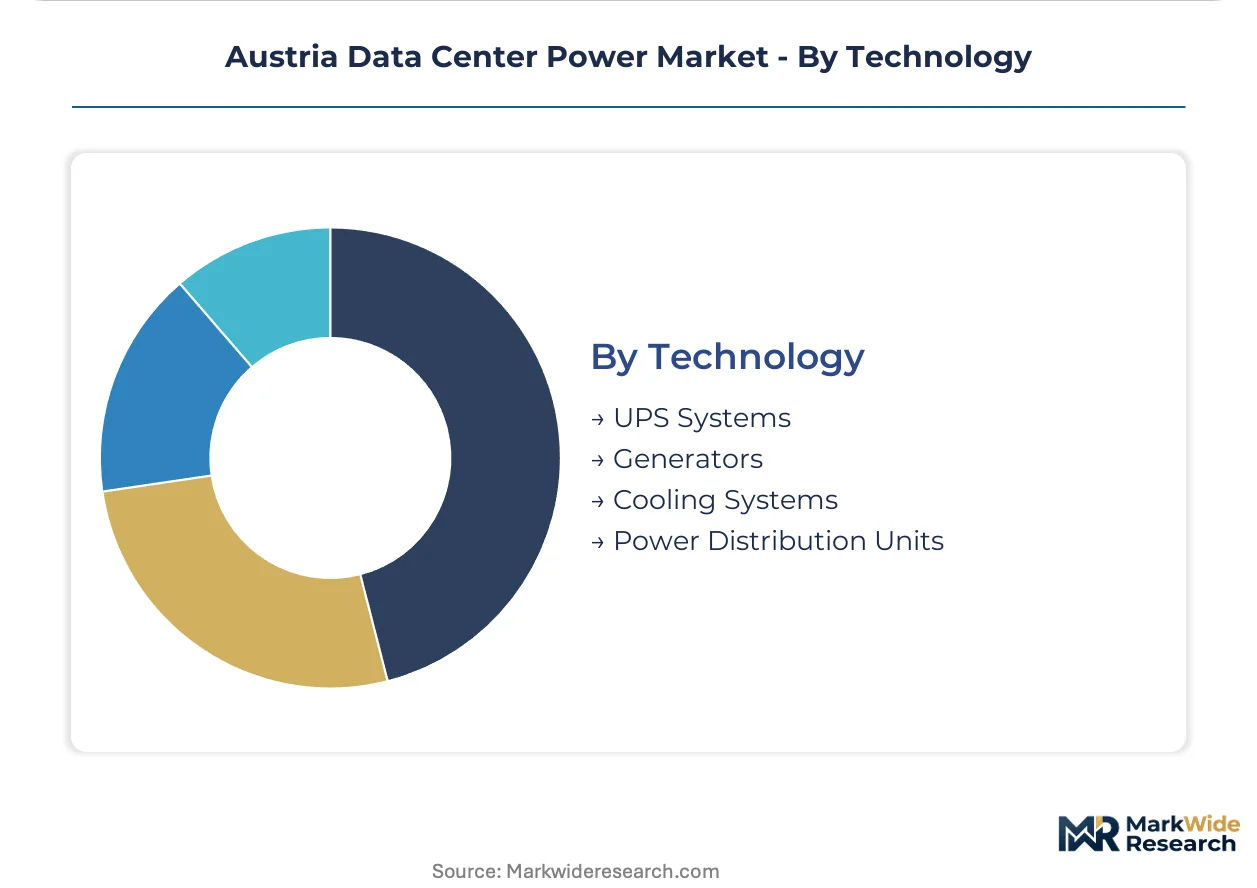
Technology:
Component replacement velocities range from 5-year cooling system refreshes to 15-year generator asset lives, creating asynchronous procurement patterns.
- Cooling Systems:Precision air handlers and emerging liquid cooling technologies capture dominant margin pools. F-Gas Regulation phase-down timelines restrict refrigerant options and accelerate heat pump deployments near Graz.
- UPS Systems:Uninterruptible power supplies face mandatory refresh cycles under stricter energy efficiency mandates. Colocation operators near Linz upgrade systems to meet carbon reporting thresholds.
- Power Distribution Units:Rack-level and floor-mounted PDUs serve mature replacement demand. Standardization limits differentiation except in hyperscale custom specifications.
- Generators:Diesel and gas backup assets interface with battery energy storage additions. Control system harmonization extends commissioning timelines for hybrid backup architectures.
Generators dominate installed base. Cooling Systems is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal efficiency mandates and F-Gas Regulation phase-down timelines reshape procurement patterns across Central European data center corridors. Austria's national implementation of these directives accelerates equipment refresh cycles while grid interconnection queues extend site development timelines.
Vienna Metropolitan Area
Hyperscale cloud providers are expanding redundant power distribution footprints across Vienna's municipal zone. The city's waste heat recovery mandates for facilities above 500kW capacity intersect with corporate sustainability commitments to reshape supplier qualification criteria. District heating integration creates new revenue streams for colocation operators near the Danube corridor.
Upper Austria
Mid-market manufacturers in Linz deploy edge infrastructure for latency-sensitive industrial automation workloads. The region's steel and chemical processing heritage concentrates electrical engineering talent for 99.999% uptime system design. Localized UPS upgrades respond to EU Green Deal carbon disclosure thresholds for tenant contracts.
Styria
Graz-area facilities face alpine topography constraints including seismic risk zones and karst geology that escalate underground construction costs. Heat pump and liquid cooling deployments accelerate ahead of 2030 F-Gas compliance deadlines. Precision cooling retrofits serve GPU-intensive analytics workloads exceeding legacy air-handler tolerance bands.
Lower Austria
Suburban Vienna expansion corridors absorb overflow demand from municipal permitting bottlenecks. Battery energy storage additions interface with existing diesel generator assets across hybrid backup architectures. Control system harmonization extends commissioning timelines for facilities seeking rapid generator startup capabilities.
Austria Data Center Power Market Competitive Landscape
Capability concentration sits with integrated energy management specialists; scale advantage sits with diversified electrical equipment conglomerates. The vendor base spans three functional tiers: full-stack infrastructure providers, component specialists in power distribution or thermal management, and regional systems integrators. Competitive moves center on strategic partnerships for district heating integration and portfolio diversification into battery energy storage systems.
Within the integrated infrastructure tier, Schneider Electric SE and Siemens AG exemplify contrasting approaches to the Vienna-area expansion wave. Schneider Electric SE occupies a position anchored in energy management software and hardware convergence. Siemens AG represents localized manufacturing scale and channel control across German-speaking utility markets. Eaton Corporation sits within the power distribution specialization archetype, serving enterprise colocation sites with modular architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Eaton Corporation |
| Vertiv Group Corp |
| Legrand Group |
| Siemens AG |
| Rittal GmbH & Co. KG |
| Cummins Inc. |
| Delta Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
German and Swiss electrical component manufacturing concentration anchors margin capture downstream at Vienna-area hyperscale campuses and Linz colocation facilities. Procurement officers face asymmetric pricing power where UPS system and precision cooling vendors extract premiums through limited qualified supplier pools under EU Green Deal certification timelines.
Pricing Analysis
Vienna metropolitan pricing runs 15-25% above Graz and Linz for equivalent UPS configurations, reflecting municipal permitting bottlenecks and district heating integration mandates. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked integrated systems from modular alternatives and refurbished legacy units. Cost compression in standard-tier power distribution units is intensifying because Chinese manufacturers are penetrating Austrian distribution channels. Enterprise colocation operators in Upper Austria exhibit highest price sensitivity; hyperscale cloud providers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships with German switchgear suppliers and Swiss precision cooling specialists. Manufacturing concentration in Germany, Switzerland, and the Netherlands feeds Austrian demand for redundant UPS architectures and liquid cooling manifolds. Semiconductor content in power conversion modules creates single-source vulnerability through Taiwanese foundry dependence. Distribution runs through Vienna-based systems integrators serving Upper Austria and Styria with localized commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's data center power market functions as a defensive-moat arena where regulatory entrenchment—EU Green Deal mandates, F-Gas phase-down timelines, and BIS-aligned certification requirements—erects barriers that protect incumbent positions from rapid disruption.
For Market Incumbents: Insulate installed base relationships by embedding battery energy storage retrofits into existing diesel generator contracts before emerging European competitors establish footholds. Deepen channel control through exclusive distribution agreements with Linz and Graz electrical engineering firms facing talent scarcity. Prioritize certification investment in liquid cooling technologies ahead of 2030 F-Gas compliance deadlines to lock out modular challengers.
For New Entrants and Emerging Players: Styria's Graz-area market presents underpenetration in precision cooling retrofits for GPU-intensive analytics workloads exceeding legacy air-handler tolerance bands. Target mid-market manufacturers in Upper Austria with modular edge infrastructure solutions bypassing Vienna's municipal permitting bottlenecks. Pursue partnership-based go-to-market positioning with Austrian steel and chemical sector engineering departments possessing 99.999% uptime design expertise.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European electrical infrastructure platforms seeking geographic expansion into German-speaking utility markets. Five-to-ten year viability hinges on heat reuse mandate compliance and hybrid AC-DC architecture transition velocity. Watch Vienna municipal heat network interconnection queue clearance rates as the inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| District Heating Integration Partnership | Vienna municipal mandates above 500kW capacity create recurring revenue streams for compliant operators. |
| Liquid Cooling Technology Licensing | F-Gas Regulation phase-down accelerates heat pump and dielectric fluid deployment ahead of deadlines. |
| Battery Energy Storage Retrofit Program | Legacy diesel generator assets require control system harmonization extending commissioning timelines. |
| CE Marking Fast-Track Certification | BIS-aligned validation cycles compress 4-6 month procurement windows for imported electrical components. |
| Upper Austria Edge Infrastructure Deployment | Mid-market manufacturing automation demand absorbs modular UPS systems bypassing Vienna permitting delays. |
Research Methodology
Initial hypotheses were tested against primary input from data center facility managers, electrical engineering contractors, colocation procurement leads, and municipal utility planning officers and refined through secondary validation against EU Green Deal implementation documents, F-Gas Regulation compliance filings, Austrian grid operator interconnection queue data, and CE marking certification databases. Bottom-up equipment procurement modeling triangulated against top-down capacity expansion announcements across Vienna, Linz, and Graz metropolitan zones.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning power type, end user category, application workload, and technology component replacement velocity. CAGRs were derived from equipment refresh cycle analysis and hyperscale capex disclosure patterns, incorporating thermal density thresholds from AI training cluster deployments and EU efficiency mandate compliance timelines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, construction cost inflation, or renewable energy certificate pricing would shift the trajectory. Forecasts reflect documented assumptions regarding grid interconnection approval timelines and refrigerant technology substitution curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Datacenter Infrastructure Services Market